
 Assortment and Space Optimization (ASO) Market | 2026-2036
Assortment and Space Optimization (ASO) Market Size, Share, and Industry Trends Forecast 2026-2036
Assortment and Space Optimization (ASO) Market Intelligence
The ASO software tier is restructuring around a sharp split between premium AI-native platforms and commodity planogram tools. RELEX Solutions leverages machine learning-driven demand forecasting to anchor its position in high-complexity grocery environments. Oracle Corporation competes through deep vertical integration with enterprise ERP stacks. Nielsen Consumer LLC differentiates via proprietary shopper panel data that feeds assortment models.
Assortment and Space Optimization encompasses algorithmic systems that allocate finite retail shelf space to product SKUs using demand elasticity curves, planogram constraints, and margin-per-square-foot targets. These platforms integrate spatial mapping engines with inventory turnover algorithms to maximize revenue density across physical and digital storefronts. Cloud-Based deployment now leads adoption curves as retailers seek elastic compute for seasonal assortment shifts. Planogram Software retains mature market share but faces margin compression from open-source alternatives. Demand Forecasting Systems represent the fastest-growing segment as probabilistic models ingest weather, event, and social signals.
Retailers navigating FDA food-labeling rules and EPA packaging waste directives must embed compliance data into ASO rule engines to avoid shelf-level violations. The EU Green Deal and REACH chemical disclosure standards are extending traceability requirements upstream into assortment decisions. Stakeholders should monitor how carbon-accounting mandates reshape space allocation algorithms before regulatory deadlines harden.
Market Dynamics
Cloud migration is consolidating ASO deployment architectures as grocery retailers abandon on-premise infrastructure for elastic compute capacity during seasonal assortment shifts.
Growth Catalysts
- Omnichannel Complexity:United States grocers are deploying ASO platforms to synchronize shelf allocation with digital fulfillment nodes, compressing inventory holding costs across hybrid storefronts.
- EU Green Deal Packaging Mandates:REACH chemical disclosure standards are forcing assortment rule engines to embed carbon-accounting data upstream into space allocation algorithms.
- Machine Learning Demand Sensing:Probabilistic models ingesting weather, event, and social signals are displacing static planogram tools in high-velocity perishable categories.
Market Restraints
- Data Fragmentation:ERP silos across legacy retail stacks obstruct real-time inventory synchronization, delaying ASO rule engine deployment by 8-14 months in typical grocery implementations.
- Specialized Talent Scarcity:Retailers face acute shortages of data scientists capable of calibrating demand elasticity curves against spatial constraints, inflating implementation costs.
- Open-Source Planogram Compression:Commodity visualization tools are eroding pricing power in the planogram software tier, squeezing margin pools for proprietary vendors.
Strategic Opportunities
- Japan Convenience Retail:Dense urban store networks and extreme SKU proliferation create fertile ground for AI-native ASO platforms optimizing micro-assortments at the store-cluster level.
- Pharmacy Shelf Integration:FDA unit-dose tracking requirements are opening adjacent demand for ASO systems that marry drug inventory to retail space planning.
- Digital Twin Convergence:Spatial mapping engines fused with real-time IoT shelf sensors enable dynamic planogram adjustment, creating subscription revenue models beyond perpetual licenses.
Industry Challenges
- Legacy System Entanglement:Mainframe-based inventory systems at established grocers resist API integration, forcing costly middleware layers that degrade ASO algorithm performance.
- Cross-Functional Alignment:Merchandising, operations, and finance teams maintain conflicting KPIs for space productivity, complicating rule-engine configuration and adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Assortment and Space Optimization (ASO) Market |
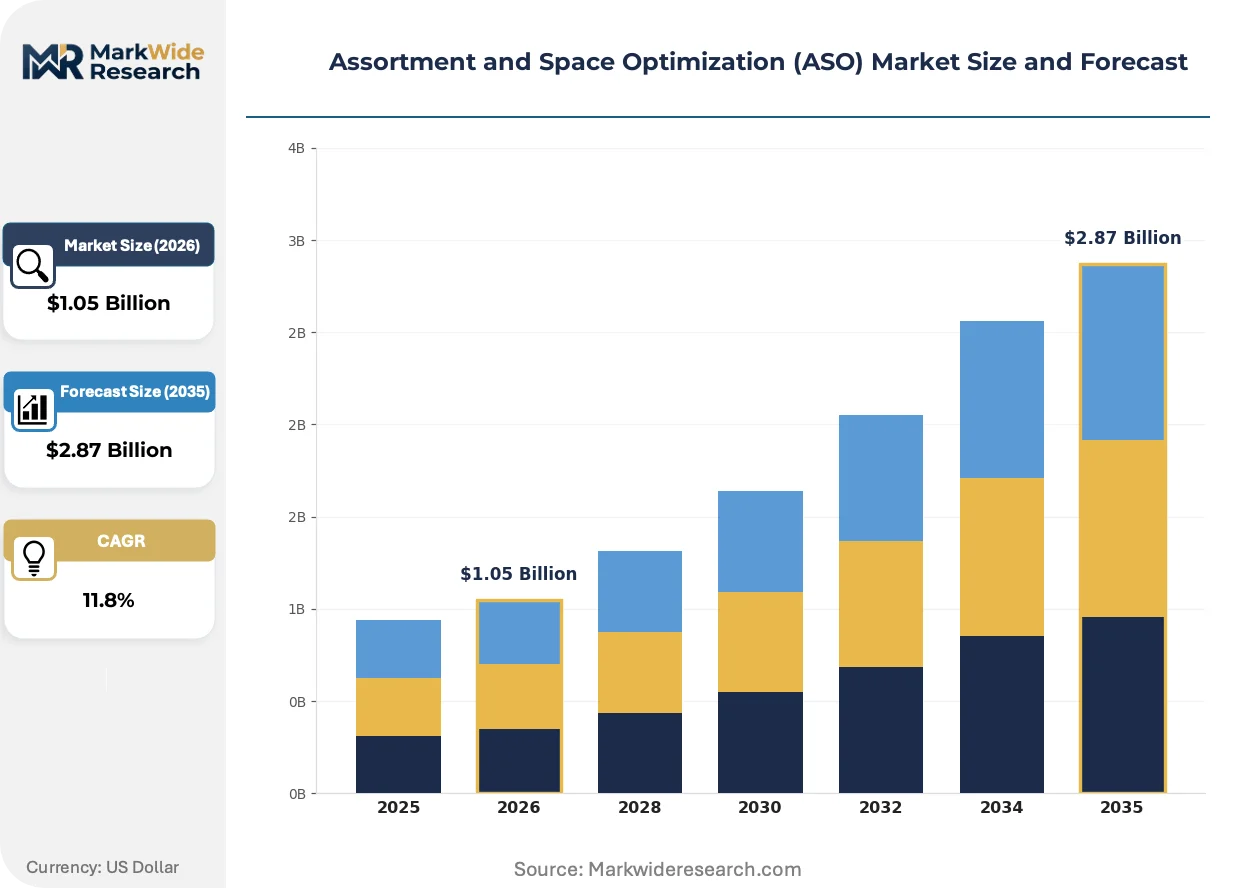
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.87 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Planogram Software, Space Planning Tools, Assortment Optimization Platforms, Performance Analytics Solutions, Demand Forecasting Systems Deployment Mode: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services Application: Category Management, Sales Optimization, Inventory Turnover Improvement, Shelf Space Allocation, Customer Experience Enhancement End User Industry: Supermarkets, Specialty Retailers, Wholesale Distributors, Convenience Stores, E-Commerce Platforms |
| Companies Covered | RELEX Solutions, Kantar Group Limited, Oracle Corporation, JDA Software, Solteq, SymphonyAI, Nielsen Consumer LLC, Infor, Blue Yonder Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Assortment and Space Optimization (ASO) Market Strategic Shifts & Innovations
Algorithmic retailing is compressing decision cycles from quarterly to weekly as probabilistic models displace merchant intuition in shelf allocation workflows.
Generative AI is consolidating planogram design workflows by automating spatial layout generation from demand elasticity inputs. Mass-market grocers in Germany and Japan are piloting these tools to reduce planogram revision cycles from weeks to days. The technology is compressing headcount in retail space planning departments while elevating strategic merchandising roles.
EPA packaging waste directives are forcing ASO vendors to embed lifecycle assessment data into rule engines. Retailers must now model carbon intensity per SKU alongside margin-per-square-foot targets. Fresh produce and private-label categories face the steepest compliance curve as biodegradable packaging alternatives reshape physical shelf requirements.
Buyer concentration among top-10 grocery chains is compressing vendor pricing power and elongating sales cycles. Procurement teams now demand outcome-based contracts tying ASO fees to measurable inventory turnover improvement. This shift is most visible in United States and German markets where retailer consolidation has advanced furthest, squeezing mid-tier software vendors toward specialized vertical positioning.
Assortment and Space Optimization (ASO) Market Segmentation
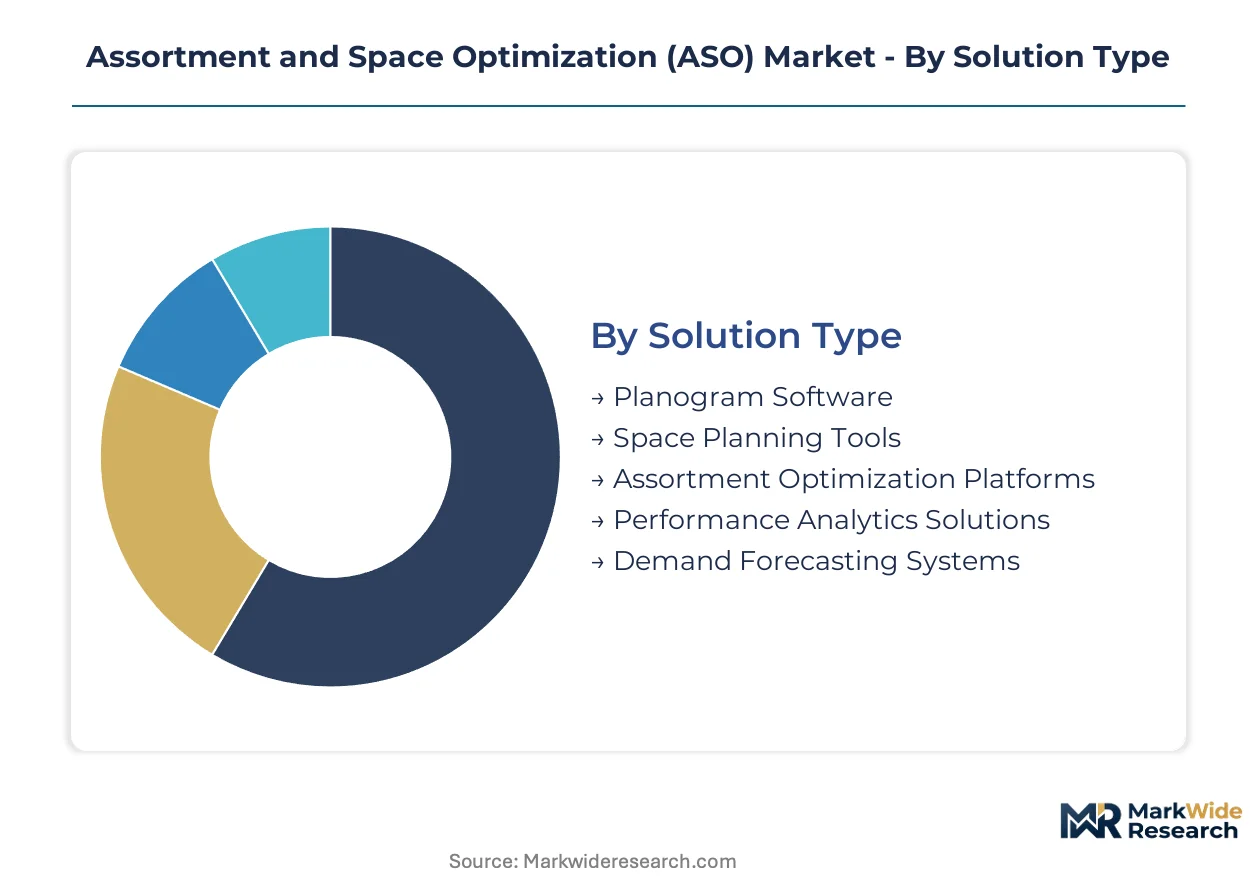
ASO procurement patterns diverge sharply by deployment architecture and buyer sophistication. Capital allocation priorities separate enterprise grocery chains from mid-market specialty retailers, creating tiered vendor opportunity structures across solution categories.
Solution Type:
Capital intensity escalates with algorithmic sophistication, separating visualization tools from predictive platforms requiring dedicated data infrastructure.
- Planogram Software:Visualization engines render shelf layouts using spatial constraints and product dimensions. United States supermarkets deploy these tools for seasonal reset workflows, though margin compression from open-source alternatives limits pricing power.
- Demand Forecasting Systems:Probabilistic models ingest weather patterns, local events, and social sentiment signals to project SKU-level demand. German grocery chains prioritize these platforms for perishable categories where spoilage costs dominate margin calculations.
- Space Planning Tools:Floor-plan optimization modules allocate square footage across departments using traffic flow analytics.
- Assortment Optimization Platforms:Algorithmic engines balance margin-per-square-foot targets against inventory turnover velocity.
- Performance Analytics Solutions:Dashboard layers aggregate ASO outputs for merchandising team KPI tracking.
Planogram Software absorbs the bulk of installed capacity; Demand Forecasting Systems are expanding most quickly.
Deployment Mode:
Operational flexibility requirements separate elastic cloud architectures from fixed on-premise installations with multi-year amortization schedules.
- Cloud-Based:Elastic compute resources scale processing capacity during seasonal assortment shifts without hardware procurement cycles. United States grocery retailers dominate adoption as omnichannel fulfillment nodes require real-time inventory synchronization.
- SaaS:Subscription licensing bundles software, infrastructure, and vendor-managed updates into per-store fees. Japanese convenience store operators favor this model for rapid rollout across dense urban networks.
- On-Premises:Dedicated servers host ASO workloads within retailer data centers for data sovereignty compliance.
- Hybrid:Split architectures process sensitive demand data locally while offloading visualization rendering to cloud instances.
- Managed Services:Third-party vendors operate ASO infrastructure on retailer behalf, absorbing talent scarcity risks.
Cloud-Based deployments command the largest share of new contract value; SaaS is climbing the fastest among mid-market buyers.
Application:
Functional priority separates revenue-focused use cases from cost-reduction workflows across merchandising organizational structures.
- Category Management:Strategic modules align SKU assortment with shopper segment preferences and competitive positioning. German retailers embed EU Green Deal packaging compliance data into these workflows to preempt regulatory shelf-level violations.
- Inventory Turnover Improvement:Algorithmic engines reduce days-on-hand for perishable categories through demand sensing and automated replenishment triggers. United States supermarket chains target these capabilities for fresh produce departments where shrinkage rates erode profitability.
- Sales Optimization:Margin-per-square-foot maximization tools prioritize high-velocity, high-margin SKU placement.
- Shelf Space Allocation:Micro-level planogram execution assigns specific facings and positions within fixture configurations.
- Customer Experience Enhancement:Shopper journey analytics link spatial layouts to satisfaction metrics and basket composition.
Category Management retains the deepest enterprise penetration; Inventory Turnover Improvement is gaining share fastest in grocery verticals.
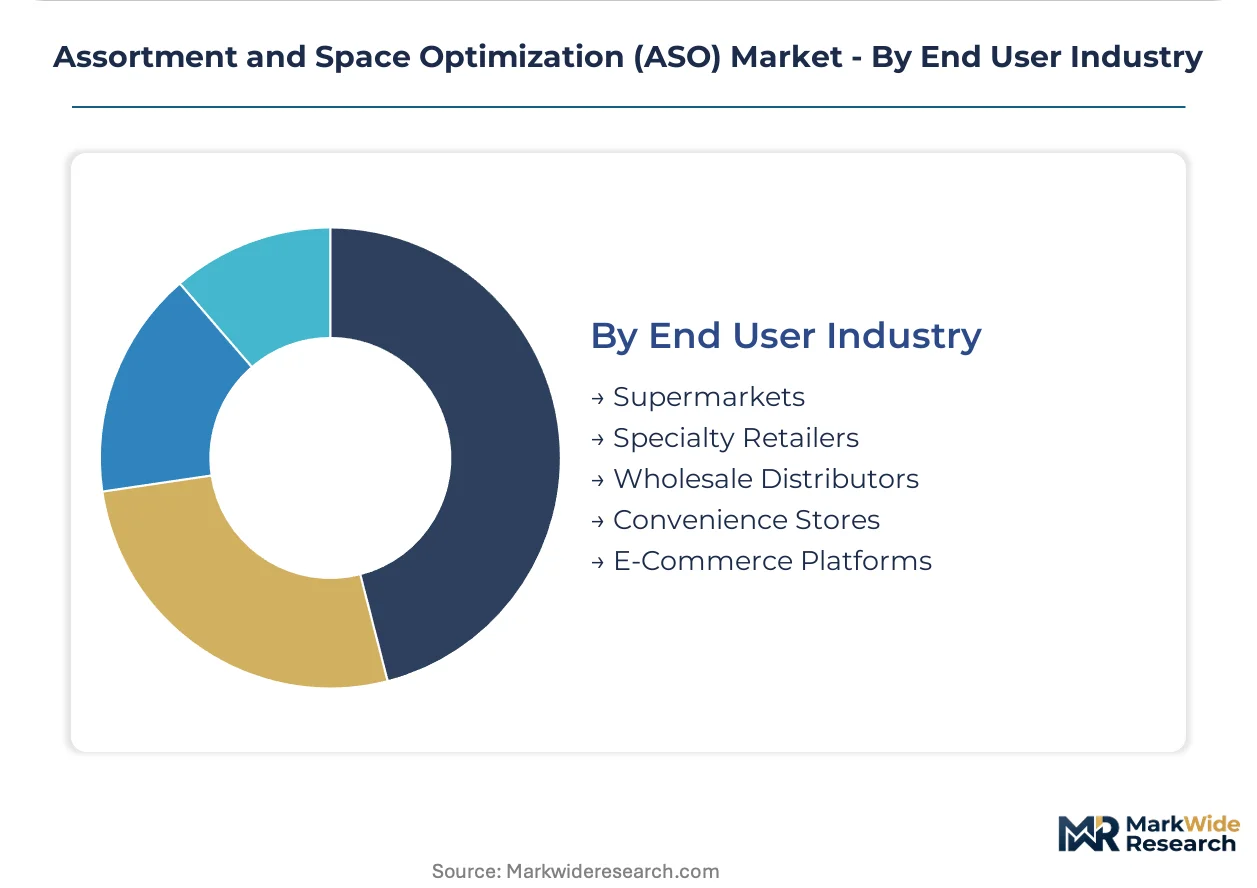
End User Industry:
Store format economics dictate ASO complexity requirements, from hypermarket-scale optimization to micro-assortment precision in constrained footprints.
- Supermarkets:Large-format operators deploy full-stack ASO platforms across tens of thousands of SKUs and multi-department space planning. United States chains lead investment as consolidation creates procurement leverage for outcome-based vendor contracts.
- Convenience Stores:Dense urban networks in Japan operate with extreme SKU proliferation in minimal square footage, requiring store-cluster-level assortment differentiation. METI efficiency mandates accelerate platform adoption for inventory precision.
- Specialty Retailers:Category-focused operators optimize curated assortments with deep SKU-level demand elasticity modeling.
- Wholesale Distributors:B2B-focused platforms balance pallet-level throughput with retail-format customer requirements.
- E-Commerce Platforms:Digital-native fulfillment operations apply ASO logic to virtual shelf ranking and warehouse slotting optimization.
Supermarkets represent the largest installed base; Convenience Stores show the steepest expansion trajectory in AI-native platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American ASO deployment as Kroger, Albertsons, and Jewel-Osco operate dense supermarket networks requiring synchronized shelf allocation across digital fulfillment nodes. The metropolitan corridor concentrates vendor implementation teams and retailer procurement headquarters.
United States
Omnichannel grocery fulfillment drives ASO adoption as Walmart and Target synchronize physical shelf allocation with curbside pickup nodes. FDA food-labeling rules force assortment rule engines to embed compliance data upstream into space planning workflows. The Dallas-Fort Worth metroplex hosts concentrated pilot programs for AI-native demand forecasting in perishable categories.
Germany
EU Green Deal packaging mandates reshape space allocation algorithms as retailers model carbon intensity per SKU alongside margin targets. REACH chemical disclosure standards extend traceability requirements into assortment decisions for private-label categories. The Rhine-Ruhr industrial corridor concentrates METRO AG and REWE Group procurement leverage for outcome-based vendor contracts.
Japan
METI efficiency mandates accelerate platform adoption across dense urban convenience store networks operating extreme SKU proliferation in minimal square footage. Seven-Eleven Japan and Lawson deploy store-cluster-level micro-assortment differentiation. The Kanto region surrounding Tokyo anchors highest-density pilot programs for probabilistic demand models ingesting weather and event signals.
United Kingdom
Tesco and Sainsbury's procurement consolidation compresses vendor pricing power and elongates sales cycles for ASO implementations. GDPR compliance requirements constrain cloud-based deployment architectures for shopper panel data integration. The London-Southeast corridor concentrates retailer headquarters and vendor account management teams.
India
Reliance Retail and D-Mart expansion creates demand for cloud-scalable ASO platforms managing rapid store rollout schedules. FSSAI food safety regulations embed compliance checkpoints into shelf-level assortment workflows. The Mumbai-Pune industrial corridor anchors emerging vendor implementation partnerships for mid-market grocery chains.
Assortment and Space Optimization (ASO) Market Key Industry Players
Capital-heavy enterprise software producers compete with asset-light specialized vendors for ASO market position. The vendor base stratifies across three tiers: AI-native platforms commanding premium pricing, legacy ERP-integrated suites competing on vertical stack depth, and open-source planogram tools eroding commodity margins. Dominant competitive moves include cloud migration acceleration and outcome-based contract structures tying fees to measurable inventory turnover improvement.
Within the AI-native tier, RELEX Solutions and SymphonyAI exemplify machine learning-first positioning for high-complexity grocery environments. Oracle Corporation and Blue Yonder Group Inc. occupy positions anchored to deep ERP integration, leveraging existing enterprise relationships to bundle space optimization with broader supply chain suites. Nielsen Consumer LLC represents the data-centric archetype, differentiating through proprietary shopper panel feeds that train assortment models.
| Leading Market Players |
|---|
| RELEX Solutions |
| Kantar Group Limited |
| Oracle Corporation |
| JDA Software |
| Solteq |
| SymphonyAI |
| Nielsen Consumer LLC |
| Infor |
| Blue Yonder Group Inc. |
| Others |
Cost & Logistics Intelligence
Cloud compute pricing indices from hyperscale providers cascade through ASO vendor cost structures, compressing SaaS subscription tiers as retailers demand elastic capacity without hardware procurement cycles. This input cost dynamic stratifies pricing power between AI-native platforms and commodity planogram tools.
Pricing Analysis
Value-based pricing anchors on inventory turnover improvement metrics tie vendor fees to measurable shrinkage reduction in perishable categories. Pricing stratifies across premium AI-native platforms, standard ERP-integrated suites, and economy-tier open-source visualization tools. Cost compression in the planogram tier intensifies as GitHub-hosted alternatives erode proprietary vendor margins. Mid-market grocery chains exhibit highest price sensitivity; enterprise supermarket consolidators leverage procurement scale for outcome-based contract terms.
Supply Chain Analysis
Machine learning talent supply rests on United States, Germany, and India educational pipelines feeding data science labor pools. GPU hardware for model training draws from Taiwan semiconductor foundries and South Korea memory fabricators. Single-source vulnerability concentrates in NVIDIA chip supply for demand forecasting model acceleration. Distribution runs through direct enterprise sales teams for large grocery chains and channel partners for mid-market specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASO procurement operates as a cost-of-compliance story where EU Green Deal packaging mandates and FDA food-labeling rules erect regulatory moats favoring vendors with embedded rule-engine capabilities.
For Market Incumbents: Deepen vertical integration into proprietary shopper panel data assets to defend against Nielsen Consumer LLC's data-centric positioning. Expand cloud-native architecture investment to capture seasonal elasticity demand from United States omnichannel grocers. Reinforce compliance module development as REACH chemical disclosure standards harden. For New Entrants and Emerging Players: Digital-channel routes through AWS Marketplace and Azure Marketplace offer lowest-friction customer acquisition for AI-native demand forecasting modules. Target Japanese convenience store operators with store-cluster micro-assortment tools as METI efficiency mandates accelerate platform replacement cycles. Lead with SaaS subscription models absorbing talent scarcity risks for buyers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier planogram vendors facing open-source margin compression in Germany and United States markets. Long-term viability hinges on AI-native platform consolidation as probabilistic models displace static tools. Watch FDA unit-dose tracking rulemaking as inflection signal for pharmacy shelf integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Migration Acceleration | Elastic compute capacity captures seasonal assortment shifts without hardware procurement delays. |
| AI-Native Platform Development | Machine learning demand sensing displaces static planogram tools in perishable categories. |
| Compliance Module Integration | Embedded EU Green Deal and FDA rule engines preempt regulatory shelf-level violations. |
| Outcome-Based Contract Structuring | Fees tied to inventory turnover improvement align vendor incentives with retailer KPIs. |
| Digital Twin Convergence | IoT shelf sensor fusion enables dynamic planogram adjustment and subscription revenue models. |
Research Approach
Document review covered SEC 10-K filings, grocery retailer earnings transcripts, and EU regulatory gazettes, complemented by interviews with merchandising executives, IT procurement officers at supermarket chains, and vendor solution architects. Secondary validation drew from Nielsen retail audit data, hyperscaler capex disclosures, and METI efficiency mandate documentation. Bottom-up and top-down triangulation reconciled vendor revenue estimates with retailer technology spend surveys.
Market sizing outputs reflect segmentation across deployment mode, solution type, and end-user industry dimensions throughout the forecast period. CAGRs derive from regression analysis against cloud adoption curves and AI investment trajectories. Model inputs incorporate grocery consolidation rates, perishable shrinkage benchmarks, and regulatory compliance cost estimates.
The model holds under stable cloud pricing and continued retailer consolidation; deviation in hyperscaler cost structures or antitrust intervention would shift vendor pricing power. Forecasts reflect assumptions around machine learning talent availability and open-source tool maturity. A small set of triggers—FDA rulemaking acceleration, EU carbon-accounting mandate enforcement, and Japanese convenience store network expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Ediscovery Solution Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Decision Support System Market
Digital Solutions
Transport Management System Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Europe ICT Market