
 Digital Transformation Market | 2026-2036
Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Transformation Market Intelligence
Platform licensing revenue is rewriting profitability expectations across enterprise software ecosystems. Microsoft Corporation leverages its Azure cloud infrastructure to anchor hybrid deployment architectures for Fortune 500 clients. SAP SE specializes in vertical ERP modules that sustain premium pricing within manufacturing verticals. IBM Corporation navigates mainframe-to-cloud transitions for regulated industries requiring sovereign data controls.
Digital transformation denotes the systematic integration of digital technologies—encompassing cloud-native architectures, API-driven interoperability, and real-time data pipelines—into operational and commercial workflows to replace analog processes and enable algorithmic decision-making. Cloud Computing dominates technology spending as enterprises retire on-premises data centers, while AI segments capture expanding margin pools through predictive analytics subscriptions. Managed Services within the Service Type dimension is maturing fastest as clients shift from project-based integration toward outcome-based operational contracts.
The EU AI Act imposes risk-tiered compliance obligations on automated decision systems, compelling vendors to rearchitect product roadmaps for European market access. FDA's software-as-medical-device framework in the US and China's GB standards for industrial data security collectively fragment certification requirements across jurisdictions. Stakeholders must monitor regulatory divergence between Brussels and Beijing as dual compliance costs threaten to bifurcate vendor product strategies.
Market Dynamics
EU AI Act risk-tiered compliance obligations are forcing enterprise software vendors to rearchitect product roadmaps for European market access, compressing procurement cycles and elevating sovereign data controls as a primary vendor selection criterion.
Growth Catalysts
- Cloud migration mandates:BFSI institutions are accelerating spending on hybrid deployment architectures to meet EU AI Act deadlines, prioritizing vendors with pre-certified automated decision systems.
- Industrial IoT deployment:Germany's automotive OEMs anchor enterprise IoT rollouts across the industrial automation corridor, creating concentrated demand for predictive analytics subscriptions.
- API-driven interoperability:Real-time data pipelines are replacing analog workflows in manufacturing verticals, enabling algorithmic decision-making at plant-floor level.
Market Restraints
- Sovereign data localization costs:China's GB standards for industrial data security and Brussels' data residency rules impose dual compliance architecture costs on multinational vendors.
- Mainframe-to-cloud transition friction:Regulated industries with decades-old COBOL cores face multi-year migration timelines that delay SaaS margin capture.
- Skills scarcity in edge computing:Shortage of engineers proficient in container orchestration and Kubernetes limits deployment velocity for hybrid architectures.
Strategic Opportunities
- Outcome-based operational contracts:Managed Services maturation creates white space for vendors willing to assume operational risk through performance-guaranteed SLAs rather than project fees.
- AI-enabled predictive maintenance:Convergence of machine learning with industrial sensor networks opens subscription revenue pools in automotive and heavy manufacturing sectors.
- India's PLI scheme for electronics:Production-linked incentives for semiconductor and hardware manufacturing create localized cloud infrastructure demand from new domestic OEMs.
Industry Challenges
- Regulatory fragmentation across jurisdictions:FDA's software-as-medical-device framework, EU AI Act risk tiers, and China's algorithmic recommendation provisions create incompatible certification requirements.
- Technical debt in legacy ERP systems:SAP and Oracle on-premise instances resist cloud-native API integration, forcing expensive middleware layers that erode project margins.
- Talent competition for MLOps engineers:Scarce practitioners who bridge data science and production infrastructure command compensation premiums that inflate service delivery costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Transformation Market |
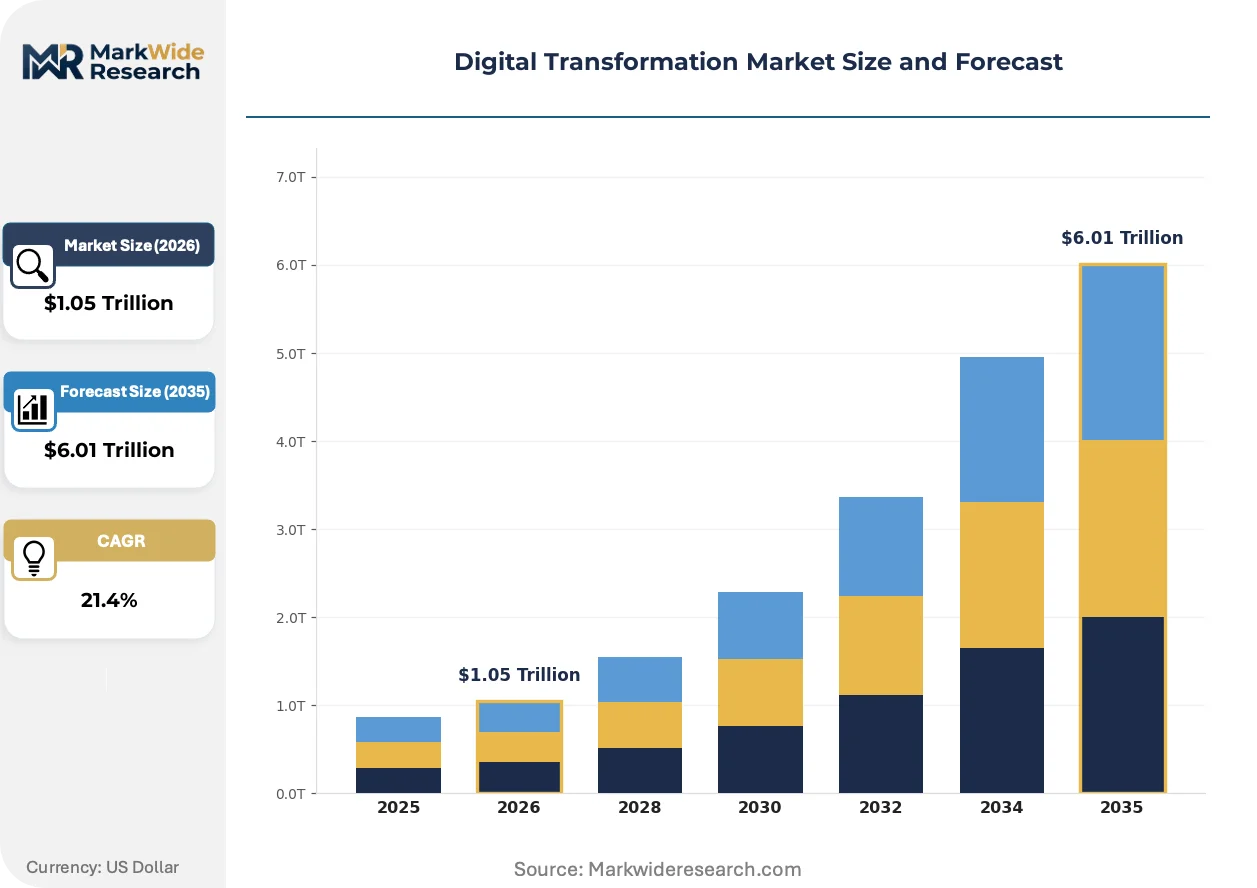
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $6.01 Trillion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Big Data, Cloud Computing Service Type: Consulting, Integration, Support, Managed Services End User: Retail, BFSI, Healthcare, Manufacturing Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Accenture PLC, IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Cisco Systems, Inc., Adobe Inc., Google LLC, Capgemini SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Transformation Market Strategic Shifts & Innovations
Edge-to-cloud orchestration platforms are collapsing traditional IT-OT boundaries, while regulatory divergence between Brussels and Beijing fragments vendor product strategies and procurement patterns shift toward consumption-based pricing models.
Serverless computing architectures are collapsing the distinction between infrastructure provisioning and application deployment. Automotive OEMs in Germany's industrial corridor adopt function-as-a-service platforms to process telemetry streams from connected vehicles without maintaining persistent server capacity. This technology is collapsing capital expenditure requirements for mid-tier manufacturers seeking real-time analytics capabilities.
REACH chemical substance restrictions and RoHS hazardous material bans are reshaping hardware procurement specifications for data center equipment. Server and networking vendors must reformulate solder compositions and capacitor electrolytes to maintain European market access. Industrial automation OEMs in Germany's manufacturing belt face the steepest compliance recertification timelines.
Buyers now unbundle implementation services from software licensing, treating systems integration as a competitive tender separate from platform selection. Value-added resellers and boutique consultancies capture implementation margins that incumbent vendors once retained. This pattern is most visible in France and the Netherlands where procurement regulations mandate multi-vendor bidding for professional services above threshold contract values.
Digital Transformation Market Segmentation
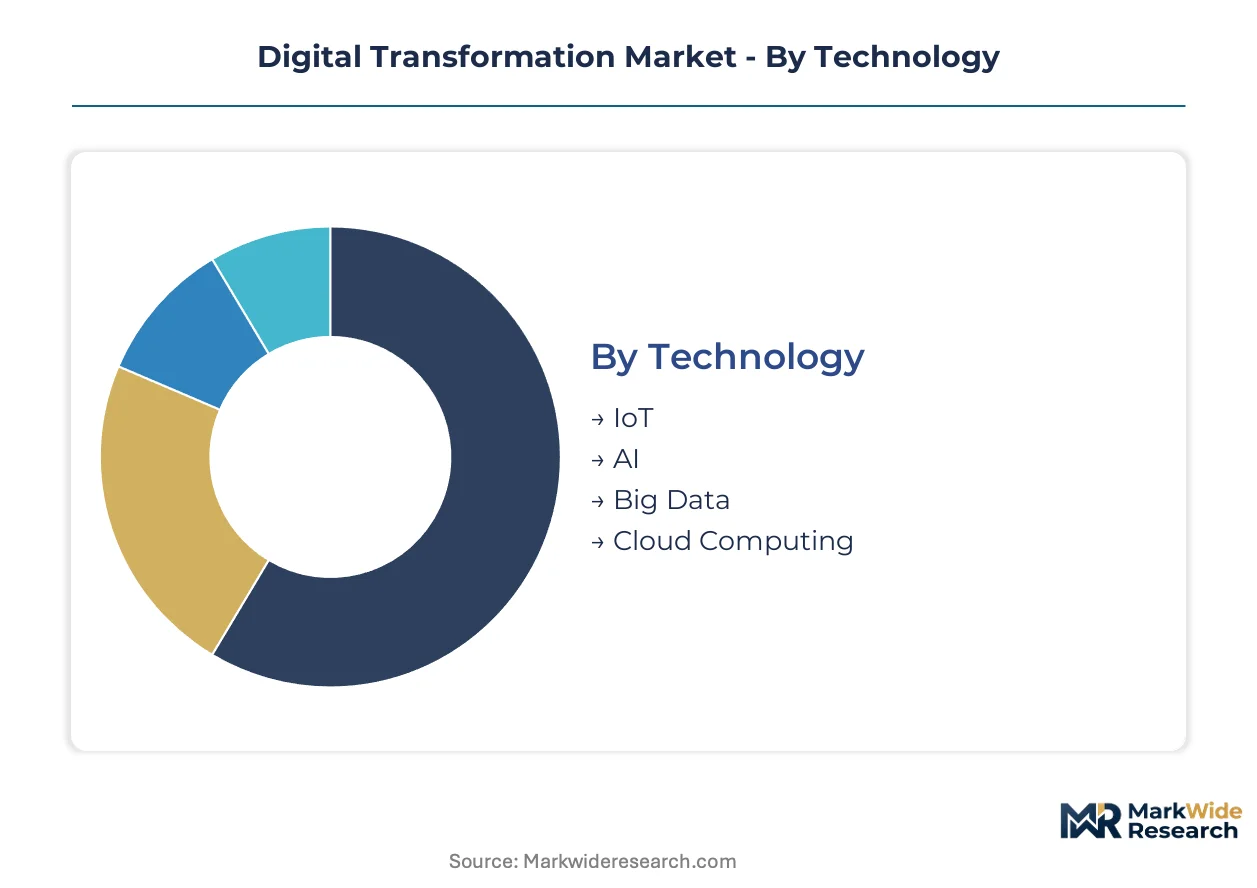
Segmentation reveals how procurement priorities diverge across technology stacks, service models, and deployment architectures. Understanding these fault lines exposes where margin pools concentrate and which vendor configurations align with buyer risk profiles.
Technology:
Technology selection determines capital intensity, compliance exposure, and integration complexity across enterprise buyers.
- Cloud Computing:Hyperscale infrastructure enables elastic capacity provisioning without on-premises hardware depreciation. BFSI institutions in Germany and France prioritize sovereign cloud instances to satisfy EU AI Act data residency requirements while retiring legacy data center assets.
- AI:Machine learning platforms automate decision workflows through predictive models and natural language processing. Automotive OEMs across Germany's industrial corridor embed computer vision into quality control systems, driving subscription revenue for edge-deployed inference engines.
- IoT:Sensor networks and connected device ecosystems generate real-time operational telemetry. Manufacturing verticals deploy industrial IoT gateways to monitor equipment health and optimize production line throughput.
- Big Data:Distributed storage and analytics frameworks process petabyte-scale datasets for pattern recognition. Healthcare systems leverage clinical data lakes to support population health management and research collaborations.
Cloud Computing commands the established base. The steepest expansion runs through AI.
Service Type:
Service model selection reflects buyer maturity and risk transfer preferences.
- Managed Services:Outcome-based operational contracts shift infrastructure accountability to vendors through performance-guaranteed SLAs. German automotive suppliers favor multi-year managed service agreements to internalize operational risk while preserving capital for core R&D.
- Consulting:Strategic advisory engagements assess digital readiness and roadmap transformation initiatives. France's procurement regulations mandate competitive tendering for consulting contracts above threshold values, fragmenting vendor capture rates.
- Integration:Systems implementation connects disparate platforms through API orchestration and middleware deployment. Retail chains require point-of-sale integration with e-commerce backends to unify inventory visibility.
- Support:Technical maintenance and troubleshooting services sustain production system availability. Healthcare providers demand 24/7 support coverage for clinical systems governed by FDA software-as-medical-device frameworks.
Consulting commands the established base. Managed Services is climbing the fastest.
End User:
End-user verticals impose distinct regulatory, security, and workflow requirements on solution architecture.
- Manufacturing:Industrial automation and smart factory deployments integrate MES, ERP, and IoT layers for real-time production optimization. Germany's automotive OEMs anchor concentrated demand for predictive maintenance subscriptions.
- BFSI:Banking and insurance institutions navigate stringent compliance mandates while modernizing core banking platforms. EU AI Act deadlines compress procurement cycles for automated decision systems with pre-certified risk classifications.
- Healthcare:Clinical workflows and patient data management require HIPAA-compliant infrastructure with audit trail capabilities. US health systems balance cloud migration against FDA software-as-medical-device validation requirements.
- Retail:Omnichannel commerce platforms unify inventory, fulfillment, and customer engagement across physical and digital touchpoints. European retailers adapt to CSRD sustainability reporting mandates through supply chain traceability investments.
Manufacturing commands the established base. BFSI is gaining share fastest.
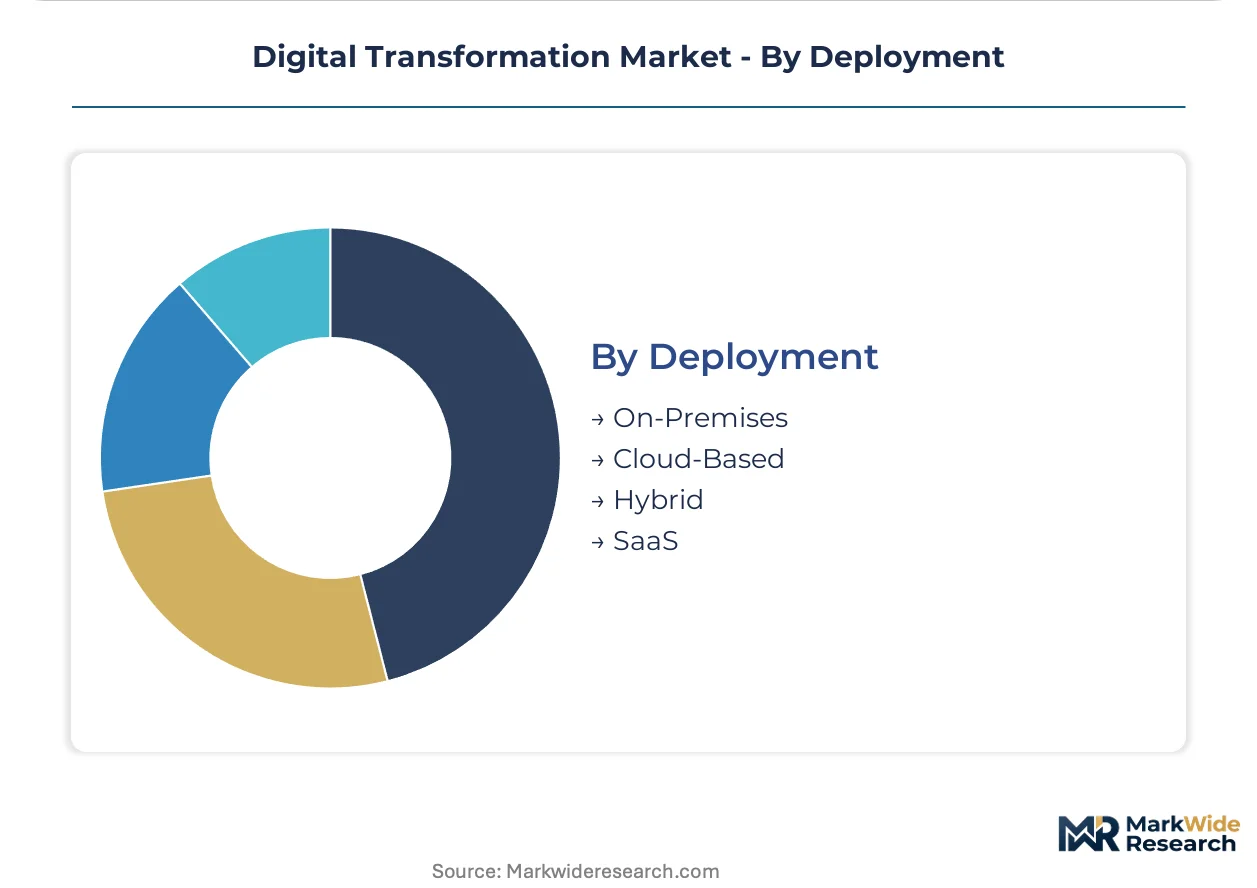
Deployment:
Deployment architecture determines data sovereignty, latency performance, and operational control trade-offs.
- Hybrid:Mixed on-premises and cloud infrastructure enables workload portability while preserving sensitive data locally. Regulated industries favor hybrid configurations to satisfy Brussels data residency rules without sacrificing scalability.
- Cloud-Based:Fully outsourced infrastructure eliminates capital expenditure and accelerates time-to-value for non-sensitive workloads. Mid-market manufacturers adopt cloud-based MES to avoid on-premises server maintenance overhead.
- SaaS:Software-as-a-service delivery standardizes functionality across tenants while enabling rapid feature updates. France and the Netherlands mandate multi-vendor bidding for SaaS implementations above threshold contract values.
- On-Premises:Self-managed infrastructure retains full operational control and air-gapped security for classified environments. Defense and critical infrastructure operators maintain on-premises deployments despite higher total cost of ownership.
On-Premises commands the established base. Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany's industrial automation corridor concentrates enterprise IoT procurement, while US health systems prioritize HIPAA-compliant cloud migration. China's GB standards for industrial data security impose architecture requirements absent in other markets.
United States
Healthcare systems and BFSI institutions drive hybrid cloud adoption. FDA's software-as-medical-device framework imposes validation requirements on clinical AI deployments. The Greater Boston corridor anchors health-tech digital transformation clusters.
Germany
Automotive OEMs anchor concentrated demand for predictive maintenance and smart factory deployments. EU AI Act risk-tiered compliance deadlines compress procurement cycles for automated decision systems. The Baden-Württemberg industrial belt sustains premium ERP module demand.
China
Manufacturing verticals deploy industrial IoT gateways under state-mandated digital upgrade programs. GB standards for industrial data security and algorithmic recommendation provisions fragment certification requirements. The Yangtze River Delta concentrates smart factory investment.
India
Production-linked incentives for electronics manufacturing create localized cloud infrastructure demand from domestic OEMs. RBI guidelines on data localization shape BFSI procurement priorities. Karnataka's Bengaluru-Tumkur corridor anchors SaaS and enterprise software development.
United Kingdom
Financial services firms navigate post-Brexit regulatory divergence while modernizing core banking platforms. FCA operational resilience requirements impose system availability standards on critical digital infrastructure. London's fintech cluster drives API-driven interoperability investment.
Digital Transformation Market Key Industry Players
Capability concentration sits with specialized consultancies; scale advantage sits with hyperscale cloud providers. The market exhibits tiered fragmentation across implementation services, platform licensing, and managed operations. Strategic archetypes include full-stack systems integrators, vertical ERP specialists, and infrastructure-centric platform vendors. Competitive moves center on outcome-based contracting structures and sovereign cloud certification acquisition.
Within the full-stack systems integrator tier, Accenture PLC and Capgemini SE exemplify service-led positioning. IBM Corporation occupies a transitional position bridging mainframe heritage with hybrid cloud architectures. These three entities represent distinct responses to regulatory fragmentation: Accenture PLC emphasizes multi-jurisdictional compliance capabilities, Capgemini SE anchors European market access, and IBM Corporation leverages regulated industry relationships.
| Leading Market Players |
|---|
| Accenture PLC |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Cisco Systems, Inc. |
| Adobe Inc. |
| Google LLC |
| Capgemini SE |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Frankfurt freight corridor channels hyperscale hardware into Germany's industrial automation belt, where elevated logistics costs compress margins for edge-computing deployments and force three-tier pricing stratification across enterprise software tiers.
Pricing Analysis
Long-term managed service contracts dominate BFSI procurement, anchoring vendor revenue visibility while spot-based SaaS tiers capture mid-market manufacturers seeking elasticity without capital commitment. Price differentiation rests on sovereign cloud certification grade and vertical customization depth. Cost compression in standard-tier offerings intensifies as Indian SaaS providers undercut European incumbents on implementation labor. Mid-market manufacturers exhibit highest price sensitivity; regulated BFSI institutions accept premium pricing for pre-certified EU AI Act compliance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor procurement risk for AI inference hardware, compelling German automotive OEMs to dual-source GPU accelerators from Taiwan and South Korea. Supply concentration in Taiwanese foundry capacity and Malaysian packaging facilities creates single-source vulnerability for edge-computing chipsets. Rare earth elements for data center magnets draw from Chinese processing facilities. Distribution runs through value-added resellers in France and the Netherlands, where procurement regulations fragment vendor capture rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards vendors commanding scarce sovereign cloud certifications and MLOps engineering talent, while buyers face procurement compression from divergent regulatory mandates across Brussels, Beijing, and Washington.
For Market Incumbents: Insulate recurring revenue streams by embedding outcome-based SLAs into managed service contracts that internalize operational risk. Accelerate certification investment for EU AI Act high-risk system classifications before compliance deadlines harden vendor selection criteria. Acquire boutique Kubernetes consultancies to address edge-computing skills scarcity threatening deployment velocity. For New Entrants and Emerging Players: Pursue white space in India's PLI-driven electronics manufacturing corridor, where domestic OEMs lack localized cloud infrastructure partners. Target mid-tier automotive suppliers in Baden-Württemberg seeking predictive maintenance subscriptions without hyperscale vendor lock-in. Lead with API-first interoperability positioning that bypasses entrenched ERP integration complexity. For Investors and Strategic Acquirers: Sovereign cloud specialists with pre-certified EU AI Act compliance represent the most defensible acquisition profile against regulatory fragmentation. Long-term viability hinges on dual-compliance architecture capabilities spanning Brussels and Beijing mandates. Monitor FDA software-as-medical-device validation timelines as inflection indicators for healthcare vertical penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acquisition | EU AI Act pre-certification locks in BFSI procurement decisions ahead of compliance deadlines. |
| Outcome-Based Contract Structuring | Performance-guaranteed SLAs shift risk from German automotive suppliers to vendors. |
| Edge-to-Cloud Platform Integration | Serverless architectures collapse capital requirements for mid-tier manufacturers. |
| Specialist Consultancy Acquisition | Kubernetes expertise scarcity inflates service delivery costs without captive talent. |
| Geographic Expansion into India | PLI scheme electronics manufacturing creates localized infrastructure demand from domestic OEMs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC filings, EU regulatory filings, and trade data covering cloud infrastructure equipment. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners across manufacturing and BFSI verticals inform demand-side validation. Bottom-up sizing of subscription revenue pools triangulates against top-down analysis of enterprise software spending across the analysis window.
Forecast inputs span deployment architecture, organization size, vertical end-use, integration complexity, and regional regulatory cluster. CAGRs derive from segmented growth trajectory modeling across technology and service type dimensions. AI-enabled predictive maintenance adoption curves and sovereign cloud procurement velocity anchor the projection framework throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers into managed services would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Workplace Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Saudi Arabia Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Italy Digital Transformation Market