
 Digital Pattern Generator Market | 2026-2036
Digital Pattern Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pattern Generator Market Outlook
Multi-gigabit pattern fidelity is redrawing competitive boundaries in digital pattern generators. Keysight Technologies leverages in-house semiconductor fabrication to sustain waveform precision leadership. Tektronix anchors North American defense and aerospace calibration demand through deep channel partnerships. Berkeley Nucleonics competes in portable high-speed instruments for field-deployed research teams.
A digital pattern generator is an electronic instrument that produces precise digital waveforms with defined voltage levels, edge rates, and timing relationships to stimulate devices under test. FPGA-based architectures now dominate because reprogrammable logic enables protocol flexibility without hardware redesign across PCIe, DDR, and MIPI standards. Standalone generators capture the largest revenue pool among product types due to their universality across R&D benches and production floors. Semiconductor manufacturers represent the fastest-expanding end user segment as advanced packaging nodes multiply test insertion points per wafer.
FCC equipment authorization rules shape electromagnetic compatibility requirements for instruments sold into US telecom infrastructure projects. China's MIIT enforces GB standards on signal generators used in domestic 5G and satellite communication development. ISO/IEC 17025 laboratory accreditation requirements in Europe and East Asia filter market access to metrology-grade customers. Stakeholders must monitor how export control expansions on high-bandwidth test equipment reshape supplier eligibility for defense and semiconductor fabrication accounts.
Market Dynamics
Multi-gigabit pattern fidelity requirements are compressing vendor margins while fragmenting procurement authority between R&D benches and centralized test operations teams. Semiconductor manufacturers now demand protocol-flexible instruments that span PCIe, DDR, and MIPI standards without hardware swaps.
Growth Catalysts
- MIIT signal integrity mandates:China's stricter GB standards for 5G baseband chips force domestic foundries to upgrade test equipment fleets, creating instrument refresh cycles.
- Advanced packaging test insertion multiplication:Each wafer now requires pattern generators at bumping, stacking, and final test stages, expanding unit demand per semiconductor output.
- East Asian foundry cluster concentration:Memory manufacturers near Seoul are consolidating procurement around high-channel-count systems, driving volume commitments.
Market Restraints
- High-bandwidth component supply concentration:Specialized DACs and clocking ICs source from limited US and Japanese foundries, creating allocation risk during demand spikes.
- FCC equipment authorization complexity:Electromagnetic compatibility certification for instruments sold into US telecom infrastructure extends time-to-revenue by six to nine months.
- FPGA silicon cost volatility:Reprogrammable logic devices from Xilinx and Intel constitute thirty to forty percent of bill-of-materials, exposing margins to foundry pricing swings.
Strategic Opportunities
- Portable field-deployed instruments:Research teams operating outside traditional lab environments need battery-powered pattern generators with optical isolation, a category underserved by benchtop-centric vendors.
- Calibration-as-a-service models:ISO/IEC 17025 accredited laboratories in Germany and South Korea are unbundling hardware sales from recurring metrology subscriptions.
- Defense channel partnerships:North American aerospace primes are consolidating vendor lists around instruments with pre-approved TAA compliance and secure supply chains.
Industry Challenges
- High-speed signal integrity engineering scarcity:Vendors compete for limited talent pools capable of designing sub-picosecond jitter circuits across multiple process nodes.
- Legacy GPIB integration friction:Automated test equipment floors running decades-old infrastructure resist Ethernet-based instrument control, forcing dual-interface hardware designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pattern Generator Market |
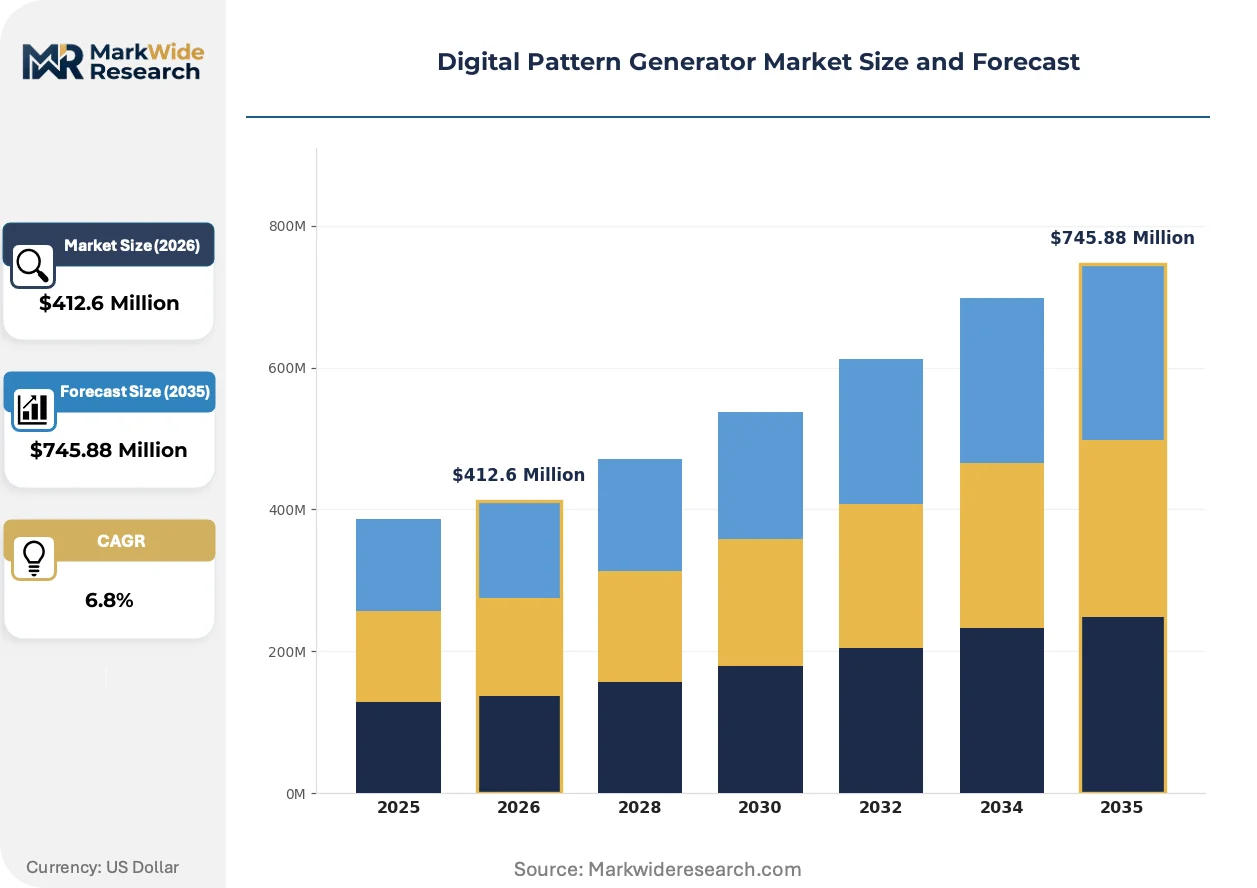
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Generators, Integrated Systems, Software Solutions, Test Equipment Application: Electronic Testing, Signal Processing, Telecommunication, Imaging Systems Technology: A/D Converters, FPGA-Based, ASIC-Based, Microcontroller-Based End User: Telecom Companies, Semiconductor Manufacturers, Research Institutions, Defense |
| Companies Covered | Keysight Technologies, Tektronix, Berkeley Nucleonics, Chroma, National Instruments, Active Technologies, Teledyne LeCroy, Siglent Technologies, Tabor Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pattern Generator Market Strategic Shifts
FPGA-based architectures are dissolving the boundary between hardware-defined and software-defined test, enabling single instruments to morph across digital protocols through firmware loads rather than module swaps.
Software-defined pattern generation is decomposing the traditional instrument stack. FPGA fabrics with embedded ARM cores now execute waveform sequencing that previously demanded external controllers. Memory foundries in South Korea are deploying these systems at line-replaceable-unit scale. The shift is compressing vendor differentiation toward firmware ecosystems rather than analog front-end superiority.
China's MIIT is tightening GB standard enforcement on signal generators used in domestic 5G and satellite communication development. Equipment sold into these programs must demonstrate traceable calibration to national metrology institutes. Domestic semiconductor manufacturers are responding by qualifying only instruments with in-country service infrastructure, filtering foreign vendor access.
Research procurement is consolidating around multi-year framework agreements rather than transactional spot purchases. University labs and government research institutes are bundling pattern generator acquisitions with adjacent oscilloscope and probe investments. This concentration is visible across European national measurement institutes and US Department of Energy facilities, where centralized procurement offices now override individual PI authority.
Digital Pattern Generator Market Segmentation
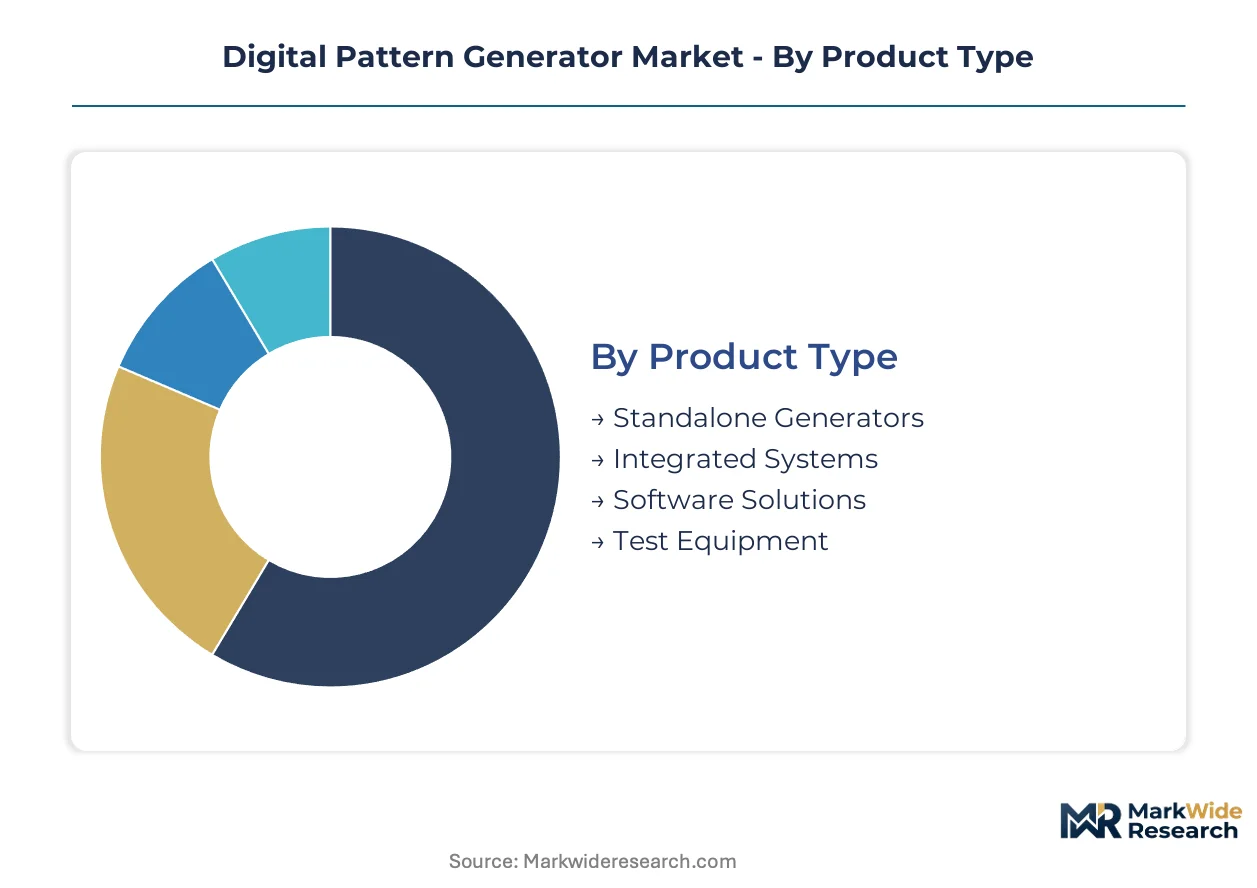
Digital pattern generator procurement fragments sharply between domestic calibration laboratories and export-driven semiconductor fabrication facilities. Understanding where demand concentrates within each segment category reveals which product configurations justify dedicated SKU investment versus modular platform coverage.
Product Type:
Domestic R&D facilities favor benchtop instruments with local service infrastructure, while export-led semiconductor foundries prioritize rack-mountable systems with remote calibration capabilities.
- Standalone Generators:Self-contained instruments with integrated power supplies and touchscreen interfaces dominate university electronics laboratories and mid-tier contract manufacturers. Demand clusters in Germany's metrology institutes and South Korea's memory foundry cluster near Seoul, driven by ISO/IEC 17025 accreditation requirements that mandate traceable calibration chains.
- Integrated Systems:Modular chassis accepting multiple pattern generator cards alongside oscilloscope and power supply modules serve high-volume production floors. Procurement concentrates among China's domestic 5G baseband chip manufacturers responding to MIIT signal integrity mandates, with volume commitments tied to multi-year framework agreements rather than spot purchases.
- Software Solutions:Pattern generation firmware running on third-party FPGA hardware appeals to cost-constrained research teams with existing instrumentation infrastructure.
- Test Equipment:Bundled configurations combining pattern generators with probes, cables, and calibration accessories capture institutional procurement offices seeking single-vendor accountability.
Standalone generators hold the largest share; momentum sits with integrated systems.
Application:
Cost tier stratification separates premium instruments for satellite communication development from economy configurations serving educational laboratories.
- Electronic Testing:Characterization of integrated circuits, printed circuit boards, and system-level prototypes consumes the majority of pattern generator hours. Demand concentrates in Japan's automotive electronics suppliers verifying MIPI DSI interfaces for dashboard displays, with procurement authority shifting from individual engineers to centralized test operations teams.
- Signal Processing:Algorithm validation for radar, software-defined radio, and spectral analysis applications requires arbitrary pattern sequencing with sub-nanosecond edge placement. China's domestic satellite communication programs under MIIT GB standards enforcement drive qualification of instruments with in-country service infrastructure.
- Telecommunication:5G baseband and mmWave frontend verification demands multi-gigabit pattern fidelity with programmable impairment injection.
- Imaging Systems:Sensor readout timing verification for medical and industrial cameras requires precise horizontal and vertical sync pattern generation.
Electronic testing commands the dominant revenue pool; signal processing is climbing the fastest.
Technology:
Supply concentration in Xilinx and Intel FPGA foundries exposes margins to silicon pricing volatility across reprogrammable architectures.
- FPGA-Based:Reprogrammable logic fabrics enable protocol flexibility across PCIe, DDR, and MIPI standards through firmware loads rather than hardware redesign. Memory foundries in South Korea deploy these systems at line-replaceable-unit scale, compressing vendor differentiation toward firmware ecosystems.
- A/D Converters:High-speed digital-to-analog conversion cores with integrated pattern memory serve specialized arbitrary waveform generation requirements in defense and aerospace calibration.
- ASIC-Based:Application-specific integrated circuits deliver lowest unit cost for high-volume production test with fixed protocol requirements.
- Microcontroller-Based:Embedded processor solutions with limited pattern depth satisfy educational and low-speed industrial control applications.
FPGA-based architectures hold the largest share; ASIC-based alternatives are gaining share fastest in cost-sensitive production environments.
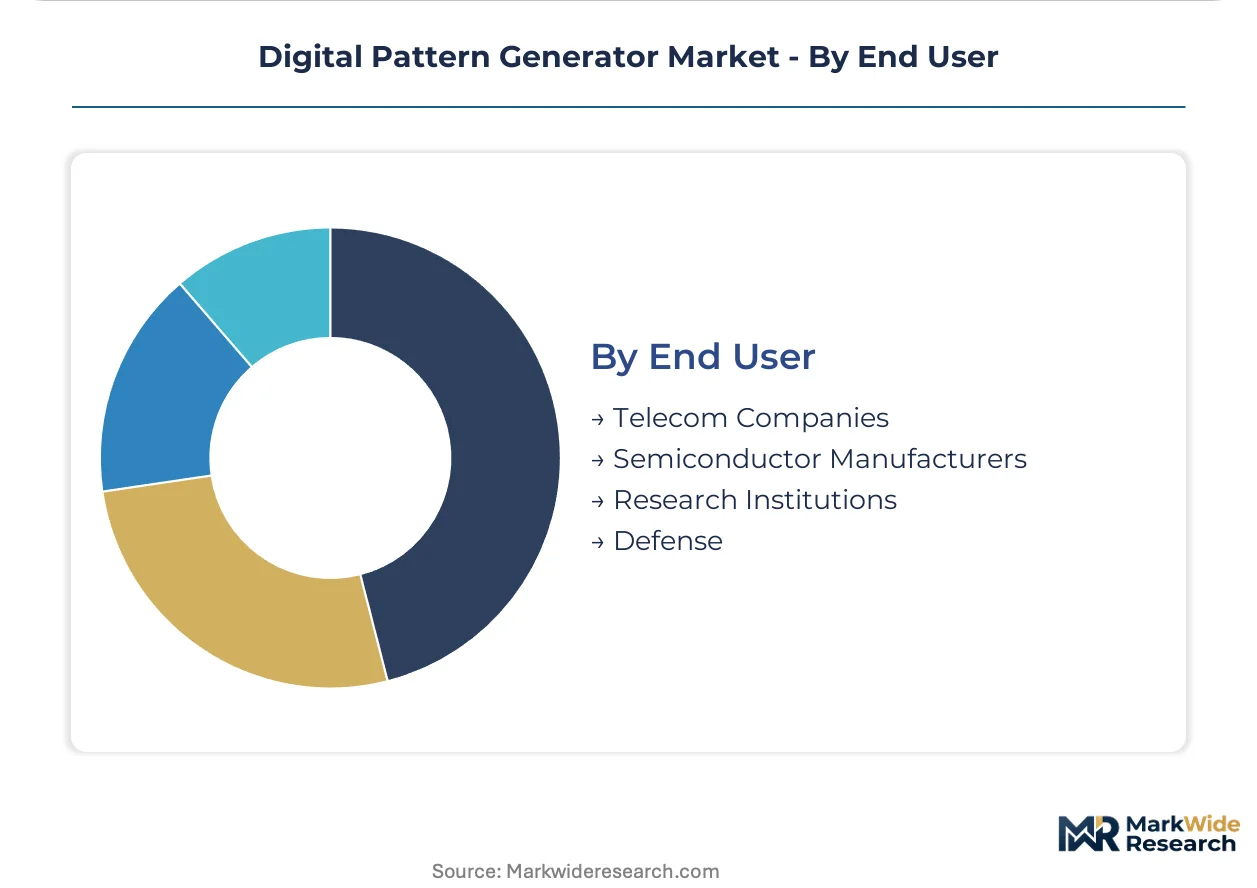
End User:
Customer type determines margin structure, with defense and semiconductor manufacturers accepting premium pricing for secure supply chains and protocol flexibility.
- Semiconductor Manufacturers:Advanced packaging nodes multiply test insertion points per wafer, expanding unit demand at bumping, stacking, and final test stages. Procurement concentrates in East Asian foundry clusters, with China's domestic manufacturers qualifying only instruments with in-country service infrastructure.
- Defense:North American aerospace primes consolidate vendor lists around instruments with pre-approved TAA compliance and secure supply chains, filtering access for foreign component suppliers.
- Telecom Companies:5G infrastructure deployment drives pattern generator demand for baseband verification and optical transceiver testing.
- Research Institutions:University laboratories and government research institutes bundle pattern generator acquisitions with adjacent oscilloscope investments under multi-year framework agreements.
Semiconductor manufacturers hold the largest share; defense exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in digital pattern generators tilt toward East Asian fabrication clusters, with equipment imports concentrated in semiconductor-producing economies and calibration-grade instruments circulating within European metrology networks.
China
Domestic 5G baseband chip production and satellite communication programs drive instrument procurement. MIIT enforces GB standards on signal generators, requiring traceable calibration to national metrology institutes. Foundries in Shanghai and Beijing qualify only equipment with in-country service infrastructure, filtering foreign vendor access.
South Korea
Memory foundry expansion near Seoul multiplies test insertion points per wafer, expanding unit demand. The national standards body aligns with ISO/IEC 17025 for laboratory accreditation. Samsung and SK Hynix operations in Gyeonggi Province consolidate procurement around high-channel-count systems with multi-year volume commitments.
United States
Defense and aerospace calibration demand anchors North American procurement, with FCC equipment authorization rules shaping electromagnetic compatibility requirements. Northrop Grumman and Lockheed Martin primes in California and Texas consolidate vendor lists around TAA-compliant instruments with secure supply chains.
Germany
Automotive electronics verification and national measurement institute operations sustain demand for metrology-grade instruments. REACH and RoHS directives constrain component sourcing for instruments sold into European markets. Calibration laboratories in Berlin and Munich unbundle hardware sales from recurring metrology subscriptions.
Japan
Automotive MIPI DSI interface verification and industrial imaging sensor development consume pattern generator hours. METI oversees industrial standards alignment with international test protocols. Suppliers in Nagoya and Osaka serve Denso and Renesas with instruments optimized for production floor durability.
Digital Pattern Generator Market Competitive Environment
Concentration sits with diversified test equipment conglomerates and specialized high-speed instrument developers. The vendor base stratifies across three tiers: full-stack measurement platforms, protocol-specific modular systems, and portable field-deployed units. Strategic moves center on FPGA firmware ecosystem development and defense channel pre-qualification for TAA compliance.
Among diversified instrumentation conglomerates, Keysight Technologies and Tektronix exemplify platform-scale positioning through in-house semiconductor fabrication and deep channel partnerships respectively. Berkeley Nucleonics occupies a specialist tier focused on portable high-speed instruments. These three represent the archetype spread: captive silicon control, aerospace-defense anchoring, and field-deployed research flexibility.
| Leading Market Players |
|---|
| Keysight Technologies |
| Tektronix |
| Berkeley Nucleonics |
| Chroma |
| National Instruments |
| Active Technologies |
| Teledyne LeCroy |
| Siglent Technologies |
| Tabor Electronics |
| Others |
Value Chain & Pricing Dynamics
FPGA silicon substitution for discrete logic components simultaneously shifts procurement geography toward Xilinx and Intel foundries and compresses margin structures across reprogrammable instrument tiers. This input transition concentrates pricing power with semiconductor foundries while forcing pattern generator vendors to absorb silicon cost volatility or pass through to concentrated buyer bases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium metrology-grade, standard production-test, and economy educational-laboratory instruments. Price differentiation rests on ISO/IEC 17025 certification tier and channel service bundling rather than raw performance specifications alone. Cost compression in economy tiers intensifies because Chinese domestic manufacturers qualify only instruments with in-country service infrastructure, filtering foreign vendor access and forcing localization investments. Research institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while defense primes accept premium positioning for TAA compliance and secure supply chain documentation.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for specialized DACs and clocking ICs that feed pattern generator assembly. Component sourcing draws from limited US and Japanese foundries for high-bandwidth analog front-ends, creating allocation risk during semiconductor demand spikes. Single-source vulnerability concentrates in Xilinx and Intel FPGA supply, with reprogrammable logic constituting substantial bill-of-materials exposure. Distribution runs through authorized test equipment distributors serving metrology laboratories and direct OEM relationships with memory foundries in East Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital pattern generator market exhibits cyclical recovery characteristics as semiconductor capital expenditure cycles rebound from foundry utilization troughs. Memory fab expansion in South Korea and domestic 5G baseband investment in China provide the cyclical impetus.
For Market Incumbents: Secure firmware ecosystem lock-in through protocol-specific intellectual property libraries that raise switching costs for memory foundry customers. Acquire calibration-as-a-service capabilities in Germany and South Korea to capture recurring metrology subscription revenue and defend against modular instrument commoditization. Channel control through defense prime pre-qualification offers margin protection against emerging portable instrument competitors. For New Entrants and Emerging Players: Differentiate on battery-powered optical isolation for field-deployed research teams operating outside traditional laboratory infrastructure, a configuration underserved by benchtop-centric incumbents. Target European national measurement institutes consolidating procurement under multi-year framework agreements that bundle pattern generators with adjacent oscilloscope investments. Pursue university laboratory channel partnerships with aggressive service bundling to overcome brand disadvantage against established metrology vendors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed test equipment conglomerates seeking portfolio rationalization. Five-to-ten year viability hinges on FPGA firmware ecosystem depth rather than analog hardware superiority. Monitor MIIT GB standard enforcement intensity as inflection indicator for Chinese domestic manufacturer qualification windows and foreign vendor access filtration.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Ecosystem Expansion | Protocol library depth locks in memory foundry customers across PCIe and DDR verification requirements. |
| Calibration-as-a-Service Launch | ISO/IEC 17025 accredited laboratories in Berlin and Seoul unbundle hardware from recurring metrology subscriptions. |
| Defense Channel Pre-Qualification | TAA compliance documentation opens Northrop Grumman and Lockheed Martin procurement lists to qualified vendors. |
| Portable Instrument Development | Battery-powered optical isolation captures research teams operating outside traditional laboratory environments. |
| In-Country Service Infrastructure | Domestic calibration capabilities satisfy MIIT mandates filtering foreign vendor access to Chinese foundries. |
Study Parameters
Cross-validation between primary interviews with test equipment procurement managers and secondary validation through FCC equipment authorization databases anchors the qualitative findings. Semiconductor manufacturer test operations directors, metrology laboratory accreditation officers, defense prime supplier quality engineers, and university research facility managers provided operational perspective. Trade flow data, MIIT GB standard filings, ISO/IEC 17025 accreditation registries, and SEC disclosures from diversified instrumentation conglomerates furnished quantitative grounding. Bottom-up instrument shipment estimates and top-down semiconductor capital expenditure patterns were reconciled through iterative triangulation.
Sensitivity analysis across FPGA silicon pricing scenarios, foundry utilization cycles, and regulatory enforcement intensity brackets the projection range. Segmentation dimensions modeled include product architecture, end-user industry, protocol application, geographic regulatory cluster, and service bundling configuration. CAGRs were derived from instrument unit demand elasticities tied to wafer-level test insertion multiplication and value-per-unit trajectories reflecting firmware ecosystem premium capture. Defense procurement cycle timing and academic research grant funding patterns provided industry-specific forecast inputs.
Material uncertainties — export control expansions on high-bandwidth test equipment, FPGA foundry allocation disruptions, and MIIT standard enforcement variability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding semiconductor capital expenditure recovery trajectory and defense budget authorization continuity. Recalibration cycles align with material shifts in foundry buildout announcements and national security technology restriction updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Professional Printers Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Digital Production Printer Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Cloud Print Market
Printing Technology
Card Printers Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Web to Print Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Digital Franking Machine Market