
 Print Equipment Market | 2026-2036
Print Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Print Equipment Market Intelligence
The traditional offset press operator skill base is collapsing under pressure from digital workflow automation. This shift benefits digital-native firms, where HP Inc. leverages its deep expertise in inkjet technology. In contrast, Heidelberger Druckmaschinen AG sustains its market position by integrating digital front-ends into its offset presses, while Koenig and Bauer AG competes in high-growth packaging segments.
Print equipment encompasses machinery that transfers images onto substrates like paper or textiles, using technologies such as piezoelectric printheads to eject ink droplets. Their primary commercial purpose is producing materials for packaging, advertising, and publishing. Digital presses and 3D printers represent the fastest-growing product types, displacing some traditional laser printer applications. The packaging application segment offers higher margins than the more commoditized commercial printing space.
Regulatory frameworks influence equipment design and ink formulation. In Europe, compliance with both REACH for chemical safety and CE marking for machinery is mandatory. Manufacturers must also navigate EPA rules on solvent emissions in the United States and meet China's GB standards. Stakeholders must decide whether to invest in flexible, multi-substrate digital platforms or optimize existing analog workflows for specific high-volume applications.
Market Dynamics
The print equipment market's central dynamic is the structural shift from analog offset processes to digital workflows. This transition creates tension between optimizing legacy systems for high-volume runs and investing in flexible digital platforms for customized, short-run production.
Growth Catalysts
- Packaging Sector Demand:The need for customized, short-run boxes and labels in the consumer goods industry creates significant pull for new digital press installations, particularly in high-consumption markets.
- Environmental Regulations:Mandates such as Europe's REACH framework accelerate the transition to eco-solvent and UV-curable inks, compelling investment in compatible new equipment and phasing out older, non-compliant systems.
- Geographic Industrial Concentration:Demand is highly focused within established manufacturing corridors, such as China's Pearl River Delta and Germany's industrial heartland, where supply chains for both equipment and consumables are mature.
Market Restraints
- High Capital Expenditure:The substantial upfront investment required for industrial-grade digital presses acts as a barrier to entry for smaller commercial print shops, slowing fleet modernization.
- Analog Workflow Inertia:Many large-scale printing operations have deeply integrated and fully depreciated offset workflows, making the business case for a complete digital transition difficult without a compelling external trigger.
- Substitution by Digital Media:The proliferation of digital advertising and electronic communication channels continues to erode the total addressable volume for certain commercial print applications like magazines and direct mail.
Strategic Opportunities
- Industrial Textile Printing:Digital printing technology offers a significant opportunity to disrupt traditional screen-printing in the fast fashion and home decor textile segments with on-demand production.
- Printed Electronics:The convergence of printing and electronics creates an opportunity for specialized equipment capable of depositing conductive inks on flexible substrates for applications like RFID antennas and sensors.
- Service and Consumables Contracts:Shifting from a pure capital equipment sales model to a recurring revenue model based on service, software, and certified ink supplies offers more predictable revenue streams.
Industry Challenges
- Operator Skill Gap:The decline of the traditional offset press operator base leaves a void that is difficult to fill, requiring significant investment in training for digital press operation and workflow management.
- System Integration Complexity:Integrating new digital front-ends and presses with a company's existing management information systems and prepress software presents a significant technical and operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Print Equipment Market |
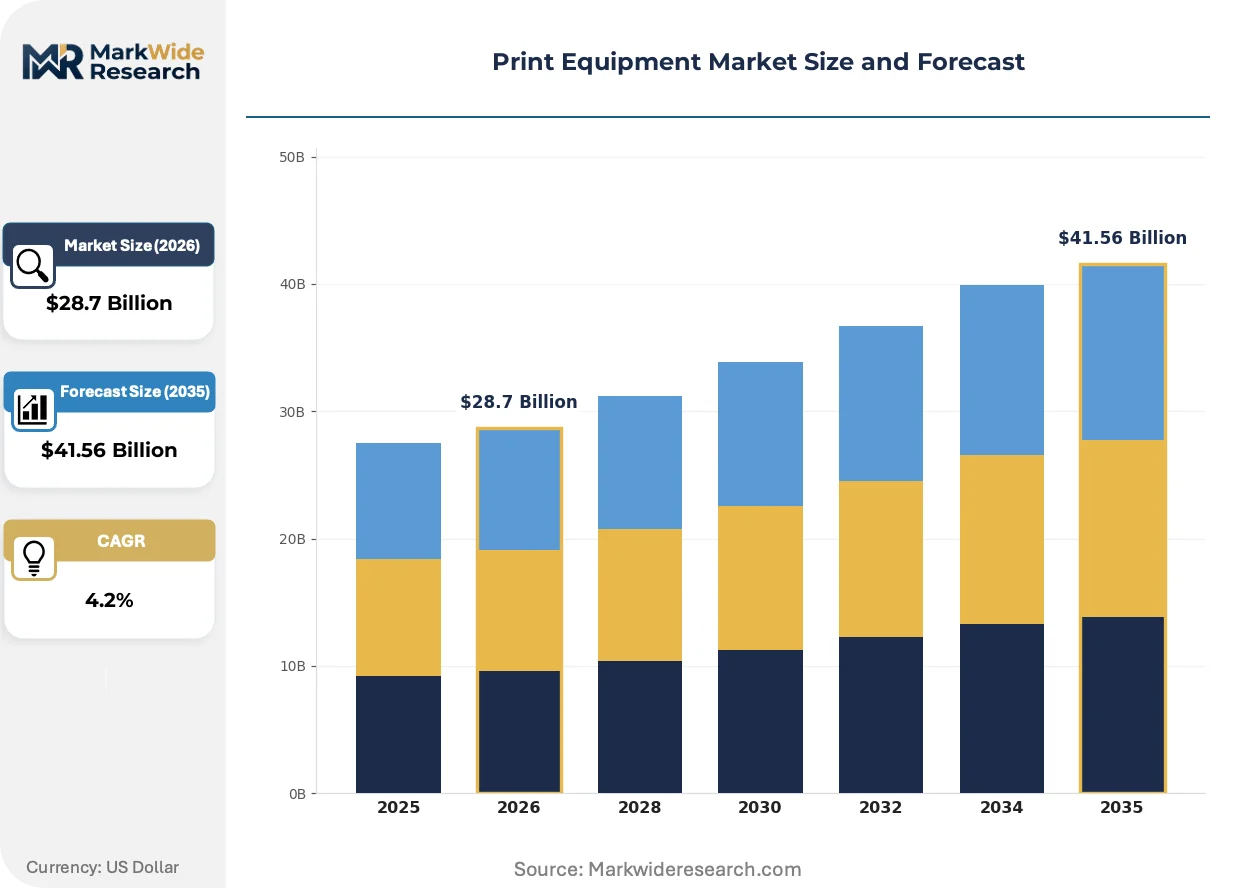
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $41.56 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, 3D Printers, Thermographic Printers, Digital Presses Technology: Thermal, Electrophotographic, Piezoelectric, Dye Sublimation, Solid Ink Application: Commercial Printing, Packaging, Textile Design, Architectural Modeling, Prototyping End User: Publishing Houses, Advertising Agencies, Fashion Designers, Engineering Firms, Educational Institutions |
| Companies Covered | Heidelberger Druckmaschinen AG, Koenig and Bauer AG, Bobst Group SA, HP Inc., Canon Inc., Seiko Epson Corporation, Fujifilm Holdings Corporation, Ricoh Company Ltd., Komori Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Print Equipment Market Strategic Shifts & Innovations
The industry is being reshaped by the twin pressures of sustainability mandates and the economic necessity of automation. These forces are compelling manufacturers to develop more efficient, less wasteful printing systems that require less manual intervention from operators.
Digital Inkjet Technology
Advanced piezoelectric printheads define the leading edge of product innovation, enabling precise ejection of ink droplets for high-resolution imaging. Packaging converters and commercial printers are adopting this technology to meet demands for variable data printing and rapid prototyping. This technology is supplanting traditional offset and flexographic methods for short-to-medium run lengths, fundamentally altering production economics.
Chemical and Safety Compliance
Regulatory frameworks, particularly the EU's REACH regulation, directly influence ink formulation and equipment design. This legislation restricts the use of certain chemicals, forcing a move towards safer, low-VOC or water-based inks. The commercial printing segment is most affected, as operators must invest in new ventilation systems or compliant print technologies to meet occupational safety and environmental standards.
On-Demand Production Models
Buyer behavior is shifting from large, speculative orders to smaller, just-in-time print runs that minimize waste and inventory costs. This change disrupts the business model of high-volume commercial printers who rely on economies of scale. The trend is most pronounced in the book publishing and direct mail advertising verticals, favoring printers with agile digital production capabilities.
Print Equipment Market Segmentation
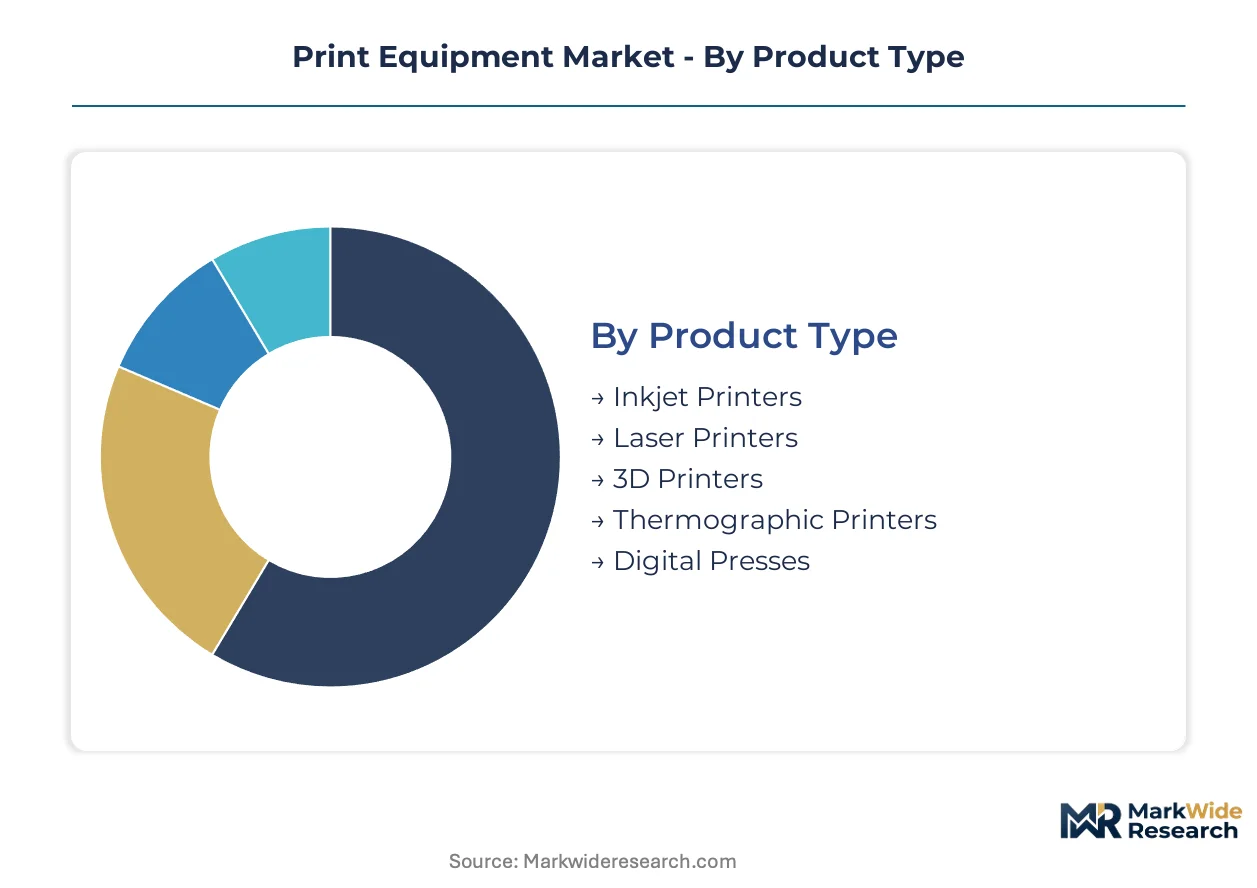
Segmentation of the print equipment market reveals distinct demand patterns and technological preferences across various user groups. Understanding these divisions helps manufacturers tailor product development and market entry strategies. This analysis delineates the market by product type, technology, application, and end-user sectors.
Product Type:
The distribution of print equipment varies significantly based on the product type, with specialized channels serving industrial buyers and broader retail networks addressing smaller-scale needs.
- Digital Presses:These machines integrate digital front-ends for variable data printing, directly transferring images from computer files to substrate. Demand concentrates in commercial printing and packaging hubs, driven by short-run customization and rapid turnaround.
- 3D Printers:These additive manufacturing systems build three-dimensional objects layer by layer from digital designs, often using polymers, metals, or composites. Prototyping and architectural modeling applications in Germany and Japan drive demand, leveraging complex geometries.
- Inkjet Printers:Inkjet technology uses piezoelectric printheads to precisely eject ink droplets onto various substrates for high-resolution imaging.
- Laser Printers:Laser printers employ electrostatic charges to attract toner powder onto a drum, fusing it to paper for office and document output.
- Thermographic Printers:These printers use heat-sensitive paper or ribbons to create images, often found in point-of-sale receipts and label printing.
Laser Printers dominate the installed base for general office use. Digital Presses are where expansion concentrates for commercial and industrial applications.
Technology:
Technology choices in print equipment are fundamentally driven by specific application requirements, influencing output quality and material compatibility.
- Piezoelectric:This technology utilizes ceramic materials that deform under electric current, precisely ejecting ink droplets through printheads onto diverse substrates. Packaging and industrial textile printing in China's Pearl River Delta leverage this for variable data and short-run production.
- Electrophotographic:This process creates an electrostatic image on a photoreceptor drum, attracting toner particles that are transferred and fused onto paper. Commercial printing and office environments in the United States and Europe widely use this for high-speed document output.
- Thermal:Thermal technology applies heat to transfer ink or activate heat-sensitive paper, commonly used in label and receipt printing.
- Dye Sublimation:Dye sublimation printers use heat to transfer dye onto materials like fabric or plastic cards, producing continuous-tone, high-quality images.
- Solid Ink:Solid ink technology melts wax-based ink sticks, which are then transferred to a print drum and pressed onto paper, known for vibrant colors.
Electrophotographic technology currently holds a significant share of the installed base. Piezoelectric technology is expanding most quickly due to its versatility across new digital applications.
Application:
The profitability of print equipment sales is heavily influenced by the margin profiles of various application segments, with some offering significantly higher returns.
- Packaging:This application involves printing on materials for product containers, labels, and flexible packaging, often requiring specialized presses for diverse substrates. Demand in the consumer goods sector, especially in Europe and North America, drives customized, short-run solutions.
- Textile Design:Digital textile printing enables on-demand production of patterns and graphics on fabrics for fashion, home decor, and industrial textiles. Fast fashion trends and customization needs in Asia, particularly China and India, accelerate adoption.
- Commercial Printing:Commercial printing encompasses a broad range of materials like magazines, brochures, and direct mail, often characterized by high-volume runs.
- Architectural Modeling:This application utilizes 3D printing to create physical scale models of buildings and urban designs for visualization and planning purposes.
- Prototyping:Prototyping involves rapid creation of physical models for product development and testing across various industries, frequently employing 3D printing technologies.
Commercial Printing still represents significant print volume. Packaging applications offer greater value and margin opportunities for equipment manufacturers.
End User:
The specific requirements of different end-user types dictate the features and capabilities prioritized in print equipment design and procurement.
- Engineering Firms:These firms utilize print equipment, especially 3D printers, for rapid prototyping, functional part creation, and visualization of complex designs. The automotive and aerospace industries in Germany and the United States drive demand for high-precision additive manufacturing.
- Fashion Designers:Fashion designers leverage digital textile printers for on-demand fabric printing, sample creation, and customized apparel production, reducing lead times and waste. European design houses and Asian manufacturing centers increasingly adopt these flexible systems.
- Publishing Houses:Publishing houses use digital and offset presses for book, magazine, and newspaper production, adapting to smaller, just-in-time print runs.
- Advertising Agencies:Advertising agencies employ print equipment for large-format displays, promotional materials, and direct mail campaigns targeting specific demographics.
- Educational Institutions:Educational institutions utilize various printers for academic materials, research publications, and 3D printing for STEM education and model creation.
Publishing Houses represent a mature segment with established equipment needs. Engineering Firms are driving innovation in additive manufacturing equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global print equipment market exhibits diverse consumption patterns, with some regions prioritizing high-volume analog production while others rapidly adopt flexible digital platforms. This differential reflects varying industrial maturities and regulatory landscapes. Packaging and industrial textile printing drive significant demand in specific geographic clusters.
China
China's print equipment demand is propelled by its vast packaging sector and booming industrial textile market. Compliance with China's GB standards and dual carbon goals influences equipment design choices. The Pearl River Delta concentrates advanced digital press installations, leveraging piezoelectric technology for customized short-run production.
Germany
The German industrial landscape drives demand for sophisticated print equipment, particularly for high-end packaging and architectural modeling. Manufacturers navigate stringent CE marking and REACH regulations for ink formulations. Its industrial heartland, including Baden-Württemberg, invests in integrating digital front-ends into traditional offset presses.
United States
United States demand for print equipment stems from diverse commercial printing needs and growing packaging applications. EPA rules on solvent emissions compel investment in compliant ink formulations and equipment. Major metropolitan areas like New York and Chicago adopt electrophotographic systems for high-speed document output.
Japan
Japanese engineering firms and design studios drive demand for 3D printers used in prototyping and architectural modeling. Equipment design often adheres to strict JIS standards, reflecting precision and quality. The Tokyo and Osaka regions are centers for advanced 3D printing technologies, leveraging complex geometries for product development.
India
India's burgeoning textile industry and expanding consumer goods sector fuel demand for digital print equipment. BIS standards for product quality and environmental guidelines influence machinery investment. Textile manufacturing hubs in Gujarat and Maharashtra rapidly adopt digital textile printing for on-demand and customized production.
Print Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the print equipment market's competitive structure. This market segments into established players optimizing analog systems and agile innovators focusing on digital solutions. Strategic archetypes include diversified technology conglomerates, traditional press manufacturers, and niche additive manufacturing specialists. Companies primarily engage in strategic partnerships for technology co-development and targeted acquisitions to expand digital capabilities.
On the premium-tier vector, HP Inc. exemplifies a technology conglomerate leveraging deep expertise in inkjet technology for digital printing solutions. Heidelberger Druckmaschinen AG, a German-based AG, represents a traditional press manufacturer sustaining its market position by integrating digital front-ends into established offset presses. Koenig and Bauer AG, another German AG, occupies a position focused on high-growth packaging segments, adapting its machinery for specialized applications. These players anchor distinct market segments, from high-volume commercial printing to customized short-run packaging, reflecting the industry's ongoing transition.
| Leading Market Players |
|---|
| Heidelberger Druckmaschinen AG |
| Koenig and Bauer AG |
| Bobst Group SA |
| HP Inc. |
| Canon Inc. |
| Seiko Epson Corporation |
| Fujifilm Holdings Corporation |
| Ricoh Company Ltd. |
| Komori Corporation |
| Others |
Cost & Logistics Intelligence
Large-scale manufacturing economies in print equipment production dictate supply concentration in key regions. This scale also establishes price floors for traditional presses, influencing overall market pricing.
Pricing Analysis
Project-based equipment sales define the core pricing model for industrial print machinery, supplemented by recurring service and consumables contracts. Pricing differentiates based on customization level for digital platforms and comprehensive after-sales service packages. Pricing softness runs through the commoditized commercial printing segment, reflecting digital media substitution. Smaller commercial print shops exhibit high price sensitivity, while engineering firms prioritize precision over cost.
Supply Chain Analysis
Strategic stockpiling of specialized electronic components and printheads complements just-in-time procurement for standard parts in print equipment manufacturing. Supply concentrates in Germany for traditional presses, China for digital assembly, and Japan for precision components. The supply chain relies on piezoelectric ceramics and specialized electronic components. A structural risk involves single-source vulnerability for advanced printhead technology. Direct sales channels serve large industrial customers, with specialized dealers addressing smaller entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The print equipment market presents a defensive-moat story, primarily driven by high switching costs for integrated production workflows. This structural advantage protects established players, despite the ongoing digital transformation.
For Market Incumbents: Fortify existing market positions by integrating digital front-ends into traditional offset presses, countering the threat from digital workflow automation. Incumbents should also invest significantly in R&D for advanced inkjet technology to maintain product leadership. Acquire specialized digital-native firms to bridge the operator skill gap and expand into high-growth segments like industrial textile printing. Capacity additions in Germany support this strategic shift.
For New Entrants and Emerging Players: Differentiate on specialized applications and integrated software solutions, targeting white spaces like printed electronics and industrial textile printing. The packaging application segment in India represents a penetrable market due to its expanding consumer goods sector. New entrants should focus on a go-to-market angle emphasizing flexible, multi-substrate digital platforms bundled with comprehensive service contracts. This approach bypasses the capital expenditure barrier for smaller firms.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital press manufacturers leveraging service and consumable contracts. The market offers long-term viability driven by the structural shift towards digital workflows and specialized printing applications. Investors should target niche additive manufacturing specialists or software firms enhancing system integration complexity. The acceleration of eco-solvent ink adoption serves as a key inflection indicator for market transition.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Piezoelectric Printhead R&D | Advanced piezoelectric technology enables high-resolution imaging and variable data printing for packaging converters. |
| Acquire Digital Workflow Automation Providers | Integrating automation software reduces reliance on traditional offset press operator skills, benefiting digital-native firms. |
| Expand Industrial Textile Printing Capacity | Digital printing disrupts traditional screen-printing in fast fashion and home decor textile segments with on-demand production. |
| Develop Printed Electronics Equipment | Specialized equipment deposits conductive inks on flexible substrates for applications like RFID antennas and sensors. |
| Establish Eco-Solvent Ink Production Facilities | Compliance with Europe's REACH framework accelerates the transition to safer ink formulations, compelling new equipment investment. |
Research Approach
Two parallel data streams informed the analysis: primary qualitative interviews and secondary quantitative data. This combined approach triangulated insights from print equipment manufacturers' product managers, commercial printers' operations managers, and chemical suppliers' R&D directors. Secondary validation utilized SEC 10-K filings, customs data, and industry association reports. Both bottom-up and top-down approaches ensured comprehensive market sizing.
Over the projection horizon, the analytical framework modeled market dynamics across product type, technology, application, end-user, and ink chemistry. Compound annual growth rates were derived from historical trends and projected impacts of growth catalysts. Key industry-specific forecast inputs included packaging demand growth in China and the adoption rates of eco-solvent inks in Europe. This multi-dimensional approach captured market nuances.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or rapid technological obsolescence would require recalibration. Forecasts reflect assumptions regarding current market structure and known regulatory pathways. Revision becomes warranted when geopolitical trade tensions or significant digital media consumption shifts cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Digital Printing Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Printing Machinery Market
Printing Technology
Book Printing Service Market
Printing Technology
Print on Demand Software Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Global Microprinting Market
Printing Technology
Retail Printers Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Global Cloud Printing Services Market