
 Europe Commercial Printing Market | 2026-2036
Europe Commercial Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Printing Market Intelligence
The direct-to-brand sales channel is narrowing as converters consolidate procurement around fewer national print partners. Heidelberg leverages its service network to sustain installed-base loyalty across German industrial clusters. Smurfit Kappa anchors corrugated pre-print demand through integrated packaging design studios in Ireland and the Netherlands. Cimpress PLC competes on web-to-print velocity for SME marketing collateral across fragmented European territories.
Europe commercial printing encompasses the industrial reproduction of text and images onto substrates including paper, plastic, metal, and textile through mechanical or digital processes, typically operating at resolutions between 300 and 2400 dpi depending on application fidelity requirements. Lithographic printing retains dominant share in long-run magazine and catalog work where amortized plate costs yield unit economics digital cannot match. Inkjet technology captures fastest expansion in personalized direct mail and variable-data packaging, while UV printing systems command premium positioning in cosmetic and pharmaceutical label segments requiring chemical resistance and shelf appeal.
REACH mandates from ECHA restrict volatile organic compound formulations in offset inks, pushing converters toward water-based and UV-curable alternatives that alter equipment investment cycles. The EU Green Deal packaging waste directives, enforced through national transpositions in France, Italy, and Germany, mandate recycled content thresholds that reshape substrate sourcing and pre-press verification protocols. Stakeholders must monitor how the EU AI Act's emerging transparency requirements intersect with automated print quality inspection systems before committing to next-generation press installations.
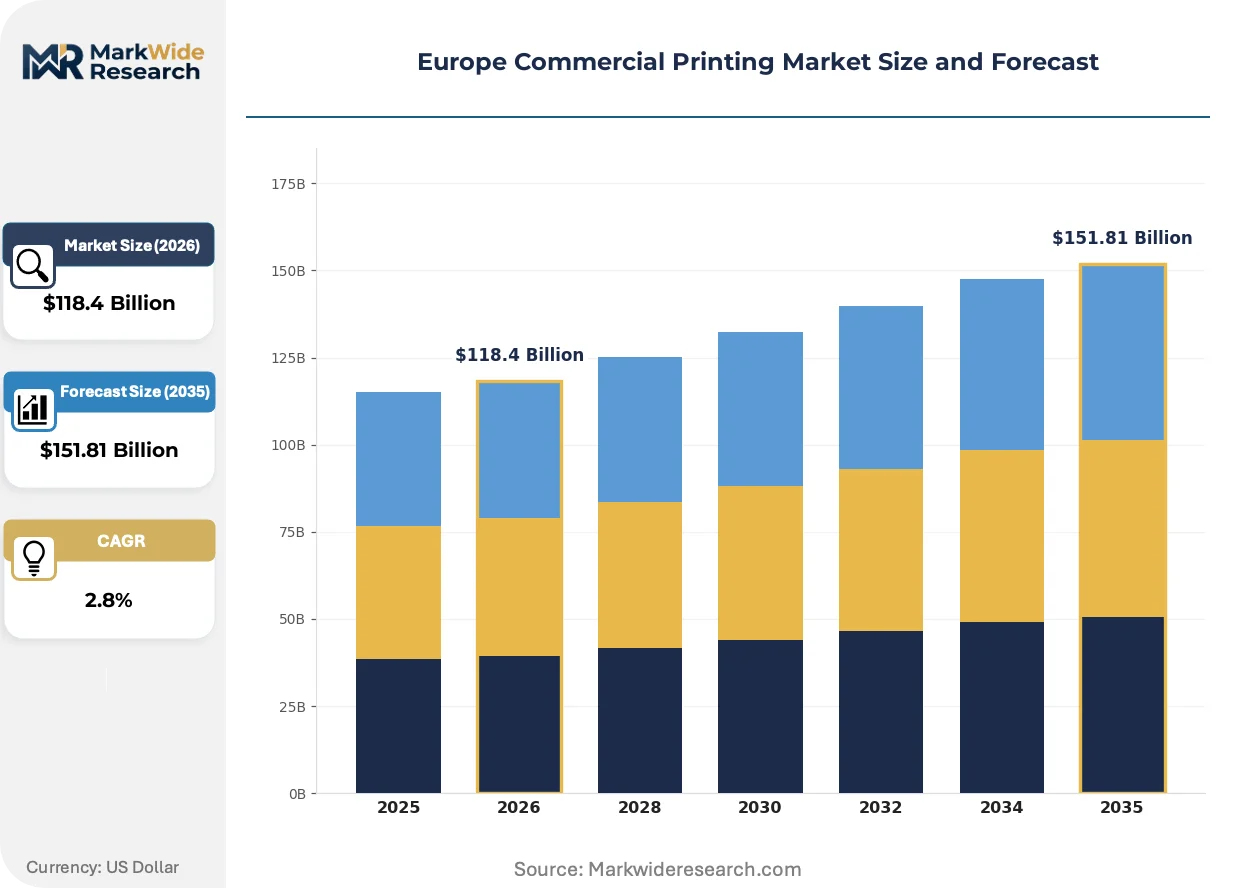
Market Dynamics
Digital inkjet presses are compressing run-length economics across European commercial print, collapsing the minimum efficient scale that once protected offset lithography's dominance in catalog and magazine work.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content thresholds in France, Germany, and Italy force substrate innovation, opening contracts for converters with verified circular supply chains.
- Pharmaceutical serialization:Track-and-trace requirements under the EU Falsified Medicines Directive expand demand for high-resolution variable-data printing on folding cartons and blister packs.
- Luxury goods labeling:France's cosmetics and spirits corridors concentrate investment in tactile embellishment and metallic finishing capabilities.
Market Restraints
- Pulp and energy cost volatility:Nordic paper mills pass through natural gas and wood fiber swings, eroding margin predictability for mid-volume sheetfed operators.
- Skilled press operator scarcity:Germany's industrial regions face retirement waves in offset craft skills without commensurate vocational pipeline replacement.
- REACH chemical disclosure:ECHA's tightening substrate compliance timelines extend pre-production validation cycles for export-bound packaging.
Strategic Opportunities
- Eastern European packaging conversion:Poland and Romania underinvestment in corrugated pre-print creates acquisition targets for Western European integrators.
- Web-to-print platform consolidation:Fragmented SME marketing collateral demand across Benelux and Iberia invites national aggregator roll-ups.
- UV-LED curing convergence:Energy efficiency gains plus instant drying chemistry enable same-day turnaround services for pharmaceutical label emergencies.
Industry Challenges
- Legacy MIS integration:ERP connectivity gaps between web-to-print front ends and Heidelberg/Komori press controls stall automated job routing.
- Color certification bottlenecks:Brand owner Pantone matching and FOGRA compliance requirements extend onboarding for new print partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Printing Market |
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printing, Lithographic Printing, Flexographic Printing, Screen Printing End User: Packaging, Publishing, Advertising, Labeling Technology: Inkjet, UV Printing, Thermal Transfer, Offset Printing Material: Paper, Plastic, Metal, Textile |
| Companies Covered | TC Transcontinental, Inc., Koenig & Bauer, RR Donnelley & Sons Company, Smurfit Kappa, Cimpress PLC, Quad/Graphics, Inc., Heidelberg, Mondi Group, Dai Nippon Printing Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Printing Market Strategic Shifts & Innovations
Automation and regulatory chemistry are rewriting production workflows across European print floors, compressing skill requirements while elevating compliance verification.
Cloud-based pre-press workflows are virtualizing file preparation and color approval cycles. Brand owners in cosmetics and pharmaceuticals adopt browser-based proofing to accelerate launch timelines. This virtualization collapses geographic distance between design studios and production facilities, enabling Baltic and Balkan converters to serve Western European brand headquarters without physical sample transit.
REACH mandates from ECHA restrict volatile organic compound formulations in conventional offset inks. Converters redirect capital toward water-based and UV-curable alternatives with altered rheology profiles. Pharmaceutical and food-contact packaging segments in Germany and France absorb the steepest compliance costs, accelerating qualification of electron-beam curing systems for oxygen-sensitive substrates.
Direct-to-brand e-commerce packaging specifications are bypassing traditional merchant and broker channels. Beauty and specialty food startups in the UK and Netherlands specify unboxing experience requirements directly to corrugated converters with integrated design studios. This disintermediation concentrates volume with national packaging networks capable of structural design, print, and fulfillment under single-roof accountability.
Europe Commercial Printing Market Segmentation
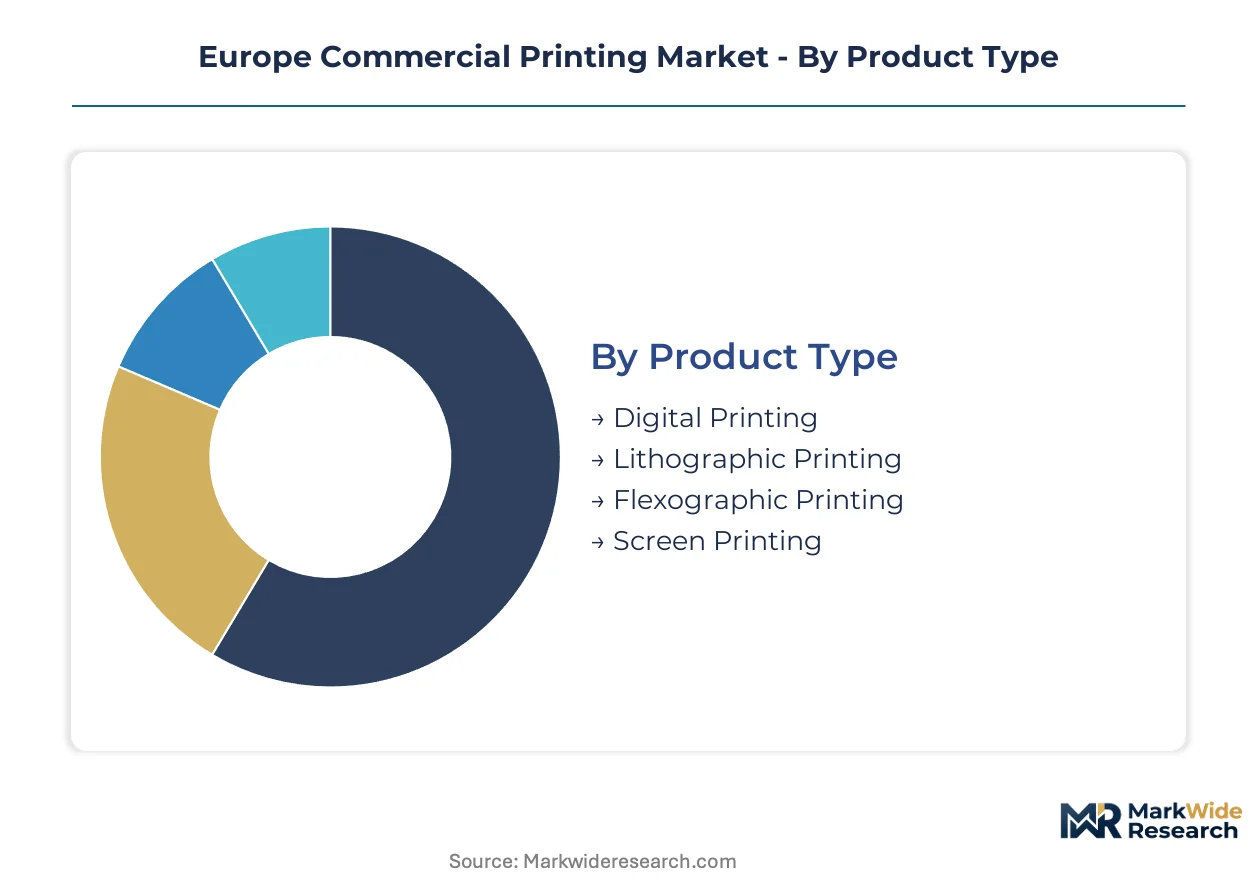
European commercial printing segments diverge sharply in capital intensity and regulatory exposure. Technology choices determine REACH compliance pathways, while end-use concentration in German pharmaceutical corridors and French luxury goods clusters reshapes regional capacity allocation.
Product Type:
Cost tier separates segments by amortization economics and run-length viability across European print floors.
- Lithographic Printing:Plate-based offset systems dominate long-run magazine and catalog work where unit costs collapse across million-plus impressions. German industrial clusters retain the deepest installed base of Heidelberg and Komori sheetfed capacity for high-volume folding carton production.
- Digital Printing:Toner and inkjet systems eliminate make-ready waste, capturing pharmaceutical serialization and personalized direct mail where variable data changes every impression. France's cosmetics labeling corridor concentrates inkjet investment for short-run tactile embellishment.
- Flexographic Printing:Rotary relief printing on continuous webs serves corrugated pre-print and flexible packaging with solvent-based or water-based ink systems.
- Screen Printing:Stencil-based deposition delivers thick ink layers for industrial graphics, electronics, and specialty textile applications.
Lithographic printing holds installed capacity. Digital printing is rotating up the share rankings.
End User:
Application concentration determines margin structure and certification requirements across EU member states.
- Packaging:Folding cartons, corrugated containers, and flexible films absorb the largest share of European print investment. EU Green Deal recycled content mandates in France, Germany, and Italy force substrate verification protocols that favor converters with integrated pre-press and structural design capabilities.
- Labeling:Pressure-sensitive and shrink-sleeve formats serve pharmaceutical track-and-trace and spirits branding. ECHA REACH restrictions on adhesive chemistries and EMA serialization deadlines compress qualification timelines for narrow-web converters.
- Publishing:Periodicals, books, and directories face secular decline as digital media displaces print circulation, concentrating remaining volume in educational and specialty segments.
- Advertising:Point-of-sale displays, direct mail, and outdoor graphics compete with digital advertising for marketing budgets, with variable-data inkjet partially offsetting volume erosion.
Packaging holds installed capacity. Labeling is rotating up the share rankings.
Technology:
Maturity curves separate established chemistries from emerging curing and deposition systems.
- Offset Printing:Conventional oil-based and UV-curable offset dominates long-run commercial work with proven color consistency and FOGRA certification pathways.
- Inkjet:Piezoelectric drop-on-demand systems achieve fastest expansion in packaging prototyping and pharmaceutical serialization, with single-pass widths now matching offset productivity for medium runs.
- UV Printing:Instant curing enables same-day turnaround on non-porous substrates, commanding premium positioning in cosmetic and pharmaceutical label segments requiring chemical resistance.
- Thermal Transfer:Ribbon-based imaging serves barcode and variable-data applications in logistics and healthcare with low capital entry costs.
Offset printing holds installed capacity. Inkjet is rotating up the share rankings.
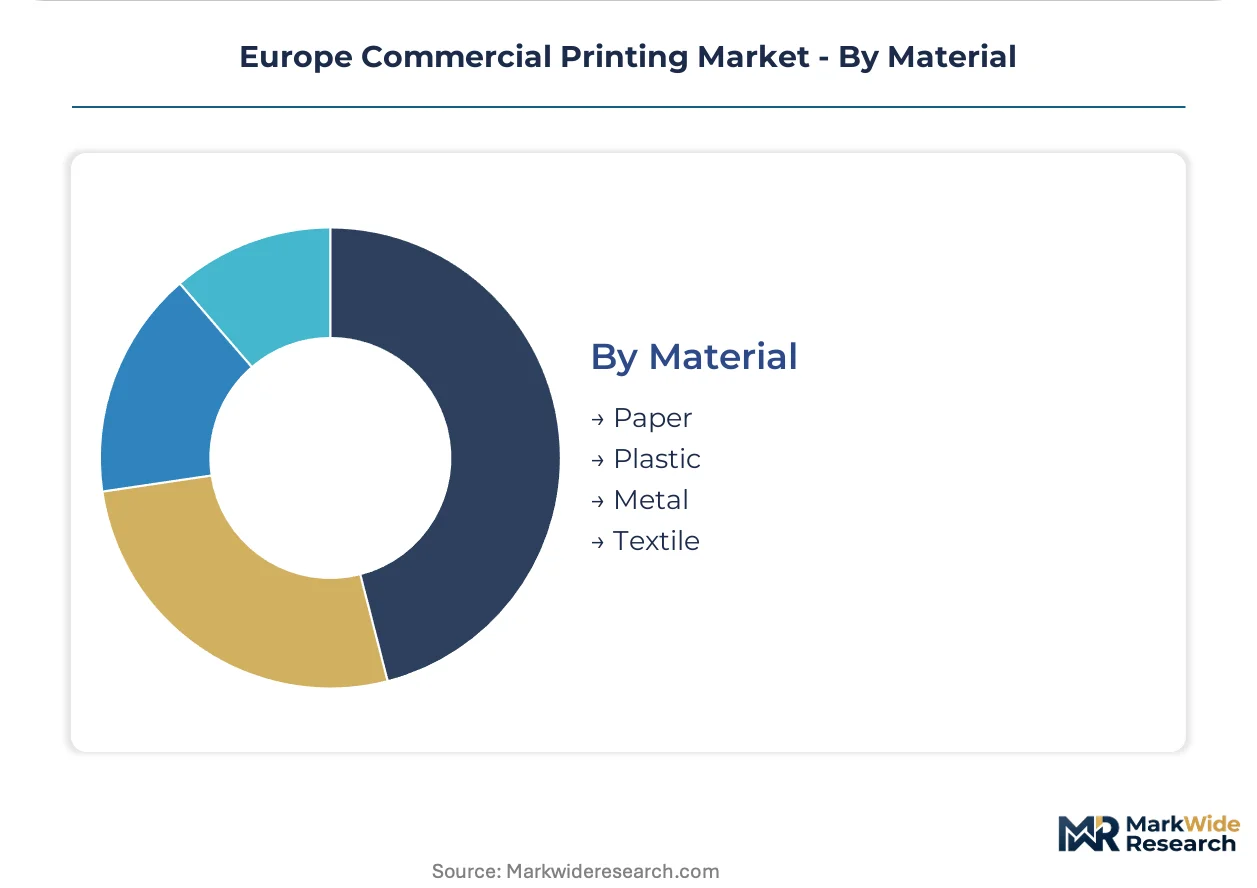
Material:
Supply concentration and circularity compliance reshape substrate sourcing across national boundaries.
- Paper:Coated and uncoated wood fiber substrates retain dominant share in publishing and folding cartons. Nordic mill energy cost volatility and EU packaging waste directive recycled thresholds alter procurement risk profiles for German and French converters.
- Plastic:PET, PP, and PE films serve flexible packaging and shrink sleeves with barrier properties for food and pharmaceutical applications. REACH substrate disclosure requirements extend pre-production validation cycles.
- Metal:Aluminum and steel substrates support aerosol cans, decorative tins, and industrial labels with embossing and metallic finishing capabilities.
- Textile:Natural and synthetic fabrics absorb direct-to-garment and industrial textile printing for fashion and technical applications.
Paper holds installed capacity. Plastic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in France's luxury goods corridor while German pharmaceutical converters absorb steeper REACH compliance costs. Nordic paper mills pass through energy volatility, compressing margins for mid-volume operators in Sweden and Finland.
Germany
Pharmaceutical serialization demand and folding carton investment dominate the commercial print landscape. ECHA's REACH mandates tighten substrate chemical disclosure timelines for export-bound packaging. Heidelberg anchors industrial clusters in Baden-Württemberg and the Rhine-Ruhr region, sustaining installed-base service networks.
France
Cosmetics and spirits labeling corridors drive premium tactile embellishment and metallic finishing capabilities. EU Green Deal packaging waste directives enforce recycled content thresholds through national transposition. The Île-de-France and Provence-Alpes-Côte d'Azur regions concentrate luxury brand procurement around integrated design-to-print studios.
United Kingdom
Direct-to-brand e-commerce packaging specifications from beauty and specialty food startups reshape corrugated converter relationships. The country's national environmental regulator enforces extended producer responsibility schemes for packaging waste. Greater London and the Midlands host design-integrated packaging networks capable of structural engineering and fulfillment under single-roof accountability.
Netherlands
Benelux SME marketing collateral demand fragments across web-to-print platforms competing on velocity and customization. The EU AI Act's emerging transparency requirements intersect with automated print quality inspection deployments. Randstad logistics infrastructure enables same-day turnaround services for pharmaceutical label emergencies.
Poland
Underinvestment in corrugated pre-print capacity creates acquisition targets for Western European integrators seeking Eastern European expansion. EU Green Deal directive transpositions lag Western member states, extending substrate verification protocol adoption timelines. The Warsaw and Łódź industrial zones concentrate mid-volume sheetfed capacity serving German and French export markets.
Europe Commercial Printing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ink chemistry and substrate engineering. The vendor base organizes around three strategic archetypes: multinational packaging networks with integrated design studios, equipment manufacturers monetizing installed-base service contracts, and web-to-print aggregators capturing fragmented SME demand. Consolidation pressures favor national print partners over distributed merchant networks. Competitive moves concentrate on M&A for geographic coverage and strategic partnerships for circular supply chain verification.
Among Germany-based equipment and service providers, Heidelberg and Koenig & Bauer occupy positions within the industrial machinery archetype, sustaining loyalty through technical service density. Smurfit Kappa, organized as a public limited company with Irish origins, exemplifies the integrated packaging network model through corrugated pre-print and structural design capabilities. Cimpress PLC represents the web-to-print aggregator archetype, competing on velocity for marketing collateral across territorially fragmented European demand.
| Leading Market Players |
|---|
| TC Transcontinental, Inc. |
| Koenig & Bauer |
| RR Donnelley & Sons Company |
| Smurfit Kappa |
| Cimpress PLC |
| Quad/Graphics, Inc. |
| Heidelberg |
| Mondi Group |
| Dai Nippon Printing Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Nordic paper mills compresses margin recovery for mid-volume sheetfed operators while simultaneously forcing substrate suppliers toward longer-term contract structures that lock in pricing floors.
Pricing Analysis
The customization-premium spread between configured-to-order pharmaceutical serialization jobs and standard catalog runs now exceeds three-to-one in German industrial clusters. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by FOGRA certification grade and after-sales service bundling. Price erosion runs through commodity magazine work as digital inkjet displaces offset at shorter run lengths. SME marketing collateral buyers in Benelux exhibit highest price sensitivity; luxury cosmetics brands in France show least.
Supply Chain Analysis
Upstream feedstock concentration in Swedish and Finnish pulp mills, combined with German chemical ink formulation capacity, anchors European substrate supply. Raw material dependencies center on wood fiber, petrochemical resins, and titanium dioxide pigments. Single-source vulnerability from Nordic energy cost volatility threatens margin stability for converters without backward integration into paper sourcing. Distribution runs through national merchant networks consolidating around fewer print partners with integrated logistics.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a service-attach opportunity as Heidelberg and Komori equipment manufacturers expand recurring-revenue service contracts faster than hardware replacement cycles.
For Market Incumbents: Harden installed-base loyalty through predictive maintenance contracts and remote diagnostics penetration in Baden-Württemberg industrial clusters. Offset craft skill retirement waves threaten production continuity; anchor retention through apprenticeship pipeline partnerships with German vocational institutes. Consolidate procurement relationships as direct-to-brand channels bypass traditional merchant networks.
For New Entrants and Emerging Players: Establish a beachhead in Polish corrugated pre-print capacity where Western European integrators seek acquisition targets. Romania and Bulgaria offer underinvested folding carton infrastructure serving German export markets. Lead with UV-LED curing convergence for pharmaceutical label emergency turnaround services.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital inkjet press deployments as single-pass widths match offset productivity. Long-term viability favors converters with verified circular supply chains under EU Green Deal mandates. Acquisition target archetype: mid-volume sheetfed operators with FOGRA certification and integrated design studios. Signal to watch: REACH compliance timeline extensions that compress pre-production validation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Substrate Sourcing | Secures EU Green Deal compliance thresholds for French and German packaging converters. |
| UV-LED Curing Technology Deployment | Enables same-day pharmaceutical label turnaround under EMA serialization deadlines. |
| Web-to-Print Platform Consolidation | Captures fragmented SME demand across Benelux and Iberia through velocity competition. |
| Cloud-Based Pre-Press Workflow Virtualization | Collapses geographic distance between Baltic production and Western European brand headquarters. |
| Corrugated Pre-Print Capacity Expansion | Targets acquisition opportunities in Poland and Romania for Western European integrators. |
Research Approach
The analysis maps lithographic, digital, flexographic, and screen printing sub-sectors, each validated through press operators, procurement managers at pharmaceutical and cosmetics brand owners, corrugated converter executives, and pre-press workflow specialists. Primary interviews combined with secondary validation from ECHA REACH filings, EU packaging waste directive transpositions, SEC filings of listed equipment manufacturers, and national trade association production statistics. Bottom-up capacity modeling and top-down demand estimation triangulate market sizing.
Assumption sets held regulatory timeline adherence and energy cost pass-through coefficients fixed while varying run-length migration rates and SME platform adoption curves across the projection horizon. Segmentation dimensions modeled include printing technology, end-use application, substrate material, and geographic member state cluster. CAGRs derived from installed base replacement cycles and incremental capacity absorption rates, incorporating pharmaceutical serialization mandate deadlines and luxury goods labeling corridor investment patterns as industry-specific inputs.
Stress conditions across pulp price volatility, natural gas supply disruption, and REACH compliance timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution elasticities and regulatory enforcement intensity. Cross-checking against national print production statistics from Eurostat and member state industry associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Web to Print Market
Printing Technology
Managed Print Services Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Professional Printers Market
Printing Technology
Global Microprinting Market
Printing Technology
Large Character Printers Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Computer-To-Plate and Computer-To-Press Systems Market
Printing Technology
RFID Printer Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Digital Production Printer Market
Printing Technology
Cloud Print Market
Printing Technology
Printing Machinery Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Global Cloud Printing Services Market