
 Card Printers Market | 2026-2036
Card Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Card Printers Market Outlook
Direct-to-government procurement channels are reconfiguring as agencies consolidate vendor lists and mandate domestic sourcing clauses. HID Global leverages its established security credentials to sustain long-term contracts with federal identification programs. Zebra Technologies anchors its position through manufacturing scale across multiple printer categories. Evolis competes by specializing in compact desktop units tailored for European public-sector specifications.
A card printer is an electromechanical device that applies pigment to PVC, composite, or polycarbonate substrates through thermal transfer or dye-sublimation processes, typically achieving resolutions of 300 dpi or higher for producing credit cards, employee badges, and government credentials. The technology dimension shows thermal transfer and dye-sublimation leading volume shipments due to superior image durability and color fidelity, while inkjet alternatives occupy niche applications requiring variable data at lower per-unit cost. The end-user dimension reveals government and corporate segments commanding the strongest margin pools because of compliance requirements and bulk replacement cycles.
The United States Federal Information Processing Standards and the European Union's General Data Protection Regulation shape product specifications by mandating encryption capabilities and audit trails for personal data handling. China's National Information Security Standardization Technical Committee imposes additional domestic certification requirements that influence design priorities for vendors seeking market access. Stakeholders must weigh certification costs against the revenue premium available in regulated procurement environments.
Market Dynamics
Government credential modernization programs are consolidating vendor relationships while imposing encryption and domestic-content mandates that reshape procurement economics across the card printer value chain.
Growth Catalysts
- Federal Information Processing Standards (FIPS):US federal agencies mandate tamper-evident credential features that require specialized printer hardware, sustaining replacement demand across national ID and access card programs.
- Dye-sublimation technology:Superior color fidelity and image durability against counterfeiting attempts drives adoption in passport and secure document applications where visual authentication remains critical.
- China's national ID infrastructure:The country's ongoing smart card rollout for citizen identification creates sustained volume demand for high-throughput issuance systems.
Market Restraints
- Polycarbonate substrate concentration:Three Asian chemical suppliers control specialty card-grade polymer supply, exposing printer manufacturers to input cost volatility and qualification delays.
- REACH substance restrictions:European chemical regulations limit certain pigment formulations used in thermal transfer ribbons, forcing reformulation investments without pricing recovery mechanisms.
- Mobile credential substitution:Smartphone-based digital ID wallets reduce physical card issuance volumes in corporate access control and transit payment verticals.
Strategic Opportunities
- India's Aadhaar-linked programs:The country's expanding state-level welfare card schemes create demand for decentralized issuance capacity beyond central government facilities.
- RFID-thermal convergence:Integrated encoding and personalization in single-pass operation reduces labor costs for contactless payment card issuers seeking operational efficiency.
- GDPR audit trail mandates:European data protection requirements favor printer vendors offering embedded encryption and transaction logging as differentiated procurement qualifiers.
Industry Challenges
- EMV certification timelines:Payment card personalization equipment requires lengthy compliance validation with payment network standards, delaying revenue recognition for new product introductions.
- Legacy mainframe integration:Government enrollment systems built on decades-old architectures demand costly middleware development to interface with modern printer management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Card Printers Market |
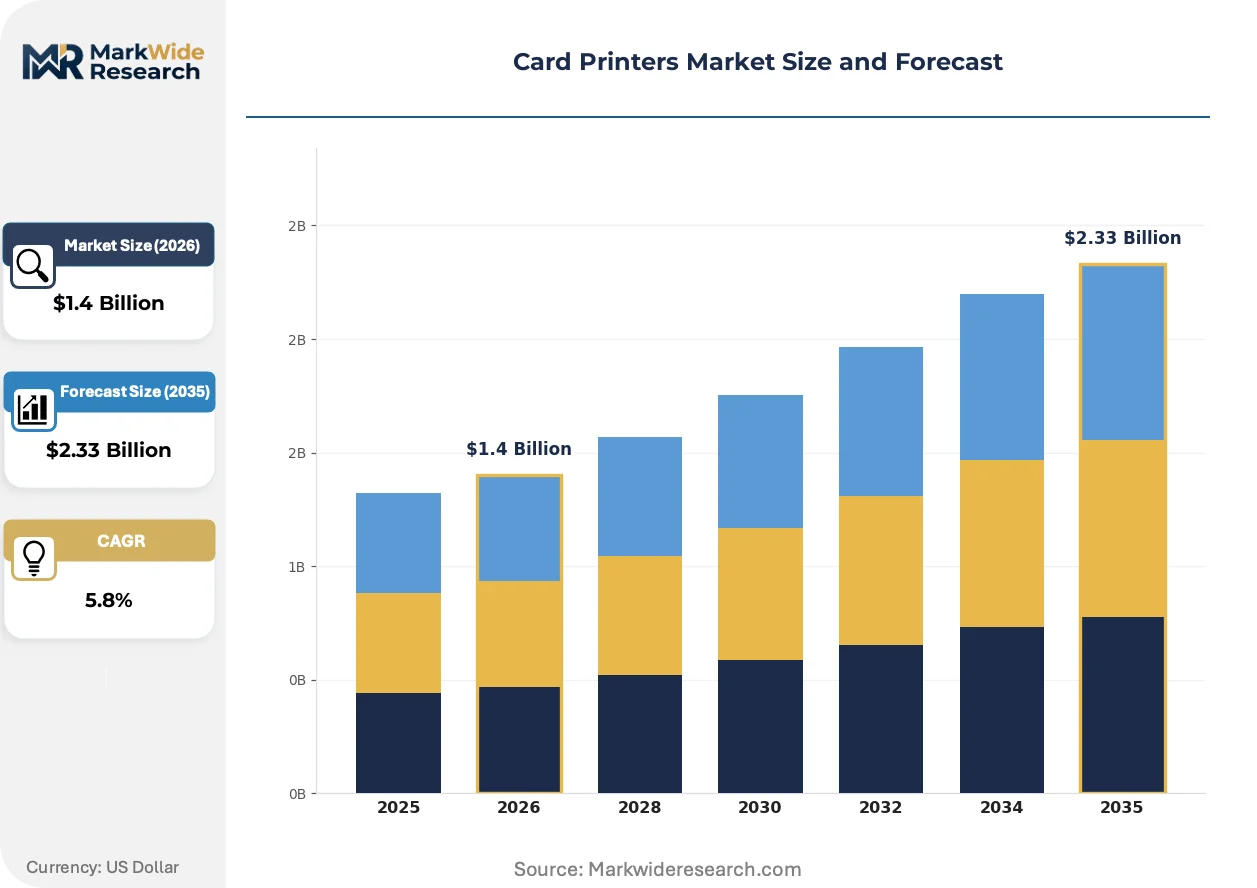
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Dual-Sided, Heavy-Duty, Portable End User: Retail, Government, Corporate, Education Technology: Thermal Transfer, Dye-Sublimation, Inkjet, Laser Connectivity: USB, Ethernet, Wi-Fi, Bluetooth |
| Companies Covered | HID Global, Zebra Technologies, Entrust, Evolis, Matica Technologies, Magicard, Datacard Group, NBS Technologies, Nisca Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Card Printers Market Strategic Shifts
Credential issuance workflows are converging with cloud-based identity management platforms, compressing the traditional separation between card production and digital identity lifecycle management.
Retransfer printing technology is digitizing card personalization by enabling edge-to-edge coverage on uneven surfaces including smart cards with embedded chips and antennas. Financial card issuers in Germany and South Korea are adopting these systems to eliminate the white border artifacts that signal lower-tier products. The technology is digitizing quality benchmarks across premium payment card segments previously tolerant of visual compromise.
China's National Information Security Standardization Technical Committee certification requirements now govern all card personalization equipment deployed in government programs, creating a parallel compliance track distinct from international ISO standards. Domestic vendors gain procurement preference through pre-qualification advantages. Foreign manufacturers are responding through joint venture structures and localized firmware development to maintain market access.
Centralized issuance models are fragmenting as banks and government agencies deploy distributed desktop units to branch offices and field stations. This pattern compresses the traditional concentration of high-volume production facilities while expanding the addressable base for compact printer categories. The shift is most pronounced in Brazil's regional bank networks and India's state-level administrative offices seeking same-day credential fulfillment.
Card Printers Market Segmentation
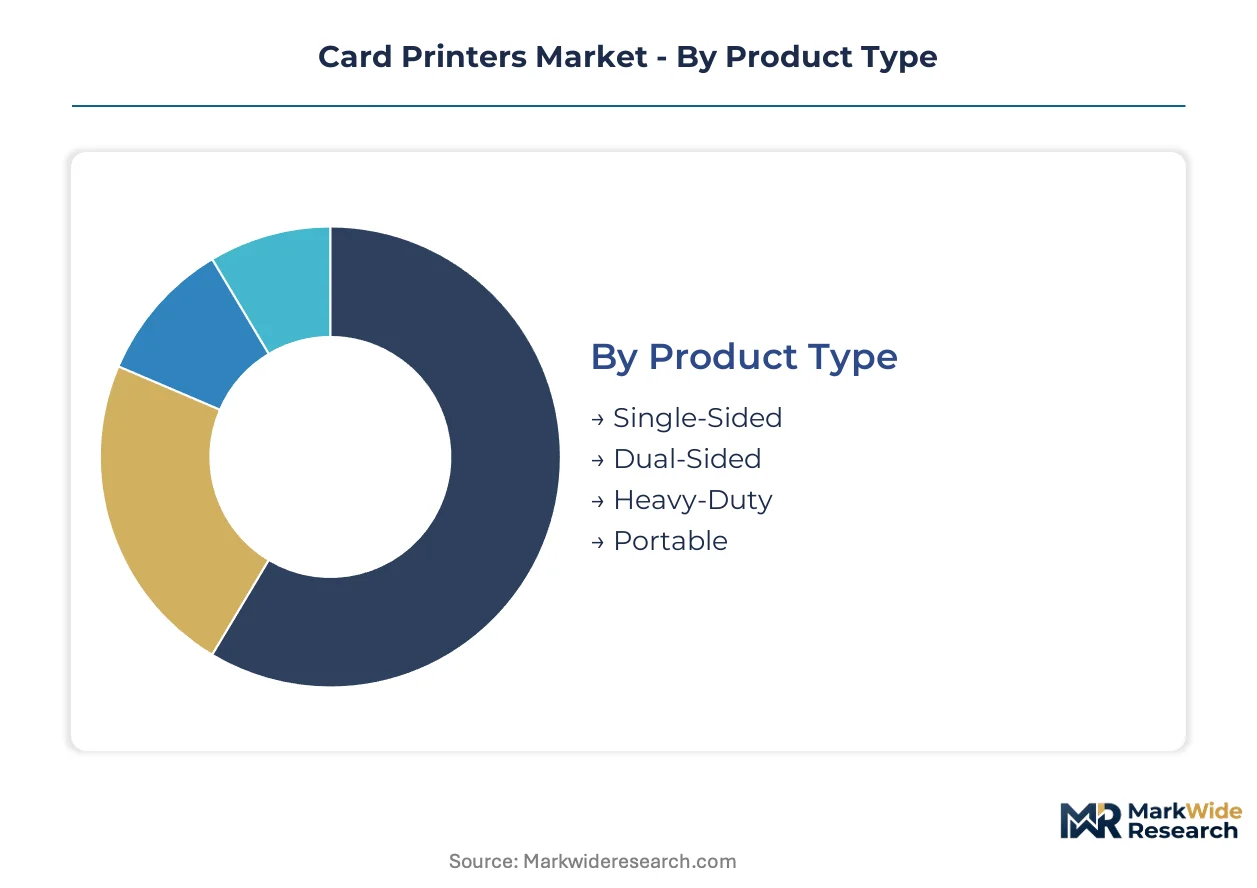
Card printer procurement varies sharply by operational intensity, security clearance levels, and network integration requirements. Vendors configure hardware specifications, firmware encryption, and service contracts around these segment boundaries rather than pursuing undifferentiated volume.
Product Type:
Operational tempo and card durability requirements create distinct hardware tiers across issuance environments.
- Single-Sided:Compact units apply pigment to one substrate face through thermal transfer or dye-sublimation processes, achieving 300 dpi resolution sufficient for basic employee badges and transit passes. Demand concentrates in India's state-level administrative offices and Brazil's regional bank networks where same-day credential fulfillment at branch level reduces central facility bottlenecks.
- Dual-Sided:Synchronized print engines personalize both card faces in a single pass, enabling machine-readable zones on reverse sides for passport and national ID applications. Germany's Federal Office for Information Security mandates this configuration for federal credential programs, sustaining premium pricing against single-sided alternatives.
- Heavy-Duty:Industrial chassis designs withstand continuous 24-hour operation for central issuance facilities processing millions of credentials annually.
- Portable:Battery-powered units with ruggedized casings serve field enrollment teams in remote or temporary deployment scenarios.
Established volume favors Dual-Sided; emerging adoption favors Portable.
End User:
Compliance architecture and procurement channel structure diverge sharply across institutional buyer categories.
- Government:Federal identification programs mandate FIPS-compliant encryption modules and tamper-evident hardware features that disqualify standard commercial units. China's National Information Security Standardization Technical Committee imposes additional domestic certification requirements, creating parallel compliance tracks distinct from international ISO standards.
- Corporate:Enterprise access control and payment card personalization drive demand for RFID encoding integration and cloud-based printer fleet management. GDPR audit trail mandates in Europe favor vendors offering embedded encryption and transaction logging as differentiated procurement qualifiers.
- Retail:Loyalty card and gift card issuance prioritizes cost efficiency over security hardening, accepting lower-duty cycle hardware.
- Education:Campus credential programs balance budget constraints against multi-function card requirements combining access, payment, and library services.
Margin concentration sits with Government; volume expansion is climbing the fastest with Corporate.
Technology:
Image durability requirements and counterfeiting risk thresholds determine process selection across application types.
- Dye-Sublimation:Solid dye diffusion into substrate surface layers produces continuous-tone images with superior color fidelity and resistance to physical alteration. Passport and secure document applications in the United States and South Korea specify this process where visual authentication remains critical.
- Thermal Transfer:Wax or resin ribbon deposition creates durable monochrome and spot-color images suitable for barcodes and text-heavy credentials. REACH substance restrictions in Europe limit certain pigment formulations, forcing reformulation investments without pricing recovery mechanisms.
- Inkjet:Piezoelectric droplet deposition enables variable data at lower per-unit cost for short-run applications.
- Laser:Toner fusion delivers high-speed output for non-secure applications where image permanence is secondary to throughput.
Security-sensitive applications favor Dye-Sublimation; cost-driven volume favors Thermal Transfer.
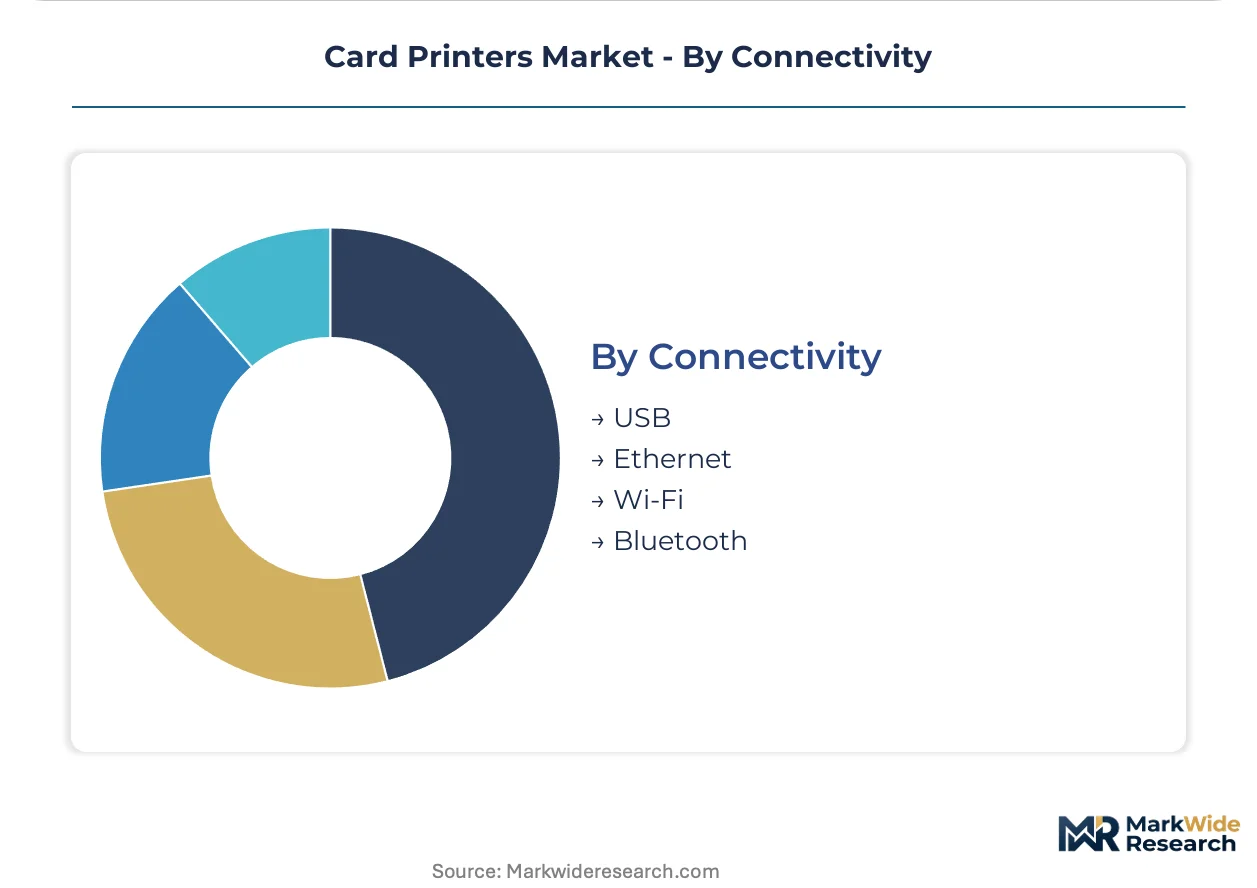
Connectivity:
Network architecture and data sovereignty requirements shape interface specifications across deployment contexts.
- Ethernet:Wired LAN integration supports centralized fleet management and audit logging for high-security environments where wireless transmission risks are unacceptable. Federal facilities in the United States mandate this configuration for classified credential production areas.
- USB:Direct host connection remains standard for desktop units in distributed issuance models where network segmentation limits peripheral access.
- Wi-Fi:Wireless infrastructure enables rapid redeployment without cabling infrastructure in temporary or mobile enrollment scenarios.
- Bluetooth:Short-range pairing supports tablet-driven field enrollment workflows with minimal hardware footprint.
Security compliance favors Ethernet; operational flexibility favors Wi-Fi.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FIPS standards from the United States anchor procurement specifications for high-security credential programs, while China's National Information Security Standardization Technical Committee and Germany's Federal Office for Information Security establish parallel compliance frameworks that reshape vendor access patterns across their respective markets.
United States
Federal credential modernization and payment card EMV migration sustain replacement cycles for specialized issuance hardware. FIPS 140-2 mandates tamper-evident modules that disqualify standard commercial units from federal procurement. Washington DC and Northern Virginia host concentrated defense and intelligence contractor facilities driving classified credential production demand.
Germany
Passport personalization infrastructure and corporate payment card issuance anchor demand for dual-sided retransfer systems. The Federal Office for Information Security mandates specific hardware configurations for federal credential programs. Frankfurt's financial services cluster and Munich's technology corridor sustain premium-tier procurement for high-durability card production.
China
National smart ID rollout and payment infrastructure expansion create sustained volume demand for centralized issuance systems. The National Information Security Standardization Technical Committee certification requirements govern all government-deployed personalization equipment. Shenzhen's electronics manufacturing base and Beijing's government procurement channels concentrate domestic vendor relationships.
India
State-level welfare card schemes and financial inclusion programs generate demand for decentralized desktop issuance capacity. The Bureau of Indian Standards shapes technical specifications for government credential equipment. Maharashtra's administrative modernization and Karnataka's banking technology corridor drive regional procurement concentration.
Brazil
Regional bank network expansion and national ID program deployment sustain demand for distributed personalization systems. ANVISA and central bank regulations influence payment card production specifications. São Paulo's financial services cluster and Rio de Janeiro's government administrative centers anchor equipment deployment patterns.
Card Printers Market Competitive Environment
Security-integrated specialists and manufacturing-scale generalists split the market along credential complexity and volume dimensions. The vendor base concentrates around three strategic tiers: established security contractors with federal certification relationships, diversified printing equipment manufacturers leveraging cross-category scale, and regional specialists optimizing for localized compliance requirements. Competitive positioning hinges on encryption module certification timelines and domestic-content qualification capabilities rather than unit cost differentiation.
Among the security-integrated tier, HID Global and Entrust exemplify archetypes anchored in federal identification program relationships. Zebra Technologies occupies a position reflecting manufacturing breadth across multiple printer categories. Evolis represents the regional specialist model tailored to European public-sector specifications.
| Leading Market Players |
|---|
| HID Global |
| Zebra Technologies |
| Entrust |
| Evolis |
| Matica Technologies |
| Magicard |
| Datacard Group |
| NBS Technologies |
| Nisca Corporation |
| Others |
Value Chain & Pricing Dynamics
Polycarbonate substrate concentration among three Asian chemical suppliers determines both the premium spread for card-grade polymer and the geographic shape of upstream sourcing. This single-source exposure compresses margins for printer manufacturers while forcing qualification investments that extend procurement timelines.
Pricing Analysis
The customization-premium spread separates FIPS-compliant federal configurations from standard commercial units by certification tier and encryption module grade. Three-tier pricing structure across premium, standard, and economy levels reflects durability ratings, throughput capacity, and after-sales service bundling. Cost compression in the retail loyalty card tier intensifies because commodity-grade hardware faces substitution from digital credential platforms. Government procurement exhibits lowest price sensitivity due to compliance mandates, while education and retail segments prioritize unit acquisition cost over lifecycle value.
Supply Chain Analysis
Supplier-financing facilities from Japanese and South Korean polymer producers extend payment terms for qualified printer manufacturers, easing working capital strain during certification cycles. Specialty card-grade polycarbonate draws from China, Japan, and South Korea, with thermal transfer ribbons and dye-sublimation films anchored in German and US chemical production. Single-source vulnerability concentrates in embedded chip supply from Taiwan semiconductor foundries. Distribution runs through direct government procurement channels, OEM-integrated systems, and authorized distributor networks serving decentralized corporate deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as credential issuance decentralizes from centralized facilities to branch-level desktop units, creating niche positions for specialized vendors.
For Market Incumbents: Harden federal certification relationships through accelerated FIPS module refresh cycles and localized firmware development for China's National Information Security Standardization Technical Committee requirements. Deepen backward integration into thermal transfer ribbon manufacturing to offset REACH-driven reformulation costs and secure pigment supply continuity. For New Entrants and Emerging Players: Pursue India's state-level welfare card schemes and Brazil's regional bank networks where same-day credential fulfillment demand outstrips incumbent service coverage. Target portable printer categories for field enrollment teams in remote geographies, leveraging battery-powered ruggedized designs with minimal infrastructure requirements. For Investors and Strategic Acquirers: China's National Information Security Standardization Technical Committee certification requirements reshape the acquisition landscape toward domestic joint venture structures and localized engineering capabilities. Long-term viability centers on vendors with established encryption module pipelines and government procurement channel access. Monitor EMV certification timeline compression as signal for payment card personalization equipment demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration | FIPS 140-2 and China NISSTC pre-qualification opens federal procurement channels. |
| Retransfer Technology Deployment | Edge-to-edge coverage eliminates white border artifacts for premium payment cards. |
| RFID-Thermal Convergence | Single-pass encoding reduces labor costs for contactless payment card issuers. |
| Cloud Fleet Management | GDPRe-compliant audit logging differentiates vendors in European corporate procurement. |
| Joint Venture Localization | Domestic firmware development maintains market access under China's certification regime. |
Study Parameters
The analysis maps single-sided, dual-sided, heavy-duty, and portable printer categories, each validated through procurement officers at government credential agencies, security technology directors at financial institutions, and channel managers at distribution partners. Primary interviews with OEM integration specialists, aftermarket service heads, and regulatory compliance consultants combined with secondary validation from FIPS certification databases, EMVCo compliance registries, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down procurement budget analysis across the analysis window.
Assumption sets held fixed the current regulatory certification timelines and polymer supply concentration while varying RFID adoption rates and mobile credential substitution intensity across the modeling period. Segmentation dimensions modeled include product type, end-user vertical, technology process, and connectivity interface, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from logistic diffusion curves fitted to credential modernization program deployment schedules and replacement cycle data.
Sensitivities concentrate around EMV certification timeline compression, polycarbonate supply disruption, and mobile credential substitution acceleration. Forecasts reflect assumptions about sustained government credential modernization funding and stable polymer input costs. Macroeconomic contraction affecting public procurement budgets, regulatory deviation expanding domestic content mandates, or technological breakthrough in digital identity verification would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Photo Printing Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Cloud Print Market
Printing Technology
Global Barcode Printer Market
Printing Technology
Large Format Printer Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Commercial Printer Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Digital Presses Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Europe Commercial Printing Market