
 UV Curing System Market | 2026-2036
UV Curing System Market Size, Share, and Industry Trends Forecast 2026-2036
UV Curing System Market Analysis
Market Context
Electronics assembly is recalibrating its curing protocols as miniaturized components require lower-heat processing solutions. Nordson Corporation leverages its precision dispensing and curing portfolio to anchor demand from semiconductor packaging lines. Phoseon Technology specializes in high-intensity LED curing architectures that compete directly with legacy mercury lamp installations. Dymax Corporation extends its position through adhesive-curing system integration that controls workflow design for medical device manufacturers.
Technical Definition and Segments
A UV curing system emits ultraviolet radiation in the 200–450 nm range to initiate photopolymerization of inks, coatings, and adhesives, converting liquid resins to solid films within seconds without thermal damage to substrates. LED-based technology segments are displacing conventional mercury lamp systems as energy efficiency standards tighten and instant-on capability reduces line idle time. The coatings application segment dominates current value pools, while adhesives curing in medical end-use represents the fastest-growing margin opportunity due to biocompatibility certification requirements.
Regulatory Frame
The EPA regulates mercury-containing lamp disposal under universal waste rules, while REACH restricts hazardous substance content in imported curing equipment sold across Europe. The EU F-Gas Regulation and RoHS directives are accelerating LED substitution by constraining mercury vapor lamp availability. Stakeholders must monitor evolving photobiological safety standards from IEC and national occupational exposure limits as UV LED intensities climb into previously unregulated spectral bands.
Market Dynamics
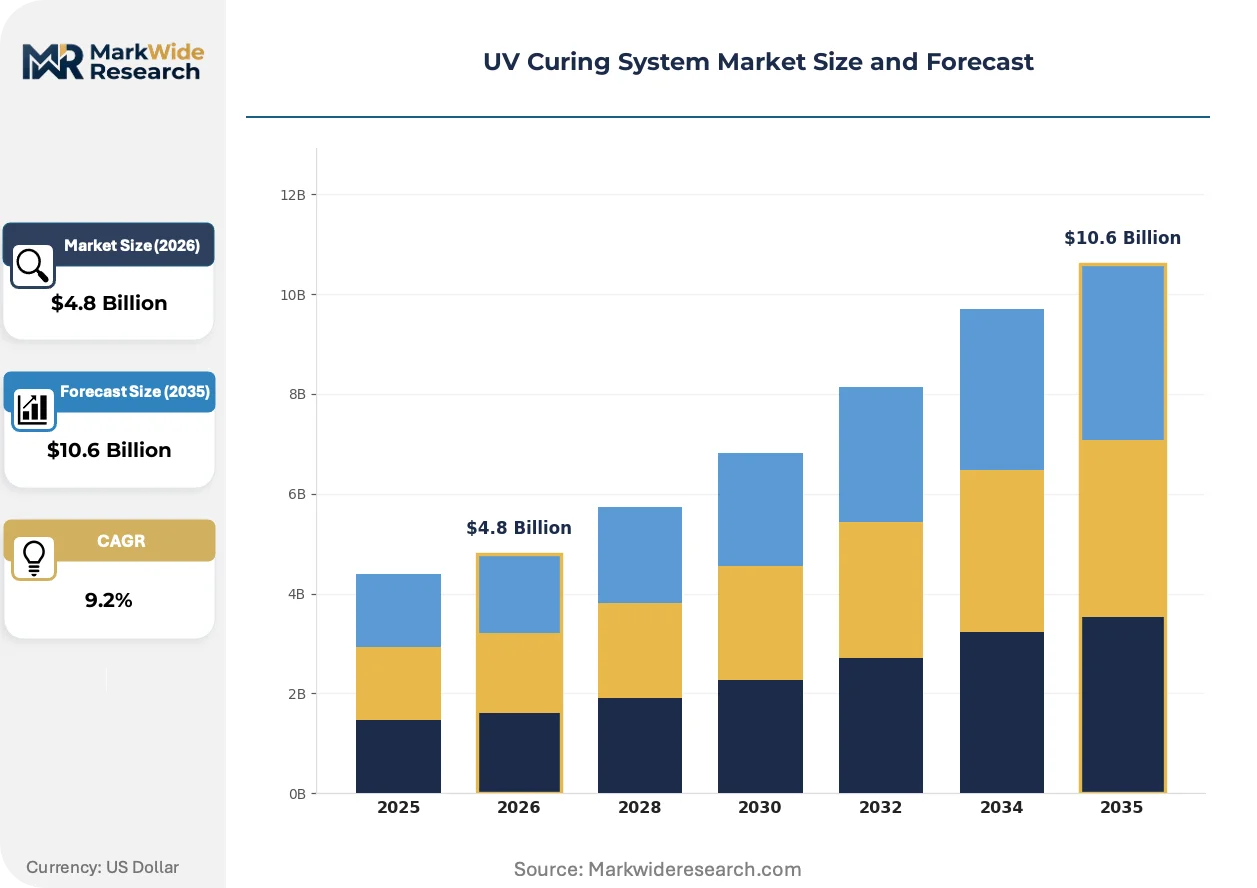
LED-based UV curing architectures are compressing equipment replacement cycles as mercury lamp phase-outs accelerate under multi-jurisdictional chemical restrictions. The transition is redistributing value from lamp consumables toward semiconductor-driven emitter modules.
Growth Catalysts
- RoHS and REACH mandates:European hazardous substance directives are eliminating mercury vapor lamp inventories from industrial supply chains. Automotive coating facilities in Germany are retrofitting production lines to maintain CE marking compliance.
- Electronics miniaturization:Semiconductor packaging lines require sub-100°C curing temperatures to protect sensitive die attach materials. UV LED systems deliver precise thermal control for flip-chip and wafer-level packaging processes.
- Instant-on capability:Solid-state emitter technology eliminates warm-up cycles that previously idified conveyor systems. Food packaging converters report throughput gains from reduced line startup delays.
Market Restraints
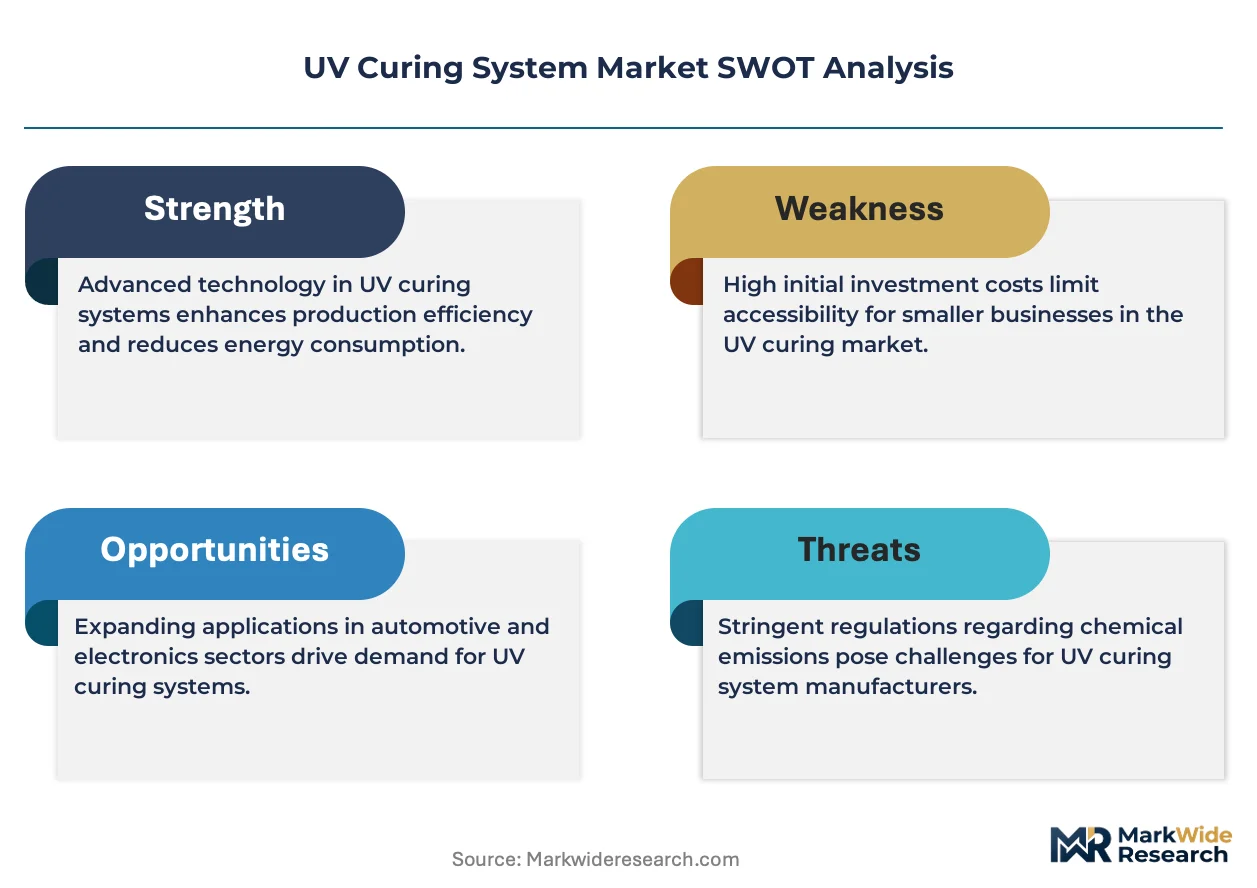
- Capital intensity:LED curing module retrofits demand 2-3x the upfront expenditure of mercury lamp replacements. Small-batch job shops in industrial coating sectors defer upgrades despite operational savings.
- UV-A emitter supply concentration:High-performance 365-405 nm LED chip fabrication concentrates among East Asian semiconductor foundries. Equipment OEMs face allocation risk during substrate supply disruptions.
- Photoinitiator formulation lock-in:Legacy coating chemistries optimized for mercury lamp spectral output require complete reformulation for LED peak wavelengths. Formulation houses pass R&D costs to end-users.
Strategic Opportunities
- Medical device sterilization:UV-C LED systems below 280 nm are penetrating low-temperature terminal sterilization for temperature-sensitive biologics. FDA 510(k) pathway clarity is accelerating hospital adoption.
- India manufacturing expansion:PLI scheme incentives for electronics and automotive component production are creating greenfield installation demand. Domestic coating capacity buildouts favor mercury-free equipment specifications.
- Hybrid curing architectures:Systems combining UV LED arrays with electron beam emitters are addressing thick-film coating applications previously outside UV penetration limits. Marine and wind turbine blade manufacturers are piloting dual-source installations.
Industry Challenges
- Photobiological safety compliance:Rising LED irradiance levels in the 315-400 nm range exceed legacy occupational exposure thresholds. Facilities must re-engineer enclosure interlocks and personal protective equipment protocols to satisfy evolving IEC 62471 interpretations.
- Legacy system integration:Retrofitting LED modules into existing conveyor architectures requires mechanical redesign of reflector geometries and cooling infrastructure. Systems integrators report 6-9 month deployment timelines for complex multi-zone installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Curing System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mercury Lamps, LED Lights, Microwave Lamps, Xenon Lamps Technology: UV LED, Conventional UV, Hybrid Systems, Ultraviolet Coatings End User: Manufacturing, Automotive, Electronics, Medical Application: Coatings, Adhesives, Inks, Print Finishing |
| Companies Covered | Dymax Corporation, American Ultraviolet, Nordson Corporation, GEW (EC) Limited, Heraeus Noblelight, Excelitas Technologies, Phoseon Technology, Miltec UV, IST METZ GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Curing System Market Emerging Trajectories
Spectral tunability and intelligent process control are converging to displace fixed-wavelength curing systems. Equipment architectures now emphasize real-time dose feedback rather than static power output.
Multi-wavelength LED arrays are unifying discrete curing steps that previously required separate mercury lamp stations. Automotive clearcoat lines in Stuttgart and Wolfsburg are consolidating primer, base, and topcoat curing into single-pass configurations. This compression is eliminating intermediate handling damage while reducing footprint requirements for new paint shop installations.
EPA universal waste rules for spent mercury lamps are tightening disposal documentation requirements across US manufacturing facilities. Industrial coating operations face elevated compliance costs and liability exposure from lamp breakage incidents. California and Michigan-based automotive suppliers are accelerating LED adoption to eliminate hazardous waste streams entirely from their environmental permits.
Service contract unbundling is separating equipment hardware from process optimization support. Medical device manufacturers increasingly procure curing systems through capital expenditure budgets while outsourcing photoinitiator selection and dose validation to application specialists. This bifurcation is visible among Minnesota and Massachusetts orthopedic implant producers seeking ISO 13485-certified process documentation without expanding in-house formulation expertise.
UV Curing System Market Segmentation
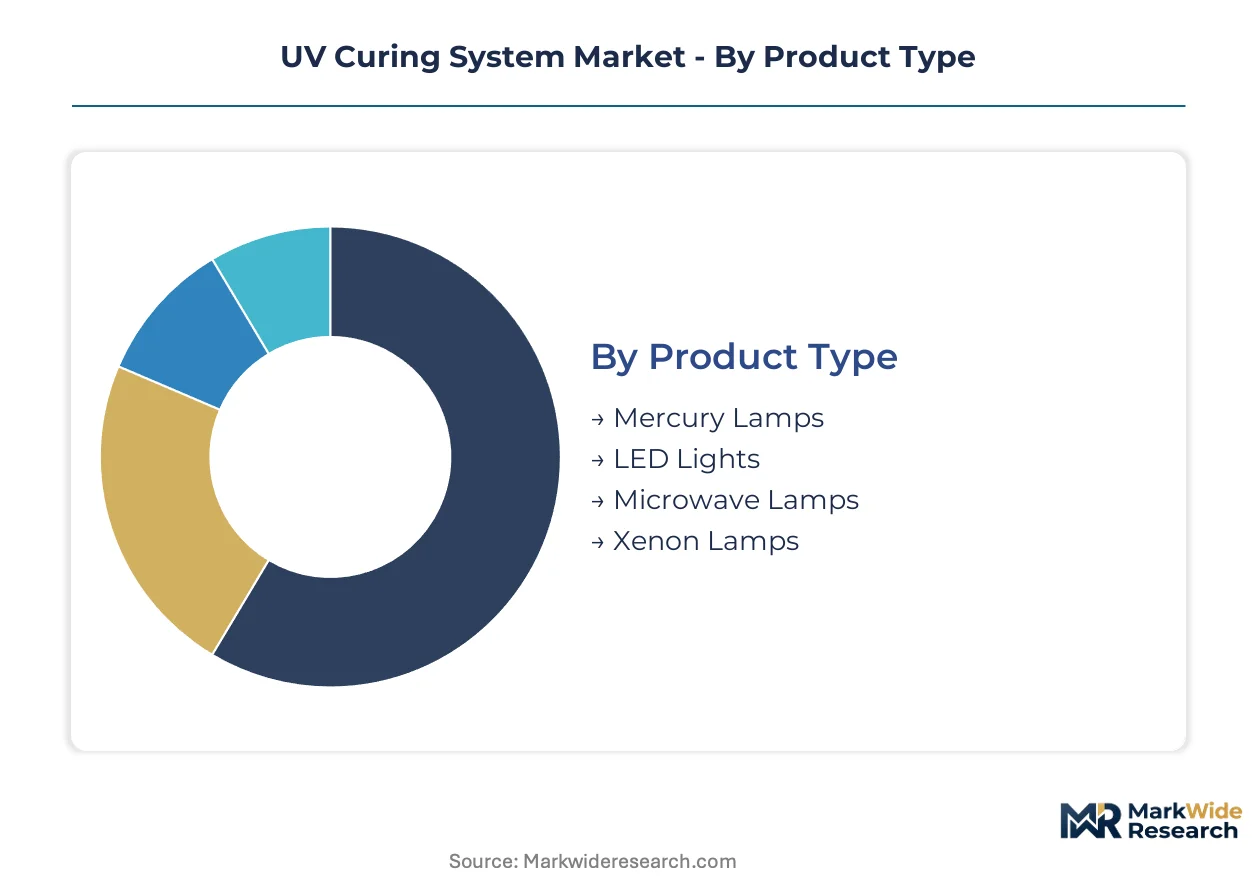
UV curing system segmentation reveals how technology transitions are fragmenting procurement patterns across end-use industries. Equipment buyers now select architectures based on spectral precision requirements, thermal constraints, and regulatory compliance obligations rather than legacy supplier relationships.
Product Type:
Supply concentration for emitter modules varies sharply across lamp chemistries, with semiconductor fabrication capacity determining availability for solid-state alternatives.
- Mercury Lamps:Arc-discharge mercury vapor technology delivers broadband UV output across 200-450 nm with established photoinitiator compatibility. Automotive coating lines in Germany and Michigan continue specified use where reformulation costs exceed retrofit capital, though REACH and EPA universal waste rules are compressing replacement timelines.
- LED Lights:Solid-state 365-405 nm emitters enable instant-on operation with 50-70% energy reduction versus mercury systems. Electronics packaging facilities in South Korea and Taiwan prioritize these for wafer-level die attach curing where thermal damage thresholds sit below 80°C.
- Microwave Lamps:Electrodeless mercury vapor architecture eliminates filament degradation for extended service intervals in continuous-duty industrial coating.
- Xenon Lamps:Pulsed broadband output serves specialized applications requiring high-peak irradiance for thick-film penetration in aerospace composite curing.
LED lights absorb the bulk of installed capacity in new electronics fabrication facilities; mercury lamps are expanding most quickly in emerging market manufacturing where capital constraints delay solid-state transitions.
Technology:
Cost tier stratification separates premium intelligent systems from standardized equipment, with process control sophistication driving margin capture.
- UV LED:Semiconductor emitter arrays with real-time dose feedback and spectral tunability command premium positioning. Medical device manufacturers in Massachusetts and Minnesota specify these for ISO 13485-compliant adhesive curing with full process traceability.
- Conventional UV:Mercury lamp and electrodeless microwave systems dominate legacy installed base with lowest capital entry point.
- Hybrid Systems:Dual-source architectures combining UV LED pre-cure with electron beam final cure address thick-film limitations. Marine coating applicators in Hamburg and Rotterdam pilot these for wind turbine blade protection exceeding 5 mm dry film thickness.
- Ultraviolet Coatings:Formulation-integrated curing chemistry where photoinitiator and resin systems are co-optimized with specific emitter spectra.
UV LED captures the premium tier of new equipment procurement; hybrid systems are climbing the fastest as thick-film applications migrate from thermal cure.
End User:
Application maturity diverges across customer types, with regulatory intensity and thermal sensitivity requirements determining technology selection.
- Manufacturing:Broad industrial coating and converting operations with standardized throughput requirements and moderate spectral precision needs.
- Automotive:Clearcoat and primer lines in Stuttgart, Wolfsburg, and Detroit require high-throughput, low-defect curing with robotic integration. Paint shop consolidation into single-pass configurations favors multi-wavelength LED arrays over legacy multi-station mercury setups.
- Electronics:Semiconductor packaging and printed circuit board assembly demand sub-100°C processing for miniaturized components. Flip-chip and wafer-level operations in Hsinchu and Suwon specify precision UV LED for die attach and underfill curing.
- Medical:Biocompatibility certification requirements and sterilization applications drive specification rigor. Orthopedic implant producers in Warsaw and Bologna procure systems with validated dose documentation for FDA 510(k) and MDR compliance pathways.
Electronics absorbs the bulk of precision UV LED demand; medical is expanding most quickly as UV-C LED sterilization penetrates temperature-sensitive biologics processing.
Application:
Volume concentration in coatings reflects automotive and industrial finishing scale, while margin opportunity concentrates in specialized adhesion and sterilization segments.
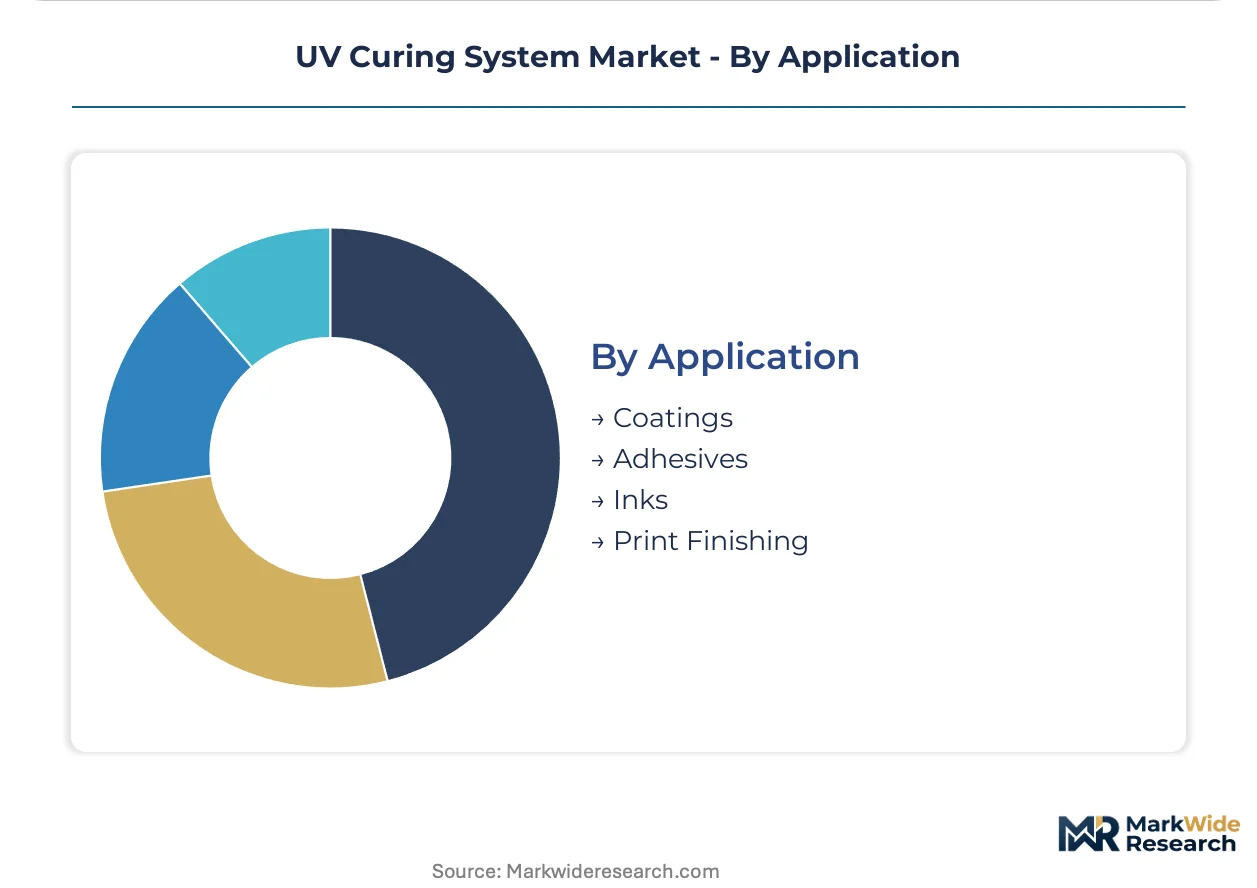
- Coatings:Protective and decorative film formation dominates current value pools with established formulation libraries. Automotive OEM clearcoat operations in Germany and Michigan represent the largest single demand concentration for high-throughput curing systems.
- Adhesives:Structural bonding and medical device assembly require precise cure depth control without thermal damage. Catheter and syringe manufacturers in Ireland and Switzerland specify LED-based systems for ISO 10993-compliant production.
- Inks:Narrow-web label and packaging printing with instant-dry requirements for food contact substrates.
- Print Finishing:Spot UV and dimensional coating effects for commercial and specialty publication enhancement.
Coatings retains the largest installed equipment base; adhesives is gaining share fastest as medical device manufacturing scales precision curing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in East Asia supply emitter modules worldwide, while consumption concentrates in automotive and electronics manufacturing corridors across Germany, the United States, and South Korea. Regional regulatory divergence is fragmenting procurement specifications as REACH, EPA universal waste rules, and RoHS create incompatible compliance baselines.
Germany
Automotive coating lines in Stuttgart and Wolfsburg drive premium LED system demand as CE marking requirements tighten under EU F-Gas Regulation. The KBA enforces hazardous substance documentation for paint shop retrofits. Bavarian and Baden-Württemberg industrial clusters are consolidating multi-station mercury setups into single-pass LED configurations.
United States
Electronics packaging facilities in Silicon Valley and Austin specify precision UV LED for wafer-level die attach curing below 80°C thermal thresholds. The EPA regulates spent mercury lamp disposal under universal waste rules with tightening documentation requirements. Michigan automotive suppliers are accelerating LED adoption to eliminate hazardous waste streams from environmental permits.
South Korea
Semiconductor foundries in Hsinchu and Suwon anchor demand for sub-100°C curing systems protecting flip-chip interconnects. The MFDS regulates medical device sterilization applications creating pathway clarity for UV-C LED hospital adoption. Seoul Capital Area packaging lines prioritize instant-on LED architectures to eliminate conveyor idle time.
China
Domestic coating capacity buildouts in the Yangtze River Delta and Pearl River Delta favor mercury-free equipment specifications under tightening environmental enforcement. The MEE restricts hazardous substance content in industrial equipment imports. Shenzhen and Dongguan electronics assembly lines are recalibrating curing protocols for miniaturized component protection.
India
PLI scheme incentives for electronics and automotive component production are creating greenfield installation demand across Maharashtra and Tamil Nadu. The BIS is developing mercury-free equipment standards aligned with RoHS frameworks. Chennai and Pune coating facilities are specifying LED-based curing modules for new paint shop installations.
UV Curing System Market Vendor Landscape
Top-tier vendors anchor premium intelligent systems with real-time dose feedback, while mid-tier fabricators compete on standardized equipment capital efficiency. The vendor base stratifies across three tiers: semiconductor-driven emitter specialists, integrated curing system architects, and regional coating equipment fabricators. Competitive positioning depends on spectral tunability capabilities and formulation-chemistry integration depth. Primary competitive moves include strategic partnerships with photoinitiator houses and geographic expansion through systems integrator networks.
Within the precision curing tier, Nordson Corporation and Phoseon Technology exemplify divergent strategic archetypes. Nordson leverages precision dispensing integration to anchor demand from semiconductor packaging lines. Phoseon occupies a position as a high-intensity LED architecture specialist competing directly with legacy mercury lamp installations. Dymax Corporation represents the adhesive-curing system integrator archetype controlling workflow design for medical device manufacturers.
| Leading Market Players |
|---|
| Dymax Corporation |
| American Ultraviolet |
| Nordson Corporation |
| GEW (EC) Limited |
| Heraeus Noblelight |
| Excelitas Technologies |
| Phoseon Technology |
| Miltec UV |
| IST METZ GmbH |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement offices in Stuttgart and Wolfsburg command contract-based long-term offtake agreements that compress margin capture for equipment vendors. REACH compliance documentation requirements and RoHS certification tiers stratify pricing across premium intelligent systems with real-time dose feedback versus standardized mercury lamp replacements.
Pricing Analysis
Margin tightening in the premium LED tier reflects semiconductor substrate allocation bottlenecks from East Asian foundries. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical systems from industrial coating equipment and emerging-market mercury lamp installations. Price differentiation rests on spectral tunability capabilities and formulation-chemistry integration depth. Small-batch job shops in industrial coating sectors exhibit highest price sensitivity, deferring LED retrofits despite operational savings, while medical device manufacturers in Massachusetts and Minnesota accept premium positioning for validated dose documentation.
Supply Chain Analysis
CE marking and FDA 510(k) pathway documentation create qualification gates that filter regional fabricators from premium tier participation. Emitter module fabrication concentrates in Taiwan, South Korea, and China, with high-performance 365-405 nm LED chip production anchored in Hsinchu and Suwon foundries. Raw material dependencies span gallium nitride substrates, sapphire wafers, and specialized photoinitiator formulations from European chemical houses. Single-source vulnerability in UV-A emitter supply exposes equipment OEMs to allocation risk during substrate disruptions. Distribution runs through systems integrator networks and direct OEM procurement channels serving automotive paint shops and semiconductor packaging lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UV curing system market functions as a cost-of-compliance story where EU F-Gas Regulation and REACH hazardous substance directives erect barrier-to-entry moats for mercury-free LED specialists. Regulatory documentation burdens favor incumbents with established certification pathways.
For Market Incumbents: Cement market position by acquiring photoinitiator formulation houses to lock in chemistry-emitter co-optimization capabilities. Expand service contract unbundling to capture recurring revenue from medical device manufacturers seeking ISO 13485-compliant process documentation without in-house expertise. Capacity addition in Bavaria and Baden-Württemberg addresses automotive retrofit demand while defending against emerging Asian LED architecture specialists.
For New Entrants and Emerging Players: Systems integrator partnerships offer the fastest channel to complex multi-zone installations where deployment timelines stretch 6-9 months. Target India's PLI scheme greenfield electronics and automotive facilities in Maharashtra and Tamil Nadu, where mercury-free specifications dominate new procurement. UV-C LED sterilization for temperature-sensitive biologics represents the most penetrable white-space, with FDA pathway clarity accelerating hospital adoption ahead of entrenched ethylene oxide sterilization.
For Investors and Strategic Acquirers: The window for entry favors semiconductor-driven emitter specialists with captive gallium nitride substrate access over pure-play systems integrators. Long-term viability hinges on spectral tunability IP and formulation-chemistry integration depth rather than hardware fabrication scale. Watch for inflection where hybrid UV LED-electron beam architectures penetrate thick-film marine and wind turbine applications previously outside UV penetration limits.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emitter Substrates | Gallium nitride wafer captive supply secures allocation priority from Hsinchu and Suwon foundries during substrate shortages. |
| Photoinitiator House Acquisition | Formulation-chemistry integration locks in spectral co-optimization for LED peak wavelengths against legacy mercury compatibility. |
| India Manufacturing Partnership | PLI scheme greenfield installations in Pune and Chennai favor mercury-free equipment specifications for new paint shops. |
| UV-C LED Sterilization Platform | FDA 510(k) pathway clarity accelerates hospital adoption for temperature-sensitive biologics terminal sterilization. |
| Hybrid System Architecture Development | Dual-source UV LED-electron beam configurations address thick-film coatings exceeding 5 mm dry film thickness for marine applications. |
Methodological Framework
Document review covered SEC filings from precision dispensing and curing equipment vendors, EPA universal waste rule enforcement records, and EU F-Gas Regulation implementation guidance, complemented by interviews with plant engineers at automotive coating facilities, semiconductor packaging line managers, medical device quality directors, and photoinitiator formulation specialists. Secondary validation drew from customs trade data for UV curing equipment imports, IEC photobiological safety standard drafts, and REACH restricted substance notifications. Bottom-up equipment shipment analysis and top-down end-use industry demand modeling enabled triangulation.
Cross-referencing historical mercury lamp phase-out trajectories against panel input from systems integrators shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-use industry, application, and regional regulatory cluster. CAGRs were derived from equipment procurement pipeline analysis and retrofit cycle compression rates. Industry-specific forecast inputs incorporated semiconductor fabrication capacity expansion schedules and automotive paint shop consolidation timelines.
Caveats apply where photoinitiator reformulation costs, substrate supply disruptions, or evolving IEC 62471 photobiological safety interpretations could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and LED emitter performance improvement curves. A model refresh is warranted upon material change in EU F-Gas Regulation implementation timelines or East Asian semiconductor export control policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Hardware in the Loop Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Mining Automation Systems Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
Global Automated Sortation System Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
GMC Based Motion Controller Market