
 North America Commercial Printing Market | 2026-2036
North America Commercial Printing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Printing Market Insights
Healthcare packaging demand is broadening as pharmaceutical serialization mandates expand. Quad/Graphics leverages in-house prepress capabilities to serve regulated industries. RR Donnelley & Sons anchors long-run publication contracts through Midwest production hubs. Cimpress competes in short-run digital segments with web-to-print infrastructure.
Commercial printing encompasses the reproduction of text and images on paper, board, plastic, and other substrates through mechanical or digital processes, typically at resolutions exceeding 300 dpi for professional applications. Lithographic printing remains the volume backbone for long-run magazines and catalogs, while digital printing captures personalized direct mail and on-demand packaging prototypes where variable data integration drives premium positioning. Prepress services retain margin concentration in color management and regulatory proofing for FDA-compliant pharmaceutical inserts.
EPA emissions standards under the Clean Air Act constrain solvent-based ink formulations across Ohio and Illinois print clusters. FDA 21 CFR Part 11 and DSCSA serialization rules elevate compliance costs for pharmaceutical label producers. OSHA lockout/tagout enforcement shapes pressroom automation investments. Stakeholders must weigh capital allocation between legacy offset capacity and inkjet systems as substrate versatility becomes the decisive procurement criterion.
Market Dynamics
EPA Clean Air Act enforcement is forcing solvent-based ink reformulation across the Great Lakes manufacturing corridor, compressing margins for legacy offset operators while accelerating capital migration toward UV-curable and water-based systems.
Growth Catalysts
- DSCSA Serialization Mandates:FDA track-and-trace rules for pharmaceutical packaging are expanding contract manufacturing demand for high-resolution variable data printing across Michigan and Ohio production hubs.
- On-Demand Packaging Prototypes:Digital inkjet systems are capturing personalized short-run work for consumer brands seeking rapid market testing without plate costs.
- Great Lakes Logistics Concentration:Proximity to Chicago distribution networks and Canadian paper mills reduces substrate inbound freight for Illinois-based commercial printers.
Market Restraints
- Petrochemical Feedstock Volatility:Crude-linked resin prices for UV inks and synthetic substrates create quarterly margin compression for mid-scale operators lacking long-term supply contracts.
- Skilled Press Operator Scarcity:OSHA lockout/tagout certification requirements and aging workforce demographics constrain 24/7 production scheduling across Ohio and Indiana facilities.
- Electronic Substitution:Digital document distribution and e-invoicing platforms are eroding transactional print volumes in financial services and healthcare administration.
Strategic Opportunities
- Pharmaceutical Compliance Services:FDA 21 CFR Part 11 validation documentation and color-proofing for regulated inserts offer margin-rich service bundling beyond commodity printing.
- Short-Run Web-to-Print Infrastructure:Cloud-based ordering portals paired with inkjet production are opening SME segments previously uneconomical for conventional offset.
- Canadian Cross-Border Expansion:Health Canada labeling harmonization with FDA standards enables qualified US printers to serve Toronto and Vancouver pharmaceutical packaging demand without redundant certification.
Industry Challenges
- Legacy Offset-to-Digital Transition Costs:Pressroom reconfiguration for hybrid workflows demands simultaneous capex for inkjet modules and staff retraining without guaranteed volume migration.
- Color Management Certification Bottlenecks:ISO 12647-2 compliance timelines for G7 Master qualification delay entry into brand-owner approved vendor lists for premium catalog work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Printing Market |
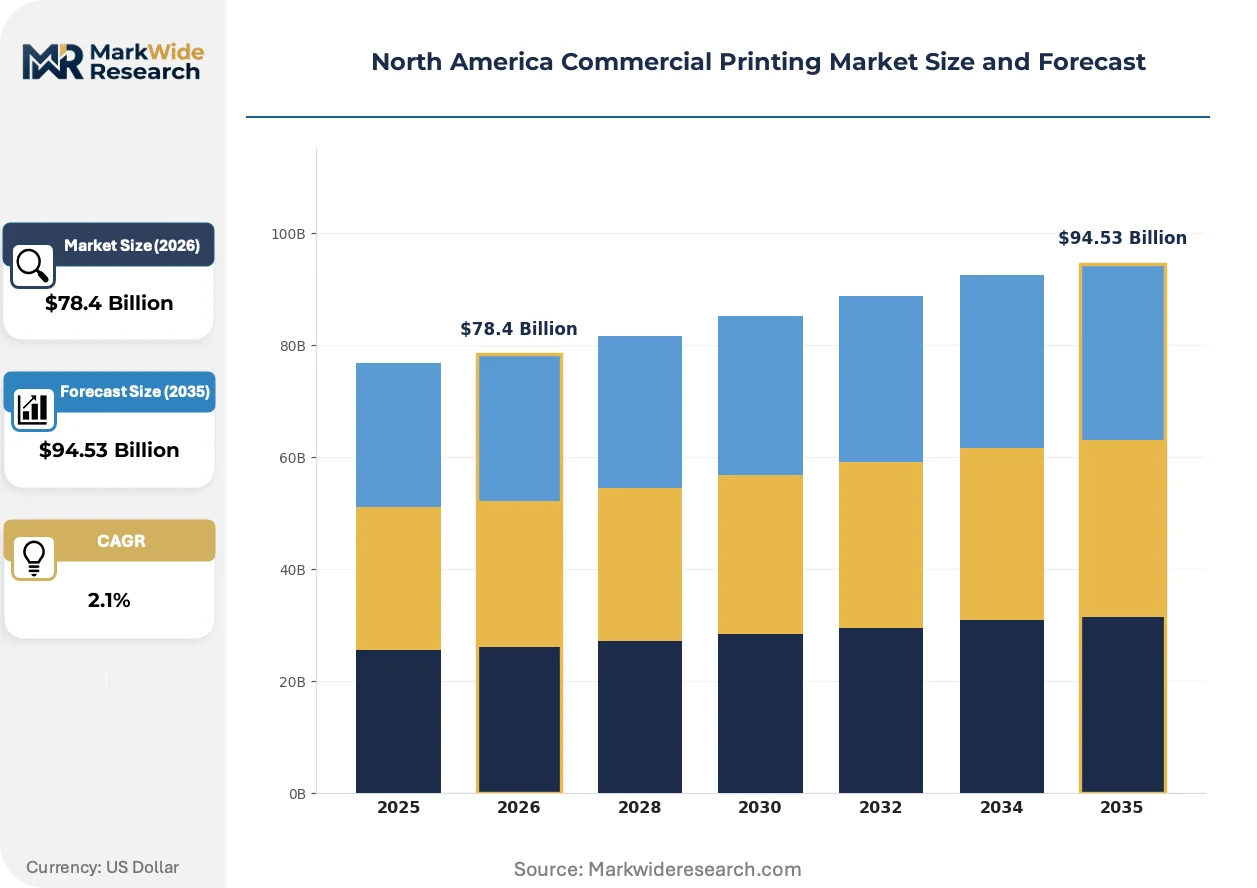
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $94.53 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Printing, Flexographic Printing, Lithographic Printing, Screen Printing Industry Vertical: Publishing, Packaging, Advertising, Commercial Graphics Service Type: Prepress Services, Printing Services, Postpress Services, Finishing Services Distribution Channel: Direct Sales, Online Sales, Retail, Distributors |
| Companies Covered | Quad/Graphics, RR Donnelley & Sons, Cimpress, Transcontinental Inc., Deluxe Corporation, Consolidated Graphics, LSC Communications, Dai Nippon Printing, Quebecor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Printing Market Trends and Innovations
Electrification of press mechanics and chemistry is reconfiguring the North American commercial printing landscape, compressing makeready times while elevating substrate versatility as the decisive procurement criterion for brand owners.
Single-pass inkjet web presses with aqueous pigment formulations are electrifying the economics of mid-run commercial work, enabling Ohio-based magazine printers to compete for 5,000-50,000 copy runs previously dominated by offset. Consumer packaged goods brands in Illinois are adopting these systems for versioning-intensive coupon inserts. The technology is electrifying competitive positioning by collapsing the traditional volume threshold where digital production becomes cost-competitive.
FDA 21 CFR Part 11 and EPA National Emission Standards for Hazardous Air Pollutants are tightening in parallel, elevating documentation burdens for pharmaceutical label producers across Michigan and Wisconsin. Printers serving regulated industries must now maintain electronic batch records and emissions compliance logs as auditable deliverables. Contract manufacturers are consolidating vendor lists to partners with validated quality management systems, privileging integrated prepress-to-fulfillment operations over single-service providers.
Brand procurement teams are unbundling print buying from agency retainers, establishing direct relationships with production facilities capable of real-time job tracking and inventory visibility. Retailers in the Chicago metropolitan area are piloting vendor-managed inventory programs where printers hold finished goods and release against weekly point-of-sale data. This pattern concentrates volume with facilities possessing warehouse management system integration and regional distribution reach.
North America Commercial Printing Market Segmentation
Equipment replacement cycles and regulatory compliance mandates are fragmenting procurement patterns across North American commercial printing. Printers now segment capital allocation by substrate versatility, serialization capability, and emissions profile rather than volume thresholds alone.
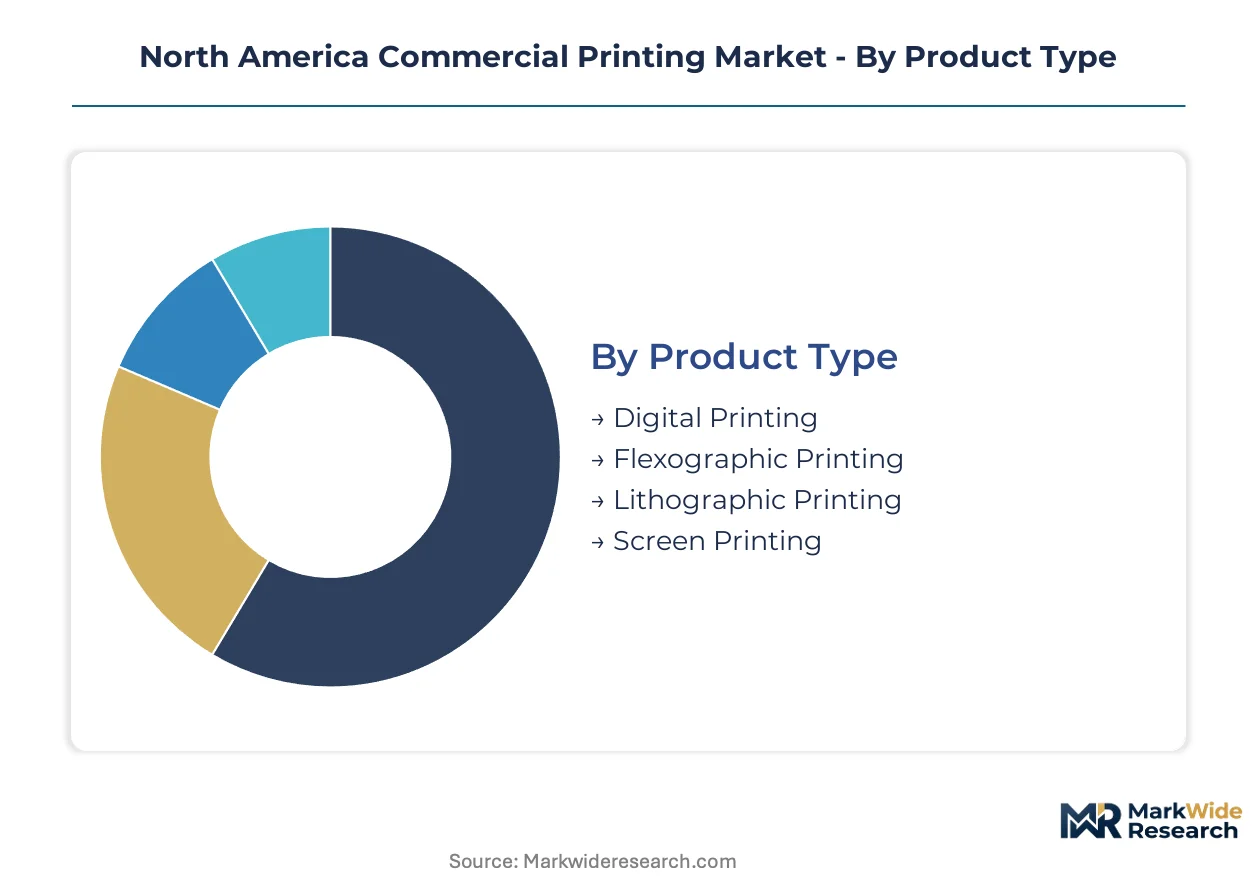
Product Type:
Upgrade cycles favor systems that reduce makeready waste while expanding substrate latitude beyond coated papers.
- Lithographic Printing:Offset lithography dominates long-run magazine and catalog production through web-fed configurations exceeding 15,000 impressions per hour. Demand concentrates in Illinois and Ohio publication hubs serving retail circulars and pharmaceutical inserts where FDA color consistency requirements reward proven G7 Master workflows.
- Digital Printing:Electrophotographic and inkjet systems capture variable-data pharmaceutical serialization, personalized direct mail, and short-run packaging prototypes. Michigan contract manufacturers are migrating sheet-fed toner devices to continuous-feed inkjet for DSCSA-compliant track-and-trace labels.
- Flexographic Printing:Central impression cylinder presses handle corrugated board and flexible film for consumer packaged goods. Ohio-based converters serving Walmart and Target private label programs dominate this segment.
- Screen Printing:Flatbed and rotary configurations apply thick-film UV inks to rigid plastics, glass, and specialty substrates. Demand localizes in Wisconsin and Minnesota for industrial signage and durable goods labeling.
Volume placements concentrate in Lithographic Printing; the faster expansion belongs to Digital Printing.
Industry Vertical:
End-use procurement patterns diverge sharply between regulated serialization requirements and commodity promotional materials.
- Packaging:Folding carton, corrugated, and flexible packaging demand is concentrating in pharmaceutical and food-grade applications where FDA 21 CFR Part 11 validation and child-resistant compliance specifications command premium pricing. Illinois converters with integrated prepress-to-fulfillment operations are capturing vendor-managed inventory contracts from Chicago-area retailers.
- Publishing:Magazine and book production faces secular decline in periodicals offset by Bible and educational text stability. Michigan web printers with in-house prepress retain long-run contracts through Midwest distribution proximity.
- Advertising:Point-of-purchase displays, outdoor signage, and direct mail sustain demand for wide-format and high-speed inkjet systems. Ohio and Indiana facilities serve automotive and retail brand campaigns with versioning-intensive short runs.
- Commercial Graphics:Corporate identity materials, annual reports, and marketing collateral represent discretionary spend vulnerable to electronic substitution. Canadian cross-border demand from Toronto financial services provides volume buffer for Detroit-area printers.
Revenue concentration sits with Packaging; Advertising is climbing the fastest as versioning requirements multiply.
Service Type:
Margin capture is migrating upstream into prepress validation and downstream into fulfillment integration.
- Prepress Services:Color management, imposition planning, and regulatory proofing for FDA-compliant pharmaceutical inserts retain premium pricing. Michigan and Wisconsin printers with ISO 12647-2 certification command preferred vendor status from brand owners.
- Printing Services:Core impression production faces commoditization pressure except where serialization or specialty substrates create technical barriers. Ohio offset houses compete on makeready speed and waste reduction rather than hourly rates.
- Postpress Services:Cutting, folding, and binding operations are consolidating into integrated facilities with automated finishing lines. Labor scarcity in Indiana and Illinois is accelerating investment in robotic material handling.
- Finishing Services:Specialty coatings, foil stamping, and die-cutting differentiate premium packaging and high-end catalogs. Chicago-area converters serve luxury goods and spirits brands with tactile embellishment capabilities.
Profit pool depth favors Prepress Services; Postpress Services is gaining share fastest through automation-driven consolidation.
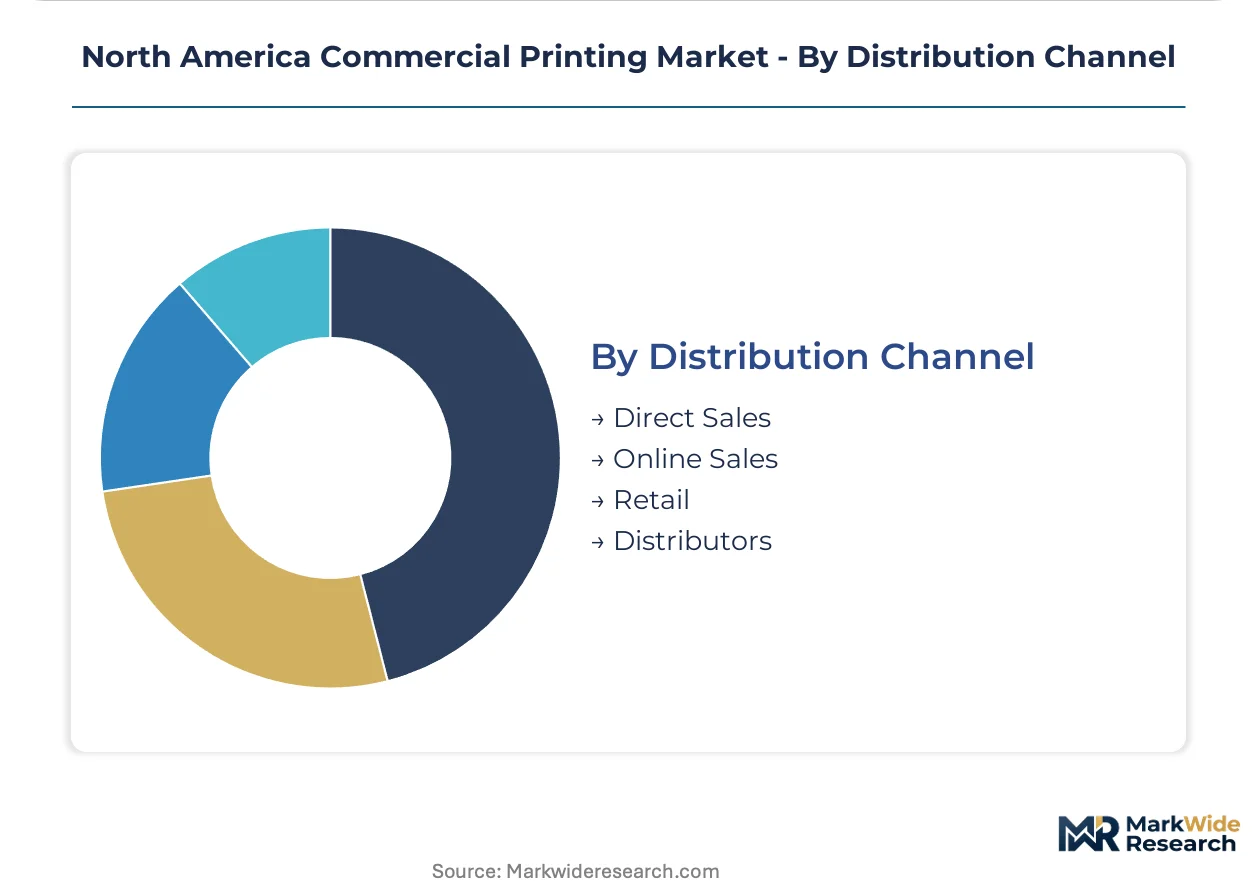
Distribution Channel:
Procurement disintermediation is compressing traditional distributor margins while rewarding direct technical engagement.
- Direct Sales:Field-based account management with embedded prepress consultation dominates pharmaceutical and Fortune 500 contracts. Quad/Graphics and RR Donnelley anchor long-term relationships through dedicated customer teams.
- Distributors:Independent rep networks serve mid-market printers lacking national coverage, though their role is narrowing to commodity substrates and consumables. Regional paper merchants in the Great Lakes corridor maintain inventory positions for JIT delivery.
- Online Sales:Web-to-print portals capture SME and individual orders for business cards, marketing materials, and photo products. Cimpress operates the most developed infrastructure, though regional competitors in Michigan and Ohio are replicating the model.
- Retail:Big-box store print centers and copy shops handle transactional document reproduction with limited substrate range. Staples and FedEx Office locations concentrate in metropolitan Chicago and Toronto corridors.
Transaction volume flows through Direct Sales; Online Sales is expanding most quickly through SME segment penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 22 in Illinois and Enterprise Zone incentives across Ohio concentrate commercial printing investment near Chicago distribution nodes and Detroit-area automotive supply chains.
United States
Pharmaceutical serialization mandates and DSCSA compliance deadlines drive variable-data printing demand across Michigan and Ohio contract manufacturers. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based ink formulations in the Great Lakes corridor. Chicago-area converters capture vendor-managed inventory contracts from retailers requiring real-time inventory visibility and regional distribution reach.
Canada
Health Canada labeling harmonization with FDA standards enables cross-border pharmaceutical packaging work for Toronto and Vancouver contract manufacturers. Quebec-based printers leverage proximity to US Midwest distribution networks for just-in-time delivery to Detroit and Cleveland markets. Ontario converters specialize in bilingual packaging compliance for consumer goods brands operating in both jurisdictions.
Mexico
Nearshoring trends in automotive and electronics manufacturing expand demand for industrial labels and technical documentation in Nuevo León and Baja California. Mexican environmental regulators enforce progressively tighter volatile organic compound limits on printing operations in border states. Tijuana and Monterrey facilities serve US OEMs seeking reduced freight costs for time-sensitive promotional materials.
North America Commercial Printing Market Competitive Landscape
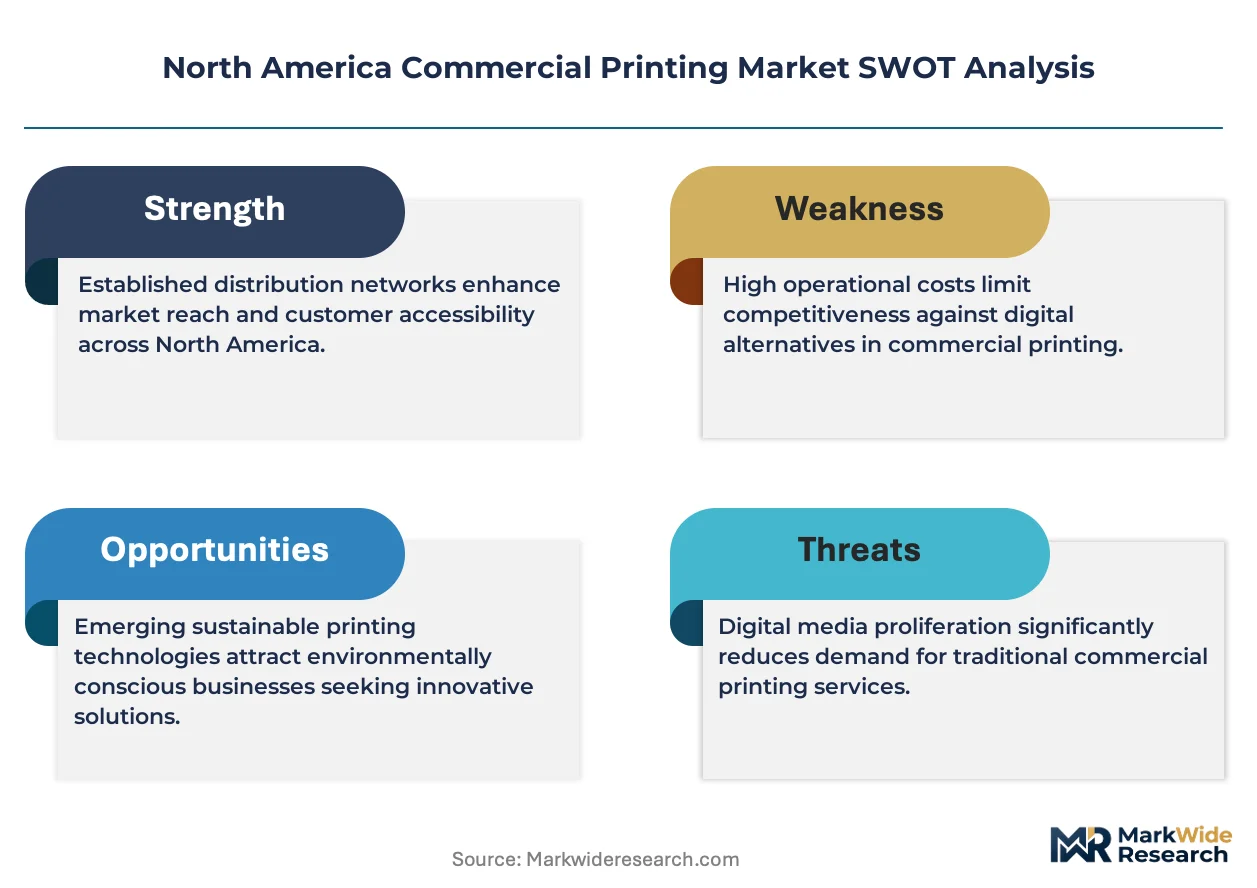
Branded specialists and contract manufacturers split share differently across segments, with integrated prepress-to-fulfillment operators commanding premium positioning in regulated verticals while commodity offset houses compete on waste reduction and makeready speed. Market structure tilts toward consolidation in pharmaceutical packaging and fragmentation in short-run digital segments. Three archetypes dominate: legacy web-offset houses with Midwest production hubs, web-to-print platforms with cloud-based ordering infrastructure, and specialty converters with FDA validation capabilities. Competitive dynamics center on strategic partnerships for serialization technology and portfolio diversification into compliance services.
Among North American integrated printers, Quad/Graphics and RR Donnelley & Sons occupy positions as scale-driven publication and commercial printing anchors with established Midwest production footprints. Cimpress represents the web-to-print platform archetype, exemplifying infrastructure-heavy digital competition for SME segments. These three companies illustrate the strategic divergence between legacy offset consolidation and digital-native market entry models.
| Leading Market Players |
|---|
| Quad/Graphics |
| RR Donnelley & Sons |
| Cimpress |
| Transcontinental Inc. |
| Deluxe Corporation |
| Consolidated Graphics |
| LSC Communications |
| Dai Nippon Printing |
| Quebecor Inc. |
| Others |
Pricing and Supply Chain Analysis
Single-pass inkjet electrification is compressing makeready economics while concentrating supply power with substrate-versatile converters across the Great Lakes corridor. UV-curable chemistry migration and aqueous pigment adoption simultaneously reshape unit cost structures and vendor selection criteria for pharmaceutical and retail buyers.
Pricing Analysis
Lead-time premiums dominate contract structures, with 24-hour turnaround commanding substantial markups over standard 5-7 day windows. Three-tier pricing separates validated FDA-compliant work from G7-certified commercial runs and commodity spot orders. Price differentiation hinges on ISO 12647-2 certification tier and serialization capability integration. Cost compression in mid-scale offset tiers is intensifying because legacy operators face simultaneous ink reformulation capex and volume migration to digital alternatives. SME buyers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize compliance assurance over rate negotiation.
Supply Chain Analysis
Domestic-content preferences embedded in Buy American provisions for federal procurement and Ontario's local manufacturing incentives are redirecting substrate sourcing toward certified North American mills. Geographic supply concentration centers on Canada for uncoated freesheet, Wisconsin for coated groundwood, and Ohio for recycled board grades. Raw material dependencies encompass titanium dioxide pigments, UV photoinitiators, and petrochemical-derived synthetic substrates. Single-source vulnerability persists in specialty ink additive formulations controlled by German and Japanese chemical suppliers. Distribution runs through regional paper merchants maintaining JIT inventory positions for Chicago and Detroit production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous-feed inkjet adoption represents the decisive technology transition, displacing web-offset dominance in mid-run commercial work while reconfiguring capital allocation priorities across the value chain.
For Market Incumbents: Anticipate accelerated volume erosion in 10,000-50,000 copy magazine segments by prioritizing hybrid pressroom configurations that preserve long-run offset efficiency while capturing inkjet versioning demand. Defensive consolidation through captive prepress capability acquisition protects margin pools in FDA-regulated verticals against pure-play digital entrants. Certification investment in ISO 12647-2 and G7 Master qualification maintains preferred vendor status with brand procurement teams unbundling agency relationships. For New Entrants and Emerging Players: SME pharmaceutical contract manufacturers in secondary Midwest markets represent the most penetrable buyer archetype, underserved by legacy web-offset houses and lacking technical bandwidth for self-service web-to-print platforms. White-space concentration appears in DSCSA serialization compliance services bundled with variable-data label production. Cloud-based ordering infrastructure paired with regional fulfillment partnerships offers the optimal go-to-market angle against Cimpress-scale investments. For Investors and Strategic Acquirers: Re-rating potential sits with integrated prepress-to-fulfillment operators given FDA 21 CFR Part 11 validation documentation requirements elevating switching costs in pharmaceutical packaging. Long-term viability over the next decade favors facilities with validated quality management systems and cross-border Health Canada certification. The signal to watch is vendor-managed inventory contract concentration with Chicago-area retailers as an inflection indicator for regional distribution scale premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Pressroom Configuration | Simultaneous offset and inkjet capacity captures volume migration without stranding legacy assets. |
| FDA Validation Documentation Investment | Electronic batch record capability secures preferred vendor status with contract manufacturers consolidating supply bases. |
| Canadian Cross-Border Certification | Health Canada labeling harmonization opens Toronto and Vancouver pharmaceutical demand without redundant compliance spend. |
| Vendor-Managed Inventory Integration | Warehouse management system connectivity captures retailer contracts requiring real-time inventory visibility. |
| UV-Curable Ink Formulation Partnership | EPA-compliant chemistry sourcing reduces emissions exposure while maintaining substrate versatility for premium packaging. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America Commercial Printing Market analysis. Primary interviews with pressroom operations directors, pharmaceutical packaging procurement managers, and prepress service heads combined with PRINTING United Alliance shipment statistics, EPA emissions compliance databases, and FDA 21 CFR Part 11 guidance documents. Bottom-up equipment installation tracking and top-down industry revenue estimates underwent triangulation validation.
Data-stream reconciliation across equipment vendor shipment reports, substrate consumption metrics, and end-use demand surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed printing technology type, substrate versatility tier, regulatory compliance level, and end-use vertical concentration. CAGRs derived from installed base evolution curves and replacement cycle timing, with specific weighting for DSCSA mandate deadlines and EPA enforcement phase-ins.
Revisions become necessary when EPA rulemaking accelerates solvent-based ink phase-outs, Health Canada diverges from FDA labeling standards, or single-pass inkjet economics shift the volume threshold for offset competitiveness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Global Wireless Printers Market
Printing Technology
Large Character Printers Market
Printing Technology
Managed Print Services Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Web to Print Market
Printing Technology
Global Microprinting Market
Printing Technology
Digital Production Printer Market
Printing Technology
Print on Demand Software Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Digital Printing on Wood Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Professional Printers Market