
 Global RFID and Barcode Printer Market | 2026-2036
Global RFID and Barcode Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Global RFID and Barcode Printer Market Foresight
Cloud-native printer management and edge-computing integration is reshaping how enterprises deploy distributed fleets of encoding equipment. Zebra Technologies leverages its software stack to sustain recurring revenue beyond hardware sales. SATO Holdings anchors its competitive position through deep specialization in precision thermal transfer systems for pharmaceutical serialization. Honeywell International dominates ruggedized industrial deployments where environmental tolerance determines procurement outcomes.
RFID and barcode printers are electromechanical devices that apply encoded data to substrates using thermal, impact, or laser processes, typically achieving print resolutions of 203 to 600 dots per inch for machine-readable compliance. Thermal transfer printers occupy the premium tier where label longevity and chemical resistance justify higher equipment and consumable costs. Direct thermal printers compete aggressively in short-lifecycle applications such as shipping labels and retail receipts where imaging permanence matters less. UHF RFID encoding modules represent the fastest-growing technology segment as apparel and automotive suppliers mandate item-level tagging for inbound logistics visibility.
FDA serialization requirements for pharmaceutical distribution and EU MDR traceability mandates for medical devices are forcing manufacturers to validate printer accuracy at the unit-of-use level. REACH restrictions on adhesive chemistries and RoHS limits on electronic components shape material selection and supplier qualification across European supply chains. Stakeholders must monitor how EPA industrial emissions guidelines and evolving ESG disclosure frameworks under CSRD alter capital allocation toward energy-efficient, recyclable labeling infrastructure.
Market Dynamics
Cloud-native printer management platforms are compressing replacement cycles as enterprises prioritize fleet-wide visibility over point-solution durability, forcing hardware vendors to restructure revenue models around recurring software subscriptions.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers in Germany and Ireland must validate unit-level label accuracy, driving precision thermal transfer printer upgrades across sterilization-resistant workflows.
- Automotive inbound logistics:Tier-1 suppliers in Michigan and Stuttgart now mandate UHF RFID encoding at item-level for just-in-sequence assembly visibility, expanding encoder module attachments.
- Battery passport requirements:The EU Green Deal's emerging cell-level tracking standards are accelerating demand for durable, chemically resistant labeling substrates in Polish and Hungarian gigafactory corridors.
Market Restraints
- Silicon supply concentration:Encoder chip fabrication concentrates in Taiwan and South Korea, exposing printer OEMs to geopolitical supply interruptions and extended lead times for RFID modules.
- REACH adhesive restrictions:ECHA limitations on solvent-based chemistries force European label converters to qualify alternative bonding agents, slowing new substrate certification timelines.
- Direct thermal substitution:Short-lifecycle shipping applications in Chinese e-commerce fulfillment increasingly favor chemical-imaging printers over thermal transfer, compressing premium equipment addressable markets.
Strategic Opportunities
- Indian pharmaceutical serialization:CDSCO's expanding track-and-trace requirements for domestic drug distribution create first-mover positioning for validated thermal transfer systems in Mumbai and Hyderabad manufacturing clusters.
- Edge-computing convergence:Integration of encoding hardware with local AI inference engines enables real-time print quality validation, opening premium pricing for fault-prevention capabilities in aerospace component marking.
- Recurring revenue platforms:Managed print services for distributed retail fleets transform capital equipment sales into subscription relationships, improving customer lifetime value across North American big-box chains.
Industry Challenges
- Validation engineering scarcity:FDA 21 CFR Part 11 compliance for pharmaceutical printer qualification requires specialized documentation expertise that concentrates among a limited pool of contract validation firms.
- Legacy ERP integration:Brownfield manufacturing sites in Japan and Germany face prolonged deployment timelines connecting modern encoding equipment to decades-old production planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RFID and Barcode Printer Market |
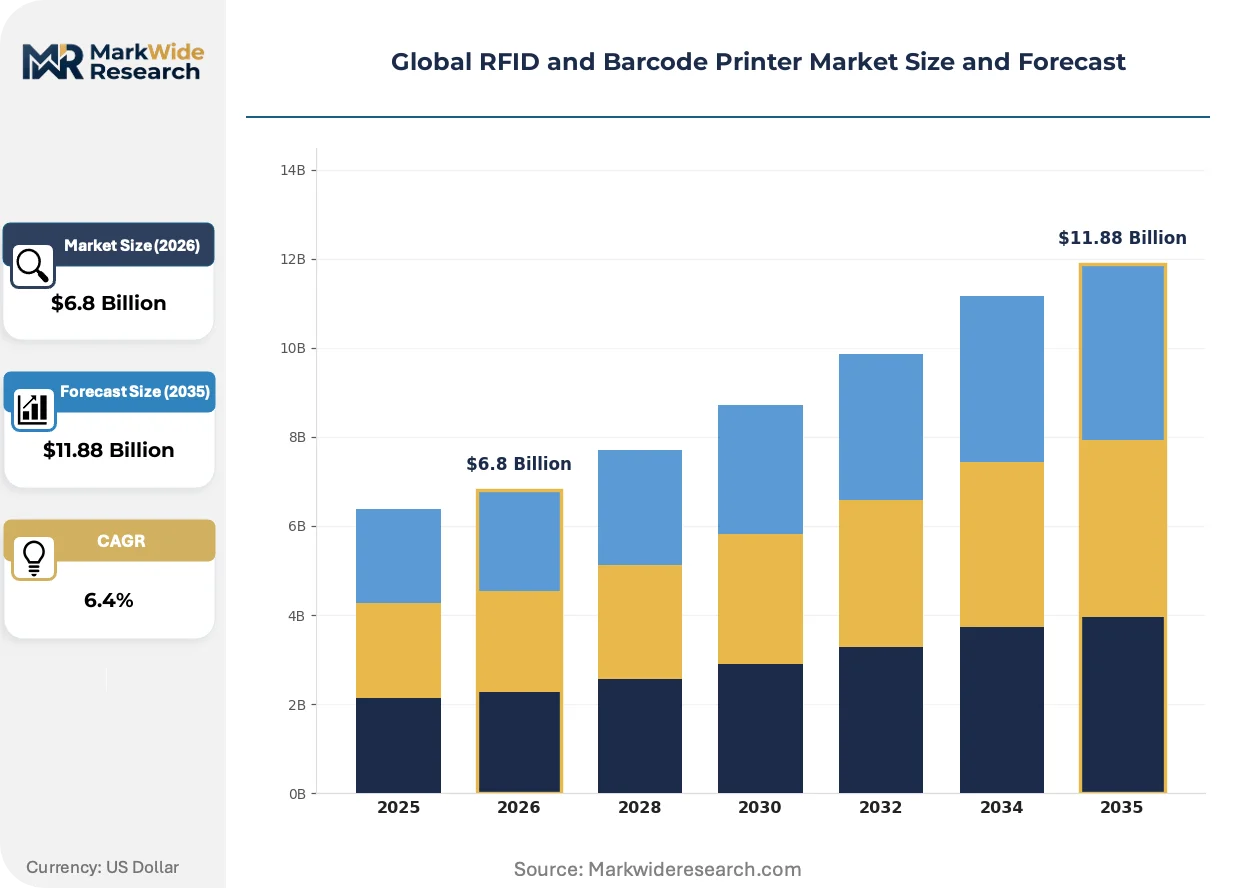
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Thermal Printers, Thermal Transfer Printers, Impact Printers, Inkjet Printers, Laser Printers Technology: UHF RFID, HF RFID, NFC, 1D Barcode, 2D Barcode, Smart Card Printers Application: Inventory Management, Asset Tracking, Ticketing Solutions, Document Management, Retail Checkout, Library Management End User: Manufacturing Units, Warehousing Facilities, Logistics Companies, Retail Chains, Educational Institutions, Transportation Providers |
| Companies Covered | Zebra Technologies Corporation, SATO Holdings Corporation, Honeywell International Inc., Toshiba Tec Corporation, Printronix Auto ID, Avery Dennison Corporation, Seiko Epson Corporation, BIXOLON, Dascom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RFID and Barcode Printer Market Shifts & Advancements
Intelligent encoding hardware is converging with predictive maintenance algorithms and sustainability tracking, compressing the traditional boundary between print execution and supply chain orchestration software.
Thermal transfer ribbon formulations are migrating from petroleum-based wax-resin blends to bio-derived polymer substrates. Automotive suppliers in Bavaria and pharmaceutical packagers in New Jersey are piloting these chemistries to preempt ESG disclosure penalties. The technology is migrating from niche sustainability pilots to standard procurement specifications for multinational manufacturers with Science Based Targets commitments.
CSRD disclosure frameworks are mandating granular carbon accounting for labeling infrastructure across European value chains. Industrial facilities in the Netherlands and Denmark must now document embodied emissions from printer manufacturing and consumable production. Packaging engineers are responding by specifying refurbished equipment programs and closed-loop ribbon take-back schemes in tender requirements.
Consolidated vendor relationships are displacing fragmented multi-brand printer fleets. Procurement teams at North American retail headquarters now demand single-source accountability for hardware, software, and consumable performance. This concentration is most visible in grocery and apparel chains operating synchronized inventory systems across thousands of store locations.
Global RFID and Barcode Printer Market Segmentation
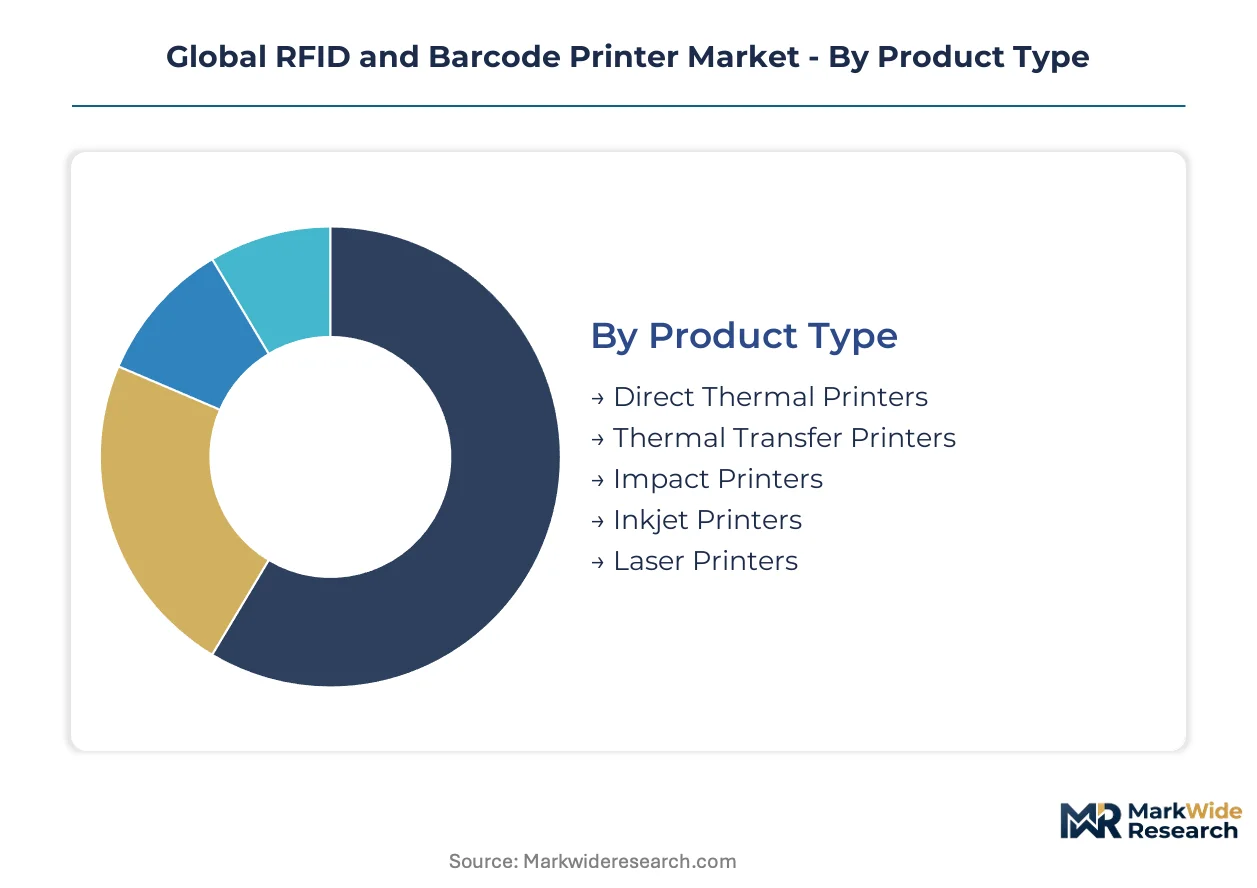
RFID and barcode printer segmentation reveals how hardware specifications, encoding protocols, and operational environments shape procurement decisions across supply chains. Technology choices directly determine compliance eligibility for regulated industries and durability requirements for industrial deployments.
Product Type:
Mature thermal technologies dominate installed bases while emerging inkjet and laser alternatives carve niches in specialized imaging applications.
- Thermal Transfer Printers:These systems apply heat to transfer ink from wax-resin or resin ribbons onto synthetic substrates, producing chemically resistant labels that withstand sterilization cycles and outdoor exposure. Pharmaceutical packagers in Germany and automotive suppliers in Michigan specify these units for unit-level serialization mandates where label longevity determines regulatory compliance.
- Direct Thermal Printers:Chemical-imaging printheads activate heat-sensitive substrates without consumable ribbons, minimizing operating costs in high-volume, short-lifecycle applications. Chinese e-commerce fulfillment centers and North American parcel carriers deploy these systems for shipping labels where imaging permanence beyond 12 months is unnecessary.
- Impact Printers:Dot-matrix mechanisms strike inked ribbons against paper, persisting in multi-part form printing for logistics documentation where physical impression copies remain legally required.
- Inkjet Printers:Piezoelectric or thermal inkjet deposition enables high-resolution color graphics on irregular surfaces, serving product decoration and brand authentication applications in cosmetics packaging.
- Laser Printers:Electrophotographic toner fusion delivers crisp document output and barcode symbologies in office environments requiring integration with existing copier fleets.
Thermal transfer systems handle the majority of industrial throughput; direct thermal configurations are gaining share fastest in logistics automation.
Technology:
Encoding protocols span from mature linear barcode symbologies to emerging RFID standards that enable non-line-of-sight data capture.
- UHF RFID:Ultra-high frequency tags operating at 860-960 MHz enable simultaneous reading of hundreds of items at distances exceeding 10 meters. Apparel retailers in the United States and automotive assembly plants in Stuttgart mandate this technology for real-time inventory visibility and just-in-sequence parts delivery.
- HF RFID:High-frequency systems at 13.56 MHz support near-field applications requiring secure, proximity-limited data exchange. Pharmaceutical cold chain monitoring and medical device authentication in Ireland rely on these encoders for tamper-evident tracking.
- NFC:Near-field communication enables consumer-facing tap interactions for product authentication and warranty registration in European consumer electronics.
- 1D Barcode:Linear symbologies including Code 128 and GS1-128 persist in legacy warehousing systems and retail point-of-sale infrastructure.
- 2D Barcode:Matrix codes such as Data Matrix and QR encode substantial data density for space-constrained medical device labeling and direct-part marking in aerospace.
- Smart Card Printers:Dedicated encoding hardware personalizes contact and contactless credentials for government identification and corporate access control programs.
1D barcode infrastructure retains the largest installed base; UHF RFID encoders are expanding most quickly as item-level tagging mandates proliferate.
Application:
Functional use cases range from high-frequency transactional operations to episodic asset lifecycle tracking with distinct durability and speed requirements.
- Inventory Management:Real-time stock visibility systems encode location and quantity data for warehouse management software integration, with demand concentrating in Indian pharmaceutical distribution hubs and German automotive spare parts operations.
- Asset Tracking:Capital equipment and returnable container monitoring requires ruggedized labels surviving repeated cleaning and outdoor exposure, driving specifications in North American manufacturing and European chemical processing.
- Ticketing Solutions:Event access and transportation fare media demand high-speed, high-volume encoding with anti-counterfeiting features for sports venues and municipal transit authorities.
- Document Management:Legal and medical record labeling prioritizes archival stability and audit trail compliance in healthcare systems and financial services.
- Retail Checkout:Point-of-sale encoding integrates with loyalty programs and return processing, prevalent in grocery and apparel chains operating synchronized omnichannel systems.
- Library Management:Automated circulation and anti-theft systems encode media identification for public and academic collections.
Inventory management absorbs the highest equipment volume; asset tracking applications command the steepest expansion trajectory as industrial IoT investments accelerate.
End User:
Customer types span from capital-intensive manufacturing operations to distributed service networks with diverging total-cost-of-ownership calculations.
- Manufacturing Units:Production floor encoding integrates with MES and ERP systems for work-in-progress tracking and finished goods serialization, with pharmaceutical manufacturers in New Jersey and medical device producers in Bavaria driving precision thermal transfer specifications.
- Warehousing Facilities:Third-party logistics operators and dedicated distribution centers prioritize throughput speed and fleet manageability across multi-shift operations.
- Logistics Companies:Parcel and freight carriers require mobile and stationary encoding solutions compatible with harsh environmental conditions and rapid package handling.
- Retail Chains:Store-level and backroom printing supports price marking, shelf labeling, and omnichannel fulfillment from thousands of distributed locations.
- Educational Institutions:Campus card issuance and library automation represent lower-volume, higher-customization procurement patterns.
- Transportation Providers:Airlines, railways, and maritime operators encode baggage, cargo, and maintenance documentation for regulatory compliance and operational efficiency.
Manufacturing units deploy the most capital-intensive encoding infrastructure; logistics companies are capturing share fastest as e-commerce fulfillment networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision equipment exports supply automotive assembly plants across Central Europe and North American Great Lakes manufacturing corridors.
United States
FDA serialization mandates for pharmaceutical distribution and NHTSA automotive traceability requirements drive thermal transfer printer upgrades. Michigan and New Jersey manufacturing clusters deploy UHF RFID encoding for just-in-sequence parts delivery to assembly lines. Retail headquarters in Chicago and Minneapolis mandate cloud-managed printer fleets for omnichannel inventory synchronization.
Germany
EU MDR traceability rules and REACH adhesive chemistry restrictions shape procurement specifications for medical device manufacturers. Bavarian automotive suppliers and Baden-Württemberg pharmaceutical packagers validate unit-level label accuracy for sterilization-resistant workflows. Stuttgart industrial corridors concentrate precision thermal transfer system demand for battery passport compliance.
China
SAMR quality infrastructure investments and NMPA pharmaceutical serialization requirements expand domestic equipment demand. Yangtze River Delta e-commerce fulfillment centers favor direct thermal configurations for short-lifecycle shipping labels. Shenzhen and Guangzhou electronics manufacturers integrate UHF encoding for outbound logistics visibility.
India
CDSCO track-and-trace expansion for domestic drug distribution creates first-mover positioning for validated thermal transfer systems. Mumbai and Hyderabad pharmaceutical manufacturing clusters upgrade serialization infrastructure. DGFT export documentation requirements accelerate barcode printer deployment in Gujarat chemical processing zones.
Japan
METI supply chain resilience programs and PMDA medical device labeling standards sustain replacement demand for precision encoding equipment. Kanto region electronics assemblers and Kansai pharmaceutical producers navigate legacy ERP integration challenges. Nagoya automotive corridors deploy edge-computing converged printers for real-time quality validation.
Global RFID and Barcode Printer Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hardware-software platforms that transform capital equipment sales into recurring revenue relationships. Three strategic archetypes dominate: diversified industrial conglomerates with captive distribution networks, precision thermal specialists with deep pharmaceutical validation expertise, and software-centric vendors leveraging cloud-native fleet management. Competitive intensity concentrates on M&A activity absorbing regional specialists and strategic partnerships linking encoding hardware with enterprise IoT platforms.
Within the diversified industrial tier, Zebra Technologies Corporation and Honeywell International Inc. exemplify platform-centric positioning through integrated software stacks that extend customer lifetime value beyond hardware transactions. SATO Holdings Corporation anchors the precision-specialist archetype with concentrated expertise in pharmaceutical serialization workflows. These three occupy positions across the premium equipment spectrum, with geographic origins spanning North American conglomerate structures and Japanese precision manufacturing heritage.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| SATO Holdings Corporation |
| Honeywell International Inc. |
| Toshiba Tec Corporation |
| Printronix Auto ID |
| Avery Dennison Corporation |
| Seiko Epson Corporation |
| BIXOLON |
| Dascom |
| Others |
Supply & Pricing Matrix
Yantian Port freight corridors connecting Shenzhen encoder module foundries to Stuttgart automotive assembly plants transmit cost volatility directly into regional price differentiation for UHF RFID equipment. Supply concentration in Taiwanese semiconductor fabrication compresses margins for mid-tier printer OEMs while rewarding integrated vendors with captive chip sourcing.
Pricing Analysis
Current-generation UHF RFID encoders command substantial premiums over legacy thermal transfer systems and emerging inkjet alternatives. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-validated units from logistics-grade configurations. Price differentiation hinges on FDA 21 CFR Part 11 certification tier and geographic delivery cost from Asian manufacturing hubs. Cost compression in economy direct thermal segments is intensifying because Chinese e-commerce fulfillment operators prioritize consumable efficiency over equipment longevity. Third-party logistics providers exhibit highest price sensitivity; pharmaceutical manufacturers with serialization mandates show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for thermal printhead assemblies and ribbon substrate formulations. Encoder chip fabrication concentrates in Taiwan and South Korea; precision mechanical components originate from Japan and Germany. Raw material dependencies span silicon wafers, wax-resin polymer feedstocks, and synthetic label substrates. Single-source vulnerability in RFID inlay production threatens just-in-sequence automotive supply chains. Distribution runs through authorized industrial distributors with regional technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native printer management platforms are disrupting traditional hardware-centric revenue models, with EU MDR traceability mandates and battery passport requirements accelerating technology refresh cycles across European manufacturing.
For Market Incumbents: Build switching-cost moats through deep ERP integration and managed print service subscriptions. Zebra Technologies and Honeywell International should consolidate channel partnerships in North American retail headquarters to preempt SaaS-native challengers. Invest in pharmaceutical validation documentation capabilities to defend against precision-specialist competition from SATO Holdings. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical serialization where CDSCO track-and-trace expansion outpaces incumbent coverage. Target Mumbai and Hyderabad manufacturing clusters with validated thermal transfer systems priced below European imports. Lead with edge-computing converged printers offering real-time print quality validation as differentiated value proposition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming auto-ID divisions. Mid-cap precision specialists with pharmaceutical serialization expertise and regional validation engineering capabilities present attractive acquisition profiles. Watch for inflection signals in EPA industrial emissions guideline enforcement altering capital allocation toward energy-efficient labeling infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Fleet Management Platform | Transforms hardware transactions into recurring SaaS revenue across North American retail chains. |
| Pharmaceutical Validation Certification | Unlocks FDA-compliant unit-level serialization contracts with New Jersey and Bavarian manufacturers. |
| Bio-Derived Ribbon Formulation | Preempts ESG disclosure penalties under CSRD frameworks for European automotive suppliers. |
| Edge-Computing Hardware Convergence | Enables real-time print quality validation commanding premium pricing in aerospace component marking. |
| Managed Print Service Expansion | Improves customer lifetime value through subscription relationships with distributed retail fleets. |
Research Methodology
A standing panel of plant engineers, OEM procurement managers, aftermarket service heads, and distribution channel partners provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade data, and industry association reports from AIM Global and VDC Research. Bottom-up equipment shipment analysis triangulated against top-down enterprise IT spending surveys.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning product type, encoding technology, application use case, and end-user industry. CAGRs derived from equipment replacement cycle analysis, regulatory mandate implementation timelines, and e-commerce fulfillment network expansion patterns. Forecast inputs incorporated SAMR quality infrastructure investments and NMPA pharmaceutical serialization requirements as demand accelerators.
Sensitivities concentrate around Taiwan semiconductor supply disruptions, REACH adhesive chemistry restrictions, and direct thermal substitution in Chinese logistics. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise cloud migration velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Web to Print Market
Printing Technology
Large Character Printers Market
Printing Technology
Professional Printers Market
Printing Technology
Card Printers Market
Printing Technology
Digital Paper System Market
Printing Technology
Global Microprinting Market
Printing Technology
Print on Demand Software Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Book Printing Service Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Oceania Digital Textile Printer Market
Printing Technology
Photo Printing Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Cloud Print Market