
 Egypt E-Commerce Market | 2026-2036
Egypt E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt E-Commerce Market Foresight
Product bundling is hardening as the dominant configuration pattern across Egyptian digital retail, with platforms combining grocery staples, electronics accessories, and fashion basics into single-cart checkout experiences. Jumia leverages its proprietary logistics network to anchor bundled fulfillment economics in Greater Cairo and the Nile Delta corridor. Amazon Egypt competes through Prime-style subscription mechanics that sustain repeat purchase frequency. Breadfast specializes in daily-essential bundling, controlling morning-delivery slots that differentiate its value proposition from generalist rivals.
Egypt e-commerce denotes digitally mediated transactions between buyers and sellers executed through web-based storefronts or native mobile applications, relying on electronic payment rails and last-mile distribution infrastructure to complete commercial exchange. The ecosystem encompasses order management systems, inventory synchronization protocols, and COD reconciliation workflows that enable merchants to reach consumers beyond traditional retail geography. Fashion and electronics command the dominant transaction value pools, while grocery delivery represents the fastest-growing product type as urban consumers prioritize convenience over in-store selection. Mobile wallets and cash-on-delivery split the payment method landscape, with margin accretion favoring digital payment channels that reduce COD reconciliation overhead and return fraud exposure.
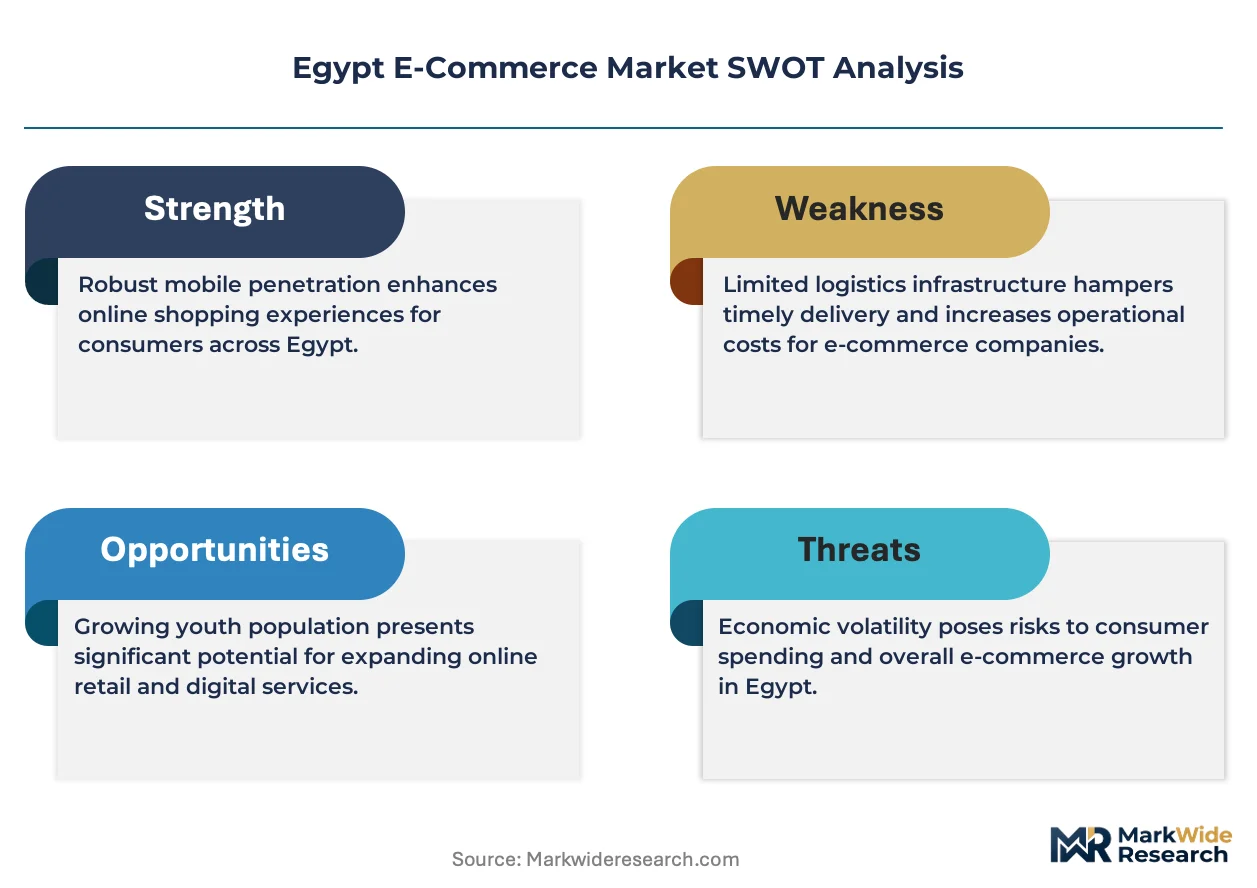
The Central Bank of Egypt governs digital payment licensing and fintech interoperability standards that determine which mobile wallet providers can integrate with merchant checkout flows. The General Authority for Investment and Free Zones shapes foreign platform market access through e-commerce licensing requirements and data localization stipulations. Stakeholders must monitor how regulatory tightening around consumer data protection and cross-border fulfillment taxation reshapes platform operating economics and merchant onboarding thresholds.
Market Dynamics
Product bundling economics and mobile wallet penetration through Central Bank of Egypt licensing reforms are compressing checkout friction and reshaping merchant viability thresholds across Egyptian digital retail.
Growth Catalysts
- Fintech licensing liberalization:Central Bank of Egypt mobile wallet authorizations expand checkout integration options for merchants beyond cash-on-delivery reconciliation overhead.
- Urban household density:Cairo and Alexandria concentration enables same-day fulfillment economics that sustain grocery delivery unit economics.
- Last-mile infrastructure buildout:Proprietary logistics networks reduce dependency on third-party courier fragmentation in Greater Cairo and Nile Delta corridors.
Market Restraints
- COD reconciliation drag:Cash-on-delivery payment rails impose working capital intensity and return fraud exposure that erode merchant margins.
- Cross-border fulfillment taxation:Customs duty complexity on electronics imports creates price discontinuities between local and international platform offerings.
- Data localization mandates:General Authority for Investment and Free Zones stipulations increase server infrastructure capex for foreign platform operators.
Strategic Opportunities
- Upper Egypt penetration:Lower e-commerce saturation in Assiut, Sohag, and Qena governorates offers first-mover bundling economics as mobile wallet coverage expands.
- Subscription mechanics:Prime-style loyalty programs lock in repeat purchase frequency and reduce customer acquisition cost volatility.
- Morning-delivery slot control:Daily-essential bundling with guaranteed AM windows captures household routine lock-in unavailable to generalist rivals.
Industry Challenges
- Warehouse management system integration:Legacy inventory synchronization protocols create stockout visibility gaps between merchant backends and platform storefronts.
- Reverse logistics infrastructure:Returns processing capacity constraints limit fashion category expansion where sizing uncertainty drives high return rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt E-Commerce Market |
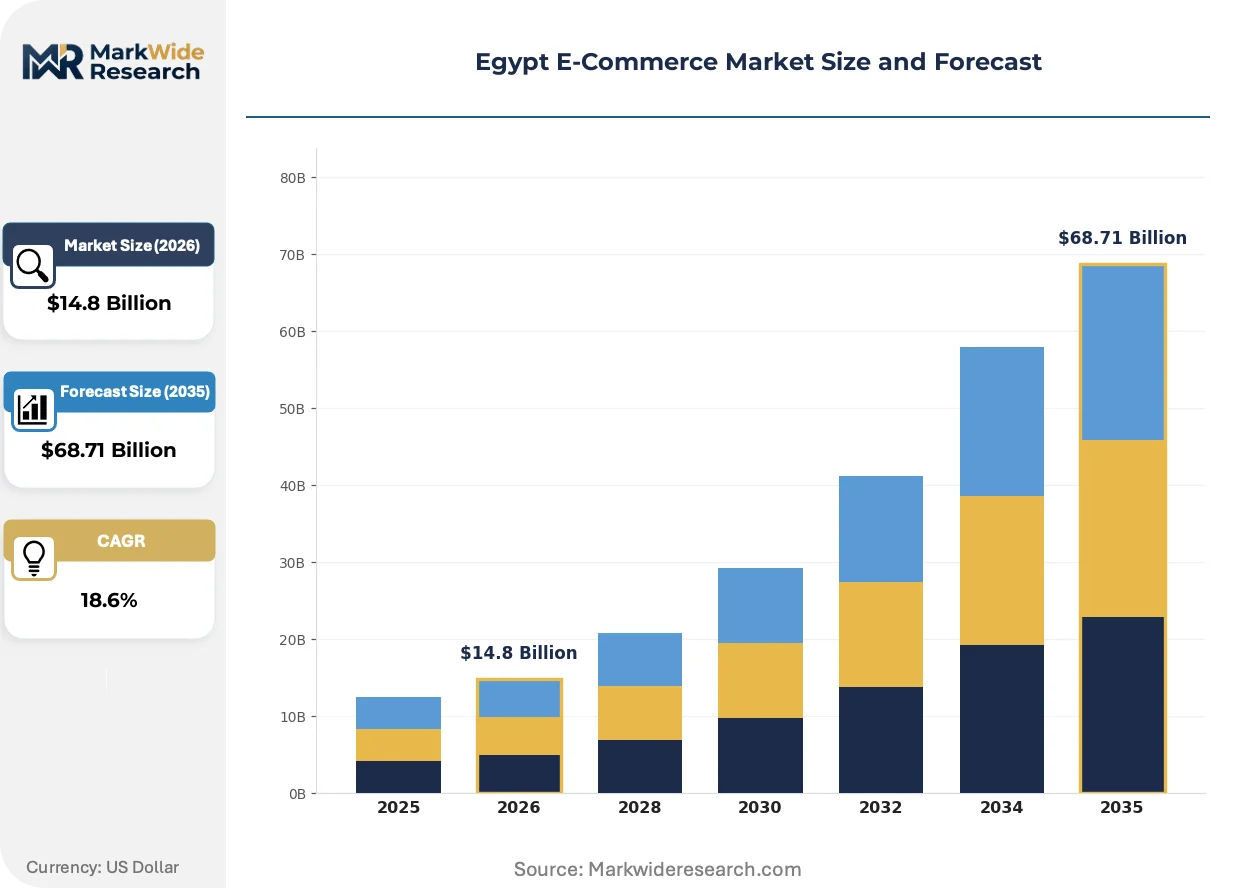
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Groceries, Home Appliances Customer Type: Individuals, Small Businesses, Corporates, Students Payment Method: Credit Cards, Cash on Delivery, Mobile Wallets, Bank Transfers Delivery Model: Standard Shipping, Express Delivery, Click and Collect, Same-Day Delivery |
| Companies Covered | Jumia, Noon, Amazon Egypt, Breadfast, Maxab, Carrefour Egypt, Shein, Yodawy, Homzmart, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt E-Commerce Market Shifts & Advancements
Mobile-first checkout architecture and embedded finance integration are compressing payment friction and reconfiguring merchant onboarding requirements across Egyptian digital commerce.
Instant checkout tokenization is electrifying payment completion rates by eliminating re-authentication steps for repeat purchases. Cairo-based fashion and electronics merchants adopting one-tap mobile wallet settlement report abandonment reduction at checkout stages. This compression of payment friction is electrifying conversion economics for mid-market sellers previously constrained by COD dependency.
Central Bank of Egypt open banking frameworks are mandating interoperability standards between licensed mobile wallet providers and merchant acquirers. These protocols force platform consolidation around standardized API architectures that reduce integration cost for multi-wallet acceptance. Electronics and grocery segments face the steepest compliance timelines as transaction volume thresholds trigger mandatory interoperability certification.
Household procurement consolidation is shifting from single-category apps toward unified-cart platforms combining grocery staples, electronics accessories, and fashion basics. Morning-delivery specialists and generalist marketplaces compete for routine-driven purchase frequency through subscription bundling. This behavioral pivot concentrates most visibly in Cairo and Alexandria metropolitan zones where dual-income households prioritize time savings over in-store selection breadth.
Egypt E-Commerce Market Segmentation
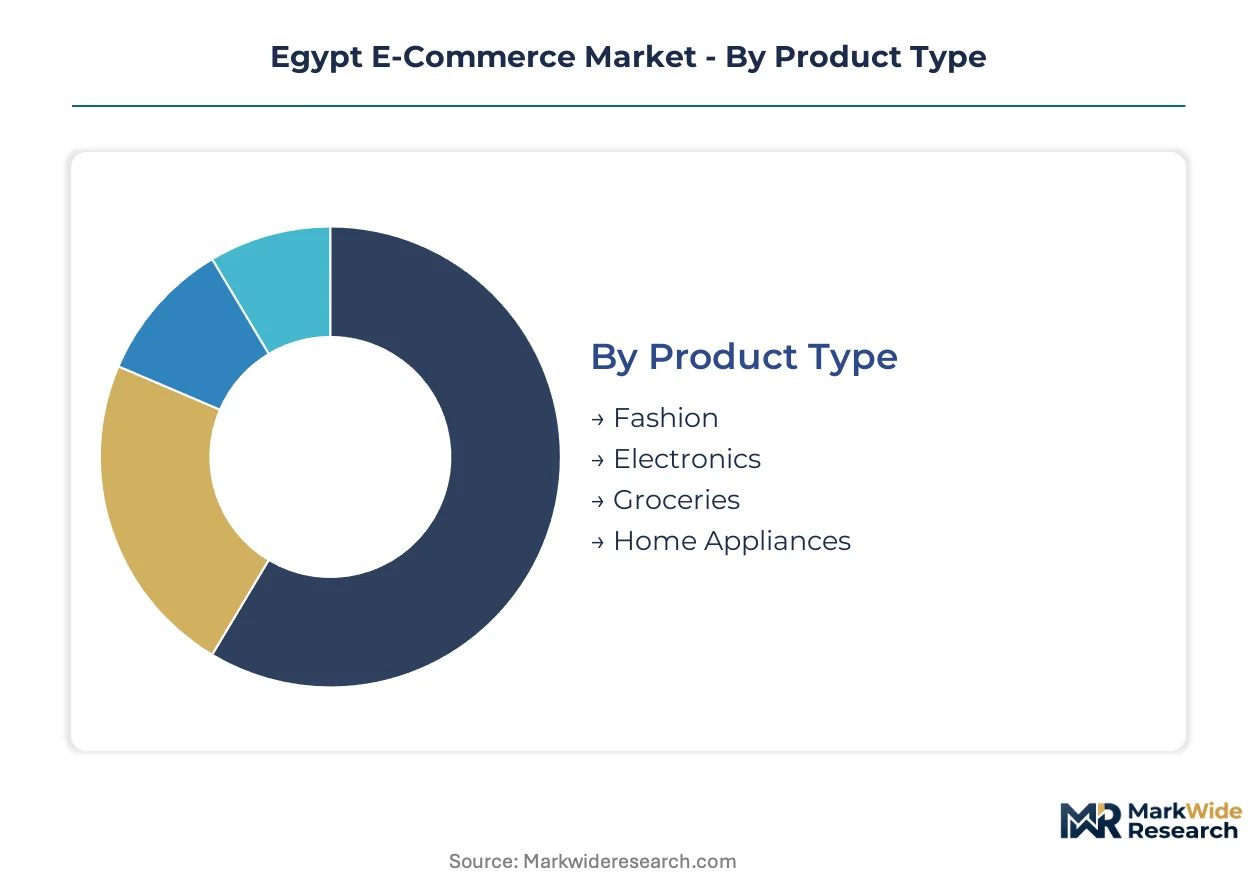
Segmentation in Egyptian digital retail reveals how payment infrastructure maturity and fulfillment speed capabilities determine addressable market scope. Merchants configure platform architectures around specific customer procurement patterns and geographic density thresholds.
Product Type:
Technology specifications and inventory turnover velocity differentiate margin structures across Egypt's e-commerce categories.
- Fashion:Apparel and accessories with high SKU proliferation and seasonal obsolescence cycles. Demand concentrates in Greater Cairo and Alexandria metropolitan zones where sizing uncertainty drives elevated return rates that strain reverse logistics capacity.
- Electronics:Consumer devices and computing equipment requiring warranty infrastructure and technical support integration. Cairo-based households dominate transaction volume, though customs duty complexity on cross-border fulfillment creates price discontinuities against local assembly alternatives.
- Groceries:Daily essentials with perishability constraints and narrow delivery windows.
- Home Appliances:Bulky goods requiring specialized last-mile handling and installation services.
Fashion leads on scale; groceries lead on momentum.
Customer Type:
Procurement volume thresholds and payment method preferences segment platform engagement models.
- Individuals:Household consumers purchasing for personal consumption with mobile wallet adoption accelerating through Central Bank of Egypt licensing reforms.
- Small Businesses:Micro-enterprises sourcing inventory and operational supplies through B2B marketplace interfaces.
- Corporates:Enterprise procurement with invoice-based reconciliation and volume-based pricing negotiations.
- Students:Price-sensitive demographic concentrated in university cities with electronics and fashion dominating basket composition.
Individuals anchor transaction volume; small businesses expand most quickly.
Payment Method:
Settlement rail economics and fraud exposure profiles determine merchant preference hierarchies.
- Credit Cards:Bank-issued plastic with chargeback mechanisms and installment plan integration. Cairo and Alexandria card penetration supports checkout completion rates that reduce abandonment versus cash alternatives.
- Cash on Delivery:Physical currency exchange at delivery point imposing working capital intensity and return fraud exposure that erode margins for mid-market sellers.
- Mobile Wallets:Smartphone-based digital wallets licensed under Central Bank of Egypt frameworks.
- Bank Transfers:Direct account debits with settlement delays limiting appeal for time-sensitive purchases.
Cash on delivery retains volume dominance; mobile wallets gain share fastest.
Delivery Model:
Fulfillment speed capabilities and infrastructure capex requirements stratify platform competitive positioning.
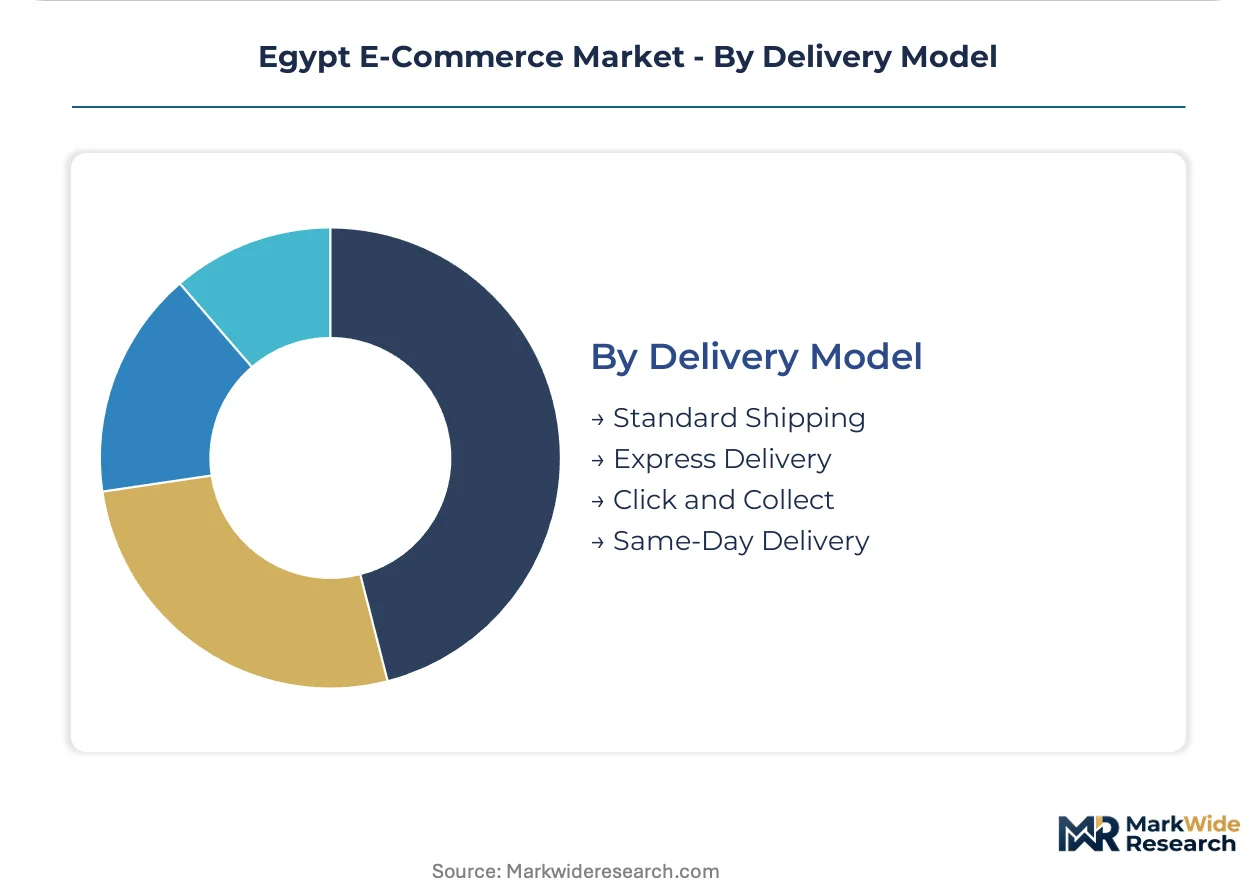
- Standard Shipping:Two-to-five-day delivery windows with lowest cost structure and broadest geographic coverage across Egypt's governorates.
- Express Delivery:Next-day fulfillment requiring proprietary logistics networks or premium courier contracts in Greater Cairo and Nile Delta corridors.
- Click and Collect:Locker or partner location pickup reducing last-mile delivery cost for cost-conscious consumers.
- Same-Day Delivery:Ultra-rapid fulfillment with morning-slot guarantees capturing household routine lock-in for grocery and daily-essential categories.
Standard shipping anchors unit economics; same-day delivery climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's e-commerce infrastructure first achieved critical mass in Greater Cairo, where early platform investments concentrated fulfillment networks and payment integration before radiating toward secondary urban centers. The market now exhibits distinct geographic performance tiers shaped by household density, mobile wallet penetration, and last-mile infrastructure maturity.
Greater Cairo
Dual-income households in Cairo and Giza governorates drive the highest per-capita online transaction frequency, with same-day grocery delivery and electronics purchases dominating basket composition. Central Bank of Egypt mobile wallet licensing reforms have accelerated digital payment adoption in these metropolitan zones, reducing cash-on-delivery dependency. Nasr City and New Cairo host the densest concentration of platform fulfillment centers, where proprietary logistics networks enable sub-two-hour delivery windows for daily essentials.
Alexandria
Mediterranean coastal households exhibit stronger cross-border purchasing behavior, particularly in fashion and electronics categories where international platform price comparisons influence merchant selection. The General Authority for Investment and Free Zones data localization requirements affect foreign platform server infrastructure decisions in this region. Smouha and Stanley districts anchor the city's e-commerce fulfillment cluster, with express delivery corridors extending toward Borg El Arab industrial zones.
Nile Delta Corridor
Manufacturing towns across Sharqia, Dakahlia, and Qalyubia governorates generate rising B2B procurement demand through digital marketplace interfaces. Small business mobile wallet adoption lags Cairo benchmarks, sustaining higher cash-on-delivery ratios that compress merchant margins. Belbeis and Mansoura function as emerging logistics nodes where platform warehouse investments target underpenetrated household segments.
Upper Egypt
Assiut, Sohag, and Qena governorates present first-mover bundling economics as mobile wallet coverage expands beyond metropolitan cores. Lower e-commerce saturation creates acquisition cost advantages for platforms willing to build localized fulfillment infrastructure. Asyut University cities concentrate student demand for electronics and fashion, though reverse logistics capacity constraints limit category expansion.
Suez Canal Zone
Port Said and Ismailia households benefit from customs-adjacent positioning that reduces cross-border fulfillment taxation exposure on electronics imports. Port logistics integration enables faster international platform delivery timelines than Upper Egypt counterparts. The zone's industrial workforce generates steady demand for home appliance categories requiring specialized installation services.
Egypt E-Commerce Market Competitive Landscape
The competitive structure tilts toward integrated marketplace-logistics hybrids rather than pure retail aggregators. Platform viability depends on proprietary fulfillment network coverage and mobile wallet integration depth. Three archetypes dominate: horizontal marketplaces spanning multiple categories, vertical specialists controlling narrow delivery windows, and international platforms leveraging global supply chains. Capacity expansion into secondary cities and subscription loyalty program deployment constitute the primary competitive moves.
Within the integrated marketplace tier, Jumia and Amazon Egypt exemplify divergent strategic postures. Jumia anchors bundled fulfillment economics through its proprietary logistics infrastructure across Greater Cairo and the Nile Delta corridor. Amazon Egypt occupies a position defined by Prime-style subscription mechanics that sustain repeat purchase frequency. Breadfast represents the vertical specialist archetype, controlling morning-delivery slots that differentiate its daily-essential bundling from generalist rivals.
| Leading Market Players |
|---|
| Jumia |
| Noon |
| Amazon Egypt |
| Breadfast |
| Maxab |
| Carrefour Egypt |
| Shein |
| Yodawy |
| Homzmart |
| Others |
Supply & Pricing Matrix
Household procurement consolidation into unified-cart platforms is forcing merchants to absorb fulfillment complexity while competing on delivery speed, compressing margins and rewarding those with captive logistics infrastructure in Greater Cairo and Alexandria.
Pricing Analysis
Subscription-based loyalty mechanics anchor pricing architecture across Egyptian digital retail, with Prime-style programs locking in repeat purchase frequency and reducing customer acquisition cost volatility. Three-tier pricing structure across premium express, standard next-day, and economy multi-day delivery windows segments buyer willingness-to-pay by urgency. Cost compression in standard shipping tiers is intensifying because cash-on-delivery reconciliation overhead erodes merchant margins on low-value baskets. Students concentrated in university cities exhibit highest price sensitivity, while dual-income households in New Cairo and Nasr City prioritize speed over cost.
Supply Chain Analysis
Electronics inventory rests on assembly operations in China, Vietnam, and Malaysia, with cross-border fulfillment exposing merchants to customs duty complexity that creates price discontinuities against local alternatives. Warehouse management systems, last-mile delivery fleets, and reverse logistics capacity constitute the critical input dependencies. Single-source vulnerability concentrates in proprietary logistics networks controlled by integrated marketplace operators. Distribution runs through platform-owned fulfillment centers in Greater Cairo and the Nile Delta corridor, with third-party courier fragmentation persisting in Upper Egypt governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egyptian e-commerce functions as a geographic-arbitrage play where Lower Upper Egypt governorates offer acquisition cost advantages against saturated Cairo benchmarks as mobile wallet coverage expands.
For Market Incumbents: Acquire morning-delivery slot capacity to lock in household routine dependency before vertical specialists consolidate daily-essential bundling. Defend against Amazon Egypt's Prime-style subscription mechanics by deepening proprietary logistics coverage in the Nile Delta corridor. Central Bank of Egypt interoperability mandates threaten platform-specific wallet lock-in advantages. For New Entrants and Emerging Players: Central Bank of Egypt mobile wallet licensing reforms in Assiut, Sohag, and Qena governorates open a window for first-mover bundling economics in undersupplied Upper Egypt markets. Target student demographics concentrated around Asyut University with electronics and fashion assortment tailored to price-sensitive procurement patterns. Launch with click-and-collect infrastructure to bypass last-mile delivery cost disadvantages against established players. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists controlling narrow delivery windows in grocery and daily-essential categories. Long-term viability favors platforms with integrated logistics networks and subscription loyalty programs over pure retail aggregators. Watch mobile wallet penetration rates in secondary cities as the inflection indicator for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Logistics Network Expansion | Captive last-mile capacity in Greater Cairo reduces dependency on fragmented courier markets and sustains same-day economics. |
| Subscription Loyalty Program Launch | Prime-style mechanics lock in repeat purchase frequency and dampen customer acquisition cost volatility for electronics merchants. |
| Morning-Delivery Slot Control | Guaranteed AM windows capture household routine lock-in unavailable to generalist rivals in grocery and daily-essential segments. |
| Mobile Wallet Integration Deepening | Central Bank of Egypt interoperability certification expands checkout options beyond cash-on-delivery reconciliation overhead. |
| Upper Egypt Geographic Expansion | First-mover positioning in Assiut and Sohag exploits lower e-commerce saturation as mobile wallet coverage radiates southward. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with marketplace operations directors, logistics network managers, mobile wallet product leads, merchant onboarding specialists, and Central Bank of Egypt regulatory affairs officers with secondary validation against customs trade records, Central Bank of Egypt payment system reports, platform SEC filings, and e-commerce transaction databases. Bottom-up merchant revenue estimates and top-down household spending pattern analysis were triangulated to anchor market sizing.
Historical reference periods spanning pre-pandemic baselines through mobile wallet licensing reform implementation anchored the forecast window, with growth trajectories modeled across product type, customer segment, payment method, and delivery model dimensions plus urban density tiers. CAGRs were derived from segment-level growth rate synthesis applied to baseline market estimates. Fulfillment infrastructure capex cycles and mobile wallet adoption curves served as primary forecast inputs.
Revisions become necessary when Central Bank of Egypt regulatory tightening, cross-border fulfillment taxation shifts, or logistics infrastructure investment delays materialize beyond modeled assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
South America E-Commerce Apparel Market
E-Commerce Solutions
UAE Ecommerce Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Direct-To-Consumer Test Market
E-Commerce Solutions
Vietnam E-Commerce Market