
 Commercial Printing Outsourcing Market | 2026-2036
Commercial Printing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Printing Outsourcing Market Insights
India is reconfiguring regional supply dynamics through new commercial print clusters in Gujarat and Tamil Nadu. R.R. Donnelley & Sons Company leverages its Asia-Pacific plant network to serve multinational retail contracts. Quad/Graphics anchors North American volume through integrated premedia-to-distribution facilities. Dai Nippon Printing Co., Ltd. dominates Japan's high-mix, short-run segment with precision inkjet systems.
Commercial printing outsourcing covers the delegation of print production, finishing, and logistics to third-party providers operating sheet-fed offset, web offset, or digital toner and inkjet platforms, typically managing run lengths from single copies to millions of impressions for corporate communications, packaging, and promotional materials. Offset printing retains the largest revenue pool in long-run magazines and catalogs, while digital printing captures the fastest expansion in personalized direct mail and variable-data packaging. Inkjet technology is displacing laser in label and wide-format applications due to substrate flexibility and lower energy per impression.
EPA enforcement of Clean Air Act standards on volatile organic compound emissions shapes ink formulation choices across US-based converters. REACH and RoHS compliance in Europe restricts heavy-metal pigments and certain photoinitiators in food-contact print applications. India's BIS certification mandates safety testing for imported printing equipment, affecting technology procurement timelines. Stakeholders must weigh regulatory compliance costs against regional outsourcing advantages when selecting production footprints.
Market Dynamics
Digital inkjet platforms are compressing run-length economics and forcing converters to reconfigure capacity allocation between offset and toner-based systems. The EU F-Gas Regulation and EPA Clean Air Act enforcement are simultaneously raising compliance costs while creating technology substitution windows.
Growth Catalysts
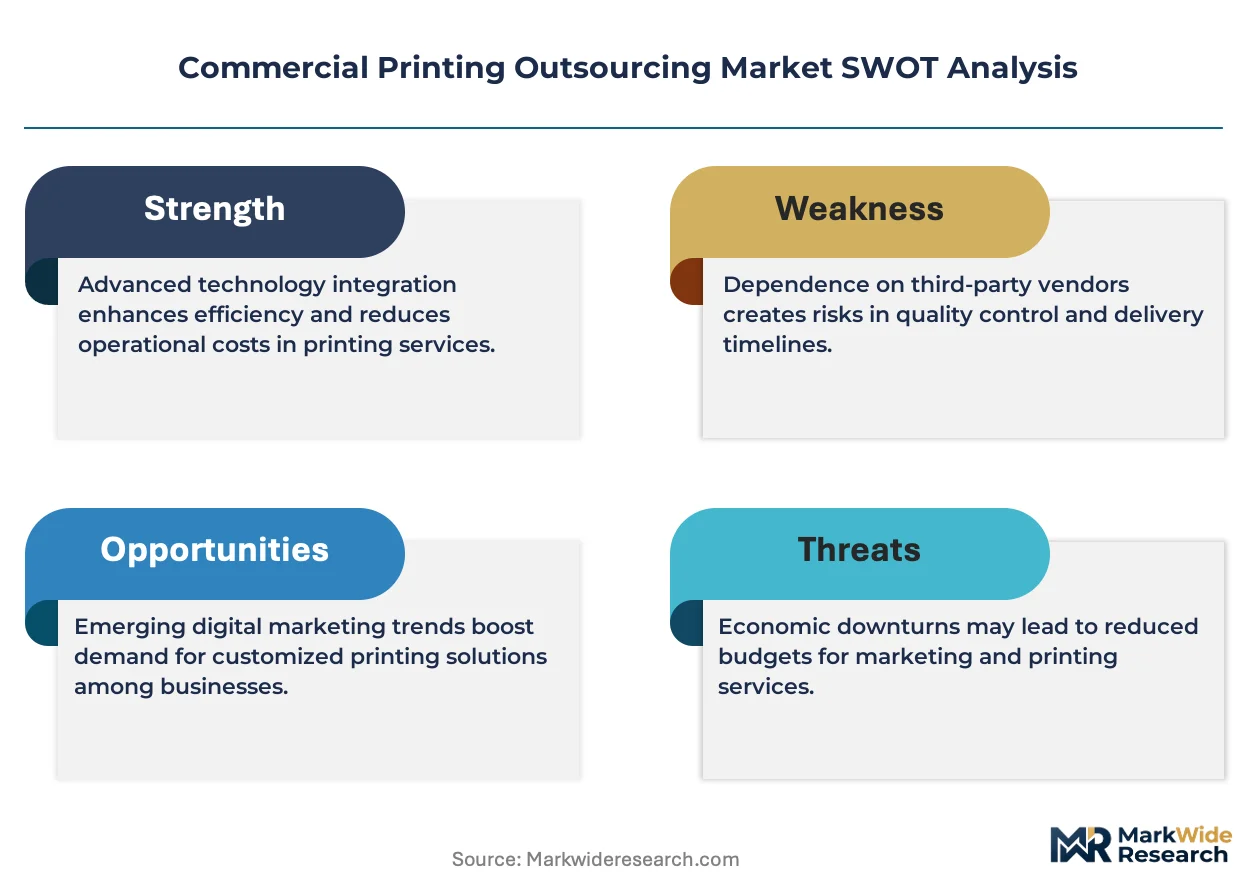
- Variable-data packaging demand:Food and beverage brands are outsourcing short-run, personalized carton production to enable regional promotional campaigns and SKU proliferation without inventory risk.
- India's PLI scheme for packaging:Domestic converters in Gujarat and Tamil Nadu are scaling commercial print clusters to capture multinational retail contracts previously routed through Southeast Asian hubs.
- Water-based ink systems:The EU Green Deal is accelerating converter migration from solvent-based formulations, expanding addressable market for equipment vendors with aqueous inkjet certification.
Market Restraints
- Pigment supply concentration:Heavy-metal pigment restrictions under REACH and RoHS have consolidated qualified supplier bases in Europe, extending procurement lead times for food-contact print applications.
- Substrate cost volatility:Pulp price fluctuations and energy-intensive paper drying processes are compressing converter margins on catalog and magazine contracts with fixed annual pricing.
- Laser-to-inkjet substitution ceiling:Toner systems retain cost advantages in ultra-short-run transactional print, limiting inkjet penetration in banking and insurance document verticals.
Strategic Opportunities
- Wide-format retail signage:Big-box chains are consolidating in-store visual merchandising procurement under single-source commercial print contracts spanning design-to-installation logistics.
- BIS certification acceleration:India's mandatory safety testing for imported printing equipment is creating captive demand for domestically certified premedia and finishing technology providers.
- Hybrid web-to-print platforms:Integration of cloud-based design tools with production scheduling software is enabling real-time job routing across distributed converter networks.
Industry Challenges
- Color management specialist scarcity:Converters face recruitment gaps for ICC profile technicians capable of calibrating across offset, toner, and inkjet color gamuts within single-facility workflows.
- Legacy MIS integration friction:Enterprise resource planning systems from the 2000s require costly middleware development to connect with modern web-to-print order intake portals.
- CE marking documentation burden:European machinery directives demand extensive technical file compilation, extending commissioning timelines for imported finishing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Printing Outsourcing Market |
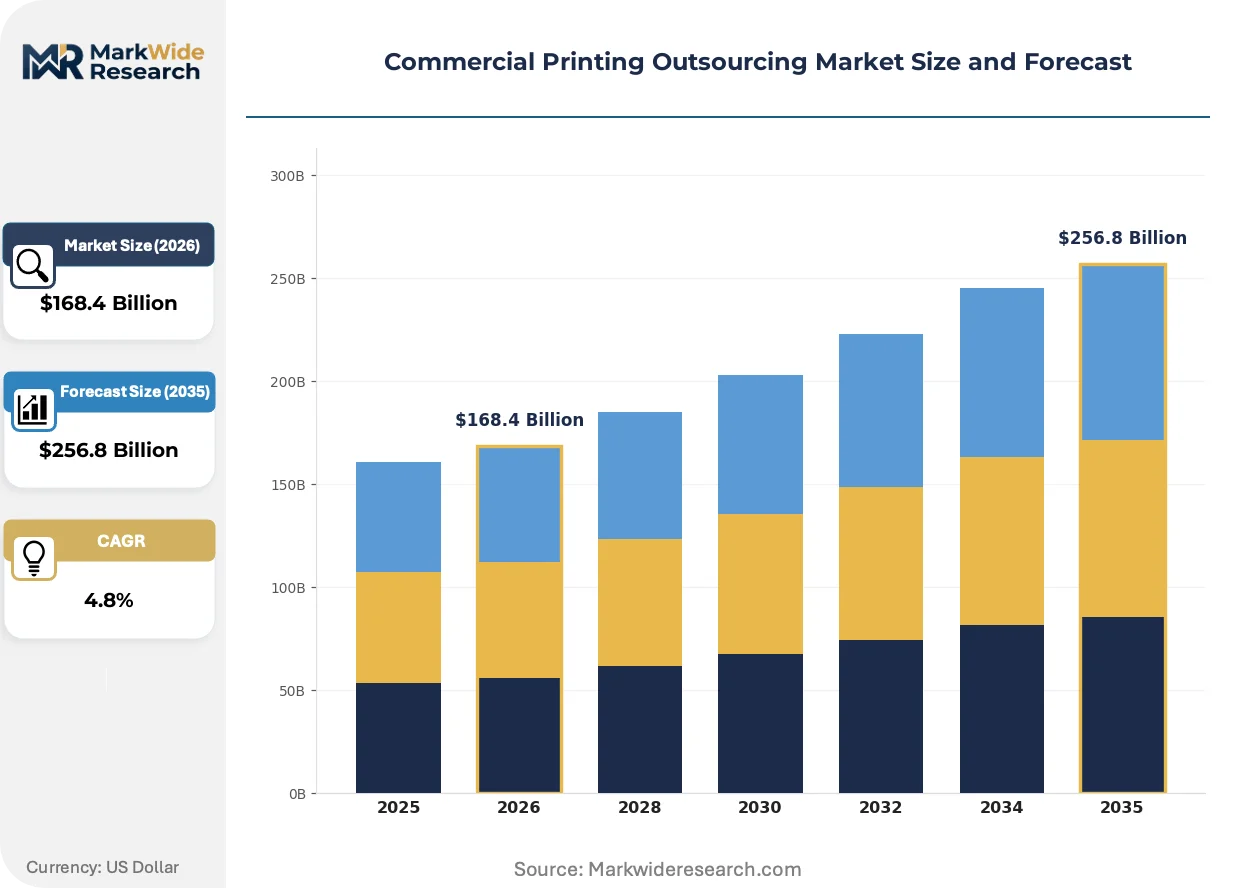
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $256.8 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Printing, Offset Printing, Flexographic Printing, Screen Printing End User: Retail, Advertising Agencies, Publishing, Packaging Product Type: Brochures, Flyers, Labels, Business Cards Technology: Inkjet, Laser, Thermal, 3D Printing |
| Companies Covered | R.R. Donnelley & Sons Company, Quad/Graphics, Cimpress plc, Deluxe Corporation, Transcontinental Inc., Taylor Corporation, Cenveo Worldwide Limited, Dai Nippon Printing Co., Ltd., ACME Printing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Printing Outsourcing Market Trends and Innovations
Production workflows are converging around data-driven automation that collapses premedia, print, and fulfillment into unified digital threads. Three developments are restructuring competitive position.
Single-pass inkjet arrays are eliminating the makeready and plate costs that defined offset economics for decades. Magazine publishers with circulations below fifty thousand copies are migrating entire title portfolios to inkjet, rendering obsolete the traditional breakeven analysis between web offset and digital. This compression is reallocating capital toward finishing and logistics integration.
REACH authorization requirements for photoinitiators in UV-cured food packaging are forcing reformulation of ink chemistries across European converter bases. Suppliers are accelerating migration to LED-UV and electron beam curing systems to bypass restricted substance lists. Dairy and ready-meal brands are demanding documentation chains that trace every photoinitiator through the supply network.
Retail procurement teams are consolidating print buying under outcome-based contracts that specify shelf-ready delivery rather than unit pricing per thousand impressions. This restructures converter revenue toward logistics and inventory management services. Mass-market apparel and grocery verticals in Germany and France are piloting vendor-managed inventory programs where converters hold finished goods stock and replenish based on point-of-sale data.
Commercial Printing Outsourcing Market Segmentation
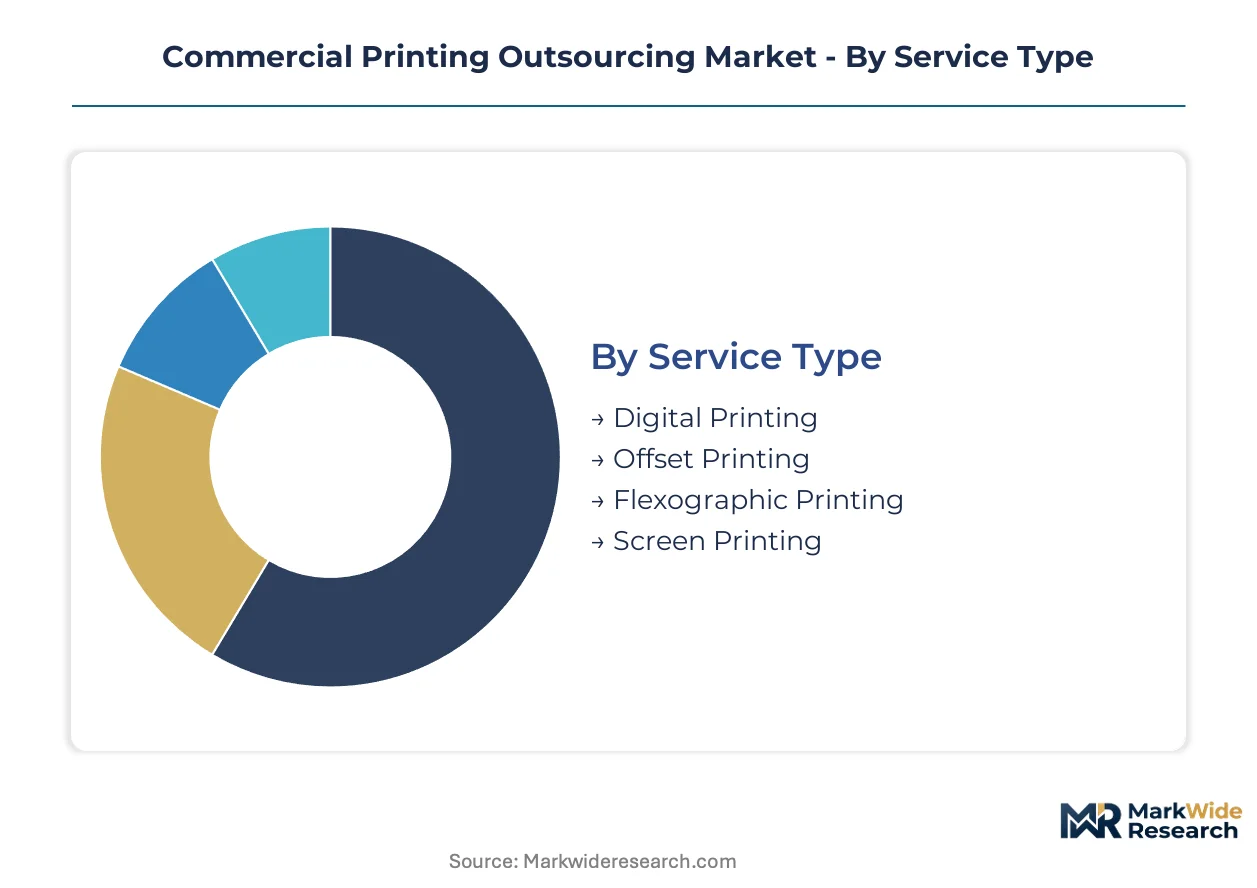
Commercial printing outsourcing fragments across four distinct dimensions that govern procurement decisions, technology selection, and margin structures. Service type determines capital intensity and run-length economics. End-user verticals impose divergent quality, speed, and compliance requirements. Product type and technology choices further stratify converter capabilities and geographic sourcing patterns.
Service Type:
Cost tier separates the four production methodologies, with capital requirements and per-unit economics creating distinct competitive territories.
- Digital Printing:Toner and inkjet platforms execute variable-data jobs without plate preparation. Retail chains in Germany and France outsource personalized direct mail and short-run promotional materials to compress campaign cycle times.
- Offset Printing:Sheet-fed and web offset systems dominate long-run magazines, catalogs, and annual reports. Magazine publishers with circulations above fifty thousand impressions retain offset for unit cost advantages on coated stocks.
- Flexographic Printing:Rotary relief printing on continuous webs serves high-volume packaging and label applications. Food-contact carton converters in India deploy flexo with water-based inks to meet BIS certification requirements.
- Screen Printing:Stencil-based ink deposition enables thick-film applications on rigid substrates. Wide-format retail signage and industrial membrane switch production utilize screen printing for opacity and durability.
Offset printing holds installed capacity. Digital printing is rotating up the share rankings.
End User:
Application context dictates specification intensity, with each vertical enforcing distinct color fidelity, turnaround, and regulatory standards.
- Retail:Big-box chains and fashion brands outsource in-store signage, point-of-purchase displays, and promotional inserts. Vendor-managed inventory programs in France consolidate procurement under outcome-based contracts specifying shelf-ready delivery.
- Advertising Agencies:Creative shops demand rapid prototyping, soft-proofing, and versioned campaign materials. Campaign compression cycles favor digital toner platforms with same-day turnaround.
- Publishing:Magazine and book publishers balance run-length economics against inventory risk. Academic and trade publishers in Japan migrate mid-list titles to inkjet to eliminate warehousing exposure.
- Packaging:Food, beverage, and cosmetics brands outsource folding cartons, labels, and flexible films. REACH-compliant photoinitiator documentation requirements reshape European converter qualification.
Publishing commands legacy volume. Packaging is expanding most quickly as SKU proliferation accelerates regional outsourcing.
Product Type:
Volume and margin profiles diverge across the four product categories, with format size and finishing complexity governing production routing.
- Brochures:Multi-page saddle-stitched or perfect-bound documents serve corporate communications and tourism promotion. Financial services firms in the US outsource quarterly shareholder materials with variable-data personalization.
- Flyers:Single-sheet promotional pieces dominate high-volume, low-margin production. Quick-turn digital platforms capture event-driven campaigns with sub-48-hour fulfillment.
- Labels:Pressure-sensitive and cut-stack formats serve product identification and logistics tracking. Wine and craft spirits brands in California specify estate-printed labels with tactile varnishes and foil stamping.
- Business Cards:Standard and premium cardstock formats with specialty finishing anchor entry-level print procurement. Design-to-distribution platforms integrate cloud-based templates with same-day production.
Flyers absorb highest impression counts. Labels command premium pricing tiers and steepest expansion trajectory.
Technology:
Maturity and substitution dynamics segment the four technology platforms, with energy efficiency and substrate flexibility driving replacement cycles.
- Inkjet:Piezoelectric and thermal drop-on-demand systems displace laser in label, wide-format, and transactional applications. Single-pass inkjet arrays eliminate makeready costs for magazine publishers below fifty thousand copies.
- Laser:Electrophotographic toner systems retain cost advantages in ultra-short-run banking and insurance documents. Legacy installed base in North American transactional print resists full inkjet migration.
- Thermal:Direct thermal and thermal transfer methods serve receipt printing, ticketing, and barcode labeling. Retail POS and logistics verticals specify thermal for durability and chemical resistance.
- 3D Printing:Additive fabrication enables prototyping, tooling, and limited production runs. Packaging converters in Gujarat pilot 3D-printed embossing dies to compress tooling lead times.
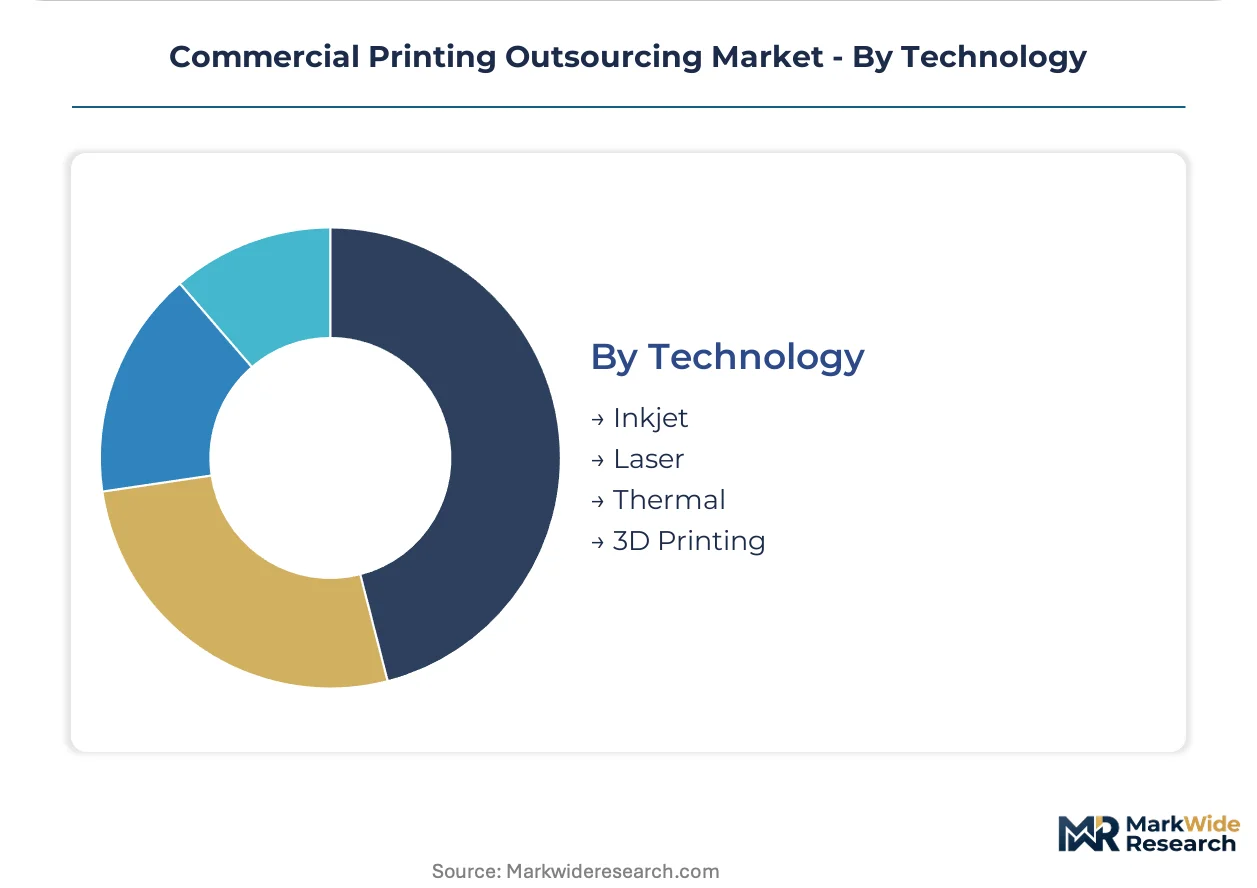
Laser retains installed base in transactional verticals. Inkjet is gaining share fastest across packaging and publishing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of Clean Air Act standards anchors the United States as the dominant geography for regulatory-driven technology substitution in commercial printing outsourcing.
United States
Retail chains and financial services firms drive outsourced print procurement for in-store signage and variable-data shareholder materials. EPA Clean Air Act enforcement on volatile organic compound emissions shapes ink formulation choices across converter bases. Integrated premedia-to-distribution facilities in Wisconsin and Illinois anchor North American volume for magazine and catalog production.
Germany
Big-box chains and grocery verticals consolidate procurement under outcome-based contracts specifying shelf-ready delivery. REACH and RoHS compliance restricts heavy-metal pigments and photoinitiators in food-contact print applications. Vendor-managed inventory programs in Bavaria and North Rhine-Westphalia pilot replenishment based on point-of-sale data.
India
BIS certification requirements and the PLI scheme for packaging accelerate domestic outsourcing capacity for multinational retail contracts. Domestic converters scale commercial print clusters in Gujarat and Tamil Nadu to capture volume previously routed through Southeast Asian hubs. Food-contact carton producers deploy flexographic systems with water-based inks to meet certification standards.
Japan
Academic and trade publishers migrate mid-list titles to inkjet to eliminate warehousing exposure and compress run-length economics. METI industrial standards guide technology procurement for precision printing equipment. High-mix, short-run production concentrates in the Kanto and Kansai regions around Tokyo and Osaka.
France
Mass-market apparel brands pilot vendor-managed inventory programs restructuring converter revenue toward logistics services. EU Green Deal and F-Gas Regulation push converters toward water-based ink systems and reduced volatile organic compound processes. Île-de-France anchors creative agency demand for rapid prototyping and versioned campaign materials.
Commercial Printing Outsourcing Market Competitive Landscape
Integrated conglomerates and specialized converters split the market between scale-driven volume plays and niche service depth. The vendor base concentrates around providers with captive premedia, print, and fulfillment capabilities. Three archetypes dominate: multinational integrated networks, regional scale operators, and technology-specialized boutiques. Competitive moves center on geographic expansion through plant network optimization and strategic partnerships for digital platform integration.
Within the integrated conglomerate tier, R.R. Donnelley & Sons Company and Dai Nippon Printing Co., Ltd. occupy positions exemplifying multinational plant network strategies. Quad/Graphics represents the North American regional scale archetype with consolidated premedia-to-distribution infrastructure. These three entities anchor the competitive structure without exhausting the field.
| Leading Market Players |
|---|
| R.R. Donnelley & Sons Company |
| Quad/Graphics |
| Cimpress plc |
| Deluxe Corporation |
| Transcontinental Inc. |
| Taylor Corporation |
| Cenveo Worldwide Limited |
| Dai Nippon Printing Co., Ltd. |
| ACME Printing |
| Others |
Pricing and Supply Chain Analysis
Gujarat's emerging commercial print clusters concentrate flexographic capacity for multinational retail contracts, translating regional scale advantages into pricing leverage over smaller converters in legacy Southeast Asian hubs. Water-based ink migration under EU F-Gas Regulation and India's BIS certification requirements is compressing margins for solvent-dependent facilities while rewarding early adopters with premium positioning in food-contact packaging procurement.
Pricing Analysis
Price spreads between German and Indian converters for comparable folding carton runs exceed thirty percent, reflecting divergent labor costs and regulatory compliance burdens. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels governs food-contact packaging procurement. Pricing pressure stems from pulp cost volatility and fixed annual contracts in magazine publishing. Retail chains exhibit lowest price sensitivity due to outcome-based contract structures, while commodity flyer producers face acute margin compression.
Supply Chain Analysis
Contract manufacturing concentrates among integrated networks like R.R. Donnelley and Quad/Graphics, with regional specialists in Gujarat and Tamil Nadu capturing PLI scheme incentives. Raw material dependencies center on coated paper stocks from Nordic mills, photoinitiator formulations from European chemical suppliers, and precision inkjet printheads from Japanese manufacturers. Single-source vulnerability in heavy-metal pigment supply under REACH restrictions threatens European converter qualification timelines. Distribution runs through vendor-managed inventory programs in France and Germany, with converters holding finished goods stock against point-of-sale replenishment triggers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial printing outsourcing sits at an inflection point where single-pass inkjet arrays are collapsing offset economics and forcing wholesale capacity reconfiguration across the installed base. EPA Clean Air Act enforcement and EU F-Gas Regulation are simultaneously raising compliance thresholds and creating technology substitution windows for prepared converters.
For Market Incumbents: Harden defensible positions by deepening captive finishing capabilities in Wisconsin and Illinois to anchor North American magazine volume against inkjet displacement. Accelerate water-based ink certification across European plant networks before REACH authorization requirements harden. Vertical integration into premedia software platforms locks in enterprise customer workflows and raises switching costs against cloud-native entrants.
For New Entrants and Emerging Players: India's Tamil Nadu corridor offers underpenetrated white space where BIS certification requirements have slowed multinational expansion and created captive demand for domestically certified technology providers. Target variable-data packaging for regional food and beverage brands seeking SKU proliferation without inventory risk. Lead with hybrid web-to-print platforms that integrate cloud design tools with distributed production scheduling, bypassing legacy MIS integration burdens that handicap incumbent responsiveness.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because single-pass inkjet capital requirements and regulatory compliance burdens are structurally incompatible with sub-scale operator economics. Acquisition targets should concentrate on regional scale operators with captive finishing and logistics integration in Germany, Japan, or India. Monitor inkjet printhead supply agreements as the critical signal: exclusive arrangements with Japanese precision manufacturers indicate sustainable competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Ink System Migration | EU F-Gas Regulation and EPA enforcement render solvent-based capacity obsolete for food-contact applications. |
| Single-Pass Inkjet Array Deployment | Eliminates makeready costs and enables economic production below fifty thousand copy thresholds. |
| Vendor-Managed Inventory Programs | Restructures converter revenue toward logistics services with point-of-sale replenishment in Germany and France. |
| BIS Certification Acceleration | India's mandatory safety testing creates captive demand for domestically certified premedia technology providers. |
| Hybrid Web-to-Print Platform Integration | Cloud-based design tools with production scheduling enable real-time job routing across distributed networks. |
Research Methodology
Initial hypotheses were tested against primary input from converter operations directors, retail procurement managers, premedia technology specialists, and regulatory compliance officers, then refined through secondary validation. Primary fieldwork encompassed plant visits in Gujarat, Wisconsin, and Bavaria alongside structured interviews with equipment vendors and ink formulation suppliers. Secondary sources included EPA enforcement records, ECHA REACH authorization databases, BIS certification registries, and trade flow data from customs authorities. Bottom-up capacity assessments triangulated against top-down demand modeling across service type, end user vertical, and technology platform dimensions.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across service type, end user vertical, product format, and technology platform dimensions. CAGRs were derived from run-length economics analysis, technology substitution curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated inkjet printhead deployment schedules, PLI scheme incentive disbursement timelines, and REACH authorization status for photoinitiator formulations.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese equipment vendors or accelerated single-pass inkjet adoption by magazine publishers would shift outcomes materially. Quarterly review of BIS certification approval rates, ECHA substance authorization decisions, and pulp futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Large Format Printer Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Global Web to Print Software Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Nordic Commercial Printing Market