
 Variable Data Printing Market | 2026-2036
Variable Data Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Data Printing Market Analysis
The capital-intensity gap between digital-native and legacy offset converters is collapsing as inkjet web presses reach cost parity at run lengths below five thousand impressions. HP Inc. leverages its PageWide inkjet architecture to anchor high-speed variable data jobs for direct mail and pharmaceutical inserts. Xerox Corporation sustains toner-based dominance in personalized business card and short-run marketing collateral workflows. Mondi competes through vertical integration from substrate manufacturing through finished label conversion, controlling fiber sourcing and coating specifications.
Variable data printing denotes a digital production method wherein each impression receives unique text, graphics, or codes from a database-driven raster image processor, typically operating at resolutions of 600 to 2400 dpi for barcode legibility and brand color fidelity. Its primary commercial purpose lies in enabling mass customization—serialized pharmaceutical labels, geographically targeted direct mail, and batch-specific packaging—without plate changes or press downtime. Inkjet printers lead volume shipments due to aqueous and UV-curable head advances that broaden substrate compatibility, while digital presses capture the highest margin pools in security-document and anti-counterfeiting applications where toner-based metallics and microtext dominate. Hybrid printers represent the fastest-growing product configuration as converters seek single-pass flexibility across rigid packaging films and folding cartons.
FDA serialization mandates under the Drug Supply Chain Security Act reshape pharmaceutical label demand by requiring unique product identifiers at the unit level. The EU F-Gas Regulation and REACH chemical restrictions constrain solvent-based ink formulations, pushing converters toward UV-curable and water-based systems certified under ECHA guidelines. Stakeholders must monitor how ISO 15415 barcode quality standards and emerging state-level packaging extended producer responsibility laws in California and New York alter equipment specification and ink chemistry roadmaps.
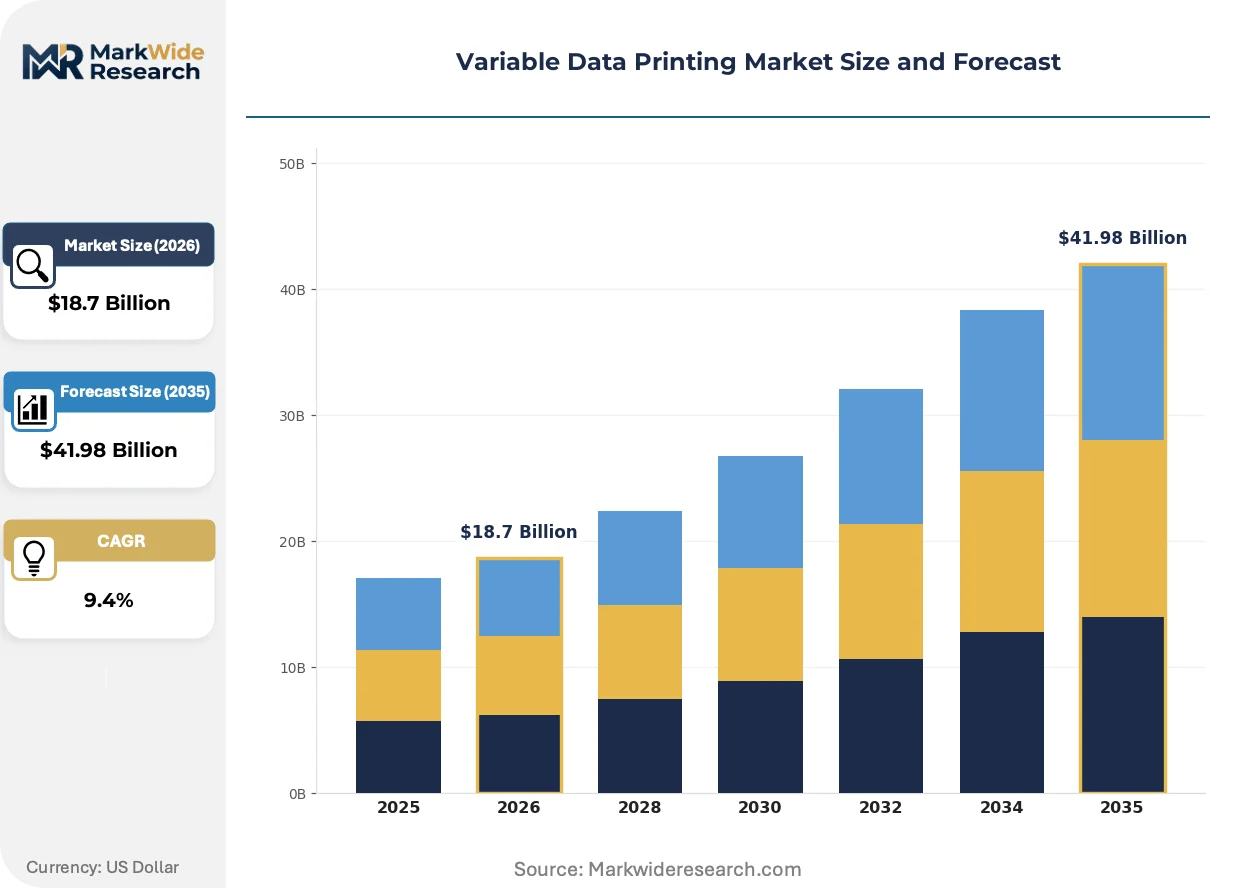
Market Dynamics
The collapse of the capital-intensity gap between digital-native and legacy offset converters now dominates competitive positioning, as inkjet web presses reach cost parity below five thousand impressions and force equipment replacement cycles across pharmaceutical packaging and direct mail verticals.
Growth Catalysts
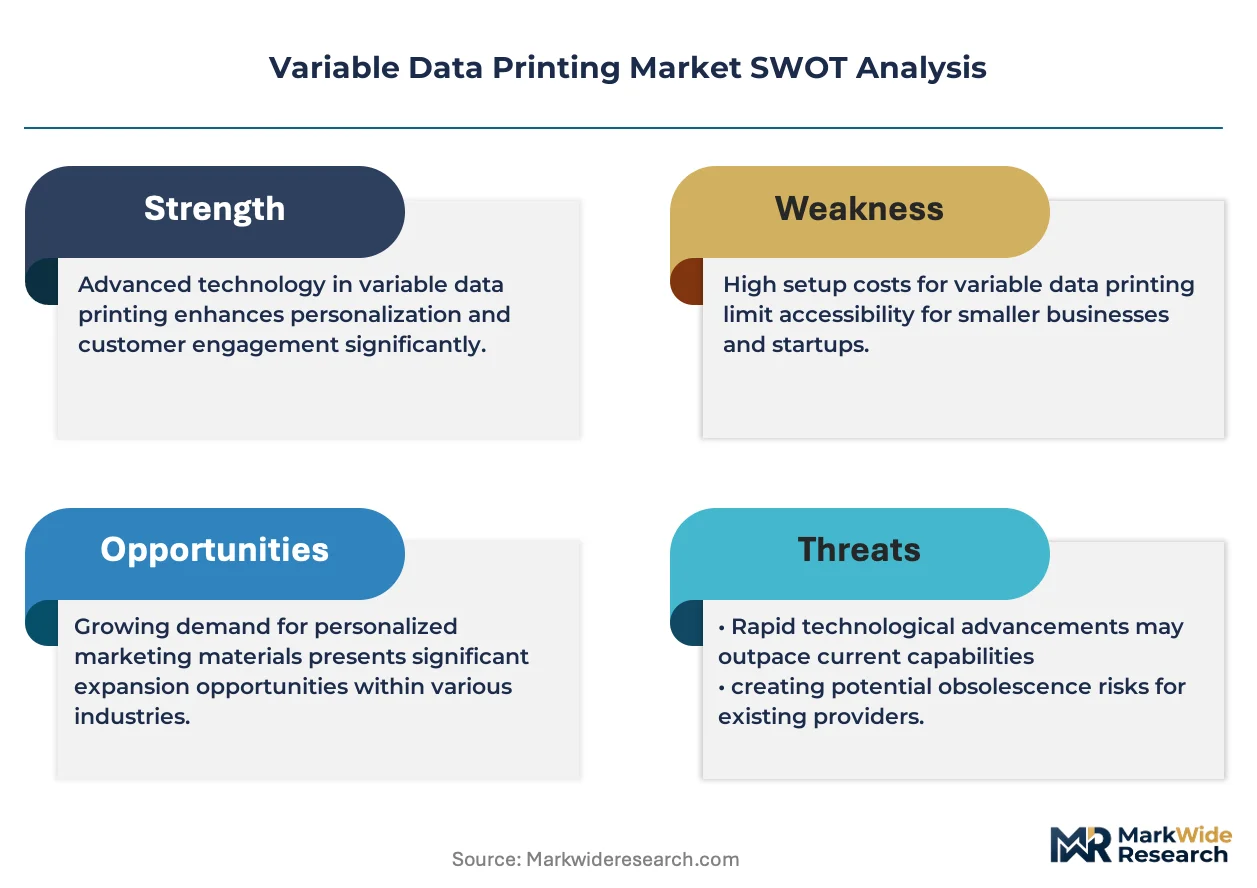
- FDA serialization mandates:The Drug Supply Chain Security Act requires unique product identifiers at the unit level, forcing pharmaceutical packaging lines to install variable data systems for track-and-trace compliance across United States distribution networks.
- EU F-Gas Regulation:REACH chemical restrictions and fluorinated gas phase-downs are constraining solvent-based ink formulations, pushing converters toward UV-curable and water-based systems certified under ECHA guidelines.
- Hybrid printer architecture:Single-pass flexibility across rigid packaging films and folding cartons is capturing converter investment as run lengths compress and SKU proliferation accelerates in food and cosmetics segments.
Market Restraints
- Substrate coating volatility:Specialized ink-receptive coatings for aqueous inkjet on non-porous films depend on petrochemical feedstocks subject to price swings, squeezing converter margins on short-run jobs.
- Head supplier concentration:Piezoelectric printhead manufacturing concentrates in Japanese and German precision engineering clusters, creating single-source vulnerability for high-resolution variable data modules.
- Legacy press stranded assets:Offset and flexo installations with remaining depreciation lifecycles block capital reallocation to digital, particularly among mid-tier packaging converters in mature European markets.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO alignment with FDA serialization standards creates demand for compliant variable data label capacity serving United States-bound generic drug shipments.
- Security-document applications:Toner-based metallics and microtext capabilities open high-margin pools in national ID cards, tax stamps, and certificate authentication where inkjet cannot replicate optical security features.
- Extended producer responsibility laws:California and New York state-level packaging EPR frameworks incentivize digital printing for versioning and localization that reduces obsolescence waste versus analog plate-based production.
Industry Challenges
- Raster image processor talent scarcity:Database-driven workflow architecture requires operators fluent in both color management science and SQL-level data handling, a hybrid skill set rarely cultivated in conventional pressroom training programs.
- ISO 15415 certification timelines:Barcode quality verification for pharmaceutical track-and-trace demands third-party validation cycles that delay job onboarding and compress effective equipment utilization rates.
- Legacy MIS integration friction:Existing print management information systems built for static job ticketing resist API-level connectivity to variable data engines, forcing expensive middleware development or manual workflow bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Data Printing Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Printers, Digital Presses, Hybrid Printers Application: Labels, Direct Mail, Packaging, Business Cards End User: Manufacturers, Retailers, Marketing Agencies, Publishers Technology: DOD, LDP, UV Printing, Toner-Based |
| Companies Covered | R.R. Donnelley & Sons Company, Mondi, HP Inc., Cenveo, Inc., Quad/Graphics Inc., Xerox Corporation, 3M Company, Avery Dennison Company, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Data Printing Market Emerging Trajectories
Digital production workflows are fragmenting the traditional converter value chain, dissolving the boundary between prepress, printing, and finishing as database-driven impression control becomes the central technical competency.
Inkjet technology is fragmenting the conventional analog press installed base. UV-curable and aqueous head advances now handle coated papers, synthetic films, and folding carton stocks previously reserved for offset. Pharmaceutical contract packagers in Germany and the United States are adopting single-pass inkjet for serialized leaflet insertion. This fragmentation is compressing the minimum efficient scale for variable data jobs and eroding the volume threshold that once protected analog equipment investments.
REACH chemical restrictions and the EU F-Gas Regulation are reshaping ink chemistry roadmaps. Solvent-based formulations face progressive phase-downs, forcing reformulation investment toward UV-curable and water-based alternatives. German and French converters are accelerating certification under ECHA guidelines to maintain pharmaceutical packaging access. The regulatory pressure falls heaviest on flexible packaging segments where solvent ink adhesion properties remain technically difficult to replicate.
Brand procurement teams are unbundling print specification from logistics execution. Pharmaceutical and consumer packaged goods buyers now separate creative versioning decisions from physical distribution contracts, inserting specialized variable data converters between brand marketing and fulfillment warehouses. This disintermediation is most advanced in United States direct mail and European e-commerce secondary packaging, where real-time personalization triggers require database connectivity that traditional print brokers cannot provide.
Variable Data Printing Market Segmentation
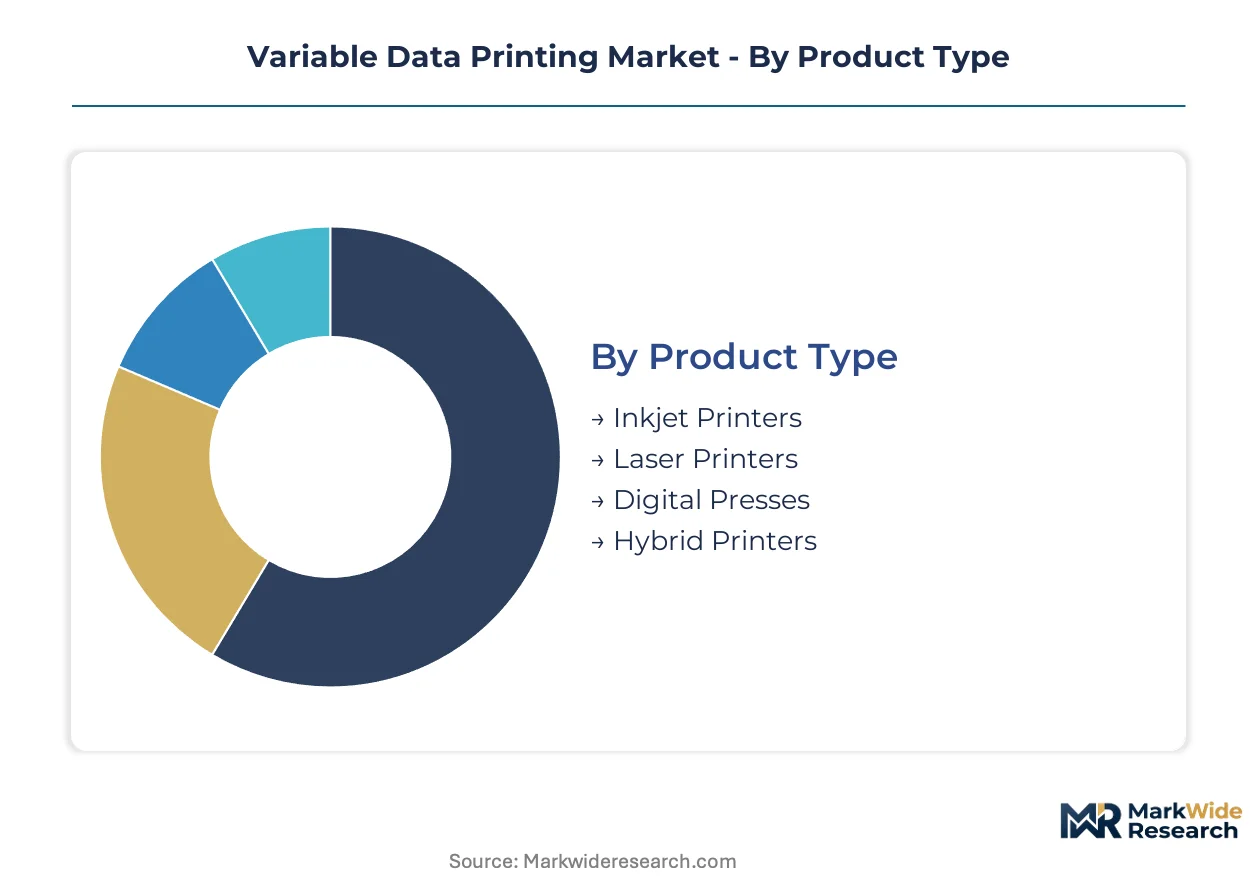
Variable data printing segments fragment along technology maturity curves, with substitution pressure from digital-native equipment reshaping legacy analog strongholds. Equipment type and application specificity determine margin capture, while end-user sophistication separates commodity transactional buyers from value-added service partners.
Product Type:
Inkjet architectures face accelerating substitution pressure from hybrid systems that merge single-pass speed with substrate versatility previously reserved for analog presses.
- Inkjet Printers:Aqueous and UV-curable piezoelectric heads operate at 600-2400 dpi resolutions, handling coated papers and synthetic films. Pharmaceutical contract packagers in Germany deploy these for serialized leaflet insertion where track-and-trace compliance mandates unit-level coding.
- Hybrid Printers:Single-pass configurations bridge rigid packaging films and folding cartons, capturing converter investment as SKU proliferation compresses run lengths. Food and cosmetics segments drive adoption where versioning flexibility outweighs analog unit economics.
- Laser Printers:Electrophotographic engines dominate personalized business card workflows and short-run marketing collateral with precise toner registration.
- Digital Presses:Toner-based metallics and microtext capabilities serve security-document applications where optical anti-counterfeiting features resist inkjet replication.
Inkjet printers retain volume leadership; hybrid printers hold the steepest expansion curve.
Application:
Application segmentation tracks how brand procurement teams unbundle creative versioning from physical logistics, inserting specialized converters between marketing and fulfillment.
- Labels:Pharmaceutical serialization under FDA Drug Supply Chain Security Act mandates unit-level identifiers, forcing packaging line retrofits. North American and European compliance deadlines concentrate demand for barcode-legible variable data systems.
- Packaging:E-commerce secondary packaging and food versioning require real-time database connectivity that traditional print brokers cannot provision. California and New York extended producer responsibility laws incentivize digital production to reduce obsolescence waste.
- Direct Mail:Geographically targeted campaigns leverage postal optimization algorithms tied to demographic databases.
- Business Cards:Personalized short-run production serves individual professionals and corporate identity refresh programs.
Labels command the largest installed base; packaging applications are climbing the fastest.
End User:
End-user categories separate buyers by workflow integration depth, from transactional print procurement to embedded database-driven production partnerships.
- Manufacturers:Pharmaceutical and consumer packaged goods producers internalize variable data capacity for batch-specific packaging and serialized compliance documentation. CDSCO alignment with FDA standards in India creates export packaging demand for United States-bound generic shipments.
- Marketing Agencies:Creative versioning decisions now separate from fulfillment execution, requiring API-level connectivity to variable data engines that legacy MIS systems resist.
- Retailers:Private label and promotional versioning drive seasonal campaign production with compressed lead times.
- Publishers:Academic and professional book segments adopt digital for print-on-demand and personalized content insertion.
Manufacturers dominate capital investment; marketing agencies show the sharpest adoption acceleration.
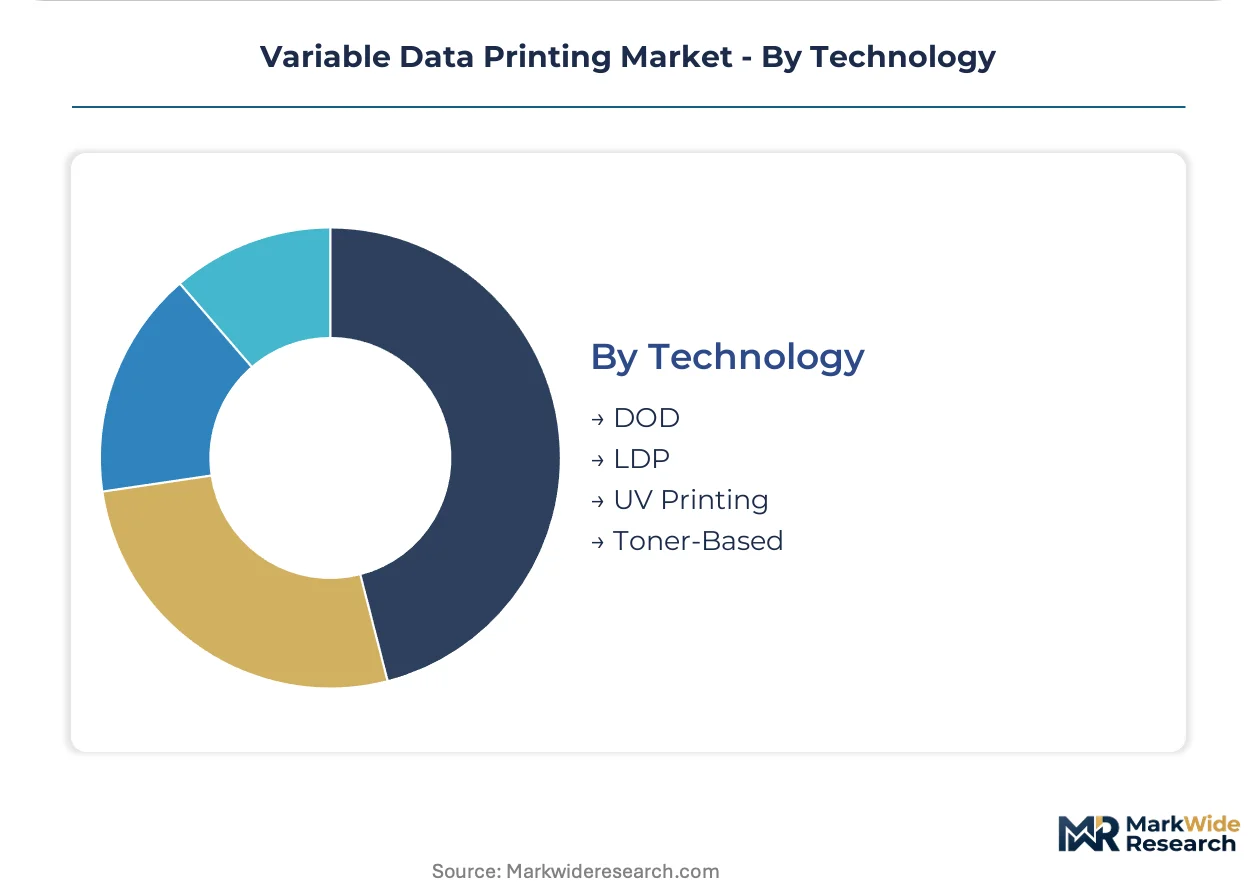
Technology:
Technology segmentation reflects chemistry roadmaps constrained by EU REACH and F-Gas Regulation phase-downs of solvent-based formulations.
- DOD:Drop-on-demand piezoelectric systems deliver precise droplet control for barcode quality under ISO 15415 standards. Japanese and German printhead manufacturing clusters concentrate supply, creating single-source vulnerability for high-resolution modules.
- UV Printing:Curable ink systems bypass substrate absorption limitations, enabling non-porous film handling where aqueous formulations fail. ECHA certification requirements in France and Germany filter market access for compliant converters.
- LDP:Liquid dry toner processes bridge electrophotographic precision with variable data throughput for security-document applications.
- Toner-Based:Conventional electrophotography sustains dominance in metallics and microtext where optical security features require particle-based deposition.
UV printing leads technology transition investment; DOD architectures maintain the broadest substrate penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Buyers in mature European markets exhibit high price sensitivity due to legacy press depreciation cycles, while pharmaceutical exporters in emerging economies absorb premium pricing for compliance-critical serialization capacity.
United States
FDA serialization mandates under the Drug Supply Chain Security Act drive pharmaceutical packaging line retrofits. Contract packagers in New Jersey and Pennsylvania invest in single-pass inkjet for serialized leaflet insertion. The FDA's unit-level tracking deadlines compress equipment procurement timelines across generic drug distribution networks.
Germany
REACH chemical restrictions and the EU F-Gas Regulation force solvent-to-UV ink formulation shifts. Converters in Baden-Württemberg accelerate ECHA certification to maintain pharmaceutical packaging access. Heidelberg and Stuttgart host precision engineering clusters supplying piezoelectric printhead modules.
India
CDSCO alignment with FDA standards creates export packaging demand for United States-bound generic shipments. Pharmaceutical manufacturers in Maharashtra and Gujarat deploy variable data systems for compliant label production. Mumbai-Pune corridor converters specialize in short-run serialization for contract research organizations.
Japan
PMDA track-and-trace requirements and METI industrial digitization programs shape equipment specifications. Precision engineering clusters in Nagoya and Osaka concentrate piezoelectric printhead manufacturing. Japanese head suppliers face capacity constraints as global converter demand accelerates.
France
ECHA enforcement of REACH chemical restrictions filters market access for compliant ink formulations. ANSM pharmaceutical serialization rules align with EU Falsified Medicines Directive implementation. Lyon and Paris basin converters serve cosmetics versioning demand where SKU proliferation compresses run lengths.
Variable Data Printing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with substrate manufacturers and digital press OEMs occupying distinct competitive positions. The capital-intensity gap between digital-native and legacy offset converters is collapsing, forcing equipment replacement cycles across pharmaceutical and direct mail verticals. Three archetypes dominate: vertically integrated substrate-to-label converters, digital press OEMs with proprietary head architectures, and specialized security-document printers with toner-based metallics expertise. Competitive moves concentrate on hybrid printer portfolio expansion and API-level workflow integration to capture marketing agency demand.
Within the integrated substrate tier, Mondi exemplifies backward integration from fiber sourcing through finished label conversion. Among digital press OEMs, HP Inc. and Xerox Corporation occupy positions anchoring divergent technology vectors—inkjet web speed versus toner-based precision. These three companies represent the structural fault lines between substrate control, hardware architecture, and output specialization that define competitive positioning.
| Leading Market Players |
|---|
| R.R. Donnelley & Sons Company |
| Mondi |
| HP Inc. |
| Cenveo, Inc. |
| Quad/Graphics Inc. |
| Xerox Corporation |
| 3M Company |
| Avery Dennison Company |
| Canon Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at piezoelectric printhead fabrication plants in Japan and Germany shapes both supply concentration and price floors for high-resolution variable data modules. Pharmaceutical contract packagers in the United States and Europe absorb premium pricing for FDA-compliant serialization systems while mid-tier converters in mature markets resist equipment upgrades due to legacy press depreciation cycles.
Pricing Analysis
After-sales revenue from printhead replacement cycles and extended service contracts drives lifetime value capture for digital press OEMs. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade systems with ISO 15415 barcode certification from general commercial print configurations. Cost compression in entry-level aqueous inkjet tiers is intensifying because Chinese equipment suppliers are expanding distribution through Southeast Asian converter networks. Brand-direct pharmaceutical manufacturers show least price sensitivity due to compliance-critical mandates, while commercial print brokers in European spot markets exhibit acute sensitivity to per-impression operating costs.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for UV-curable ink resin shipments originating from South Korean chemical manufacturers. Piezoelectric printhead production concentrates in Japan, Germany, and select precision engineering clusters in Switzerland. Raw material dependencies span silicon wafer substrates for MEMS fabrication, specialty ceramics for actuator components, and photoresist chemicals for nozzle patterning. Single-source vulnerability from Japanese head suppliers creates structural supply chain risk given capacity constraints at Nagoya and Osaka fabrication facilities. Distribution runs through OEM direct sales for pharmaceutical-grade systems and regional distributor networks for commercial print segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable data printing functions as a substitution defense market where incumbents must navigate displacement pressure from analog-to-digital conversion acceleration and emerging electrophotographic alternatives in security-document applications.
For Market Incumbents: Secure backward integration into substrate coating chemistry to control ink-receptive surface specifications for aqueous inkjet on non-porous films. Expand hybrid printer service capacity in the Mumbai-Pune corridor to capture Indian pharmaceutical export packaging demand driven by CDSCO-FDA alignment. Certification investment in ECHA-compliant UV formulations defends European market access against REACH regulatory enforcement. For New Entrants and Emerging Players: API-level workflow integration services represent a service-layer gap where legacy MIS vendors under-serve marketing agency demand for real-time database connectivity. Target California and New York extended producer responsibility compliance consulting as the most penetrable segment, pairing digital print versioning expertise with waste-reduction audit capabilities. Go-to-market angle centers on embedded production partnerships that unbundle creative versioning from fulfillment execution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized security-document printers with toner-based metallics capabilities that resist inkjet replication in national ID and tax stamp applications. Long-term viability rests on sustained regulatory tailwinds from pharmaceutical serialization mandates across multiple jurisdictions. Acquisition target archetype: regional converters with installed FDA-compliant capacity and established pharmaceutical contract packager relationships. Signal to watch: CDSCO enforcement intensity for United States-bound generic drug shipments as inflection indicator for Indian capacity demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Printer Portfolio Expansion | Captures food and cosmetics SKU proliferation where single-pass flexibility outweighs analog unit economics. |
| ECHA Certification Acceleration | Maintains pharmaceutical packaging access as EU REACH and F-Gas Regulation phase down solvent-based formulations. |
| API-Level Workflow Integration | Inserts specialized converters between brand marketing and fulfillment warehouses for real-time personalization triggers. |
| Indian Pharmaceutical Export Capacity | Serves CDSCO-aligned serialization demand for United States-bound generic drug shipments from Maharashtra and Gujarat. |
| Security-Document Metallics Investment | Opens high-margin pools in national ID cards where toner-based optical features resist inkjet replication. |
Methodological Framework
Cross-validation between primary interviews with converter operations managers and secondary validation through FDA Drug Supply Chain Security Act guidance documents anchors the qualitative findings. Pressroom supervisors at pharmaceutical contract packagers, digital press OEM product managers, ink formulation chemists at ECHA-certified facilities, and marketing agency production directors provided operational perspective. Secondary sources span SEC filings from publicly traded equipment manufacturers, ISO 15415 barcode quality standards documentation, and customs records for printhead import flows. Bottom-up equipment shipment tallies triangulate against top-down pharmaceutical packaging line retrofit estimates.
Sensitivity analysis around regulatory enforcement timelines and substrate coating petrochemical feedstock volatility shapes the analytical framework. Segmentation dimensions span equipment type, application specificity, end-user workflow integration depth, and ink chemistry certification tier across the projection horizon. CAGRs derive from equipment replacement cycle modeling tied to FDA and EU Falsified Medicines Directive compliance deadlines, with pharmaceutical serialization mandates and extended producer responsibility law adoption as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA serialization enforcement and EU REACH chemical restrictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Large Format Printer Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
ID Card Printers Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
Managed Print Services Market
Printing Technology
Printing Machinery Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Card Printers Market
Printing Technology
Global Microprinting Market
Printing Technology
Point of Sale (Pos) Printers Market