
 Laser Engraving Software Market | 2026-2036
Laser Engraving Software Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Engraving Software Market Insights
A capability gap between capital-heavy platform developers and lean open-source contributors is rotating competitive dynamics in laser engraving software. LightBurn leverages proprietary motion-control algorithms to command premium positioning among small-batch manufacturers. EzCAD sustains dominance in fiber-laser controller compatibility across Chinese and European industrial installations. CorelDRAW anchors its position through deep integration with legacy vector workflows in signage and personalization shops.
Laser engraving software constitutes programmable design-to-machine interfaces that translate vector or raster graphics into coordinated galvanometer or gantry motion commands, typically supporting pulse frequencies from 20 kHz to 4000 kHz and variable power modulation across CO2, fiber, and UV laser sources. The primary commercial purpose is to enable permanent, high-contrast marking on metals, polymers, wood, and ceramics for identification, decoration, or functional surface modification. Cloud-based deployment is gaining traction among distributed craft networks that prioritize collaborative file access over localized workstation control, while on-premise installations retain preference in defense and medical device facilities with air-gapped security protocols. Desktop software still occupies the largest revenue pool through perpetual licensing, though SaaS models are displacing upfront purchases among entry-level users.
FDA Unique Device Identification mandates shape demand for validation-ready engraving packages in medical device manufacturing, while EU Machinery Directive compliance requirements force software vendors to certify emergency-stop integration and interlock logic. ISO 11553 safety standards for laser processing machines further constrain market access for uncertified control platforms. Stakeholders must weigh perpetual-license defensibility against recurring-revenue scalability as deployment preferences fragment across security-sensitive and cost-sensitive buyer segments.
Market Dynamics
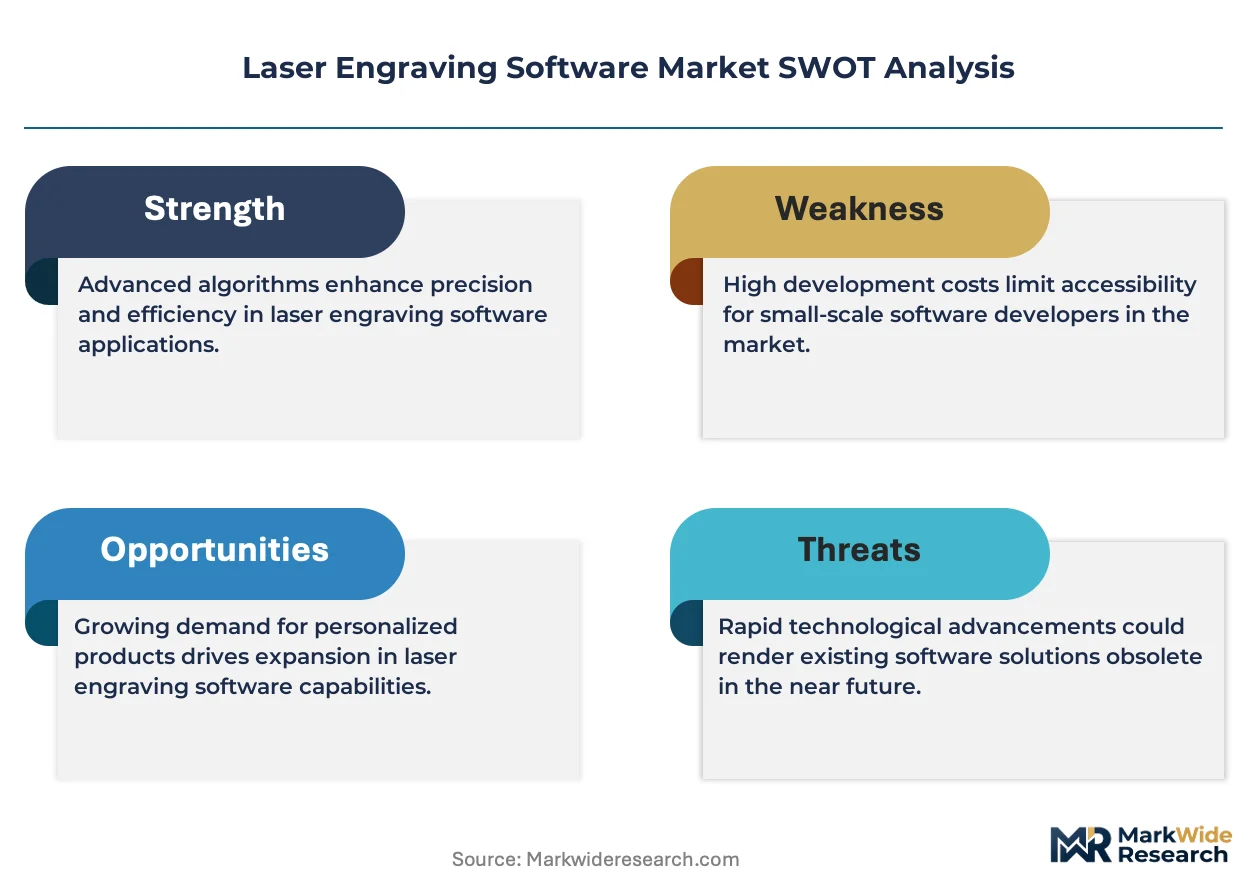
Perpetual-license defensibility is colliding with SaaS scalability as deployment preferences fracture across air-gapped defense facilities and cost-sensitive craft networks, forcing vendors to dual-track architecture investments without cannibalizing established revenue pools.
Growth Catalysts
- FDA Unique Device Identification:Serialized marking mandates for medical devices are pulling validation-ready engraving packages into sterile manufacturing environments across the United States.
- Cloud-based collaborative workflows:Distributed craft networks are displacing localized workstation control with browser-based file access and multi-user design pipelines.
- German precision manufacturing cluster:Concentrated demand for traceability-ready aerospace component marking is concentrating R&D investment in motion-control algorithm refinement.
Market Restraints
- ISO 11553 certification barriers:Uncertified control platforms face automatic exclusion from industrial procurement shortlists in safety-critical installations.
- Galvanometer controller supply concentration:Fiber-laser motion hardware sourcing remains bottlenecked through Shenzhen and Guangzhou manufacturing corridors.
- Legacy vector workflow lock-in:Signage and personalization shops face switching costs from decades of CorelDRAW-native file libraries and operator muscle memory.
Strategic Opportunities
- EU Machinery Directive emergency-stop integration:Certified interlock logic modules command premium positioning in European industrial safety audits.
- UV laser source convergence:Ceramic and polymer marking applications are opening as 355 nm sources merge with gantry motion platforms.
- Defense air-gapped installations:On-premise perpetual licensing retains pricing power in facilities with zero-cloud security protocols.
Industry Challenges
- Pulse-frequency calibration expertise:Qualified technicians who can tune 20 kHz to 4000 kHz ranges across CO2 and fiber sources remain scarce in secondary manufacturing hubs.
- Validation documentation timelines:Medical device manufacturers face 18-to-24-month software qualification cycles before production deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Engraving Software Market |
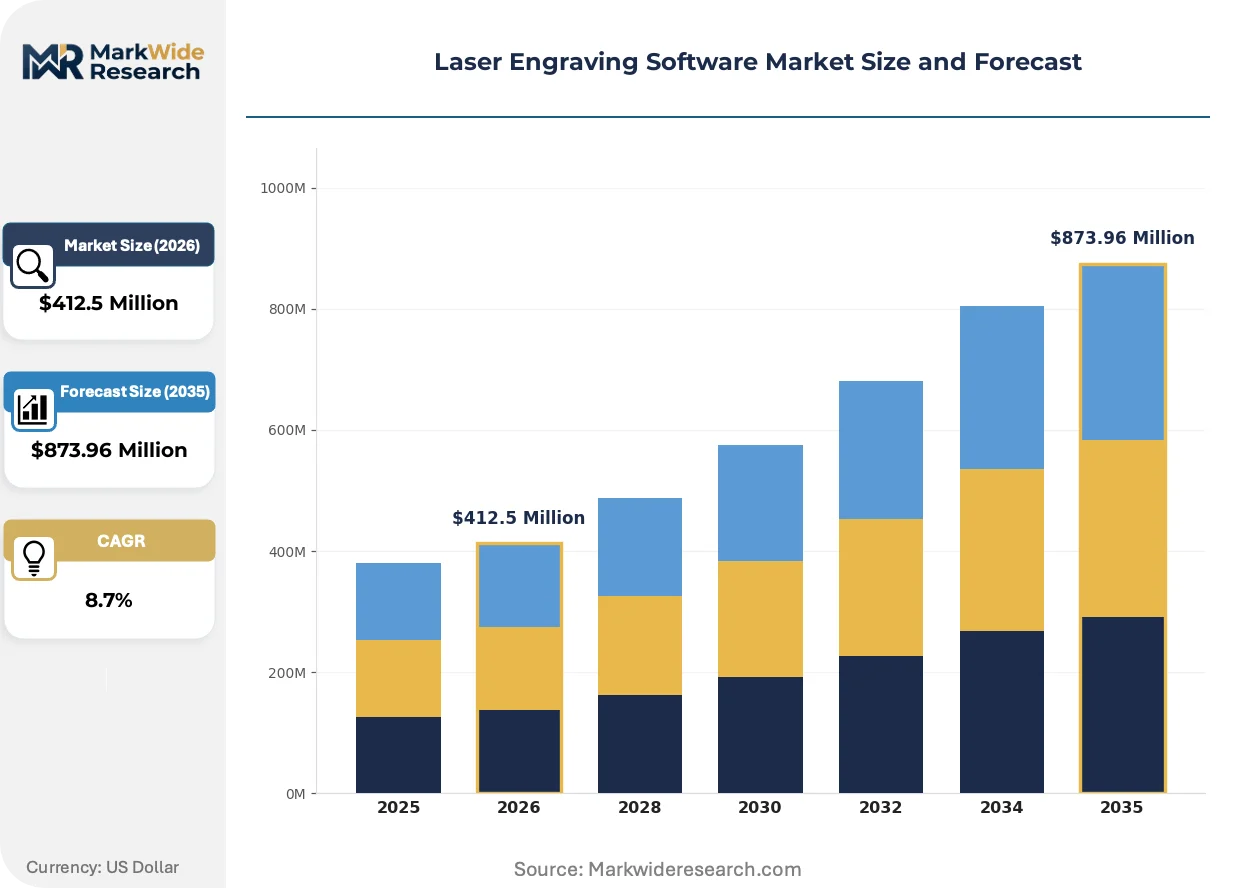
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Software, 3D Software, Cloud-Based Software, Desktop Software Application: Industrial Engraving, Artistic Engraving, Signage Making, Textile Engraving End User: Manufacturing, Retail, Automotive, Crafts Deployment: On-Premise, SaaS, Hybrid, Subscription |
| Companies Covered | LightBurn, Adobe Illustrator, CorelDRAW, Inkscape, EzCAD, RDWorks, LaserGRBL, DraftSight, Affinity Designer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Engraving Software Market Trends and Innovations
Real-time motion-path optimization is compressing job setup times while AI-assisted raster preprocessing is reducing material waste, together reshaping how operators balance throughput against consumable costs.
Adaptive power modulation algorithms are bifurcating the installed base between entry-level fixed-parameter machines and industrial systems with dynamic z-axis compensation. Small-batch manufacturers in North American job shops are upgrading controller firmware at accelerated cadences to access these features without full hardware replacement. This capability gap is compressing margins for mid-tier hardware vendors unable to license advanced motion libraries.
EU Machinery Directive 2006/42/EC amendments are mandating documented emergency-stop response times below 500 milliseconds for all new laser processing installations. German and Italian machine builders are pre-certifying software-hardware bundles to accelerate customer compliance audits. This regulatory friction is advantaging integrated platform vendors over pure-play software suppliers in European industrial tenders.
Subscription pricing is displacing perpetual licenses among entry-level users who prioritize predictable monthly outlays over capital expenditure approval cycles. Online craft marketplaces and maker-space networks are bundling cloud-based engraving software with material supply subscriptions. This preference shift is most visible in United States and United Kingdom personalization micro-businesses with sub-five-employee headcounts and minimal IT infrastructure.
Laser Engraving Software Market Segmentation
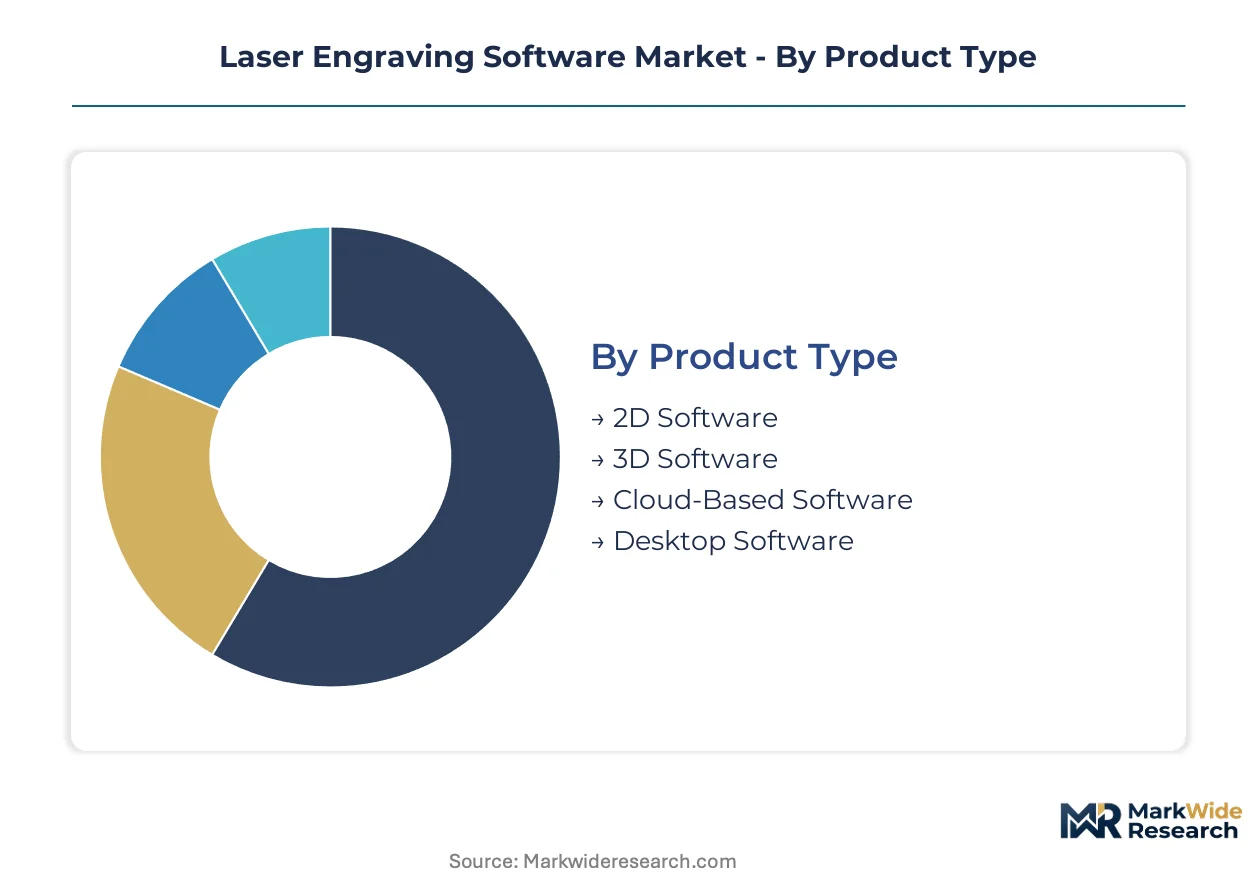
Segmentation in laser engraving software reveals how pulse-frequency capabilities, deployment security requirements, and end-use precision demands split purchasing decisions across fundamentally different buyer workflows. Understanding these divides explains why vendors maintain parallel licensing architectures rather than converging on single delivery models.
Product Type:
Geographic demand spread varies sharply across product categories, with desktop installations concentrating in domestic craft markets while cloud-based platforms serve export-oriented distributed networks.
- 2D Software:Vector-to-motion translation platforms dominate legacy installations with support for 20 kHz to 4000 kHz pulse frequencies across CO2 and fiber sources. Demand concentrates in German precision manufacturing clusters where aerospace component traceability mandates require validated planar marking sequences. FDA Unique Device Identification compliance drives medical device manufacturers toward 2D packages with documented qualification trails.
- 3D Software:Dynamic z-axis compensation algorithms enable contoured surface engraving on curved aerospace components and medical implants. Adoption clusters in North American job shops serving defense subcontractors with complex geometry requirements. The capability gap between fixed-parameter and adaptive systems is compressing margins for mid-tier hardware vendors.
- Cloud-Based Software:Browser-based file access serves distributed craft networks in United States and United Kingdom personalization micro-businesses.
- Desktop Software:Perpetual licensing retains preference in air-gapped defense and medical device facilities with zero-cloud security protocols.
Desktop software holds the largest share; momentum sits with cloud-based deployment.
Application:
Cost tier differentiation separates high-volume industrial engraving from low-margin artistic and craft applications, with pricing power correlating to validation documentation requirements.
- Industrial Engraving:Serialized marking for aerospace and medical devices demands ISO 11553-certified control platforms with interlock logic and emergency-stop integration. German and Italian machine builders pre-certify software-hardware bundles to accelerate EU Machinery Directive compliance audits. This regulatory friction advantages integrated platform vendors over pure-play software suppliers.
- Signage Making:Legacy vector workflow lock-in from decades of CorelDRAW-native file libraries creates switching costs for personalization shops. Operators resist retraining due to muscle memory embedded in established design-to-production pipelines.
- Artistic Engraving:Small-batch manufacturers upgrade controller firmware to access adaptive power modulation without full hardware replacement.
- Textile Engraving:UV laser source convergence at 355 nm opens ceramic and polymer marking applications on synthetic fabrics.
Industrial engraving commands premium positioning; artistic engraving expands most quickly among entry-level users.
End User:
Volume concentration in manufacturing contrasts with customer fragmentation across retail and craft segments, shaping divergent sales channel strategies.
- Manufacturing:Medical device producers face 18-to-24-month software qualification cycles before production deployment under FDA Unique Device Identification mandates. Validation-ready engraving packages pull specialized vendors into sterile manufacturing environments across the United States. Procurement shortlists automatically exclude uncertified control platforms.
- Automotive:Component traceability requirements mirror aerospace specifications with lower tolerance for validation documentation delays.
- Retail:Subscription pricing displaces perpetual licenses among sub-five-employee personalization micro-businesses with minimal IT infrastructure.
- Crafts:Online marketplaces and maker-space networks bundle cloud-based software with material supply subscriptions.
Manufacturing absorbs the highest absolute spending; retail shows the steepest expansion trajectory in user count.
Deployment:
Security sensitivity versus cost sensitivity fractures preferences between air-gapped facilities and collaborative networks, forcing dual-track architecture investments.
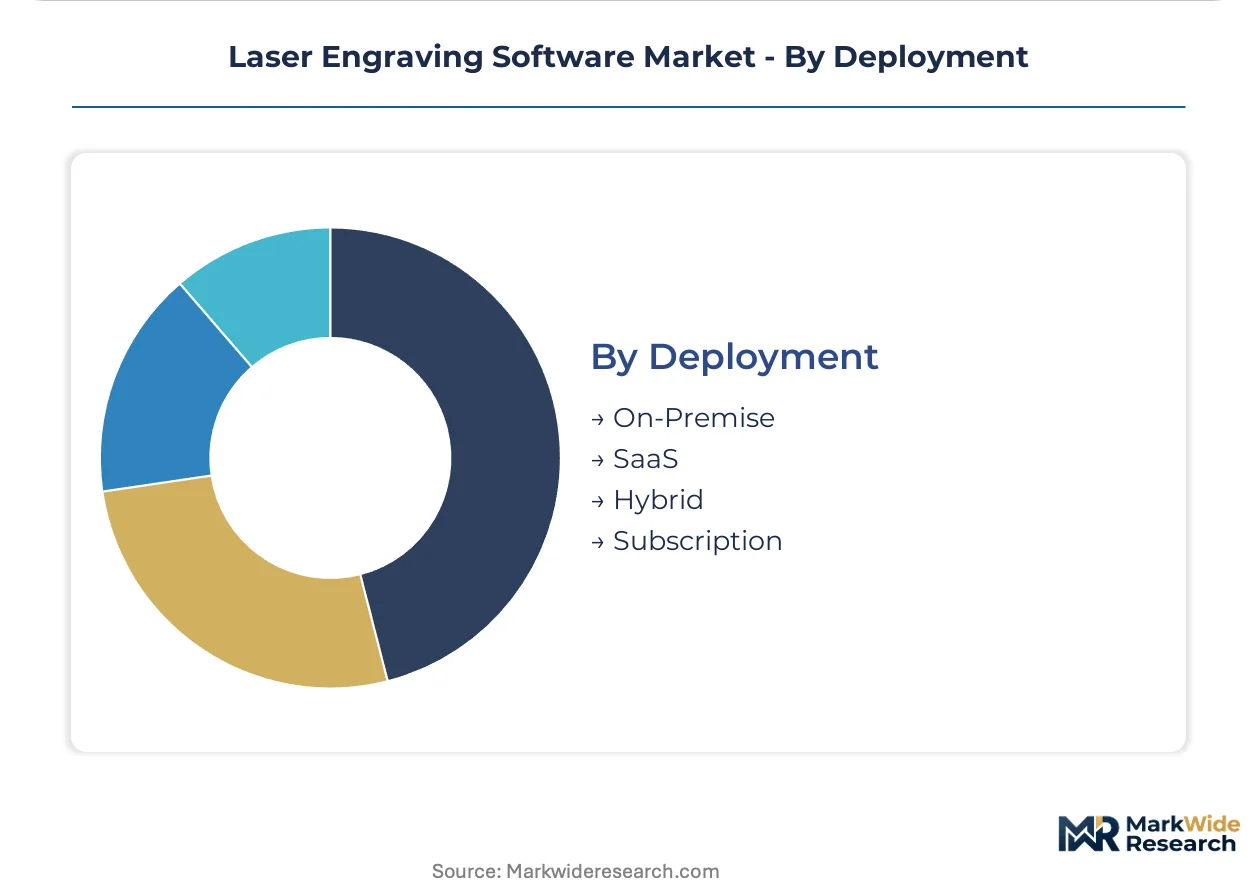
- On-Premise:Air-gapped installations in defense and medical device facilities retain pricing power for perpetual licensing with zero external connectivity. EU Machinery Directive amendments mandating documented emergency-stop response times below 500 milliseconds favor pre-certified on-premise bundles. Security protocols prohibit cloud dependency in these environments.
- SaaS:Predictable monthly outlays appeal to cost-sensitive craft networks avoiding capital expenditure approval cycles. Browser-based access enables multi-user design pipelines across distributed locations.
- Hybrid:Local processing with cloud backup serves mid-tier manufacturers balancing security and collaboration needs.
- Subscription:Entry-level users prioritize operational expenditure predictability over ownership.
On-premise deployment retains the largest revenue pool; SaaS models gain share fastest among new user acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in craft-oriented economies show acute price sensitivity to subscription tiers, while aerospace and medical device manufacturers in precision manufacturing clusters absorb premium perpetual-license costs without procurement friction.
United States
FDA Unique Device Identification mandates pull validation-ready engraving packages into sterile manufacturing environments across medical device production corridors. Defense subcontractors in Connecticut and Arizona maintain air-gapped installations with zero-cloud security protocols. The Greater Boston precision manufacturing cluster concentrates demand for serialized aerospace component marking.
Germany
EU Machinery Directive amendments mandating emergency-stop response times below 500 milliseconds favor pre-certified software-hardware bundles. Stuttgart and Munich aerospace suppliers drive adoption of traceability-ready engraving platforms with documented qualification trails. Baden-Württemberg machine builders anchor European industrial safety audit certification.
China
Fiber-laser controller compatibility requirements concentrate demand through Shenzhen and Guangzhou manufacturing corridors. Domestic medical device producers face accelerating traceability mandates from the national pharmaceutical regulator. The Yangtze River Delta precision electronics cluster absorbs high-volume industrial engraving installations.
United Kingdom
Subscription pricing displaces perpetual licenses among sub-five-employee personalization micro-businesses in London and Manchester craft networks. Cloud-based collaborative workflows gain traction through maker-space partnerships. Birmingham signage producers retain legacy vector workflow dependencies.
Japan
METI industrial safety standards constrain market access for uncertified control platforms in automotive component marking. Osaka and Nagoya precision manufacturers prioritize validated planar marking sequences for export certification. The Kanto region concentrates R&D investment in motion-control algorithm refinement.
Laser Engraving Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary motion-control developers commanding premium positioning while open-source contributors capture price-sensitive entry-level segments. The vendor base splits between integrated platform suppliers bundling hardware-software certification and pure-play software vendors licensing controller-agnostic packages. Three archetypes dominate: perpetual-license incumbents with decades of vector workflow entrenchment, SaaS-native challengers targeting craft networks, and industrial specialists pre-certifying compliance bundles. Competitive moves center on emergency-stop integration certification for EU tenders and firmware upgrade pathways that extend hardware lifecycles without full replacement.
Within the proprietary motion-control tier, LightBurn and EzCAD exemplify divergent geographic anchoring strategies. LightBurn occupies a position among North American small-batch manufacturers seeking premium positioning without enterprise-scale validation overhead. EzCAD sits within the fiber-laser controller compatibility segment serving Chinese and European industrial installations where hardware-software bundling accelerates procurement decisions. CorelDRAW anchors the legacy vector workflow tier through deep integration with established signage and personalization shop operations.
| Leading Market Players |
|---|
| LightBurn |
| Adobe Illustrator |
| CorelDRAW |
| Inkscape |
| EzCAD |
| RDWorks |
| LaserGRBL |
| DraftSight |
| Affinity Designer |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Shenzhen and Guangzhou galvanometer controller manufacturers lock in supply access and price visibility for industrial engraving platform vendors serving FDA-regulated medical device producers. These arrangements insulate certified software-hardware bundles from spot-market volatility while embedding emergency-stop response certification costs into fixed pricing structures.
Pricing Analysis
After-sales firmware upgrade revenue drives lifetime value for motion-control algorithm developers serving North American job shops. Three-tier pricing structure across validation-ready, professional-grade, and entry-level tiers separates FDA-compliant medical device packages from craft-market subscriptions. Cost compression in the mid-tier is intensifying because adaptive power modulation features are migrating downward from industrial systems. Retail personalization micro-businesses exhibit acute price sensitivity, while German aerospace suppliers absorb premium perpetual-license costs without procurement friction.
Supply Chain Analysis
Inventory lead times for fiber-laser galvanometer controllers extend through Shenzhen, Guangzhou, and Dongguan manufacturing corridors. Controller firmware draws from Taiwanese semiconductor foundries and Japanese precision optics suppliers. Single-source vulnerability concentrates in Shenzhen motion-hardware assembly where EU Machinery Directive certification documentation originates. Distribution runs through German and Italian machine builders who pre-certify software-hardware bundles for European industrial tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as defense and medical device capital expenditure cycles rebound from procurement freezes. Aerospace component traceability mandates are accelerating replacement demand for validated engraving platforms.
For Market Incumbents: Fortify perpetual-license defensibility by embedding ISO 11553-certified emergency-stop logic into controller firmware rather than external hardware modules. Deepen backward integration into galvanometer calibration services to capture aftermarket revenue from Chinese hardware installations. SaaS-native challengers threaten mid-tier positioning through subscription pricing that bypasses capital expenditure approval cycles.
For New Entrants and Emerging Players: Differentiate on UV laser source convergence at 355 nm for ceramic and polymer marking applications underserved by legacy CO2 and fiber platforms. Target United Kingdom personalization micro-businesses through maker-space partnerships that bundle cloud-based software with material supply subscriptions. Pursue white-label licensing to German machine builders seeking pre-certified software-hardware bundles for EU Machinery Directive compliance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native challengers serving distributed craft networks with predictable monthly outflows. Long-term viability favors vendors with dual-track architecture investments spanning air-gapped defense installations and cloud-based collaborative workflows. Acquisition candidates should demonstrate validated FDA Unique Device Identification compliance documentation. Monitor pulse-frequency calibration technician scarcity as an inflection indicator for aftermarket service pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Emergency-Stop Integration Certification | Pre-certified bundles accelerate EU Machinery Directive compliance audits for German machine builders. |
| Firmware Upgrade Pathway Development | Extends hardware lifecycles for North American job shops without full controller replacement. |
| UV Laser Source Platform Convergence | Opens ceramic and polymer marking applications for 355 nm gantry motion systems. |
| Cloud-Based Collaborative Workflow Launch | Serves United Kingdom personalization micro-businesses through browser-based multi-user pipelines. |
| Backward Integration into Calibration Services | Captures scarce technician expertise for 20 kHz to 4000 kHz pulse-frequency tuning. |
Research Methodology
Desk research of SEC filings from industrial software vendors, FDA Unique Device Identification guidance documents, and EU Machinery Directive amendment records preceded structured interviews with laser system integration engineers, medical device manufacturing quality directors, and German machine builder procurement heads. Primary fieldwork with North American job shop operators and United Kingdom craft network administrators validated secondary demand estimates. Bottom-up installation counts across deployment models triangulated against top-down vendor revenue disclosures.
Variance decomposition across product type, application, end user, and deployment segmentation dimensions shaped the analytical framework over the projection horizon. Modeled dimensions included 2D versus 3D motion-control capability, industrial versus artistic application workflows, manufacturing versus retail end-user concentration, and on-premise versus SaaS delivery architecture. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion constraints. Forecast inputs incorporated pulse-frequency specification migration timelines and EU regulatory certification backlog estimates.
Material uncertainties — supply chain disruption in Shenzhen manufacturing corridors, FDA enforcement intensity for medical device traceability, and technician training pipeline expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and hardware-software bundling preferences. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Decision Making Software Market
Software & Services
Europe Contract Lifecycle Management Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Transient Analysis Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Association Management Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Compensation Software Market
Software & Services
Server Operating System Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Manufacturing Quoting and Estimating Software Market
Software & Services
Account-Based Data Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Global Rapid Application Development Market
Software & Services
Construction Software As A Service Market