
 Digital Multimeter Market | 2026-2036
Digital Multimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Multimeter Market Intelligence
Silicon carbide is decoupling from traditional silicon-based measurement front-ends in premium multimeter architectures, reducing thermal drift and enabling higher-voltage industrial applications. Fluke Corporation leverages its captive calibration infrastructure to sustain North American service-channel dominance. Keysight Technologies anchors its position through precision bench-top instrumentation for semiconductor validation labs. Yokogawa Electric Corporation competes in process-industry segments where isolated-channel safety ratings command price premiums.
A digital multimeter is an electronic test instrument that measures voltage, current, and resistance with digitized signal processing, typically achieving resolution from 3½ to 8½ digits depending on architecture and cost tier. Industrial-grade units incorporate true-RMS conversion, CAT IV safety ratings, and data-logging memory for predictive maintenance workflows. Handheld units dominate volume shipments across field-service applications, while bench-top configurations capture margin concentration in R&D and calibration laboratories. Smart multimeters with Bluetooth and Wi-Fi connectivity are expanding fastest among industrial end users seeking cloud-integrated asset management.
IEC 61010 safety standards and FCC electromagnetic compatibility rules shape product certification timelines and geographic market access for instrument manufacturers. The EU AI Act and CE marking requirements increasingly influence smart-connected multimeter firmware validation and data-governance documentation. Stakeholders must monitor how evolving cybersecurity mandates for networked test equipment reshape firmware development costs and competitive positioning in connected instrument segments.
Market Dynamics
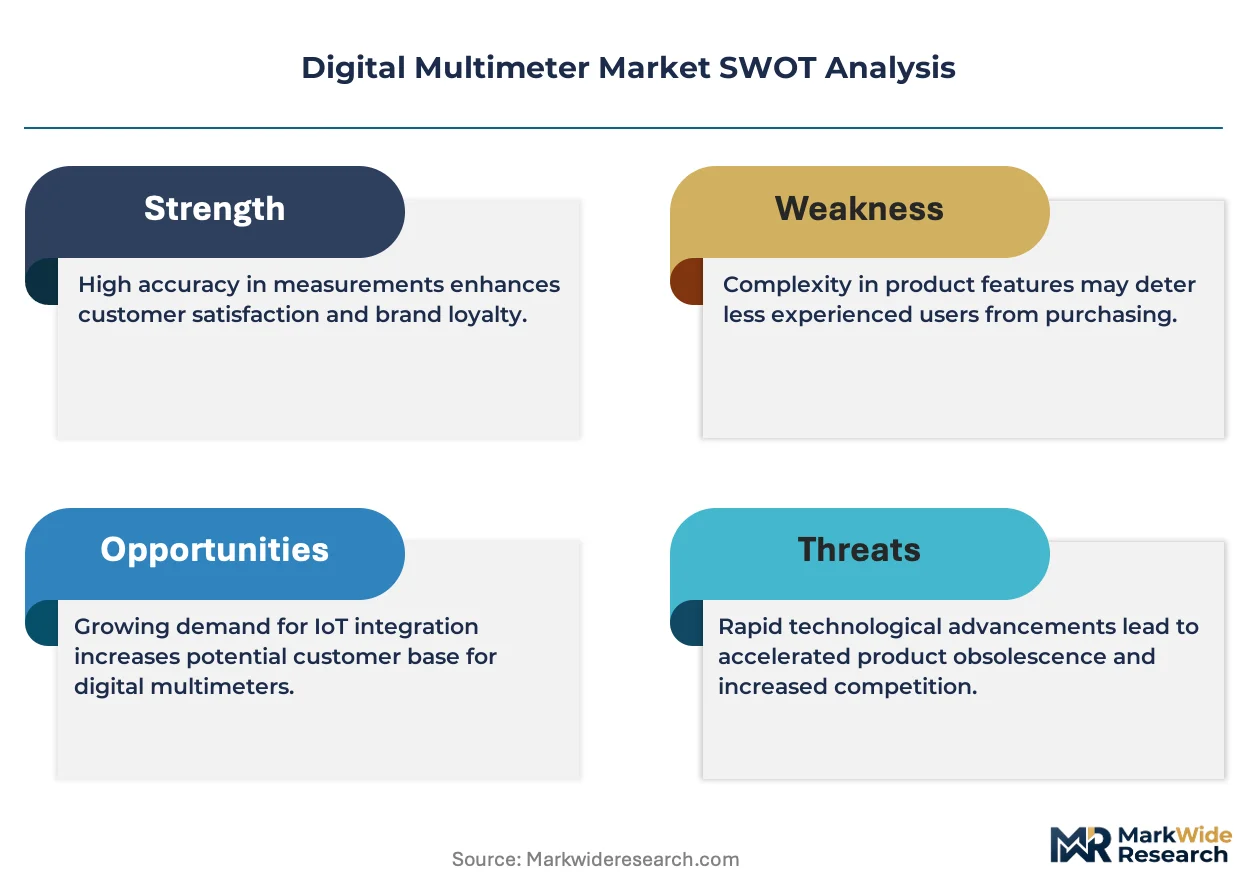
Silicon carbide front-end architectures are compressing thermal drift margins in industrial-grade instruments, forcing recalibration of competitive positioning around precision stability under high-voltage stress conditions.
Growth Catalysts
- Semiconductor fab expansion:South Korean fabs are scaling test-equipment procurement volumes as advanced node production multiplies electrical verification checkpoints across wafer processing lines.
- IEC 61010 certification tightening:Industrial safety standard revisions are accelerating replacement cycles for legacy instruments lacking CAT IV isolation ratings in high-energy electrical environments.
- Electronics assembly automation:East Asian manufacturing clusters are embedding precision multimeters directly into production-line quality gates for real-time electrical parameter verification.
Market Restraints
- Precision ADC supply concentration:High-resolution analog-to-digital converter fabrication concentrates among a limited supplier base, creating input cost volatility for 6½-digit and 7½-digit instrument tiers.
- Calibration infrastructure fragmentation:Third-party calibration laboratory density varies sharply by geography, extending total cost of ownership for distributed industrial fleets.
- Silicon carbide component cost premiums:Wide-bandgap semiconductors command material cost multiples over traditional silicon front-ends, compressing margin at mid-tier price points.
Strategic Opportunities
- Cloud-integrated asset management:Bluetooth and Wi-Fi connectivity modules are penetrating industrial maintenance workflows, enabling predictive calibration scheduling and fleet-wide traceability documentation.
- EU AI Act firmware compliance:Smart-connected instrument manufacturers can capture premium positioning through preemptive validation of data-governance documentation for networked test equipment.
- Process-industry isolated channels:Petrochemical and power generation segments command price premiums for multichannel instruments with reinforced isolation ratings in hazardous area classifications.
Industry Challenges
- Metrology talent scarcity:Precision instrument calibration and repair technician pipelines are thinning across North American and European service networks, extending field-response timelines.
- Cybersecurity firmware development:EU AI Act and emerging FCC guidance for networked industrial equipment are forcing firmware architecture redesigns, compressing product development cycles.
- Legacy system integration friction:Smart multimeter cloud platforms face interoperability barriers with entrenched enterprise asset management systems in heavy industrial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Multimeter Market |
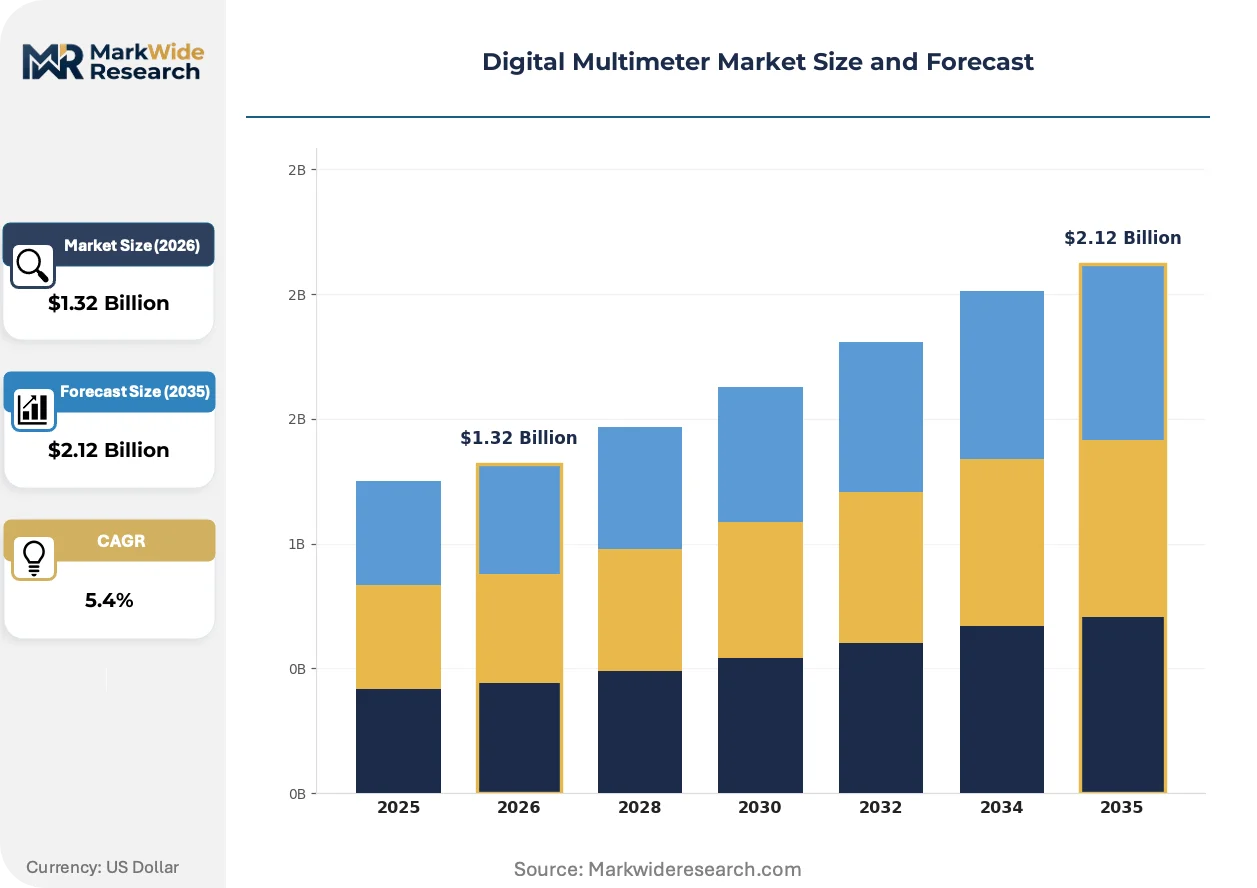
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Bench-Top, Wireless, Automotive Technology: Analog, Digital, Smart, Hybrid End User: Industrial, Educational, Healthcare, DIY Connectivity: USB, Bluetooth, Wi-Fi, Others |
| Companies Covered | Fluke Corporation, Keysight Technologies, Tektronix, Yokogawa Electric Corporation, Gossen Metrawatt, National Instruments, Hioki E.E. Corporation, Rohde & Schwarz, B&K Precision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Multimeter Market Strategic Shifts & Innovations
Measurement front-ends are migrating toward wide-bandgap semiconductors while connectivity modules rewrite service-model economics across industrial maintenance operations.
Silicon carbide transistors are expanding into high-voltage industrial multimeter architectures, replacing traditional silicon junctions in input protection circuits. Power generation and electric vehicle test facilities are adopting these front-ends fastest, prioritizing thermal stability under sustained 1000V+ measurement loads. The technology is expanding into premium instrument tiers, compressing the performance gap between laboratory-grade and field-service units.
The EU AI Act is imposing firmware validation documentation requirements on smart-connected multimeters with data-logging and cloud transmission capabilities. Industrial end users in Germany and France are now demanding supplier-provided conformity assessments before fleet procurement approvals. Bench-top instrument segments serving semiconductor validation labs face the steepest compliance cost escalations.
Buyer preference is rotating toward subscription-calibration bundles that unbundle hardware acquisition from ongoing metrology traceability. Industrial maintenance departments in US manufacturing facilities are displacing transactional calibration purchases with multi-year service agreements tied to cloud-based asset tracking. Channel partners in Texas and Michigan industrial corridors report fastest uptake of this consumption-model shift.
Digital Multimeter Market Segmentation
Digital multimeter segmentation reveals how certification burdens, connectivity requirements, and precision tiers fragment procurement patterns across industrial maintenance, semiconductor validation, and field-service workflows. Understanding these divides exposes where margin concentrates versus where volume ships.
Product Type:
Handheld units face CAT III/CAT IV IEC 61010 certification thresholds for industrial field deployment, while bench-top instruments trigger FCC electromagnetic compliance for laboratory environments. Automotive variants require additional ISO 7637-2 immunity validation for vehicle electrical system testing.
- Handheld:Portable battery-powered units with 3½ to 4½ digit resolution dominate electrical contractor field kits and plant maintenance belts. Demand clusters in Texas and Michigan industrial corridors where technicians prioritize ruggedized CAT IV safety ratings for energized circuit verification.
- Bench-Top:Laboratory-grade instruments achieve 6½ to 8½ digit precision through precision ADC architectures and temperature-controlled references. Semiconductor fabs in South Korea anchor procurement volumes for wafer-level electrical characterization requiring traceable calibration chains.
- Wireless:Bluetooth-equipped units transmit logged readings to cloud asset platforms, triggering EU AI Act documentation requirements for data governance in German and French industrial fleets.
- Automotive:Specialized units incorporate milli-ohm measurement ranges and pulse-width modulation analysis for electric vehicle battery pack diagnostics and charging system validation.
Handheld units sit at the top of the volume ranking, with wireless configurations climbing the fastest as cloud-integrated maintenance workflows displace paper-based logging.
Technology:
Technology tiers separate by signal processing architecture and intelligence integration, with cost structures scaling from basic analog conversion to firmware-heavy smart platforms.
- Analog:Legacy needle-movement instruments persist in educational laboratories and budget-constrained developing-market maintenance operations where digital literacy gaps slow instrument turnover.
- Digital:Standard digitized measurement with LCD readouts captures the mid-tier industrial bulk, balancing precision against total cost of ownership in distributed fleet deployments.
- Smart:ARM-processor-based instruments run embedded diagnostic algorithms and touchscreen interfaces, commanding price premiums in predictive maintenance applications where edge analytics reduce cloud dependency.
- Hybrid:Dual-mode architectures switch between high-speed analog tracking and precision digital sampling, serving power electronics development labs in Japan where METI-funded research programs drive instrument sophistication.
Digital platforms anchor current revenue concentration, though smart instruments are gaining share fastest as firmware capabilities displace standalone data loggers.
End User:
End-user categories fragment by precision requirements, safety criticality, and total cost of ownership sensitivity across institutional procurement frameworks.
- Industrial:Manufacturing maintenance departments demand CAT IV isolation, true-RMS conversion, and data-logging memory for compliance documentation. South Korean electronics assembly clusters embed multimeters directly into automated quality gates for real-time parameter verification.
- Educational:Universities and technical colleges prioritize durability and intuitive interfaces over precision, with procurement concentrated in India where BIS certification requirements shape vendor qualification.
- Healthcare:Biomedical engineering departments require isolated inputs and leakage current measurement modes for patient-connected equipment safety testing in hospital maintenance programs.
- DIY:Consumer-grade units with basic voltage and continuity functions serve residential electrical work and hobbyist electronics, competing primarily on retail price point and brand recognition.
Industrial end users command the steepest price premiums, with healthcare applications expanding most quickly as hospital infrastructure modernization accelerates electrical safety audit frequencies.
Connectivity:
Interface options determine integration friction with enterprise asset management systems and expose manufacturers to evolving cybersecurity compliance burdens.
- USB:Tethered data transfer remains standard for calibration laboratory workflows where EMI isolation and deterministic timing outweigh convenience priorities.
- Bluetooth:Short-range wireless enables tablet-tethered field diagnostics without Wi-Fi infrastructure dependency, penetrating utility and telecommunications maintenance fleets fastest.
- Wi-Fi:Direct cloud connectivity triggers the most stringent EU AI Act firmware validation requirements, with German industrial buyers now demanding supplier-provided conformity assessments.
- Others:NFC and proprietary radio protocols serve niche applications including hazardous area classifications where intrinsic safety ratings limit standard radio module deployment.
USB retains the largest installed base, with Wi-Fi modules showing the steepest expansion trajectory as cloud-native asset management platforms displace on-premise maintenance software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters anchor procurement volumes for precision electrical verification instruments, with semiconductor fabs and electronics assembly automation driving regional differentiation across certification standards and connectivity requirements.
United States
Industrial maintenance departments in Texas and Michigan industrial corridors prioritize ruggedized CAT IV safety ratings for energized circuit verification. FCC electromagnetic compatibility rules shape product certification timelines for laboratory-grade instruments. Greater Boston anchors precision instrument R&D concentration where calibration infrastructure sustains North American service-channel positioning.
Germany
Industrial end users demand supplier-provided conformity assessments for smart-connected multimeters under EU AI Act data-governance documentation. REACH and RoHS directives constrain material composition in instrument housings and circuit assemblies. The Ruhr industrial belt embeds precision multimeters into automated quality gates for real-time electrical parameter verification.
South Korea
Semiconductor fabs scale test-equipment procurement volumes as advanced node production multiplies electrical verification checkpoints across wafer processing lines. MFDS-equivalent industrial safety frameworks align with IEC 61010 certification tightening for high-energy electrical environments. The Seoul Capital Area concentrates electronics assembly automation requiring precision electrical verification at production-line quality gates.
Japan
METI-funded research programs drive instrument sophistication in power electronics development labs requiring dual-mode measurement architectures. JIS standards complement IEC frameworks for industrial-grade safety ratings. The Chubu region around Nagoya anchors automotive testing concentration where specialized multimeters incorporate milli-ohm measurement ranges for electric vehicle battery pack diagnostics.
India
Technical colleges and universities prioritize durability and intuitive interfaces over precision in procurement decisions for educational laboratories. BIS certification requirements shape vendor qualification pathways for domestic distribution. Maharashtra industrial corridors expand electronics manufacturing capacity where embedded quality verification systems demand mid-tier digital multimeter deployment.
Digital Multimeter Market Key Industry Players
Global majors compete with regional champions across calibration infrastructure and connectivity integration, producing a tiered structure where precision bench-top specialists, field-service ruggedization leaders, and smart-connected platform builders occupy distinct competitive spaces. Strategic archetypes separate around captive calibration networks, silicon carbide front-end integration, and cloud-native asset management capabilities. M&A activity concentrates on connectivity module suppliers and metrology software platforms, while geographic expansion targets South Korean semiconductor fab corridors and German industrial maintenance fleets.
Among precision instrumentation specialists, Fluke Corporation, Keysight Technologies, and Yokogawa Electric Corporation exemplify three competitive anchors. Fluke represents the field-service ruggedization archetype with North American calibration infrastructure dominance. Keysight occupies the semiconductor validation lab tier where precision bench-top instrumentation commands margin concentration. Yokogawa sits within process-industry segments where isolated-channel safety ratings extract price premiums in petrochemical and power generation hazardous area classifications.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Tektronix |
| Yokogawa Electric Corporation |
| Gossen Metrawatt |
| National Instruments |
| Hioki E.E. Corporation |
| Rohde & Schwarz |
| B&K Precision |
| Others |
Cost & Logistics Intelligence
Captive calibration infrastructure anchors pricing power for incumbent instrument manufacturers, creating defensive moats that resist margin erosion even as silicon carbide front-end costs escalate. This integration choice sustains premium positioning in North American service channels where third-party laboratory density remains fragmented.
Pricing Analysis
Input-cost pass-through from precision ADC suppliers and wide-bandgap semiconductor vendors shapes tiered pricing across instrument categories. Three-tier pricing structure across premium, standard, and economy levels separates laboratory-grade bench units with 8½-digit resolution from field-service handhelds and educational entry models. Price differentiation rests on CAT IV safety certification attainment and embedded connectivity modules. Cost compression in mid-tier digital segments is intensifying because silicon carbide component premiums compress assembler margins. Educational buyers in India exhibit highest price sensitivity, while semiconductor validation labs in South Korea absorb premium pricing for traceable calibration chains.
Supply Chain Analysis
Reverse-logistics flows for recalibration and refurbishment extend instrument lifecycles, with Fluke Corporation and Keysight Technologies operating captive North American facilities that reduce replacement velocity. Component sourcing concentrates in Taiwan for precision ADC fabrication, South Korea for advanced semiconductor test equipment, and Japan for high-stability reference components. Raw material dependencies span silicon carbide substrates, precision resistors, and lithium-ion battery cells for handheld units. Single-source vulnerability in 6½-digit and 7½-digit ADC supply creates procurement risk for premium instrument tiers. Distribution runs through authorized industrial distributors in Texas and Michigan corridors, direct OEM relationships with South Korean fabs, and educational procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital multimeter market functions as a stable compounder where electronics assembly automation sustains replacement-cycle visibility and calibration-service recurring revenue.
For Market Incumbents: Cement North American calibration infrastructure dominance through service-network densification in Michigan and Texas industrial corridors. Defend against silicon carbide front-end cost escalation by backward integration into wide-bandgap component sourcing or long-term supply agreements with South Korean semiconductor vendors. Prioritize EU AI Act firmware compliance investment to capture German and French industrial fleet procurement. For New Entrants and Emerging Players: EU AI Act data-governance requirements in Germany and France open a window for cloud-native asset management platforms that preemptively validate conformity documentation. Target wireless connectivity modules for industrial maintenance fleets where incumbent firmware architectures lag compliance timelines. Pursue white-label partnerships with South Korean electronics assembly automation integrators seeking embedded quality verification systems. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration infrastructure fragmentation extends total cost of ownership for distributed industrial fleets. Long-term viability favors precision instrument specialists with captive metrology networks and semiconductor validation lab relationships. Acquisition target archetype: regional champions in process-industry isolated-channel segments with petrochemical and power generation customer concentration. Monitor IEC 61010 certification revision timing as inflection indicator for replacement-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Captive service networks in Texas and Michigan corridors defend recurring revenue against third-party laboratory competition. |
| Silicon Carbide Front-End Integration | Wide-bandgap semiconductor adoption in premium tiers reduces thermal drift under 1000V+ industrial measurement loads. |
| EU AI Act Firmware Compliance | Preemptive data-governance documentation unlocks German and French industrial fleet procurement approvals. |
| Cloud-Native Asset Management Platform | Bluetooth and Wi-Fi connectivity modules enable predictive calibration scheduling for distributed maintenance operations. |
| Process-Industry Isolated Channel Development | Reinforced isolation ratings command price premiums in petrochemical and power generation hazardous area classifications. |
Research Approach
Coverage spans North America, Europe, and East Asia, with primary inputs from each region combined with secondary validation. Primary interviews engaged maintenance directors at Texas and Michigan manufacturing facilities, calibration laboratory operators, South Korean semiconductor fab equipment procurement teams, German industrial automation integrators, and Japanese power electronics research program administrators. Secondary sources incorporated IEC 61010 certification databases, FCC electromagnetic compatibility filings, EU AI Act regulatory guidance documents, and trade flow data for precision instrument categories. Bottom-up triangulation across product-type shipments and top-down cross-check against end-user industry expenditure patterns anchored value estimates.
Rate-of-change decomposition across the analysis window isolated volume drivers from price-mix effects in handheld, bench-top, wireless, and automotive product categories. Segmentation dimensions modeled include product type, technology tier, end-user industry, and connectivity interface. CAGR derivation incorporated semiconductor fab capital expenditure cycles, IEC certification replacement timelines, and cloud-integrated maintenance workflow adoption curves. Industry-specific forecast inputs encompassed South Korean electronics assembly automation deployment rates and German industrial fleet connectivity upgrade patterns.
Revisions become necessary when IEC 61010 certification timelines accelerate, silicon carbide component supply disruptions materialize, or EU AI Act enforcement interpretations shift. Forecasts reflect assumptions regarding calibration infrastructure stability and semiconductor capital expenditure continuity. Practitioners should monitor South Korean fab equipment procurement announcements and German conformity assessment demand for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
LCR Meter Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Compression Testing Machines Market
Test and Measurement
AI-Enabled Testing Tools Market