
 Ultrasonic Testing Equipment Market | 2026-2036
Ultrasonic Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Testing Equipment Market Intelligence
The divergence between advanced, software-driven phased array systems and lower-cost, single-function portable flaw detectors is restructuring the market. High-end demand centers on integrated solutions for complex inspections in aerospace and energy. EVIDENT leverages its legacy in precision optics and electronics to offer sophisticated imaging capabilities. Eddyfi Technologies specializes in advanced NDT solutions for critical industrial assets, while Sonatest competes by providing rugged, field-ready portable devices for conventional UT applications.
Ultrasonic testing equipment comprises instruments that generate and receive high-frequency sound waves, typically in the 0.1 to 25 MHz range, to evaluate material properties. Its primary purpose is non-destructive detection of internal flaws, measurement of thickness, and characterization of materials. Phased Array Devices represent the fastest-growing product category due to their speed and imaging capabilities. Demand from aerospace manufacturers and power plants continues to dominate end-user segments, driving requirements for both portable and automated systems.
Asset integrity management is governed by stringent standards, including ISO 9712 for personnel qualification and specific industry codes from ASME in the United States and EN standards in Europe. These regulations mandate periodic inspections, directly shaping equipment demand and technician certification requirements. The critical decision for equipment suppliers now involves balancing investment in advanced software for data analytics against the need for cost-effective, easy-to-use hardware for field technicians.
Market Dynamics
The ultrasonic testing equipment market is bifurcating along a technological and cost axis, driven by the dual needs for advanced, software-integrated systems and basic, ruggedized field units. This split between complex Phased Array UT for aerospace and energy versus conventional flaw detectors for general industry defines current investment and product development trajectories.
Growth Catalysts
- Personnel Certification Mandates:International standards like ISO 9712 and parallel national schemes mandate formal qualification for NDT technicians, which directly sustains demand for training and operational equipment for a certified workforce.
- Infrastructure Investment in China:Expansive public works projects in China, particularly in high-speed rail and nuclear power generation, necessitate extensive ultrasonic inspection to ensure the integrity of critical welds and materials.
- Composite Material Use:The expanding use of carbon fiber reinforced polymers and other composites in aerospace structures requires advanced ultrasonic techniques to detect delaminations and internal defects not visible with other methods.
Market Restraints
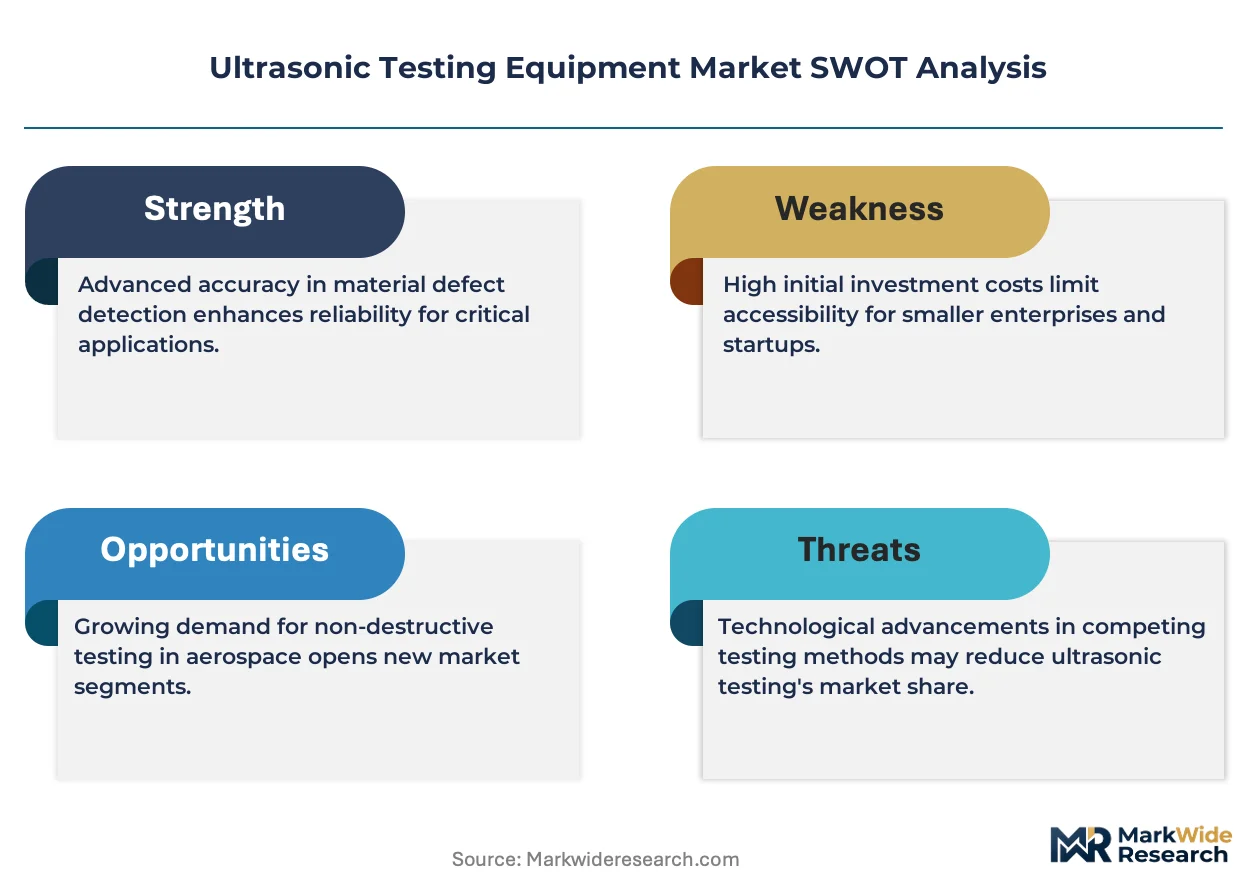
- High Capital Expenditure:The significant upfront investment required for advanced phased array and TFM/FMC systems acts as a barrier to entry for smaller inspection service companies and in-house quality control departments.
- Technical Complexity:Interpreting the complex data sets generated by advanced ultrasonic techniques demands a high level of operator skill and training, creating a bottleneck that limits widespread deployment.
- Alternative NDT Methods:In certain applications, particularly for surface or near-surface flaw detection, alternative methods like Eddy Current Testing or Magnetic Particle Inspection offer a more cost-effective or faster solution.
Strategic Opportunities
- Additive Manufacturing Inspection:The growth of 3D-printed metal parts in aerospace and medical implants creates a new opportunity for UT to validate internal structural integrity and detect process-induced flaws.
- AI and Data Analytics Integration:There is a significant opportunity to embed AI and machine learning algorithms into UT software to automate flaw recognition, predict component failure, and streamline reporting.
- Power Sector Modernization:Modernizing aging power grids and extending the life of existing power plants in regions like North America and Europe presents an opportunity for advanced UT in asset integrity management programs.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of Level II and Level III certified UT technicians constrains the ability of service providers to meet inspection demand, particularly for specialized techniques like phased array.
- Data Standardization:The lack of common data formats among equipment from different manufacturers complicates the ability of asset owners to create unified inspection databases and perform fleet-wide analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Testing Equipment Market |
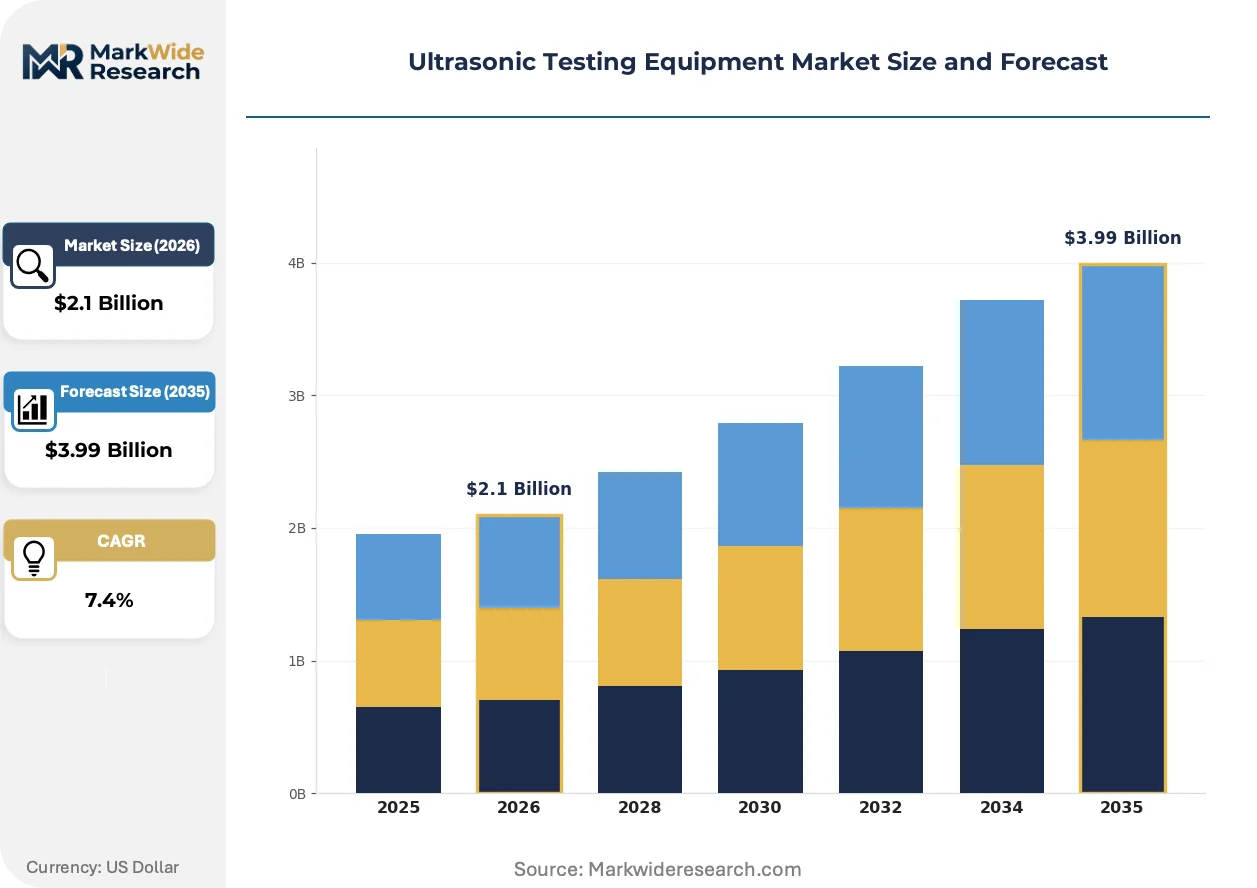
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Instruments, Conventional Systems, Phased Array Devices, Electromagnetic Acoustic Transducers Technology: Pulse-Echo, Through Transmission, Time-of-Flight Diffraction, Phased Array, Resonance Testing Application: Weld Inspection, Corrosion Analysis, Thickness Measurement, Flaw Detection, Bond Evaluation End User: Aerospace Manufacturers, Power Plants, Petrochemical Facilities, Shipbuilding Yards, Construction Companies |
| Companies Covered | Baker Hughes Company, EVIDENT, Eddyfi Technologies, Sonatest, Mistras Group, Zetec, NDT Systems Inc, Waygate Technologies, TÜV Rheinland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Testing Equipment Market Strategic Shifts & Innovations
The evolution of ultrasonic testing equipment is defined by the integration of advanced software and imaging algorithms. This transforms instruments from simple flaw detectors into powerful data acquisition tools for comprehensive asset integrity management. The focus is shifting from hardware specifications to the analytical capabilities of the supporting software ecosystem.
Total Focusing Method (TFM) and Full Matrix Capture (FMC) provide highly detailed, real-time images of material cross-sections. The aerospace and nuclear power sectors are adopting these methods for inspecting complex geometries and critical welds. This advanced imaging technology is automating the characterization of flaws, reducing ambiguity and dependence on operator skill for precise sizing.
New revisions to the ASME Boiler and Pressure Vessel Code (BPVC) emphasize performance-based validation for non-destructive testing procedures. This requires equipment and techniques to demonstrate a specific probability of detection, pushing manufacturers beyond simple compliance checks. The oil and gas and power generation industries are most affected, driving investment in more capable and verifiable UT systems to meet these stringent asset integrity standards.
A transition toward leasing and rental models for high-end equipment is altering acquisition patterns for inspection service companies. This approach allows smaller firms to access sophisticated phased array systems for specific projects without incurring large capital costs, disrupting traditional direct sales channels. This trend is most pronounced in Europe and North America, where project-based cost management is a critical competitive factor for service providers.
Ultrasonic Testing Equipment Market Segmentation
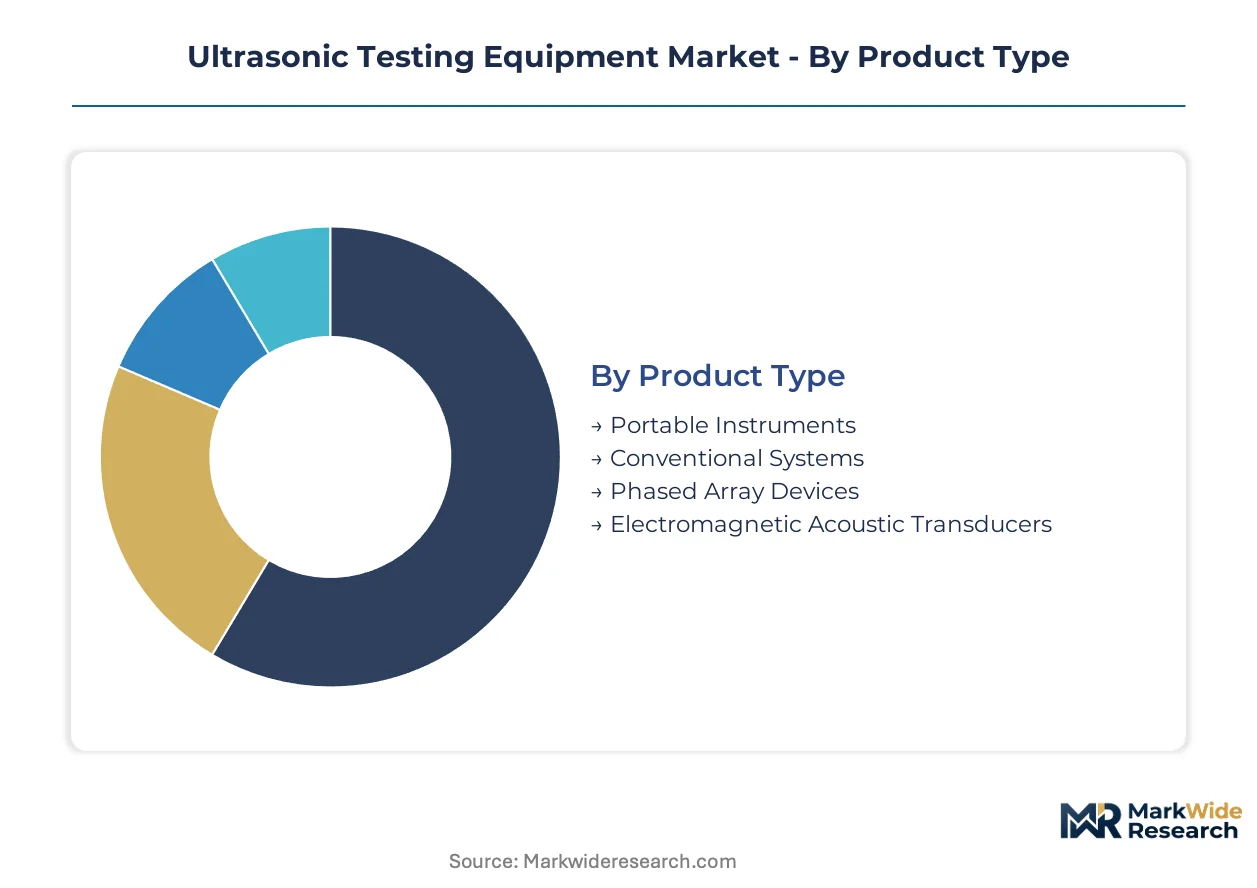
The ultrasonic testing equipment market demonstrates diverse requirements across industries, necessitating careful segmentation to understand demand patterns and technological preferences. This detailed categorization helps identify specific product functionalities and application needs driving market expansion. Analyzing these segments reveals where technological advancements and investment are most impactful.
Product Type:
The market for ultrasonic testing equipment is defined by its core technological specifications and portability.
- Phased Array Devices:These instruments employ multiple ultrasonic elements that can be pulsed independently, allowing for electronic beam steering and focusing. Demand concentrates in aerospace manufacturing and power generation due to their superior imaging capabilities for complex geometries.
- Portable Instruments:These handheld, often single-function devices offer convenience and ease of use for on-site inspections. General industry and smaller service companies drive demand for these cost-effective units, especially for routine checks.
- Conventional Systems:These standard pulse-echo units provide basic flaw detection and thickness measurement, serving a broad range of industrial applications.
- Electromagnetic Acoustic Transducers:EMATs generate sound waves in materials without direct contact, finding application in high-temperature or rough surface inspections.
Mature deployment sits with Conventional Systems. Newer deployment is concentrated in Phased Array Devices.
Technology:
Different ultrasonic technologies address specific inspection challenges, varying by their wave generation and reception methods.
- Phased Array:This technology uses an array of transducers to generate steerable and focusable ultrasonic beams, enabling rapid scanning and complex flaw characterization. Aerospace and nuclear power sectors utilize Phased Array for high-resolution imaging of critical components.
- Time-of-Flight Diffraction:TOFD relies on the diffraction of ultrasonic waves from flaw tips to accurately size defects, particularly in thick-walled components. Oil and gas pipelines and pressure vessel inspections frequently employ TOFD for precise crack sizing.
- Pulse-Echo:This fundamental technique transmits a pulse and measures the time for its echo, primarily used for basic flaw detection and thickness gauging.
- Through Transmission:Through transmission involves separate transmitting and receiving transducers, often used for laminate and composite material inspection.
- Resonance Testing:Resonance testing identifies material properties or defects by measuring changes in an object's natural vibration frequencies.
Phased Array technology is gaining share fastest. Pulse-Echo remains a foundational technique.
Application:
The diverse applications of ultrasonic testing equipment directly reflect the critical inspection needs across various industrial sectors.
- Weld Inspection:Ultrasonic testing is indispensable for detecting internal discontinuities like cracks, porosity, and lack of fusion in welded joints. Infrastructure projects in China and pipeline integrity management in petrochemicals heavily rely on UT for weld quality assurance.
- Flaw Detection:This broad application identifies internal defects, such as inclusions, voids, and delaminations, within materials and components. Aerospace manufacturers and power plants use flaw detection to ensure structural integrity and prevent catastrophic failures.
- Corrosion Analysis:UT accurately measures remaining wall thickness to assess corrosion and erosion, crucial for aging infrastructure and asset integrity management.
- Thickness Measurement:This application determines material thickness, essential for quality control in manufacturing and monitoring wear in operational assets.
- Bond Evaluation:UT assesses the quality of adhesive bonds and composite laminates, critical for aerospace structures and advanced material applications.
Weld Inspection consistently accounts for significant equipment utilization. Bond Evaluation experiences increasing specialized demand.
End User:
End-user segments dictate equipment sophistication and inspection volume, driven by regulatory mandates and asset criticality.
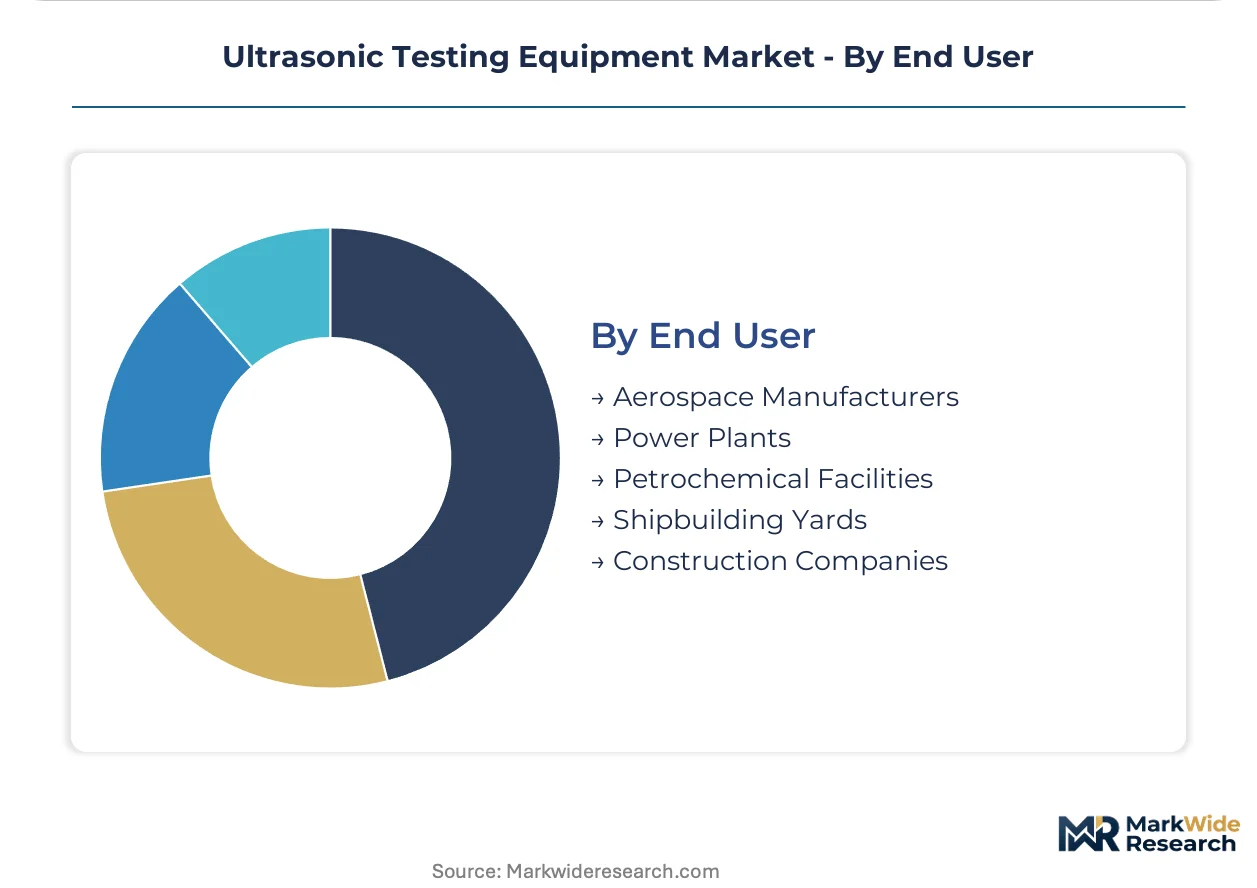
- Aerospace Manufacturers:This sector demands advanced UT systems for inspecting complex composite structures and critical metallic components, ensuring airworthiness. Stringent FAA regulations and composite material use drive high-end equipment procurement for these manufacturers.
- Power Plants:Nuclear and conventional power generation facilities require robust UT for inspecting pressure vessels, turbines, and piping to maintain operational safety. ASME Boiler and Pressure Vessel Code compliance mandates extensive ultrasonic inspections in these environments.
- Petrochemical Facilities:These facilities employ UT for pipeline integrity, tank inspection, and corrosion monitoring to prevent leaks and ensure operational safety.
- Shipbuilding Yards:UT is vital for inspecting welds and material integrity in hull structures and critical components during ship construction and maintenance.
- Construction Companies:Construction uses UT for concrete inspection, rebar location, and structural steel weld integrity, particularly in large-scale infrastructure.
Aerospace Manufacturers represent the fastest-growing demand segment. Construction Companies maintain steady demand for basic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai, a global manufacturing and innovation hub, drives significant demand for ultrasonic testing equipment. The city's extensive industrial base, including aerospace and infrastructure projects, requires advanced non-destructive testing solutions. This demand reflects a broader global need for stringent asset integrity management across diverse industrial sectors.
China
China's massive infrastructure projects, such as high-speed rail networks and nuclear power plants, necessitate extensive ultrasonic inspection. The national GB standards for material quality and construction integrity mandate precise flaw detection capabilities. Industrial clusters in the Yangtze River Delta, including Nanjing and Suzhou, are centers for manufacturing and energy, requiring continuous UT application.
United States
Stringent regulations from the FAA and ASME drive the procurement of advanced ultrasonic testing systems in the United States. Aerospace manufacturers and power generation facilities demand high-resolution phased array devices for critical component inspection. The Gulf Coast region, with its petrochemical facilities, heavily utilizes UT for pipeline integrity and corrosion analysis.
Germany
German industries, particularly automotive and energy, require sophisticated UT solutions for quality control and asset longevity. European EN standards and the country's strict industrial safety regulations ensure consistent demand for advanced NDT technologies. The industrial heartland of North Rhine-Westphalia, encompassing cities like Essen and Düsseldorf, represents a major hub for specialized UT equipment users.
India
India's expanding manufacturing sector and significant investments in power infrastructure generate substantial demand for ultrasonic testing equipment. The Bureau of Indian Standards (BIS) promotes quality assurance across various industries, reinforcing the need for reliable NDT methods. Industrial corridors like the Delhi-Mumbai Industrial Corridor are seeing increased deployment of UT for structural integrity and quality checks.
Japan
Japanese precision manufacturing and nuclear power facilities consistently adopt high-end ultrasonic testing for quality assurance. METI guidelines for industrial safety and product reliability ensure continuous investment in advanced inspection technologies. The Kansai region, including Osaka and Kobe, houses critical heavy industries and shipyards that rely on UT for structural integrity.
Ultrasonic Testing Equipment Market Key Industry Players
Premium-margin players sit above commodity-margin players across the ultrasonic testing equipment market, reflecting a distinct bifurcation in product offerings. This market structure features a tiered competitive landscape, ranging from specialized advanced NDT solution providers to manufacturers of cost-effective, portable flaw detectors. Strategic archetypes include innovation-driven firms focusing on software integration and established hardware providers emphasizing ruggedness. Companies in this space frequently engage in strategic partnerships to expand technological capabilities or diversify their product portfolios.
Specialists in advanced non-destructive testing solutions include Eddyfi Technologies, which focuses on sophisticated inspection for critical industrial assets. EVIDENT, leveraging its legacy in precision optics and electronics, represents a segment offering highly sophisticated imaging capabilities. Sonatest, a UK-based company, exemplifies the providers of rugged, field-ready portable devices for conventional UT applications. These companies anchor different segments of the market, catering to varying levels of technical complexity and operational environments.
| Leading Market Players |
|---|
| Baker Hughes Company |
| EVIDENT |
| Eddyfi Technologies |
| Sonatest |
| Mistras Group |
| Zetec |
| NDT Systems Inc |
| Waygate Technologies |
| TÜV Rheinland |
| Others |
Cost & Logistics Intelligence
Specialized technology firms, often backed by private equity, influence both supply chain resilience and pricing discipline in the ultrasonic testing equipment market. Their investment in R&D for advanced systems drives premium pricing, while their strategic sourcing for high-precision components impacts overall supply availability.
Pricing Analysis
Pricing anchored to inspection accuracy and the probability of detection drives value for advanced ultrasonic testing equipment. The dominant pricing structure involves tiered premium-mid-economy differentiation, reflecting technological sophistication and feature sets. Price differentiation stems from certification level, such as ASME compliance, and the extent of software integration for data analytics. Pricing softness impacts conventional portable units due to commoditization and broader availability. Aerospace manufacturers exhibit low price sensitivity for high-end systems, prioritizing safety and regulatory compliance over cost, while construction companies remain highly price-sensitive for basic measurement tools.
Supply Chain Analysis
Domestic content mandates for critical infrastructure projects, particularly in China and India, reshape sourcing strategies for ultrasonic testing equipment components. Geographic supply concentration for high-precision transducers and advanced imaging chips centers on Japan, Germany, and the United States. Raw material dependencies include specialized piezoelectric ceramics and rare earth elements for advanced sensors. A structural supply chain risk involves single-source vulnerability for highly specialized software modules. Distribution runs through a mix of direct sales channels for high-end systems and regional distributors for portable, conventional equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with advanced Phased Array and TFM/FMC techniques displacing legacy conventional ultrasonic testing in critical applications.
For Market Incumbents: Acquire advanced software IP and data analytics capabilities to maintain a competitive edge against emerging AI-driven solutions. Consolidate market share by integrating sophisticated imaging algorithms directly into hardware platforms, leveraging existing customer relationships. Invest in Level II and Level III technician training programs to address the skilled labor shortage, mitigating a significant market threat. Control key component supply chains for specialized transducers to ensure production stability.
For New Entrants and Emerging Players: Capture niche opportunities in additive manufacturing inspection, where existing solutions are less mature. Target underpenetrated segments like small-to-medium enterprises in general industry with cost-effective, user-friendly portable devices. Focus on developing AI-powered flaw recognition software that integrates with existing hardware, offering a compelling go-to-market angle. Prioritize partnerships with training institutions to build a talent pipeline for advanced NDT techniques.
For Investors and Strategic Acquirers: Distressed-cycle entries favor software-centric NDT specialists in Europe, particularly those with strong intellectual property in data analytics and automation. Long-term viability rests on companies capable of transitioning from hardware-centric sales to integrated software-as-a-service models. Target firms with robust recurring revenue streams from software licenses or advanced inspection services. The signal to watch is the increasing adoption rate of AI-driven flaw characterization tools in regulated industries.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI for automated flaw recognition | Enhances inspection speed and reduces dependence on operator skill for critical applications. |
| Develop advanced TFM/FMC imaging software | Provides superior defect characterization for complex geometries in aerospace and nuclear power. |
| Expand leasing and rental models | Lowers capital expenditure barriers for smaller inspection service companies, broadening market access. |
| Invest in technician training and certification | Addresses the acute shortage of skilled NDT personnel, improving service delivery capacity. |
| Standardize data formats across equipment | Enables unified inspection databases and fleet-wide analysis for asset integrity management programs. |
Research Approach
Independent corroboration across industry association reports, academic research, and regulatory body publications underwrites the qualitative findings of this study. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided crucial insights. Secondary data sources included ASME code revisions, FAA guidance documents, and national NDT society publications, ensuring a robust bottom-up and top-down triangulation.
The rate-of-change decomposition framing informed the analytical framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived from historical data analysis and projected market drivers. Industry-specific forecast inputs included infrastructure investment trends in key emerging economies and new material adoption rates in aerospace manufacturing.
The model holds under stable regulatory environments and consistent technological development; deviation in global trade policies or unexpected geopolitical shifts would shift the forecast trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hour Meter Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Asia-Pacific Electronic Test and Measurement Market
Test and Measurement
Structure Tester Market
Test and Measurement
Voltage Tester Market
Test and Measurement
Surface Vision and Inspection Equipment Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Heat Deformation Tester Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
CCTV Tester Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Digital Oscilloscope Market