
 Thin Film Metrology Systems Market | 2026-2036
Thin Film Metrology Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Metrology Systems Market Outlook
Aftermarket service revenue for installed metrology fleets is fragmenting across third-party calibration houses and original equipment channels. KLA Corporation leverages its captive service network to lock in long-term maintenance contracts at advanced logic fabs. Horiba anchors its position through deep integration with Japanese display and semiconductor equipment supply chains. Nova Ltd competes by specializing in inline optical solutions for atomic-layer deposition monitoring.
Thin film metrology systems measure thickness, refractive index, and surface topography of deposited layers ranging from angstroms to several microns, primarily serving semiconductor manufacturing where film uniformity directly impacts device yield. Optical and ellipsometry platforms lead installed base volumes, while X-ray metrology captures expanding share in high-aspect-ratio memory stacks where optical penetration fails. Process control applications generate the most recurring hardware demand, though research and development spending on novel materials keeps spectroscopy and interferometry technology segments growing above equipment replacement rates.
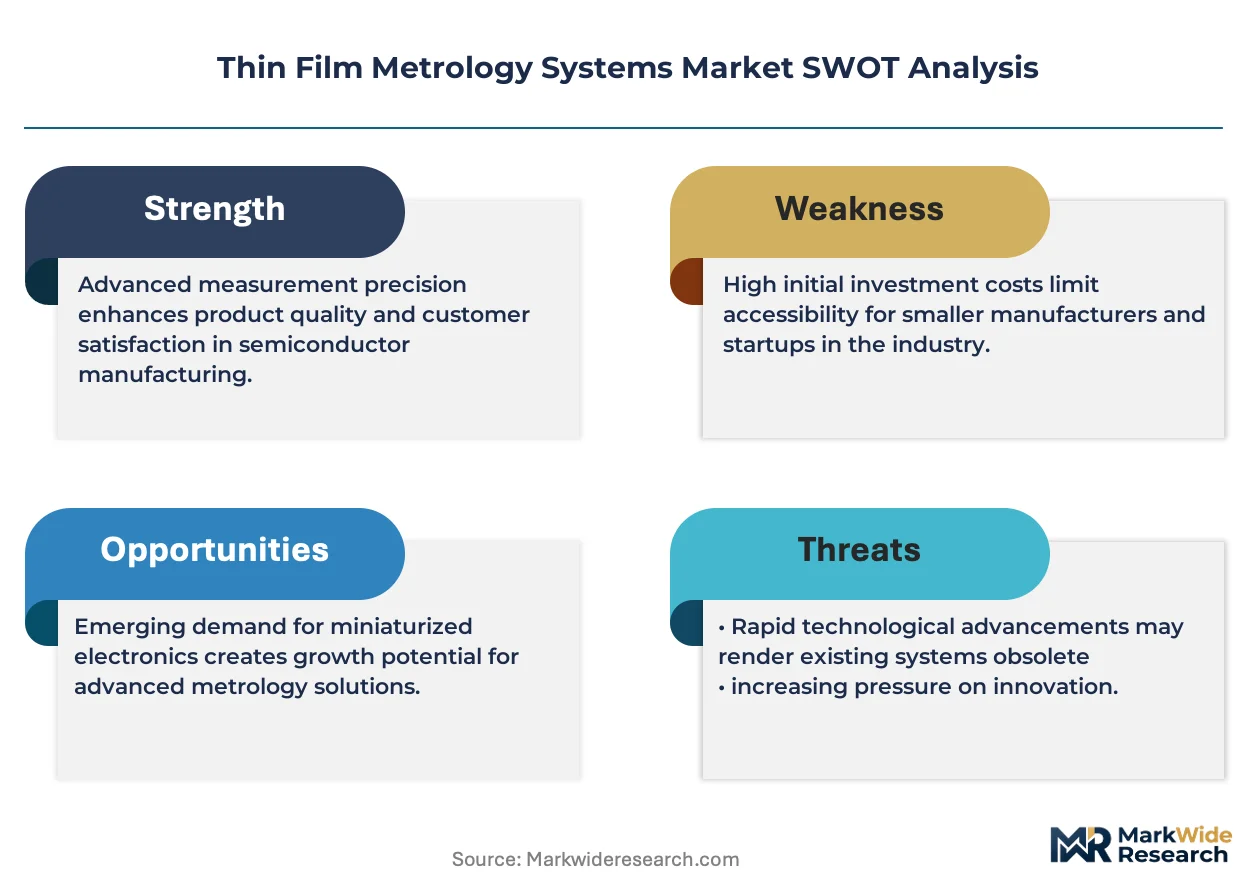
SEMI standards, FDA quality system regulations for medical device fabs, and REACH chemical disclosure requirements in Europe collectively shape equipment specifications and market access conditions for metrology vendors. The EPA enforces hazardous substance reporting that affects thin film precursor handling, indirectly elevating inline monitoring requirements to minimize waste. Stakeholders must weigh capital allocation between extending optical platform life and migrating to X-ray and hybrid architectures as three-dimensional device geometries proliferate.
Market Dynamics
Sub-7nm logic node ramp-ups and high-aspect-ratio 3D NAND architectures are forcing fabs to abandon single-technique metrology in favor of multi-modal platforms that fuse optical, X-ray, and electron-beam measurements into unified process control workflows.
Growth Catalysts
- EUV lithography diffusion:Taiwan Semiconductor Manufacturing and Samsung Foundry deployments at 3nm and 2nm nodes require angstrom-level film thickness verification that only advanced ellipsometry combined with X-ray reflectometry can deliver.
- REACH chemical disclosure mandates:European semiconductor fabs face intensified precursor tracking requirements that elevate inline monitoring density to minimize waste and avoid regulatory penalties.
- Memory stack verticality:200+ layer 3D NAND and emerging gate-all-around transistor geometries create measurement scenarios where optical penetration fails entirely.
Market Restraints
- X-ray source supply concentration:Microfocus X-ray tube manufacturing concentrates among Japanese and German component suppliers, creating single-source vulnerability for hybrid metrology system builders.
- SEMI S2/S8 compliance timelines:Equipment safety and ergonomic certification requirements extend qualification cycles by 6-12 months for new platform introductions.
- Optical technique saturation:Traditional spectroscopic ellipsometry hits fundamental limits at sub-nanometer dielectric films on complex finFET and nanosheet geometries.
Strategic Opportunities
- Indian semiconductor fabrication:Tata Electronics and CG Power are building domestic foundry capacity where greenfield facilities lack installed metrology bases, creating equipment-first deployment scenarios.
- Photonics packaging metrology:Silicon photonics and co-packaged optics for AI clusters require film thickness control on non-planar waveguide structures that conventional semiconductor tools underserve.
- US CHIPS Act capital access:Department of Commerce funding for Arizona, Texas, and Ohio fabs includes equipment procurement incentives that favor advanced process control technology adoption.
Industry Challenges
- Multi-physics algorithm development:Integrating optical, X-ray, and electron-beam data streams demands rare expertise spanning electromagnetics, quantum scattering, and machine learning model training.
- Legacy tool interoperability:Brownfield fabs in South Korea and Japan operate 200mm and 300mm lines with 15-20 year-old metrology fleets that resist seamless data integration with new hybrid platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Metrology Systems Market |
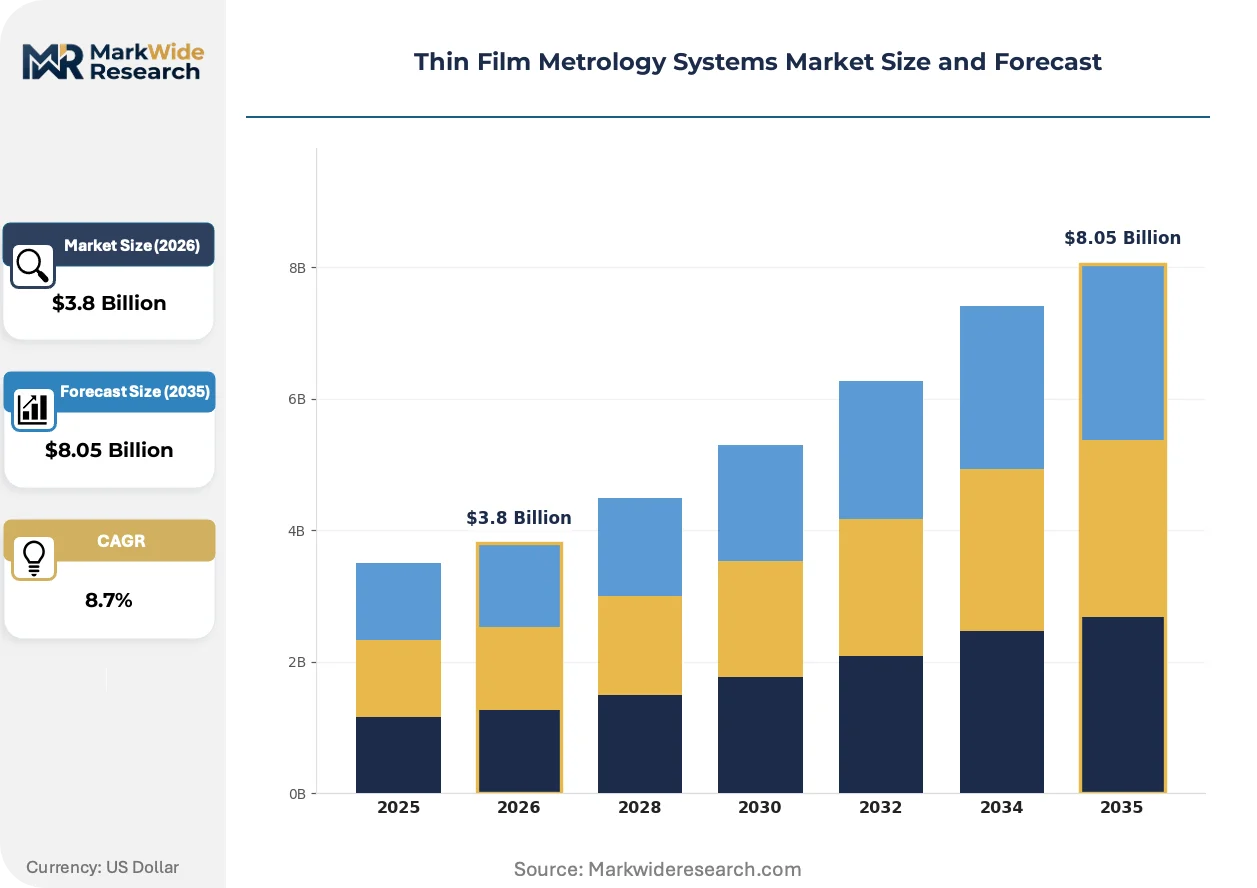
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, X-ray, Surface Profiling, Ellipsometry End User: Semiconductor, Electronics, Data Storage, Photovoltaics Technology: Reflectometry, Interferometry, Spectroscopy, Talystep Application: Quality Control, Research & Development, Process Control, Characterization |
| Companies Covered | SCREEN Holdings, Horiba, KLA Corporation, Veeco Instruments, Rudolph Technologies, Nova Ltd, Hitachi High-Tech Corporation, Semilab Inc., Onto Innovation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Metrology Systems Market Strategic Shifts
Metrology platform architecture is undergoing forced convergence as device complexity outpaces the capability of any single measurement physics, compressing vendor roadmaps toward unified software layers and shared vacuum chambers.
Hybrid metrology is hybridizing optical ellipsometry with X-ray reflectometry and critical-dimension scanning electron microscopy into single-vacuum platforms. Samsung and Intel process development teams now specify these configurations for high-volume manufacturing qualification. The structural consequence is collapsing the historical separation between R&D laboratory and fab floor metrology equipment categories.
REACH enforcement by ECHA is tightening chemical inventory reporting for thin film precursors used in atomic layer deposition. European memory and logic fabs must now document precursor consumption at chamber level, driving demand for real-time film thickness feedback that correlates deposition rate with material usage. German and French equipment buyers now prioritize metrology systems with embedded precursor monitoring modules.
Service contract unbundling is fragmenting the traditional OEM captive service model. Third-party calibration houses in Taiwan and South Korea now compete for preventive maintenance on KLA and Applied Materials installed bases. Foundry procurement teams at United Microelectronics and PSMC actively solicit multi-vendor service agreements to reduce single-source dependency and compress annual maintenance expenditure.
Thin Film Metrology Systems Market Segmentation
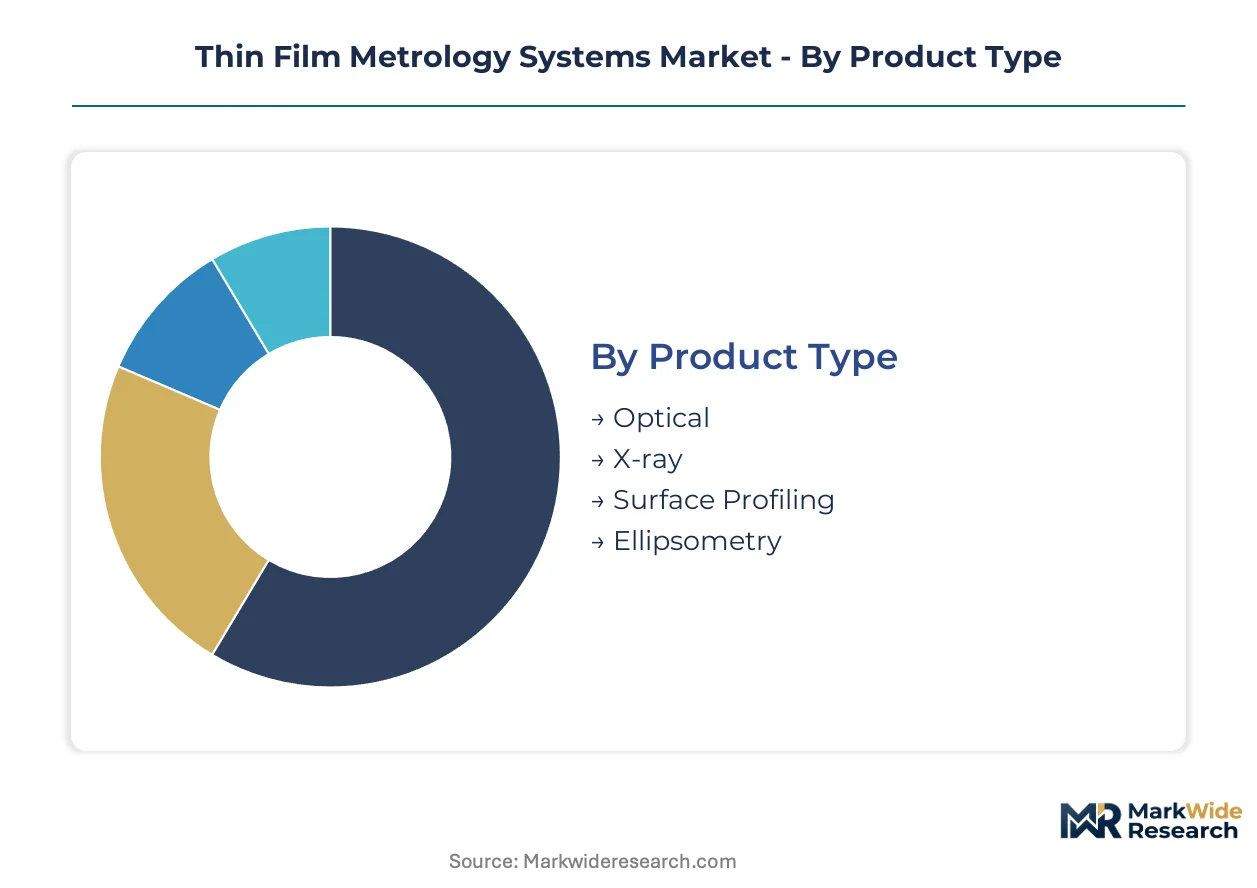
Thin film metrology systems serve distinct measurement physics and process requirements across semiconductor fabrication workflows. Segmentation reveals where capital cycles accelerate versus where installed bases mature slowly.
Product Type:
Optical platforms refresh every 3-4 years at leading-edge fabs, while X-ray systems endure 7-10 year cycles due to source longevity and vacuum chamber durability.
- Optical:Spectroscopic reflectometry and bright-field imaging dominate wafer-level thickness mapping for dielectric stacks. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement teams specify these for 3nm node production lines where throughput exceeds 200 wafers per hour.
- Ellipsometry:Polarization-change measurement achieves angstrom-level precision on sub-nanometer films. South Korean memory fabs deploy these for atomic-layer deposition monitoring where high-k dielectric uniformity determines yield.
- X-ray:Reflectometry and fluorescence penetrate high-aspect-ratio 3D NAND structures beyond optical limits. Japanese and German source suppliers constrain system availability.
- Surface Profiling:Stylus and optical profilometers map topography on planarization layers. Mature 200mm fabs in Japan maintain these for legacy process control.
Optical dominates installed base. X-ray is where expansion concentrates.
End User:
Semiconductor fabs absorb premium pricing for multi-technique platforms, while photovoltaics buyers prioritize cost-per-measurement metrics over specification breadth.
- Semiconductor:Logic and memory manufacturers drive specifications for sub-nanometer precision. United States CHIPS Act funding accelerates Arizona and Texas fab buildouts where greenfield metrology procurement lacks legacy constraints.
- Electronics:Printed circuit board and display panel producers require film thickness control on flexible substrates. South Korean OLED manufacturers specify compact ellipsometry units for roll-to-roll deposition lines.
- Data Storage:Hard disk drive and tape media fabrication demands magnetic layer characterization. Japanese precision equipment suppliers anchor this segment.
- Photovoltaics:Silicon and thin-film solar cell producers monitor anti-reflective coatings and transparent conductors. Indian domestic manufacturing incentives expand addressable equipment demand.
Semiconductor commands capital allocation. Photovoltaics is climbing the fastest.
Technology:
Reflectometry and interferometry platforms achieve highest utilization rates, while spectroscopy tools face longer qualification cycles for novel material sets.
- Reflectometry:Single-wavelength and spectroscopic variants measure film thickness through interference pattern analysis. Taiwan foundry clusters standardize on these for high-volume oxide and nitride monitoring.
- Interferometry:Phase-shifting and white-light techniques resolve surface topography at sub-nanometer vertical resolution. German automotive sensor fabs deploy these for MEMS process control.
- Spectroscopy:UV-visible and infrared platforms identify material composition alongside thickness. Research laboratories at United States national facilities drive adoption for exotic dielectric development.
- Talystep:Contact stylus profilometry delivers traceable step height measurements for calibration standards. Metrology institutes and equipment manufacturers maintain limited installed bases.
Reflectometry holds broadest deployment. Spectroscopy shows steepest expansion trajectory.
Application:
Process control applications generate recurring hardware demand, while research and development spending fluctuates with materials innovation cycles.
- Process Control:Inline monitoring at deposition and etch stations enables real-time recipe adjustment. South Korean 3D NAND fabs require these for 200+ layer stack uniformity verification.
- Quality Control:Final inspection and outgoing verification ensure shipped wafers meet customer specifications. Japanese discrete semiconductor manufacturers emphasize these for automotive qualification.
- Research & Development:Materials characterization and process development support next-node technology. United States Department of Energy laboratories and consortia fund advanced platform acquisition.
- Characterization:Destructive and non-destructive analysis validates film properties for failure analysis. Third-party test houses in Taiwan cluster near major foundry complexes.
Process control anchors revenue stability. Research and development is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan deploys metrology systems at the highest density per wafer start, while the United States prioritizes greenfield multi-technique platforms over legacy tool refresh cycles. South Korea concentrates investment in memory-specific configurations, and Japan maintains the deepest installed base of optical profilometers for mature nodes.
Taiwan
TSMC's 3nm and 2nm ramp-ups drive angstrom-level ellipsometry procurement for EUV lithography film stacks. The island's EPA enforces hazardous substance reporting that elevates inline monitoring requirements at Hsinchu Science Park facilities. Taichung's Central Taiwan Science Park hosts the densest concentration of hybrid metrology deployments for leading-edge logic production.
United States
CHIPS Act funding accelerates Arizona and Texas fab construction where greenfield metrology procurement lacks legacy optical tool constraints. Department of Commerce equipment incentives favor advanced process control technology adoption at Intel's Ohio and TSMC's Arizona sites. The EPA's precursor handling regulations indirectly expand inline monitoring density to minimize chemical waste.
South Korea
Samsung Foundry and SK Hynix drive specifications for 200+ layer 3D NAND measurement where optical penetration fails. MFDS chemical tracking requirements for semiconductor materials elevate real-time film thickness feedback systems. Yongin and Pyeongtaek clusters anchor the world's highest concentration of X-ray reflectometry installations for high-aspect-ratio memory stacks.
Japan
Tokyo Electron and Hitachi High-Tech supply chains anchor domestic metrology tool consumption for display and memory applications. METI's semiconductor equipment subsidies support precision manufacturing infrastructure in Kumamoto and Hiroshima prefectures. Kyoto and Osaka maintain specialized ellipsometry demand for OLED roll-to-roll deposition lines serving South Korean panel makers.
China
Domestic foundry expansion at SMIC and Hua Hong drives cost-optimized optical platform procurement for mature node production. MIIT's GB standards for semiconductor equipment quality create certification barriers for imported hybrid systems. Shanghai's Zhangjiang Hi-Tech Park clusters the highest density of local metrology system integrators serving 28nm and above processes.
Thin Film Metrology Systems Market Competitive Environment
Capability concentration sits with specialized optical and X-ray platform developers; scale advantage sits with diversified semiconductor equipment conglomerates. The vendor base organizes into three tiers: captive service network operators, regional supply chain integrators, and niche technique specialists. Dominant competitive moves include strategic partnerships for X-ray source supply security and portfolio diversification into hybrid metrology architectures.
Within the specialized tier, Nova Ltd and Onto Innovation Inc. occupy positions exemplifying inline optical solutions for deposition monitoring. KLA Corporation anchors the diversified equipment category with captive service network advantages. Horiba represents deep regional supply chain integration with Japanese display and semiconductor equipment ecosystems. These three companies collectively illustrate the competitive tension between technique depth and geographic coverage in thin film metrology system supply.
| Leading Market Players |
|---|
| SCREEN Holdings |
| Horiba |
| KLA Corporation |
| Veeco Instruments |
| Rudolph Technologies |
| Nova Ltd |
| Hitachi High-Tech Corporation |
| Semilab Inc. |
| Onto Innovation Inc. |
| Others |
Value Chain & Pricing Dynamics
Japanese and German microfocus X-ray tube manufacturing concentrates upstream supply for hybrid metrology platforms, anchoring margin pools with system integrators who control multi-technique platform assembly and captive service networks. This concentration creates asymmetric pricing power where source suppliers extract premiums while foundry procurement teams face limited substitution options for high-aspect-ratio memory measurement.
Pricing Analysis
Long-term service contracts dominate equipment procurement at leading-edge fabs, with KLA Corporation's captive maintenance agreements spanning 5-7 year terms that bundle preventive calibration with software updates. Price differentiation rests on certification tier—SEMI S2/S8 compliant platforms command 15-25% premiums over non-certified alternatives—and volume scale, where TSMC and Samsung negotiate enterprise pricing across multi-fab deployments. Cost compression in optical ellipsometry intensifies as third-party calibration houses in Taiwan fragment aftermarket service revenue. Photovoltaics buyers exhibit highest price sensitivity, prioritizing cost-per-measurement over angstrom-level precision, while memory fabs show least sensitivity given yield failure costs.
Supply Chain Analysis
Microfocus X-ray tubes, high-precision optical interferometers, and vacuum chamber assemblies feed from concentrated manufacturing bases in Japan, Germany, and the United States. Japanese suppliers anchor X-ray source production for reflectometry systems, while German precision optics houses dominate ellipsometry component supply. Single-source vulnerability for microfocus tubes creates structural risk if geopolitical restrictions disrupt component flows. Distribution runs through direct OEM sales teams for leading-edge semiconductor fabs, with regional integrators serving mature-node buyers in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin film metrology is approaching a platform-economics inflection where hybrid architecture interoperability determines competitive survival, accelerated by Samsung and Intel's unified software layer specifications that collapse historical boundaries between R&D and fab floor equipment categories.
For Market Incumbents: Entrench through backward integration into X-ray source supply chains, securing captive access to Japanese and German component manufacturers against single-source vulnerability. Expand service contract bundling to lock out third-party calibration houses in Taiwan and South Korea. Threat: Nova Ltd and Onto Innovation's specialized optical depth erodes share in atomic-layer deposition monitoring. Lever: SEMI S2/S8 certification investment creates switching costs for brownfield fabs with 15-20 year legacy fleets. For New Entrants and Emerging Players: India's greenfield semiconductor fabrication at Tata Electronics and CG Power facilities offers underpenetrated terrain lacking installed metrology bases, enabling equipment-first deployment without legacy optical tool displacement. Photonics packaging for AI cluster silicon photonics presents adjacent white space where conventional semiconductor tools underserve non-planar waveguide structures. Go-to-market angle: Partner with Applied Materials or Tokyo Electron for chamber integration, bypassing direct fab sales team buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision optics specialists holding proprietary interferometry IP but lacking hybrid platform roadmaps. Long-term viability favors vendors with multi-physics algorithm development capabilities spanning electromagnetics, quantum scattering, and machine learning model training. Acquisition target archetype: Niche X-ray reflectometry developers with Japanese supply chain relationships. Signal to watch: Intel and TSMC public specifications for unified vacuum chamber architectures that force vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Integration | Samsung and Intel specifications for single-vacuum multi-technique systems collapse R&D-fab equipment boundaries. |
| X-ray Source Supply Agreement | Japanese and German tube manufacturers' concentration creates captive supply priority for system builders. |
| Service Network Expansion | KLA Corporation's maintenance contract density in Taiwan and South Korea locks out third-party calibration competition. |
| Photonics Packaging Specialization | Silicon photonics for AI clusters requires film thickness control on non-planar structures beyond conventional tool reach. |
| Regulatory Certification Investment | SEMI S2/S8 compliance extends qualification cycles 6-12 months, creating barrier for unvalidated new entrants. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with process control engineers at TSMC and Samsung Foundry, metrology procurement leads at SK Hynix and Intel, equipment R&D directors at KLA Corporation and Nova Ltd, and aftermarket service managers at third-party calibration houses in Taiwan. Secondary validation drew from SEMI equipment market data, EPA hazardous substance reporting filings, ECHA REACH enforcement disclosures, and SEC 10-K filings from listed equipment vendors. Bottom-up wafer start projections were triangulated against top-down capital expenditure forecasts from foundry announcements.
Calibration against historical platform replacement cycles and node transition timelines anchored projections across the analysis window. Segmentation dimensions modeled include measurement physics platform, end-user industry vertical, application workflow, and regional regulatory cluster. CAGRs were derived from equipment shipment volumes correlated with fab capacity expansion schedules and EUV lithography adoption curves. Industry-specific inputs incorporated 3D NAND layer count trajectories and gate-all-around transistor geometry proliferation rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic equipment integrators or unexpected X-ray source supply disruptions would shift outcomes. Cross-checking against SEMI capital equipment shipment reports and foundry quarterly capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
AI-Enabled Semiconductor Defect Classification and Review Systems Market
Test and Measurement
Density Meter Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Scuff Tester Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Automatic Impact Testing Machine Market
Test and Measurement
Production Testing Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Metrology Services Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Destructive Testing Market