
 Automated Optical Inspection (AOI) Equipment Market | 2026-2036
Automated Optical Inspection (AOI) Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
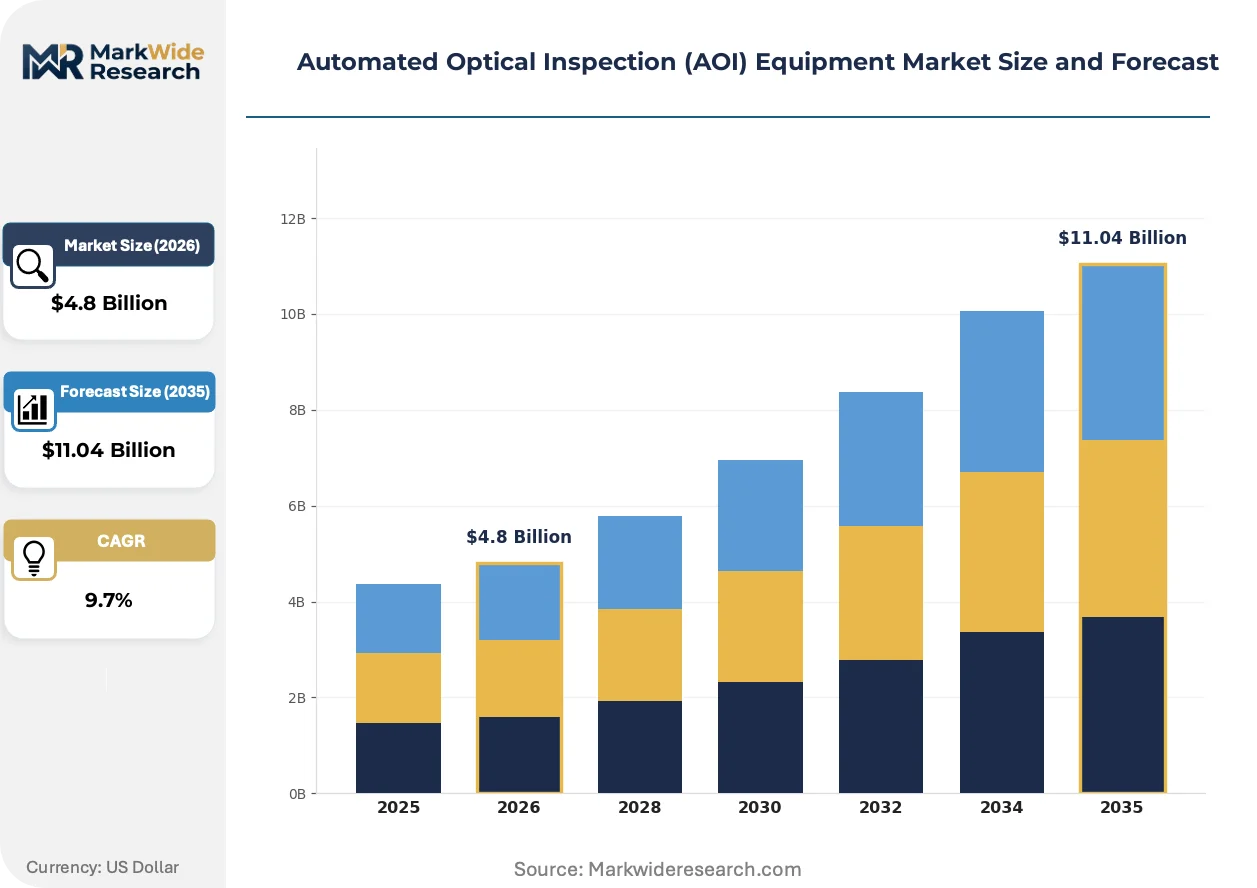
Automated Optical Inspection (AOI) Equipment Market Outlook
Modular platform bundling is hardening as the dominant procurement pattern, with buyers favoring configurable 3D AOI and SPI combinations over standalone units. Koh Young Technology leverages its software-hardware integration to anchor premium positioning in semiconductor packaging inspection. Test Research, Inc. competes through dense service networks across East Asian electronics manufacturing clusters. Omron Corporation differentiates via machine-learning defect classification that reduces false-call rates for automotive PCB clients.
Automated optical inspection equipment comprises vision-based systems that capture high-resolution images of printed circuit boards and electronic assemblies at speeds exceeding 100 cm² per second, applying algorithmic analysis to detect solder defects, component placement errors, and trace anomalies before functional testing. The equipment serves primarily to eliminate downstream rework costs and warranty failures in volume electronics production. Three-dimensional AOI systems lead value capture as stacked die and advanced packaging geometries exceed 2D detection thresholds, while inline configurations dominate throughput-sensitive automotive supplier lines where SPI precedes placement verification in continuous-flow layouts. Machine learning technology segments show the fastest structural expansion as training datasets from multi-factory deployments improve classification accuracy without explicit rule programming.
FDA quality system regulations for medical device electronics and EPA hazardous substance reporting requirements shape validation protocols that AOI vendors must embed in traceability software. China's SAMR enforces GB standards for consumer electronics safety that mandate inspection documentation at contract manufacturer level. Japan's METI promotes JIS-aligned smart factory standards that reward vision-system integration with energy efficiency credits. Stakeholders must weigh regulatory documentation burdens against the operational savings of unified inspection databases spanning multiple OEM customer requirements.
Market Dynamics
AI-driven defect classification is compressing false-call rates below human-tolerable thresholds, forcing incumbent vendors to retrain algorithmic models on multi-factory datasets or cede premium positioning to software-native competitors.
Growth Catalysts
- EU RoHS and REACH frameworks:Material traceability mandates compel electronics manufacturers to deploy vision systems with embedded documentation layers, accelerating replacement of legacy 2D inspection lines.
- Semiconductor packaging miniaturization:Stacked die geometries and heterogeneous integration exceed 2D detection thresholds, pulling demand toward 3D AOI configurations with sub-micron z-axis resolution.
- China's SAMR enforcement:Stricter GB standards for consumer electronics safety require inspection documentation at contract manufacturer level, embedding AOI as a non-discretionary production cost.
Market Restraints
- High-resolution sensor cost volatility:CMOS image sensor pricing fluctuates with semiconductor foundry allocation cycles, compressing hardware margins for mid-tier equipment vendors.
- Specialized optics supplier concentration:Telecentric lens fabrication concentrates among German and Japanese precision optics houses, creating single-source vulnerability for 3D AOI module producers.
- 2D inspection substitution ceiling:Mature PCB geometries in consumer white goods sustain demand for legacy 2D systems, delaying full-platform upgrade cycles at price-sensitive assemblers.
Strategic Opportunities
- India's electronics PLI scheme:Contract manufacturing incentives for mobile and IT hardware are creating greenfield fab capacity requiring inline inspection infrastructure.
- AI-Moore's Law convergence:Edge inference chips enabling real-time defect classification without cloud latency are opening standalone retrofit markets for brownfield SMT lines.
- Japan's METI smart factory credits:JIS-aligned vision-system integration rewards offer subsidized upgrade pathways for automotive PCB suppliers.
Industry Challenges
- Machine vision engineer scarcity:Algorithm tuning for low-contrast solder joint detection requires rare cross-training in optical physics and Python-based model deployment.
- Multi-OEM validation complexity:Each automotive tier-1 supplier maintains proprietary defect taxonomies, forcing AOI vendors to maintain parallel software branches.
- Legacy MES integration friction:Brownfield factories run 1990s-era shop-floor databases that resist API-based traceability handshakes with modern inspection equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Optical Inspection (AOI) Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D AOI, 3D AOI, SPI, Inline Systems End User: Electronics Manufacturers, Automotive Suppliers, Aerospace Firms, Medical Device Companies Technology: Computer Vision, Image Processing, Machine Learning, Artificial Intelligence Application: PCB Inspection, Component Inspection, Final Assembly Verification, Quality Control |
| Companies Covered | Koh Young Technology, Test Research, Inc. (TRI), Omron Corporation, Viscom AG, Saki Corporation, Camtek, Nordson Corporation, CyberOptics Corporation, Mirtec Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Optical Inspection (AOI) Equipment Market Strategic Shifts
Computational imaging and edge-native AI are collapsing the latency between image capture and defect classification, enabling real-time process feedback loops that were previously confined to post-shift quality reviews.
Deep learning-based solder joint analysis is expanding into high-mix low-volume production environments previously deemed uneconomical for automated inspection. Medical device contract manufacturers in Minnesota and Bavaria are piloting these systems for Class II PCB assemblies. The technology is compressing the minimum viable lot size for AOI deployment from ten thousand units toward single-digit prototype runs.
EPA hazardous substance reporting requirements for electronics recyclers are mandating component-level material identification that exceeds traditional barcode traceability. Equipment vendors are responding with hyperspectral imaging modules that detect RoHS-restricted substances through spectral signature matching. Automotive suppliers in Michigan face the steepest compliance timelines, with 2026 documentation deadlines accelerating capital expenditure approvals.
Service unbundling is fragmenting the traditional equipment-plus-maintenance contract into separately priced algorithm updates, spare-pool access, and training credits. Tier-1 EMS providers in Guadalajara and Penang are negotiating per-inspection pricing for overflow capacity rather than fixed asset purchases. This shift concentrates vendor risk on uptime guarantees while transferring balance-sheet liability to equipment lessors.
Automated Optical Inspection (AOI) Equipment Market Segmentation
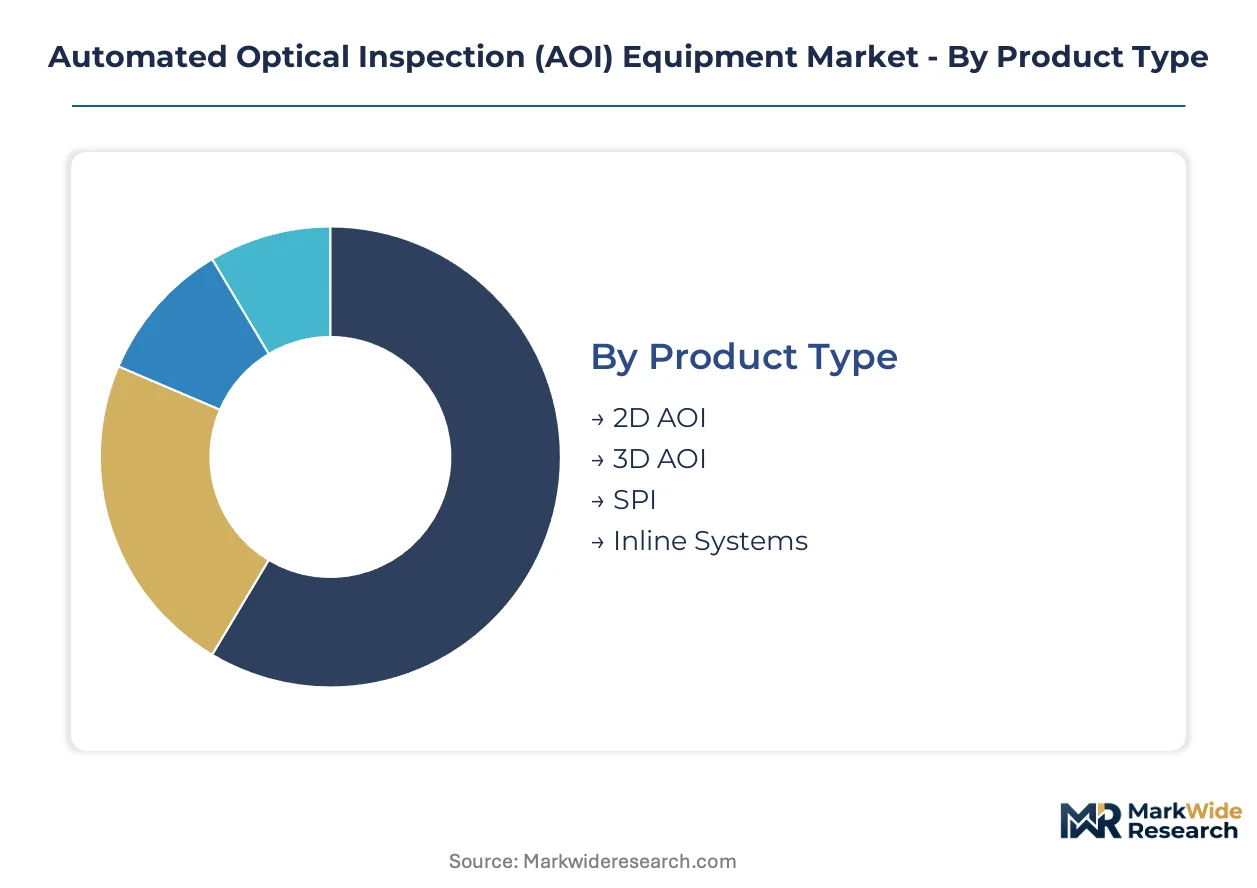
AOI equipment segmentation reveals how inspection complexity and production economics split procurement decisions across technology tiers and end-use requirements. Understanding these divides clarifies why 3D systems command premium positioning while 2D lines retain volume relevance in mature electronics categories.
Product Type:
Technology specification defines the core purchasing axis, with resolution capabilities and throughput rates determining factory-floor deployment patterns.
- 3D AOI:Sub-micron z-axis resolution captures stacked die geometries and heterogeneous integration profiles that 2D systems miss entirely. Semiconductor packaging facilities in Taiwan and South Korea anchor demand as advanced substrate inspection becomes non-negotiable for yield protection.
- 2D AOI:Planar imaging systems remain cost-effective for legacy PCB geometries where component height variation stays within narrow tolerances. White goods manufacturers in China sustain replacement demand despite technology obsolescence pressure from downstream miniaturization trends.
- SPI:Solder paste inspection modules operate upstream of placement verification, catching stencil printing defects before component mounting commits material.
- Inline Systems:Continuous-flow configurations integrate directly with SMT line pacing, eliminating manual board handling for throughput-sensitive automotive supplier operations.
3D AOI leads on scale; SPI leads on momentum as upstream defect prevention gains priority in zero-failure automotive supply chains.
End User:
Customer type segmentation tracks how regulatory intensity and liability exposure reshape inspection investment thresholds across manufacturing verticals.
- Automotive Suppliers:Tier-1 PCB assemblers face zero-defect contractual obligations from EV drivetrain and ADAS module OEMs. Michigan and Bavaria production clusters drive 3D AOI penetration as functional safety standards harden traceability requirements.
- Medical Device Companies:FDA quality system regulations mandate inspection documentation for Class II and III electronic assemblies. Minnesota contract manufacturers pilot AI-enhanced classification to compress validation cycles for implantable device substrates.
- Electronics Manufacturers:Consumer hardware assemblers balance inspection depth against unit economics, with smartphone and laptop production lines driving the largest absolute equipment volumes.
- Aerospace Firms:Defense and commercial aviation electronics carry extended warranty horizons that justify premium inspection coverage despite low production batch sizes.
Electronics manufacturers lead on scale; medical device companies lead on specification intensity as FDA validation protocols tighten algorithmic performance requirements.
Technology:
Software capability layers increasingly determine competitive positioning as hardware commoditization pressures sensor and optics margins.
- Machine Learning:Neural network architectures trained on multi-factory defect datasets reduce false-call rates below rule-based thresholds without explicit programming. Automotive PCB lines in Guadalajara deploy these systems to handle high-mix production without per-SKU algorithm recalibration.
- Artificial Intelligence:Broader AI frameworks extend beyond defect classification into predictive maintenance and process parameter optimization, collapsing the latency between inspection feedback and upstream correction.
- Computer Vision:Traditional algorithmic approaches using edge detection and geometric pattern matching retain relevance for standardized component geometries with stable lighting conditions.
- Image Processing:Preprocessing pipelines for noise reduction, distortion correction, and multi-image fusion remain foundational for all downstream analysis accuracy.
Computer vision leads on installed base; machine learning leads on expansion trajectory as training dataset scale becomes the primary competitive moat.
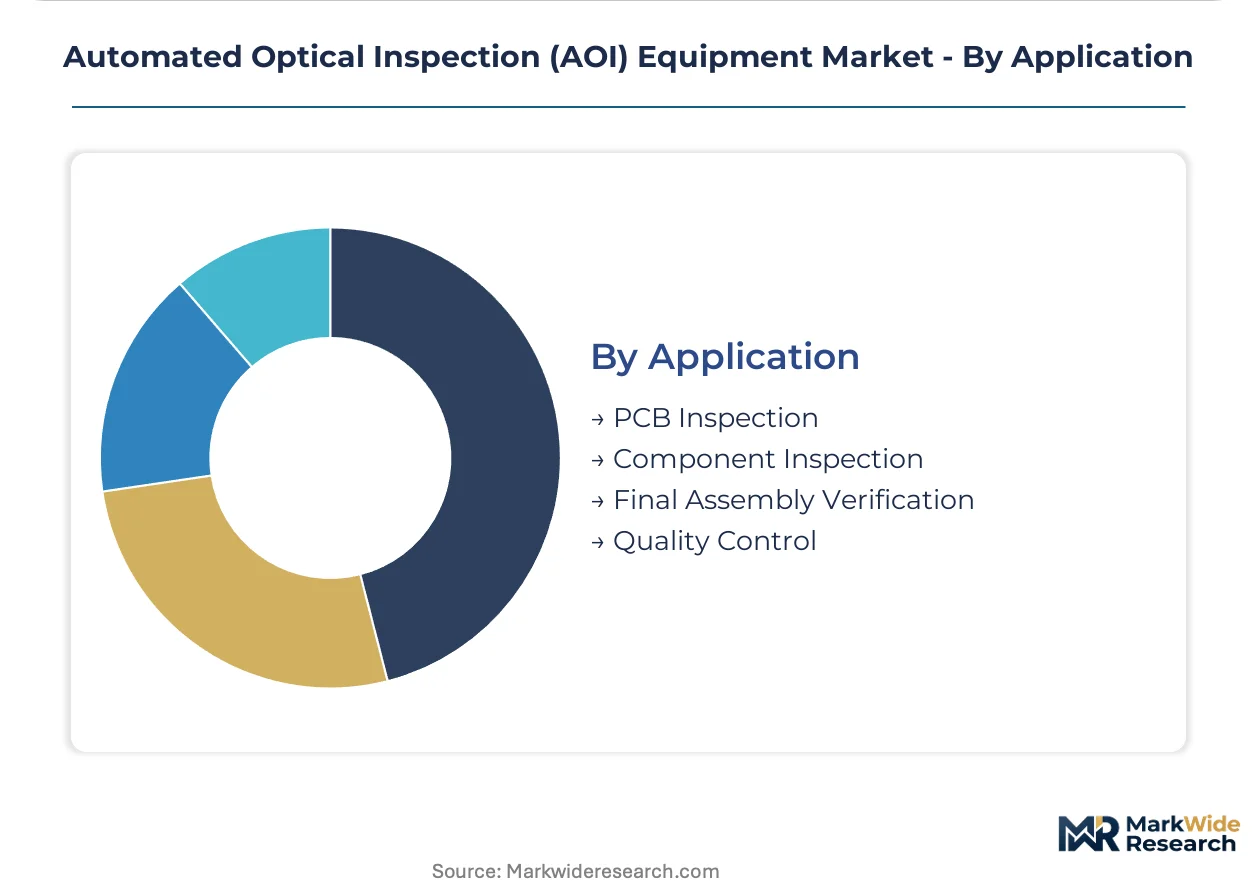
Application:
Process stage positioning determines inspection economics, with earlier defect detection delivering exponentially higher cost avoidance.
- PCB Inspection:Bare board and populated substrate verification captures trace anomalies, solder defects, and component placement errors before functional testing commits additional value. China's SAMR-mandated documentation requirements embed this as a non-discretionary production cost for consumer electronics contract manufacturers.
- Quality Control:Final verification gates before shipment protect against field failure liability and warranty exposure, particularly for automotive and medical end-uses where downstream failure costs dwarf inspection investment.
- Component Inspection:Pre-assembly verification of individual parts catches supplier quality excursions before they propagate into finished assemblies.
- Final Assembly Verification:System-level optical checks confirm mechanical integration and labeling compliance for regulatory traceability.
PCB inspection leads on scale; quality control leads on value capture as liability exposure concentrates investment at final verification stages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated optical inspection technology originated in Japanese electronics factories during the 1980s before migrating to Taiwan and South Korea as semiconductor packaging scaled. Today procurement patterns split between mature manufacturing clusters upgrading legacy lines and emerging contract manufacturing hubs installing greenfield capacity.
China
Domestic PCB production volume exceeds any other nation, with Yangtze River Delta and Pearl River Delta clusters driving equipment absorption. SAMR enforcement of GB standards for consumer electronics safety mandates inspection documentation at contract manufacturer level, embedding AOI as non-discretionary production infrastructure. Shenzhen and Suzhou production corridors concentrate the highest 3D AOI deployment densities for smartphone and laptop substrate inspection.
United States
Michigan automotive supplier corridors and Minnesota medical device clusters anchor North American demand for high-specification inspection systems. FDA quality system regulations for Class II and III electronic assemblies require validation documentation that favors AI-enhanced classification platforms. EPA hazardous substance reporting deadlines for electronics recyclers are accelerating hyperspectral imaging adoption among Michigan-based Tier-1 PCB assemblers.
Germany
Bavaria and Baden-Württemberg automotive electronics corridors face zero-defect contractual obligations from EV drivetrain OEMs that pull 3D AOI penetration ahead of European averages. REACH framework compliance mandates material traceability layers that legacy 2D inspection lines cannot satisfy. Munich and Stuttgart production clusters are retrofitting continuous-flow inline configurations to match throughput requirements of automotive supplier lines.
Japan
Kanto and Kansai regions retain foundational expertise in precision optics and vision system engineering that originated AOI technology decades ago. METI smart factory standards reward JIS-aligned vision-system integration with energy efficiency credits, subsidizing upgrade pathways for automotive PCB suppliers. Nagoya automotive electronics corridors and Osaka semiconductor packaging facilities concentrate domestic equipment demand.
South Korea
Seoul Capital Area and Busan-Ulsan semiconductor packaging clusters drive sub-micron z-axis resolution requirements as stacked die geometries proliferate. Domestic memory and logic foundry expansion sustains premium 3D AOI procurement despite pricing pressure from Chinese equipment vendors. Pyeongtaek and Hwaseong advanced packaging facilities represent the most demanding inspection specifications in global electronics manufacturing.
Automated Optical Inspection (AOI) Equipment Market Competitive Environment
The competitive structure tilts toward technology-integrated specialists rather than pure-play hardware vendors. Equipment producers with captive software development capabilities command pricing premiums over assembly-focused competitors. Two archetypes dominate: precision optics houses with telecentric lens fabrication expertise, and machine-learning-native platforms trained on multi-factory defect datasets. Consolidation pressure concentrates on mid-tier vendors lacking either optical component control or algorithmic differentiation. Strategic moves center on sensor supply partnerships and cloud-based training dataset pooling.
Among Korea-based technology-integrated specialists, Koh Young Technology exemplifies software-hardware convergence archetypes that anchor premium positioning in semiconductor packaging inspection. Test Research, Inc. occupies a position within the dense service network archetype, with geographic naming suggesting East Asian electronics manufacturing cluster proximity. Omron Corporation represents the diversified industrial automation conglomerate model, where vision systems sit within broader factory automation portfolios rather than standalone specialization.
| Leading Market Players |
|---|
| Koh Young Technology |
| Test Research, Inc. (TRI) |
| Omron Corporation |
| Viscom AG |
| Saki Corporation |
| Camtek |
| Nordson Corporation |
| CyberOptics Corporation |
| Mirtec Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Machine vision engineer scarcity in Taiwan and South Korea widens pricing-tier spreads, as algorithm-tuning expertise commands wage premiums that OEMs pass through to automotive and medical device buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade 3D AOI systems from automotive PCB inspection platforms and legacy 2D white goods configurations. Price differentiation hinges on sub-micron z-axis resolution certification and embedded machine learning classification modules. Pricing pressure stems from CMOS image sensor cost volatility as foundry allocation cycles compress hardware margins. Contract manufacturers in China's Pearl River Delta exhibit highest price sensitivity, while Minnesota medical device assemblers accept premium positioning for FDA-validated traceability software.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Taiwan semiconductor packaging facilities and South Korean memory foundries, while regional distributors serve mid-tier automotive PCB assemblers in Michigan and Bavaria. Component sourcing draws from German and Japanese precision optics houses for telecentric lenses, Chinese CMOS sensor fabricators, and South Korean edge inference chip suppliers. Single-source vulnerability concentrates in telecentric lens fabrication, where Schott and Nikon Precision dominate sub-micron specifications. Distribution runs through equipment lessors offering per-inspection pricing to Guadalajara and Penang EMS providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated optical inspection equipment functions as a stable compounder, with regulatory documentation mandates embedding recurring replacement demand across electronics manufacturing verticals.
For Market Incumbents: Extend software-hardware integration moats by pooling multi-factory defect datasets for machine learning model training, defending against algorithm-native entrants. Deepen captive optics capabilities through strategic partnerships with German telecentric lens fabricators, reducing single-source exposure. Prioritize API development for legacy MES integration to capture brownfield retrofit demand. For New Entrants and Emerging Players: Contract manufacturing service providers represent the most penetrable channel, particularly India's PLI-subsidized mobile hardware fabs requiring greenfield inline inspection infrastructure. Target high-mix low-volume medical device PCB assemblers in Minnesota and Bavaria with deep learning-based solder joint analysis for Class II prototype runs. Pursue edge-native AI retrofit markets for brownfield SMT lines through standalone per-inspection pricing models. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, consolidating mid-tier vendors lacking algorithmic differentiation or optical component control. Long-term viability centers on training dataset scale as the primary competitive moat. Watch for EPA hazardous substance reporting deadline acceleration as the signal triggering hyperspectral imaging module capex surges among Michigan automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Factory Dataset Pooling | Aggregated defect libraries from Taiwan and South Korea fabs improve classification accuracy without explicit rule programming. |
| Hyperspectral Imaging Module Launch | RoHS-restricted substance detection through spectral signature matching satisfies EPA documentation deadlines for Michigan recyclers. |
| Legacy MES API Development | Shop-floor database integration enables traceability handshakes with 1990s-era brownfield factories resisting modernization. |
| Edge Inference Chip Partnership | Real-time defect classification without cloud latency opens standalone retrofit markets for price-sensitive contract manufacturers. |
| Per-Inspection Pricing Model | Equipment leasing transfers balance-sheet liability to vendors while concentrating risk on uptime guarantees for Penang EMS providers. |
Study Parameters
Direct dialogue with AOI equipment procurement managers at Tier-1 automotive suppliers, semiconductor packaging engineers in Taiwan and South Korea, and FDA regulatory affairs leads at Minnesota medical device contract manufacturers grounded qualitative findings. Secondary validation drew from SAMR GB standard documentation, EPA hazardous substance reporting guidelines, METI smart factory credit specifications, and SEC filings of publicly traded industrial automation conglomerates. Bottom-up equipment shipment data triangulated against top-down electronics manufacturing value-add estimates.
Segment-level value outputs combined technology tier splits with end-use intensity scoring across automotive, medical, and consumer electronics verticals. Modeled dimensions spanned 2D versus 3D AOI configurations, machine learning versus rule-based classification architectures, and inline versus standalone deployment patterns. CAGRs derived from regression analysis of historical equipment replacement cycles and regulatory mandate enforcement timelines. Forecast inputs included semiconductor packaging miniaturization roadmaps and China's SAMR inspection documentation expansion schedules.
Revisions become necessary when CMOS image sensor foundry allocation disruptions, telecentric lens supply concentration failures, or multi-OEM validation complexity escalations materialize beyond base-case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Test Benches Market
Test and Measurement
Digital Thickness Gauge Market
Test and Measurement
Calibration Services Market
Test and Measurement
Europe Electronic Test and Measurement Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Calorimeters Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Marine Electronics Tester Market
Test and Measurement
DSL Tester Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Destructive Testing Market
Test and Measurement
Global Source Measure Unit Market