
 Reverberation Chambers Market | 2026-2036
Reverberation Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Reverberation Chambers Market Analysis
MIL-STD-461G compliance-grade specifications is reorganizing procurement priorities across the reverberation chambers market. ETS-Lindgren leverages its installed base in defense and aerospace testing to sustain premium positioning in North America. Frankonia Germany EMC Solutions GmbH anchors European demand through specialized chamber architectures for automotive EMC validation. Siepel competes on compact, modular designs that address space-constrained laboratory environments.
A reverberation chamber is an enclosed test environment with highly reflective interior surfaces that create a statistically uniform electromagnetic or acoustic field distribution, typically achieving field uniformity within specified tolerance limits across a defined test volume. Its primary purpose is to enable repeatable, standardized electromagnetic compatibility testing and acoustic measurement without the anechoic treatment required by alternative test methods. Multi-chamber configurations are capturing expanded share as integrated test sequences demand sequential acoustic and electromagnetic validation within unified workflows. Fixed installations retain dominant value share due to the structural permanence required for precision calibration, though portable chambers are gaining traction among acoustic consultants serving distributed manufacturing sites.
The FCC and FDA in the United States, alongside ETSI and CE marking requirements in Europe, mandate specific test environments that directly determine chamber design specifications and market access eligibility for equipment suppliers. ISO 17025 accreditation requirements further constrain vendor qualification, favoring established manufacturers with documented calibration traceability. Stakeholders must monitor evolving automotive EMC protocols and 5G device testing standards to align chamber capability roadmaps with imminent regulatory scope expansion.
Market Dynamics
MIL-STD-461G compliance specifications are reorganizing procurement priorities across defense and aerospace testing facilities, forcing chamber manufacturers to reengineer shielding architectures and calibration protocols.
Growth Catalysts
- Automotive EMC validation:Electric vehicle platforms require new acoustic and electromagnetic compatibility testing protocols that reverberation chambers uniquely provide.
- FCC mandate expansion:Updated electromagnetic compatibility testing requirements in the United States are compelling facilities to upgrade chamber specifications.
- German automotive cluster concentration:Stuttgart and Munich aerospace and automotive engineering centers drive precision testing infrastructure investment.
Market Restraints
- Specialized steel alloy costs:Mu-metal and galvanized steel price volatility constrains chamber construction budgets.
- Calibration equipment supplier concentration:Precision field probe and signal generator sourcing depends on a limited vendor base in Japan and Germany.
- Anechoic chamber substitution:Free-space test methods compete for certain wireless device validation applications.
Strategic Opportunities
- India automotive testing:Chennai and Pune manufacturing corridors lack certified reverberation capacity for domestic OEM export compliance.
- 5G millimeter-wave device validation:FR2 frequency band testing creates demand for compact, high-frequency chamber designs.
- EU Green Deal alignment:Energy-efficient chamber HVAC and lighting retrofits attract sustainability-linked procurement preferences.
Industry Challenges
- ISO 17025 calibration technician scarcity:Qualified metrology specialists with chamber-specific expertise command premium compensation.
- Legacy facility retrofit complexity:Existing anechoic chambers require structural reinforcement to accommodate reverberation mode stirrers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverberation Chambers Market |
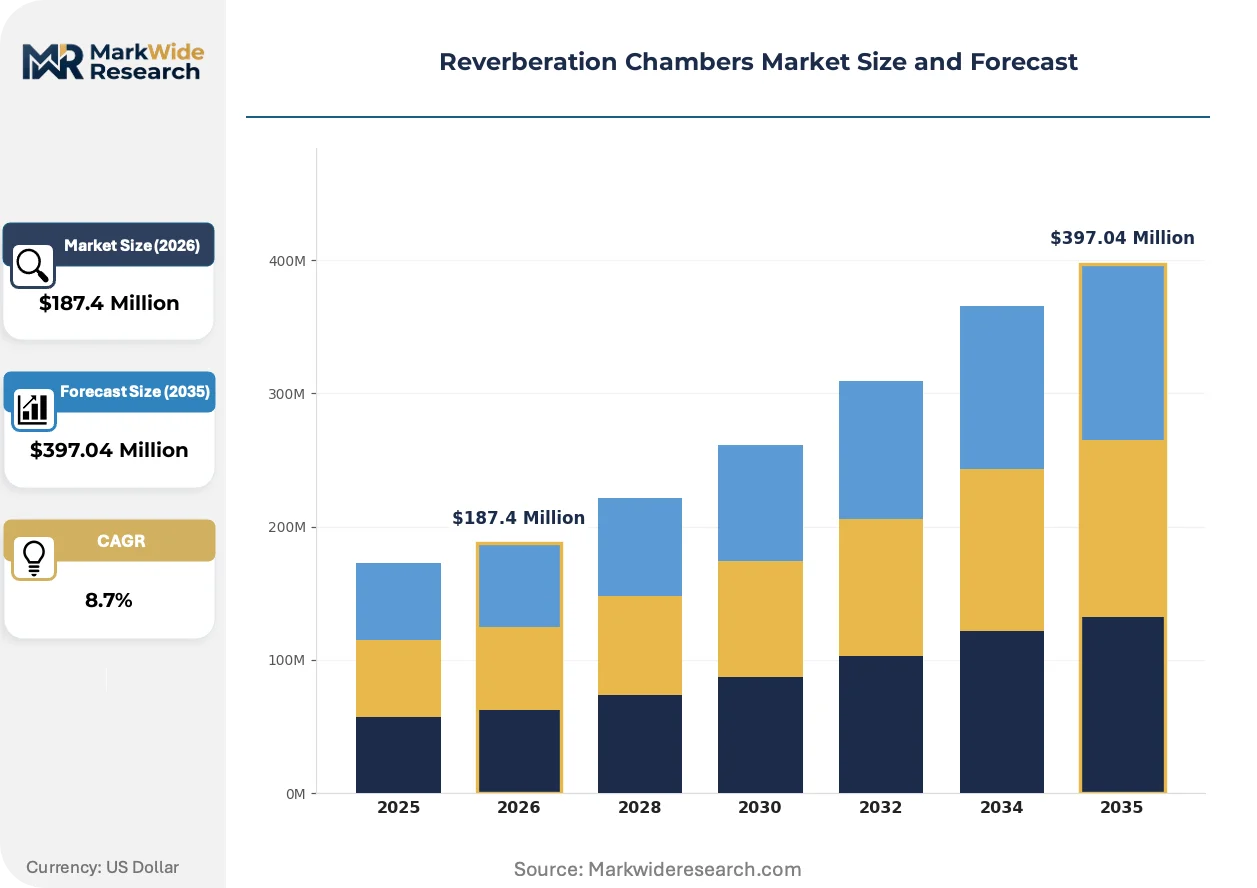
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Multi-Chamber, Acoustic Panels, Sound Absorbers Application: Research Testing, Sound Quality Assessment, Environmental Testing, Product Validation End User: Educational Institutions, Research Facilities, Acoustic Consultants, Manufacturers Installation Type: Fixed Installation, Portable Chambers, Semi-Permanent Structures, Custom Builds |
| Companies Covered | Siepel, AMETEK CTS, IAC Acoustics, Brüel & Kjær Sound & Vibration Measurement A/S, Eckel Industries, ETS-Lindgren, Kapolnek Acoustics India, Reed Electronique SCA, Frankonia Germany EMC Solutions GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverberation Chambers Market Emerging Trajectories
Reverberation chamber architectures are converging with automated test execution platforms, compressing validation timelines for multi-protocol device certification.
Mechanical mode-stirring systems with programmable paddle geometries are displacing fixed-geometry chamber designs in high-throughput automotive EMC facilities. Tier-1 suppliers in Germany and Japan are adopting these systems to accommodate sequential acoustic and electromagnetic test sequences. This displacement is compressing chamber commissioning timelines from months to weeks.
CE marking requirements under the EU Radio Equipment Directive are mandating expanded immunity test levels for connected industrial equipment. Chamber manufacturers must now document field uniformity across broader frequency ranges to maintain market access eligibility. Automotive and medical device segments in France and Italy are accelerating facility upgrades to meet these specifications.
Integrated test sequences now demand unified workflows that combine acoustic NVH and electromagnetic validation within single facility footprints. Tier-1 automotive suppliers are consolidating previously separate test departments to reduce capital duplication. This consolidation pattern is most visible in southern Germany, where OEMs co-locate electric powertrain and infotainment system validation.
Reverberation Chambers Market Segmentation
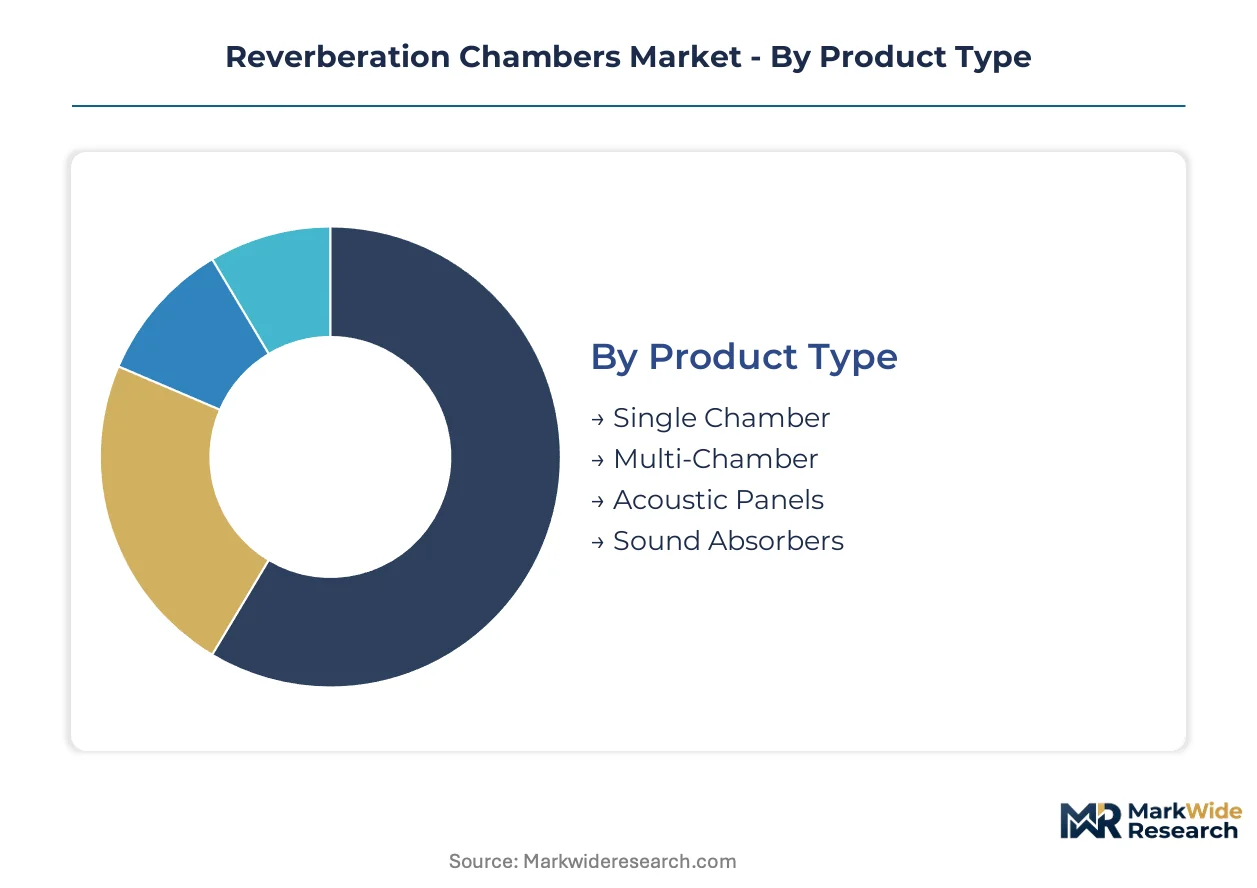
Reverberation chamber procurement diverges sharply across installation contexts, with automotive EMC validation demanding permanent precision infrastructure while acoustic consulting services favor mobility. Segment boundaries are blurring as integrated test sequences force hybrid configurations that span traditional product categories.
Product Type:
Margin pools concentrate in multi-chamber systems where sequential acoustic and electromagnetic validation commands premium pricing from automotive OEMs consolidating test footprints.
- Single Chamber:Enclosed test environments with reflective interior surfaces achieve field uniformity for standardized EMC or acoustic measurement in a single controlled volume. German automotive suppliers in Stuttgart deploy these for dedicated electric powertrain NVH validation where test protocols remain siloed.
- Multi-Chamber:Interconnected test volumes enable sequential electromagnetic and acoustic validation without specimen relocation, compressing certification timelines. Tier-1 suppliers in southern Germany are consolidating previously separate EMC and NVH departments around these configurations to eliminate capital duplication.
- Acoustic Panels:Modular surface treatments tune reverberation characteristics for specific frequency ranges in retrofit applications.
- Sound Absorbers:Complementary components manage edge effects and modal distribution in hybrid chamber designs.
The dominant share belongs to single chamber configurations, while multi-chamber systems are closing the gap fastest.
Application:
Volume concentrates in product validation where OEM export compliance mandates drive repeat procurement cycles across manufacturing corridors.
- Research Testing:Universities and national laboratories employ chambers for fundamental acoustic and electromagnetic field studies. Indian engineering institutes in Chennai lack certified capacity for domestic automotive export compliance, creating procurement backlogs.
- Sound Quality Assessment:Automotive infotainment and electric vehicle pedestrian warning systems require precise acoustic signature characterization. Munich-based OEMs co-locate these facilities with powertrain EMC validation to unify electric vehicle certification workflows.
- Environmental Testing:Chambers simulate combined thermal, humidity, and electromagnetic stress conditions for aerospace component qualification.
- Product Validation:Final certification testing before market entry demands documented field uniformity traceable to ISO 17025 standards.
Product validation commands the largest revenue pool, though sound quality assessment is climbing fastest as electric vehicle acoustic regulations tighten.
End User:
Cost tier differentiation separates capital-intensive permanent installations from service-based consulting models with divergent procurement cycles.
- Educational Institutions:Universities prioritize compact, modular designs for graduate training and sponsored research programs.
- Research Facilities:National metrology institutes demand MIL-STD-461G compliance-grade specifications with documented calibration traceability.
- Acoustic Consultants:Portable chamber configurations serve distributed manufacturing sites where on-site validation reduces specimen transport risk. These operators compete on rapid deployment timelines measured in days rather than months.
- Manufacturers:Automotive and medical device producers in France and Italy are accelerating facility upgrades to meet expanded CE marking immunity test levels under the EU Radio Equipment Directive.
Manufacturers retain the dominant procurement volume, while acoustic consultants are expanding their share fastest through portable service models.
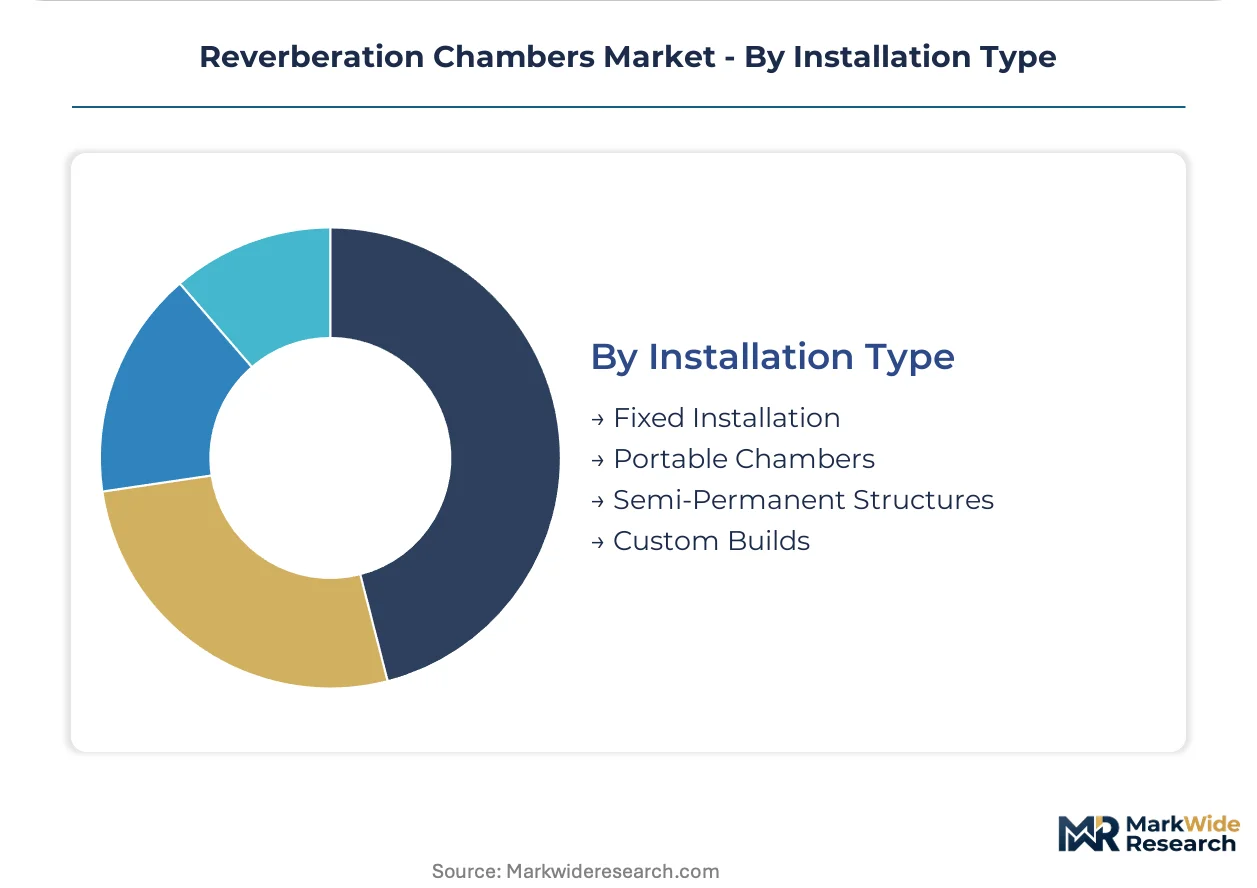
Installation Type:
Supply concentration favors fixed installations where structural permanence enables precision calibration, though modularity is reshaping competitive dynamics.
- Fixed Installation:Permanent steel and mu-metal structures provide the dimensional stability required for precision field uniformity calibration. These dominate defense and aerospace testing where MIL-STD-461G specifications mandate documented shielding effectiveness.
- Portable Chambers:Deployable enclosures serve acoustic consultants conducting distributed manufacturing site validation. Japanese and German Tier-1 suppliers are adopting programmable mechanical mode-stirring systems in these formats to compress commissioning timelines.
- Semi-Permanent Structures:Hybrid designs balance mobility with performance for multi-year production facility deployments.
- Custom Builds:Bespoke architectures accommodate non-standard specimen dimensions or extreme frequency range requirements.
Fixed installations hold the dominant value position, while portable chambers are gaining share fastest among acoustic service providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication and precision calibration expertise concentrate in Germany, the United States, and Japan, while emerging automotive manufacturing corridors in India and Mexico are generating new chamber procurement cycles. Chamber vendors maintain engineering centers proximate to defense and aerospace clusters to support MIL-STD-461G compliance validation. Regulatory divergence across FCC, CE marking, and BIS standards is forcing manufacturers to maintain jurisdiction-specific certification capabilities.
United States
Defense and aerospace testing facilities in California and Texas drive demand for MIL-STD-461G compliant chambers with documented shielding effectiveness. FCC mandate expansion for 5G device electromagnetic compatibility is compelling upgrade cycles at existing EMC laboratories. Boston-area medical device manufacturers are accelerating facility investments to meet FDA electromagnetic compatibility validation requirements for connected health equipment.
Germany
Automotive OEMs in Stuttgart and Munich are consolidating EMC and NVH test departments around multi-chamber configurations to eliminate capital duplication. CE marking requirements under the EU Radio Equipment Directive mandate expanded immunity test levels for connected industrial equipment. Bavarian aerospace suppliers are procuring programmable mechanical mode-stirring systems to compress commissioning timelines from months to weeks.
Japan
Precision electronics manufacturers in the Kanto and Kansai regions require high-frequency chamber designs for FR2 millimeter-wave device validation. METI industrial standards alignment with international EMC protocols is driving replacement of legacy fixed-geometry installations. Tier-1 automotive suppliers in Nagoya are adopting compact, modular chamber architectures to accommodate space-constrained laboratory environments.
India
Chennai and Pune manufacturing corridors lack certified reverberation capacity for domestic OEM export compliance, creating procurement backlogs for European and Japanese automotive testing standards. BIS electromagnetic compatibility regulations are tightening alignment with ETSI and FCC specifications for telecommunications equipment. Engineering institutes in Tamil Nadu are seeking compact chamber designs for graduate training and sponsored research programs.
China
MIIT certification requirements for 5G base station equipment are expanding demand for high-frequency chamber infrastructure in Shenzhen and Shanghai. GB standards evolution for automotive electromagnetic compatibility is forcing chamber architecture redesigns for domestic EV platform validation. Yangtze River Delta electronics manufacturers are investing in multi-chamber systems to unify acoustic and electromagnetic test workflows under single facility footprints.
Reverberation Chambers Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision calibration specialists commanding premium positioning against modular system fabricators. The vendor base spans three tiers: defense-aerospace specialists with MIL-STD documentation capabilities, automotive-focused integrators with multi-chamber expertise, and compact-system providers serving space-constrained laboratories. Strategic differentiation centers on calibration traceability documentation and programmable mode-stirring engineering. Competitive moves concentrate on geographic expansion into Indian and Mexican automotive corridors and technology licensing partnerships for high-frequency FR2 designs.
Among European specialists, Frankonia Germany EMC Solutions GmbH anchors the premium-tier segment through specialized chamber architectures for automotive EMC validation. ETS-Lindgren occupies a position within the defense-aerospace archetype, leveraging established relationships with North American military testing facilities. Siepel exemplifies the compact-system vector, competing on modular designs that address laboratory space constraints. These three players represent distinct strategic postures without overlapping capability claims.
| Leading Market Players |
|---|
| Siepel |
| AMETEK CTS |
| IAC Acoustics |
| Brüel & Kjær Sound & Vibration Measurement A/S |
| Eckel Industries |
| ETS-Lindgren |
| Kapolnek Acoustics India |
| Reed Electronique SCA |
| Frankonia Germany EMC Solutions GmbH |
| Others |
Supply Flow & Price Mechanics
ISO 17025 accreditation requirements simultaneously gate supplier qualification and stratify price tiers across the reverberation chambers market, compressing vendor pools while expanding premium positioning for documented calibration traceability. Buyers face bifurcated procurement economics where certification-grade specifications command substantial premiums over modular alternatives.
Pricing Analysis
MIL-STD-461G compliance dictates the pricing tier structure across defense and aerospace procurement channels, separating premium-grade shielding architectures from standard commercial configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ISO 17025 traceability and programmable mode-stirring capability driving top-tier differentiation. Cost compression in economy-tier portable chambers is intensifying because Japanese and German suppliers are flooding acoustic consulting segments with compact modular designs. Research facilities exhibit lowest price sensitivity due to grant-funded capital cycles, while acoustic consultants serving distributed manufacturing sites demonstrate acute cost consciousness.
Supply Chain Analysis
Extended lead times for mu-metal and specialized galvanized steel alloys are stretching chamber construction timelines from procurement to commissioning. Supply concentrates in Germany, the United States, and Japan, where precision calibration expertise and steel fabrication capabilities co-locate with defense and automotive testing clusters. Raw material dependencies rest on nickel-iron alloy foundries in Germany, high-grade steel mills in Japan, and precision field probe manufacturers in Germany and Japan. Single-source vulnerability in calibration equipment sourcing from Japanese and German vendors creates procurement risk. Distribution runs through direct OEM relationships for fixed installations and rental-service networks for portable configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as integrated test sequences dissolve traditional boundaries between acoustic and electromagnetic validation, creating specialist niches for hybrid chamber architects. Electric vehicle platform proliferation is spawning demand pockets underserved by legacy single-protocol vendors.
For Market Incumbents: Consolidate defensive positions around programmable mode-stirring intellectual property and MIL-STD-461G documentation capabilities to repel modular competitors encroaching from below. Deepen backward integration into mu-metal supply through captive sourcing arrangements with German foundries. Expand calibration service attach rates to lock in recurring revenue streams against anechoic chamber substitution threats. For New Entrants and Emerging Players: ISO 17025 fast-track certification programs in India offer the most penetrable entry vector, as Chennai and Pune manufacturing corridors lack certified reverberation capacity for domestic OEM export compliance. Target compact, modular chamber designs for space-constrained automotive Tier-1 laboratories in Japan and southern Germany. Pursue technology licensing partnerships with established German vendors to shortcut FR2 millimeter-wave design validation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-chamber system configurations as automotive OEMs consolidate previously separate EMC and NVH departments. Long-term viability favors vendors with documented calibration traceability and defense-aerospace installed bases. Target acquisition archetype: mid-cap specialists with ISO 17025 accreditation and programmable mode-stirring engineering teams. Signal to watch: BIS electromagnetic compatibility regulation tightening in India triggering procurement backlog clearance.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Chamber Configuration Deployment | Tier-1 automotive suppliers in Stuttgart consolidate EMC and NVH validation to eliminate capital duplication. |
| Programmable Mode-Stirring Investment | Bavarian aerospace suppliers compress commissioning timelines from months to weeks. |
| ISO 17025 Accreditation Expansion | Chamber manufacturers document calibration traceability to maintain market access eligibility. |
| FR2 Millimeter-Wave Design Licensing | Japanese precision electronics manufacturers validate 5G device performance in high-frequency chambers. |
| India Automotive Testing Facility Buildout | Chennai and Pune corridors address certified reverberation capacity gaps for domestic OEM export compliance. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and industry association disclosures across the reverberation chambers market. Primary interviews engaged chamber manufacturer engineering directors, automotive OEM test facility managers, EMC laboratory procurement leads, and national metrology institute calibration specialists. Secondary validation drew from FCC equipment authorization databases, ETSI harmonized standards publications, BIS certification registries, and ISO 17025 accreditation body records. Bottom-up demand modeling triangulated against top-down market sizing through steel consumption patterns and precision electronics import data.
Segmentation dimensions modeled include product type, application context, end-user archetype, and installation format across the projection horizon. Analytical framework derived CAGRs through regression analysis of historical procurement cycles correlated with regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated electric vehicle platform rollout schedules and 5G FR2 device certification trajectories. Automotive EMC protocol evolution and CE marking immunity test level expansion shaped scenario weightings.
Underlying assumptions cover regulatory mandate adherence timelines and steel alloy price stability, with deviation risk concentrated in BIS electromagnetic compatibility regulation acceleration and mu-metal supply disruption. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when defense procurement budget reallocations or automotive platform standardization shifts cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
PXI SMU Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Test and Measurement Equipment Market
Test and Measurement
Telescopic Inspection Mirror Market
Test and Measurement
Clamp Meters Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Metrology Services Market
Test and Measurement
Surface Measurement Equipment and Tools Market
Test and Measurement
Global Leak Test Equipment Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Shock Testing System Market