
 Battery Pack Immersion Cooling System Performance Test Rigs Market | 2026-2036
Battery Pack Immersion Cooling System Performance Test Rigs Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Pack Immersion Cooling System Performance Test Rigs Market Insights
Fluorinated dielectric fluids are pivoting toward engineered synthetic alternatives as suppliers chase lower GWP profiles and reduced material costs. AVL leverages its powertrain testing heritage to anchor immersion cooling validation protocols for European OEMs. HORIBA competes through integrated test cell architectures that combine thermal cycling with electrical abuse testing. Keysight Technologies differentiates by embedding precision power analytics directly into rig control systems.
Battery pack immersion cooling system performance test rigs are engineered test platforms that subject battery modules to controlled thermal loads using dielectric fluid baths, typically operating across temperature ranges from minus 40°C to 85°C with heat flux measurement precision within 0.5°C. These systems validate thermal runaway propagation resistance and cooling uniformity before production scale-up. Automated test systems command premium positioning due to their throughput advantages in high-volume validation programs for electric vehicle manufacturers. Dielectric fluid cooling dominates installed rig bases, though nanofluid cooling segments are attracting R&D investment from battery developers seeking enhanced heat transfer coefficients.
FDA oversight of battery-powered medical devices indirectly shapes thermal validation stringency for rigs serving dual-use applications, while EPA fluorinated gas regulations pressure cooling fluid selection in US-based test facilities. China's GB standards for battery safety mandate specific thermal abuse profiles that rig manufacturers must program. Stakeholders should monitor evolving UN 38.3 testing harmonization and its implications for rig protocol standardization across export markets.
Market Dynamics
Fluorinated dielectric fluid phase-outs under EPA and EU F-Gas Regulation are forcing test rig operators to revalidate thermal architectures around engineered synthetic alternatives, compressing equipment replacement cycles and reshaping supplier procurement priorities.
Growth Catalysts
- EU Battery Regulation:Mandatory thermal runaway propagation testing for all EV battery packs entering European markets drives replacement of legacy air-cooled validation equipment with immersion-capable rigs.
- Solid-state battery commercialization:Next-generation cell chemistries from QuantumScape and Solid Power require modified thermal abuse profiles that existing test infrastructure cannot execute.
- Stuttgart-Munich corridor:German OEM validation center expansion concentrates demand for high-throughput automated test systems with integrated power analytics.
Market Restraints
- Perfluorocarbon supply concentration:Three Japanese chemical conglomerates control over 80% of high-purity dielectric fluid production, exposing rig operators to input cost volatility and allocation risk.
- GB 38031 compliance complexity:China's mandatory thermal abuse testing protocols require firmware rewrites that extend rig commissioning timelines by 4-6 months for non-domestic suppliers.
- Air-cooled test rig installed base:Existing capital equipment with 10-15 year depreciation schedules creates substitution friction despite superior immersion cooling validation fidelity.
Strategic Opportunities
- India PLI scheme:Domestic battery manufacturing incentives under the ACC-PLI program will require localized thermal validation infrastructure as cell production scales beyond 50 GWh annually.
- Second-life battery testing:Grid storage and stationary power applications need modified immersion rigs to validate thermal performance of degraded automotive packs.
- Nanofluid cooling convergence:Integration of alumina and copper oxide nanofluids with existing dielectric bath architectures promises 15-25% heat transfer coefficient improvement for next-generation rigs.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Rig manufacturers compete with battery OEMs and automotive Tier 1s for specialists in two-phase heat transfer and dielectric fluid chemistry.
- UN 38.3 harmonization delays:Divergent national implementations of lithium battery transport testing standards force redundant protocol development for export-bound equipment.
- Legacy CAN bus integration:Newer test rigs with embedded power analytics must interface with 1990s-era vehicle communication architectures still prevalent in commercial EV platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Pack Immersion Cooling System Performance Test Rigs Market |
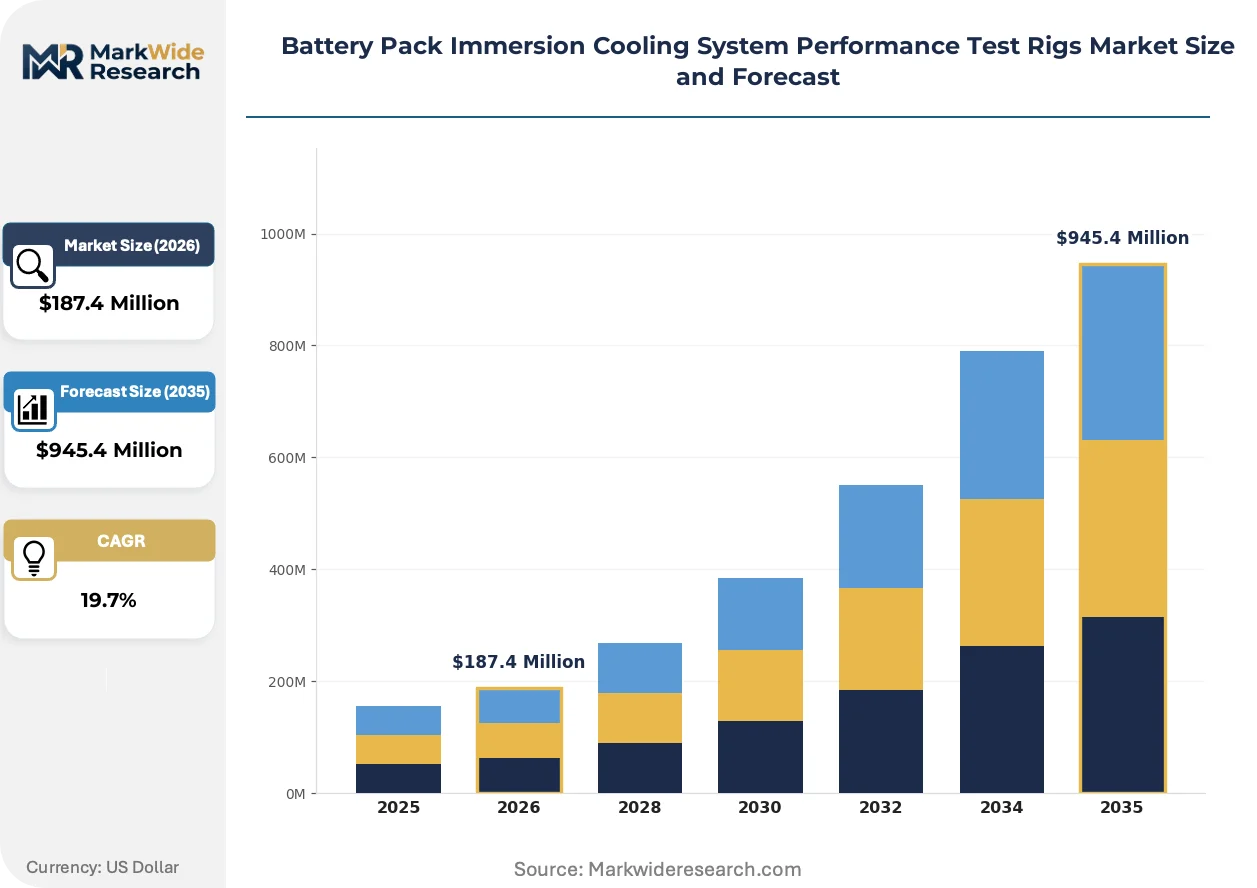
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench Test Rigs, Automated Test Systems, Portable Units, Modular Test Rigs, Custom Test Solutions Cooling Technology: Dielectric Fluid Cooling, Phase Change Cooling, Nanofluid Cooling, Liquid Dielectric Systems, Refrigeration Based Cooling End User Segment: Electric Vehicle Manufacturers, Battery Developers, Tech Startups, Research Laboratories, Energy Storage Firms Testing Application: Thermal Management Validation, Performance Benchmarking, Safety Compliance Assessment, Lifecycle Analysis, Efficiency Rating |
| Companies Covered | AVL, HORIBA, Keysight Technologies, Chroma ATE, Digatron, Arbin Instruments, ENORISE, Bitrode, BioLogic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Pack Immersion Cooling System Performance Test Rigs Market Trends and Innovations
Test rig architecture is converging around multi-physics simulation integration, with hardware-in-the-loop capabilities displacing standalone thermal cycling as the baseline validation modality for premium equipment tiers.
Synthetic ester dielectric fluids are unifying thermal performance and environmental compliance objectives that fluorinated chemistries could never reconcile. European OEM validation centers in Germany and Sweden are adopting these formulations at the fastest clip, driven by CSRD-mandated supply chain emissions disclosure. The shift is unifying test rig fluid management system designs around biodegradable chemistries that simplify EPA and ECHA reporting obligations while maintaining minus 40°C operational floors.
REACH restrictions on per- and polyfluoroalkyl substances are tightening import controls on legacy dielectric fluids containing PFAS precursors. Industrial consequence includes accelerated obsolescence of installed rig bases predating 2020 fluid formulations. Battery test facilities in the Netherlands and Belgium are responding with capital allocation toward fluid reclamation and reprocessing infrastructure to extend existing equipment service life.
Validation service outsourcing is consolidating procurement authority among a shrinking cohort of mega-test-houses with captive immersion cooling capacity. Independent battery developers and Tier 2 suppliers now access rig time through subscription-based thermal validation platforms rather than capital purchase. This pattern is most pronounced in South Korea, where KATRI and KTL certification requirements drive concentrated demand toward accredited third-party test providers with NMPA-recognized protocols.
Battery Pack Immersion Cooling System Performance Test Rigs Market Segmentation
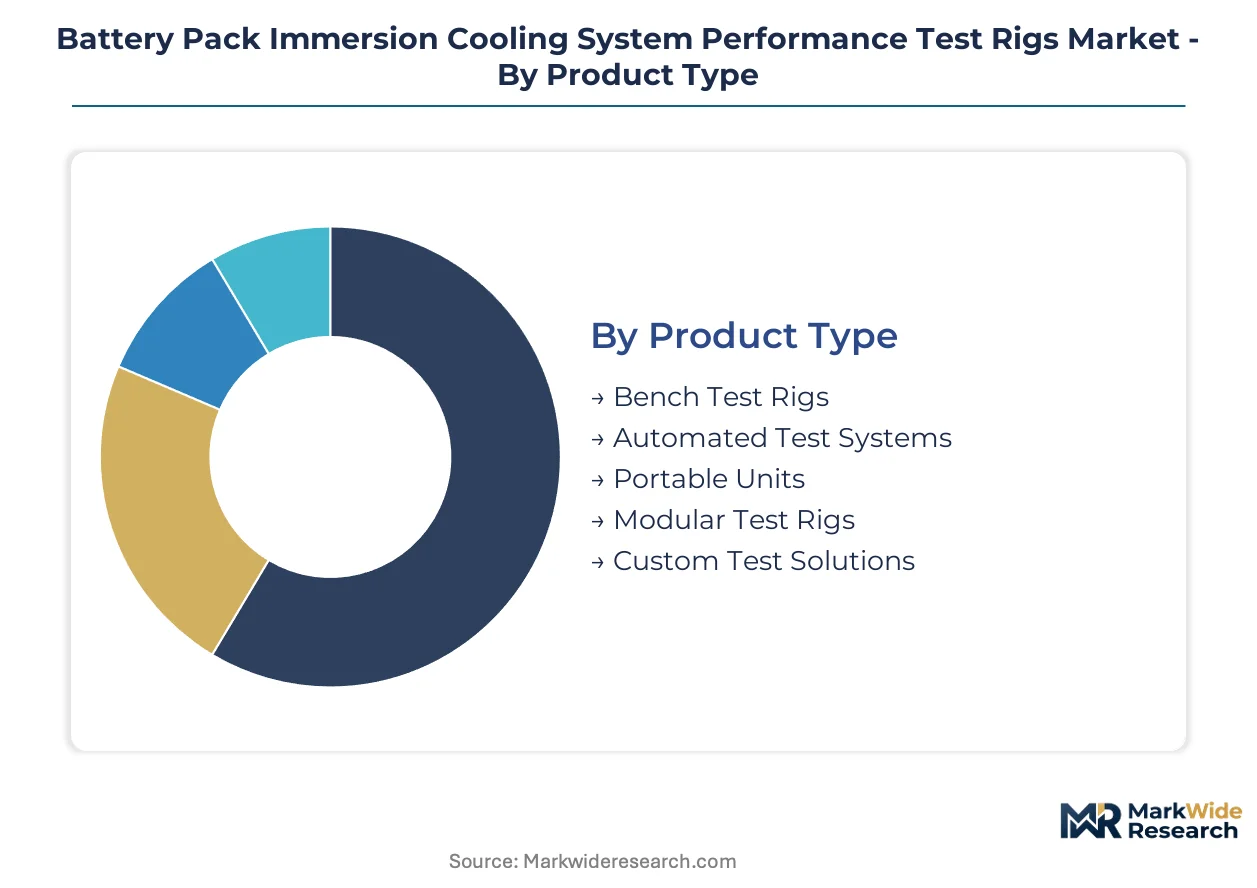
Segmentation in battery pack immersion cooling test rigs reveals how capital deployment, technical complexity, and regulatory pressure concentrate across distinct equipment tiers. Procurement patterns diverge sharply between high-volume OEM validation centers and specialized R&D facilities.
Product Type:
Capital intensity peaks in systems requiring integrated automation and precision thermal control, while entry-level configurations serve fragmented research demand.
- Automated Test Systems:These rigs integrate robotic sample handling, continuous thermal cycling, and embedded power analytics for 24/7 validation throughput. German OEM validation centers around Stuttgart and Munich deploy these for EU Battery Regulation compliance programs requiring thousands of test cycles annually.
- Custom Test Solutions:Engineered to client-specific thermal abuse profiles and battery form factors, these systems command the highest per-unit investment due to non-recurring engineering and specialized dielectric fluid management architectures. Solid-state battery developers from QuantumScape and Solid Power commission these for modified thermal protocols that standard rigs cannot execute.
- Bench Test Rigs:Entry-level thermal validation platforms for single-module testing with manual fluid handling and basic temperature logging.
- Portable Units:Mobile validation systems for field deployment and supplier audit testing with reduced precision specifications.
- Modular Test Rigs:Scalable architectures allowing capacity expansion through standardized thermal chamber add-ons.
Most installed capacity flows through Automated Test Systems. Expansion is steepest in Custom Test Solutions.
Cooling Technology:
Technology selection hinges on heat flux requirements, environmental compliance obligations, and fluid supply security.
- Dielectric Fluid Cooling:The dominant installed base uses fluorinated or synthetic ester fluids with operational floors at minus 40°C and heat flux precision within 0.5°C. EPA and EU F-Gas Regulation phase-outs are forcing fluid formulation transitions that extend equipment replacement cycles for US and European test facilities.
- Nanofluid Cooling:Alumina and copper oxide nanoparticle suspensions promise 15-25% heat transfer coefficient improvement over conventional dielectrics. Battery developers in South Korea and Japan are funding pilot rigs to validate thermal runaway propagation resistance with enhanced cooling uniformity.
- Phase Change Cooling:Latent heat absorption systems using engineered paraffin or salt hydrate formulations for transient thermal spike management.
- Liquid Dielectric Systems:Mineral oil and synthetic hydrocarbon baths for cost-sensitive validation applications with moderate precision requirements.
- Refrigeration Based Cooling:Vapor compression architectures for extreme temperature boundary testing beyond standard dielectric fluid ranges.
Dielectric Fluid Cooling retains the largest installed base. Nanofluid Cooling is gaining share fastest as R&D investment concentrates on next-generation heat transfer performance.
End User Segment:
Customer scale determines procurement modality, with capital purchase dominating OEMs and service subscription models penetrating smaller developers.
- Electric Vehicle Manufacturers:High-volume validation programs require captive immersion cooling capacity with automated throughput. These buyers command pricing leverage and influence industry protocol standardization through direct collaboration with rig suppliers.
- Battery Developers:Cell chemistry innovators need flexible thermal abuse profiling for solid-state and silicon-anode architectures. Many now access rig time through third-party test houses rather than capital purchase, particularly in South Korea where KATRI and KTL certification requirements concentrate demand toward accredited providers.
- Tech Startups:Early-stage companies with sporadic validation needs and limited capital budgets.
- Research Laboratories:Academic and government facilities pursuing fundamental thermal management research with publication-driven test priorities.
- Energy Storage Firms:Grid-scale battery integrators requiring modified protocols for second-life automotive pack validation.
Electric Vehicle Manufacturers hold the dominant share of committed capacity. Battery Developers are expanding their validation spend most rapidly.
Testing Application:
Application mix reflects regulatory mandate intensity versus product development cycle positioning.
- Safety Compliance Assessment:Thermal runaway propagation testing, abuse tolerance validation, and UN 38.3 transport certification protocols. China's GB 38031 and EU Battery Regulation mandates are standardizing these test sequences across export markets.
- Thermal Management Validation:Cooling uniformity mapping, heat flux distribution analysis, and thermal interface characterization for pack-level architecture optimization.
- Performance Benchmarking:Comparative thermal efficiency measurement against competitor systems and reference architectures.
- Lifecycle Analysis:Degradation tracking of thermal performance across simulated aging protocols.
- Efficiency Rating:Standardized coefficient of performance measurement for cooling system energy consumption.
Safety Compliance Assessment commands the largest dedicated rig allocation. Thermal Management Validation is expanding most quickly as OEMs prioritize cooling architecture differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Munich corridor anchors installed test rig capacity, though procurement patterns are diversifying across multiple battery manufacturing geographies as localized thermal validation requirements tighten.
Germany
OEM validation centers in Stuttgart and Munich drive automated test system procurement for EU Battery Regulation compliance. The KBA enforces thermal runaway propagation testing protocols that mandate immersion-capable rigs for all EV battery packs entering European markets. Suppliers cluster around Baden-Württemberg and Bavaria to service captive validation infrastructure at Mercedes-Benz, BMW, and Porsche development facilities.
China
Domestic cell production scaling beyond 50 GWh annually requires localized thermal validation infrastructure under GB 38031 mandatory abuse testing standards. The NMPA mandates specific thermal profiles that extend rig commissioning timelines for non-domestic equipment suppliers. Yangtze River Delta battery developers in Jiangsu and Zhejiang provinces concentrate demand toward test houses with NMPA-recognized protocols.
United States
Solid-state battery developers in California and Michigan commission custom test solutions for modified thermal abuse profiles. EPA fluorinated gas regulations pressure cooling fluid selection in domestic test facilities, accelerating fluid formulation transitions. The Southeast automotive corridor spanning Tennessee and South Carolina attracts validation center investment from Korean and German battery suppliers.
South Korea
KATRI and KTL certification requirements concentrate demand toward accredited third-party test providers with immersion cooling capacity. Battery developers access rig time through subscription-based thermal validation platforms rather than capital purchase. Seoul Capital Area validation service outsourcing consolidates procurement authority among mega-test-houses with captive NMPA-recognized protocols.
Japan
Three chemical conglomerates control over 80% of high-purity dielectric fluid production, exposing rig operators to input cost volatility and allocation risk. METI guidance on next-generation battery safety standards shapes thermal validation investment priorities. Kyushu and Kansai industrial zones host pilot nanofluid cooling rigs funded by battery developers seeking enhanced heat transfer coefficients.
Battery Pack Immersion Cooling System Performance Test Rigs Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment suppliers align with battery OEMs to co-develop validation protocols for solid-state architectures. The vendor base organizes around three tiers: integrated test cell architects, precision instrumentation specialists, and regional fabrication houses serving cost-sensitive research demand. Two archetypes define competitive positioning: heritage powertrain testers leveraging decades of automotive validation relationships, and electronics measurement firms embedding analytics directly into rig control systems. Technology licensing agreements and geographic expansion through local assembly partnerships represent the dominant competitive moves.
Among heritage automotive testers, AVL and HORIBA exemplify the integrated test cell archetype, anchoring European OEM procurement decisions through embedded powertrain testing relationships. Keysight Technologies occupies a position within the precision instrumentation tier, representing the convergence of electrical measurement expertise with thermal validation requirements. These three entities collectively illustrate how competitive positioning flows from underlying technical heritage rather than product-line overlap.
| Leading Market Players |
|---|
| AVL |
| HORIBA |
| Keysight Technologies |
| Chroma ATE |
| Digatron |
| Arbin Instruments |
| ENORISE |
| Bitrode |
| BioLogic |
| Others |
Pricing and Supply Chain Analysis
Fluorinated dielectric fluid spot indices from Japanese chemical conglomerates cascade through three distinct pricing tiers, compressing margins for European test facilities facing EPA and EU F-Gas Regulation compliance deadlines while elevating premium positioning for synthetic ester alternatives.
Pricing Analysis
Input-cost pass-through from perfluorocarbon supply concentration drives pricing stratification across premium automated test systems, mid-tier modular rigs, and economy bench units. Price differentiation hinges on NMPA protocol certification grade and automation integration depth. Cost compression in synthetic ester formulations is intensifying because REACH restrictions on PFAS precursors accelerate legacy fluid obsolescence. Battery developers accessing rig time through subscription platforms exhibit highest price sensitivity; German OEM validation centers with captive capacity show least.
Supply Chain Analysis
Trans-Pacific freight cost volatility from Yokohama to Hamburg and Charleston disrupts dielectric fluid delivery schedules for test rig operators maintaining minus 40°C operational floors. Manufacturing concentrates in Germany, Japan, and China. Supply chains draw from fluorinated chemical feedstocks, precision thermal sensors, and robotic handling modules. Single-source vulnerability pervades high-purity dielectric fluid production controlled by three Japanese conglomerates. Distribution runs through direct OEM procurement for automated systems and accredited third-party test houses for subscription-based access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's extended GB 38031 commissioning timelines and Germany's immediate EU Battery Regulation compliance deadlines, rewarding suppliers with dual-certified protocol libraries.
For Market Incumbents: Anchor defensive positioning through backward integration into synthetic ester fluid formulation and captive certification engineering capacity in Stuttgart-Munich corridor facilities. Solid-state battery thermal protocol fragmentation threatens installed base relevance; vertical integration into nanofluid cooling R&D preserves technology leadership against emerging entrants with clean-sheet architectures. For New Entrants and Emerging Players: Enter via India's ACC-PLI scheme localization requirements, where domestic cell production scaling beyond 50 GWh annually lacks thermal validation infrastructure. Second-life battery testing for grid storage applications represents the most penetrable white space. Go-to-market leverage rests on subscription-based thermal validation platforms displacing capital purchase for mid-tier battery developers. For Investors and Strategic Acquirers: Asymmetric upside sits with precision instrumentation specialists embedding power analytics into rig control systems rather than heritage powertrain testers facing protocol obsolescence cycles. Long-term viability favors acquisition targets with multi-physics simulation integration and hardware-in-the-loop capabilities. Watch for UN 38.3 harmonization implementation as inflection signal triggering replacement demand for export-bound equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Fluid Formulation Transition | Synthetic ester chemistry unifies thermal performance with REACH compliance for European OEM validation centers. |
| Certification Engineering Investment | NMPA-recognized protocol libraries unlock China's Yangtze River Delta battery developer procurement. |
| Nanofluid Cooling R&D Partnership | Alumina nanoparticle suspensions promise 15-25% heat transfer coefficient improvement for next-generation rigs. |
| Subscription Platform Development | Thermal validation-as-a-service captures South Korean battery developers facing KATRI certification requirements. |
| Second-Life Testing Protocol Adaptation | Modified immersion rigs address grid storage thermal validation for degraded automotive packs. |
Research Methodology
Direct dialogue with thermal validation directors at OEM development centers, battery pack engineering leads, dielectric fluid procurement specialists, and accredited test house operations managers grounded qualitative findings. Secondary validation drew from NMPA GB standard filings, EU Battery Regulation implementation guidance, EPA fluorinated gas regulatory dockets, and customs trade data on dielectric fluid imports. Bottom-up rig shipment tallies and top-down EV battery production forecasts were triangulated against capital expenditure disclosures from validation center operators.
Bottom-up modeling segmented volume and value across automated test systems, custom solutions, and bench rigs by cooling technology tier and end-user procurement modality. Analytical framework incorporated product type, cooling technology, end user segment, and testing application dimensions throughout the projection horizon. CAGRs were derived from regression against EV battery production trajectories and regulatory mandate implementation schedules. Industry-specific inputs included thermal runaway propagation testing cycle counts per EU Battery Regulation and GB 38031 abuse profile complexity indices.
The model holds under sustained EV battery production scaling and regulatory harmonization timelines; deviation in fluorinated fluid supply allocation or UN 38.3 implementation delays would shift replacement cycle assumptions. Forecasts reflect documented assumptions on dielectric fluid formulation transitions and certification protocol recognition reciprocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Gloss Meters Market
Test and Measurement
LCR Meter Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Tensile Testers Market
Test and Measurement
Fluorometers Market
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Electrical Test Equipment Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market