
 Data Acquisition Equipment Market | 2026-2036
Data Acquisition Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Data Acquisition Equipment Market Insights
Market Dynamics
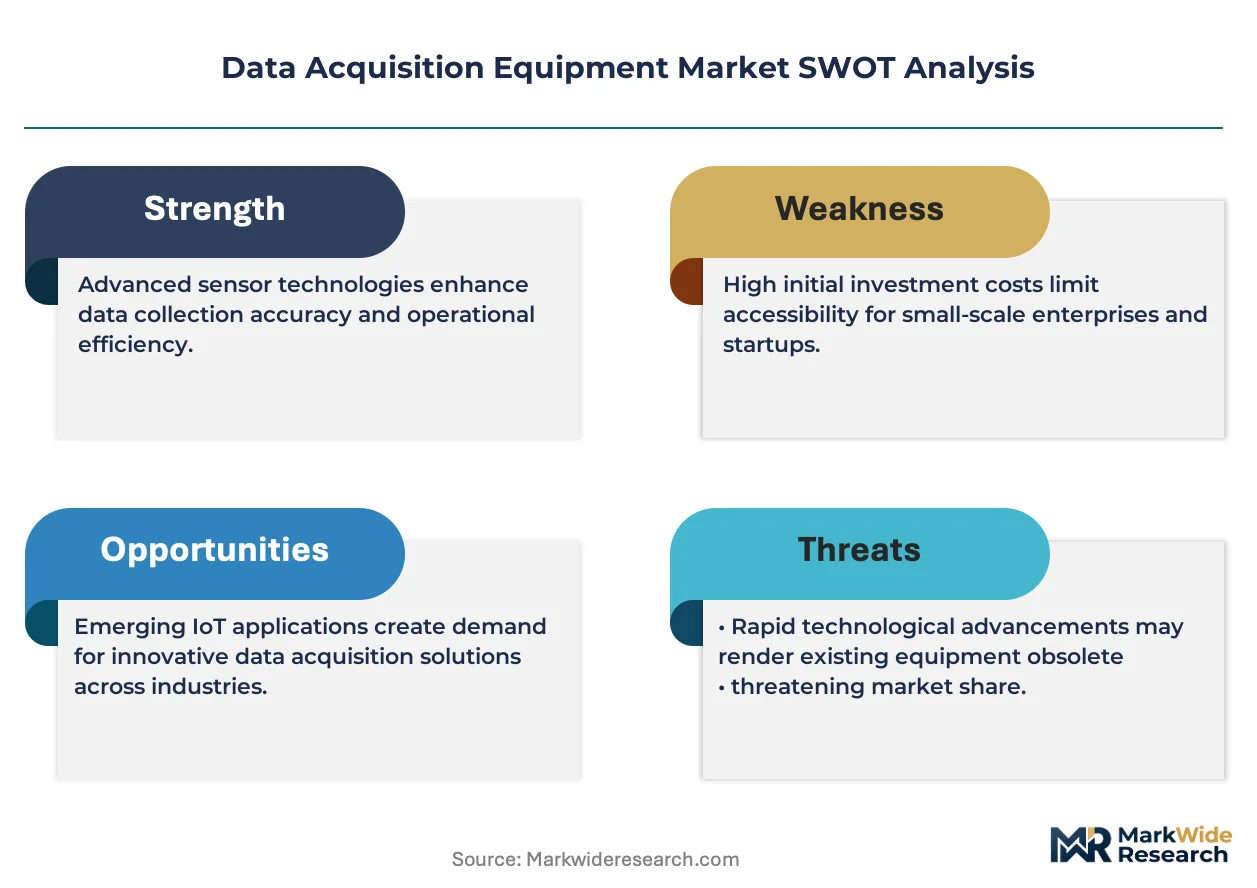
Edge computing integration with sensor networks is fragmenting traditional centralized DAQ architectures into distributed acquisition nodes. National Instruments leverages its software-defined platform to sustain design-win momentum across automated test environments. Keysight Technologies anchors its position through precision instrumentation for 5G and automotive radar validation. Yokogawa Electric Corporation dominates high-speed measurement segments where electromagnetic compatibility testing demands sub-nanosecond sampling resolution.
Segmentation
Data acquisition equipment comprises modular hardware systems that digitize analog signals from physical sensors, typically achieving sampling rates from kilohertz to gigahertz with 12- to 24-bit resolution, for the purpose of recording, analyzing, and controlling industrial processes and scientific experiments. Wireless technology segments are expanding fastest as battery-powered IoT sensor networks displace cabled installations in environmental monitoring and structural health applications. Data loggers retain mature margin pools in cold-chain pharmaceutical distribution where regulatory audit trails require continuous temperature documentation. Signal conditioners command premium positioning in aerospace propulsion test stands where thermocouple and strain-gauge signal integrity must survive extreme thermal cycling.
Regulatory Environment
FDA 21 CFR Part 11 compliance shapes medical research DAQ procurement by mandating electronic signature and audit-trail capabilities for clinical trial instrumentation. EPA emissions testing protocols and NHTSA crash-safety regulations in the United States, alongside REACH substance restrictions and CE marking under EU MDR for medical devices in Europe, collectively dictate sensor calibration standards and data-integrity requirements. Stakeholders must monitor evolving cybersecurity frameworks for connected industrial sensors as regulatory bodies on both sides of the Atlantic draft baseline requirements for operational technology network segmentation.
Market Dynamics
Edge computing architectures are fragmenting traditional centralized data acquisition systems into distributed acquisition nodes, forcing vendors to re-engineer hardware-software stacks for real-time processing at the sensor edge rather than backend aggregation.
Growth Catalysts
- EU AI Act traceability mandates:Automotive OEMs in Germany must maintain calibrated sensor chains for algorithmic decision documentation, expanding test cell instrumentation budgets across Stuttgart and Munich industrial clusters.
- 5G millimeter-wave validation:Telecommunications equipment manufacturers require sub-nanosecond sampling resolution for beamforming antenna characterization, pulling high-speed digitizer demand.
- Battery-powered IoT sensor networks:Environmental monitoring agencies are deploying wireless nodes for structural health monitoring of bridges and dams, displacing cabled installations in remote terrain.
Market Restraints
- Precision analog component concentration:Specialized ADC and signal conditioning chip supply concentrates among a handful of semiconductor foundries, exposing lead time volatility.
- REACH substance restrictions:RoHS compliance costs for lead-free solder and restricted material documentation compress margins on legacy product lines.
- Optical fiber sensing substitution:Distributed acoustic sensing systems are capturing temperature and strain measurement applications previously served by electrical sensor networks.
Strategic Opportunities
- India industrial automation corridors:PLI scheme incentives for manufacturing localization are creating greenfield demand for process control instrumentation in Gujarat and Tamil Nadu.
- Clinical trial decentralization:FDA 21 CFR Part 11 compliance requirements for electronic signatures and audit trails are expanding portable DAQ procurement for decentralized patient monitoring.
- Digital twin convergence:Real-time sensor fusion with physics-based simulation models is collapsing hardware-in-the-loop test cycles for powertrain development.
Industry Challenges
- Embedded firmware security certification:IEC 62443 cybersecurity standards for operational technology networks are extending product validation timelines by six to nine months.
- Multi-physics simulation integration:Test engineers face skill gaps in coupling thermal, mechanical, and electromagnetic sensor data into unified analysis workflows.
Report Scope
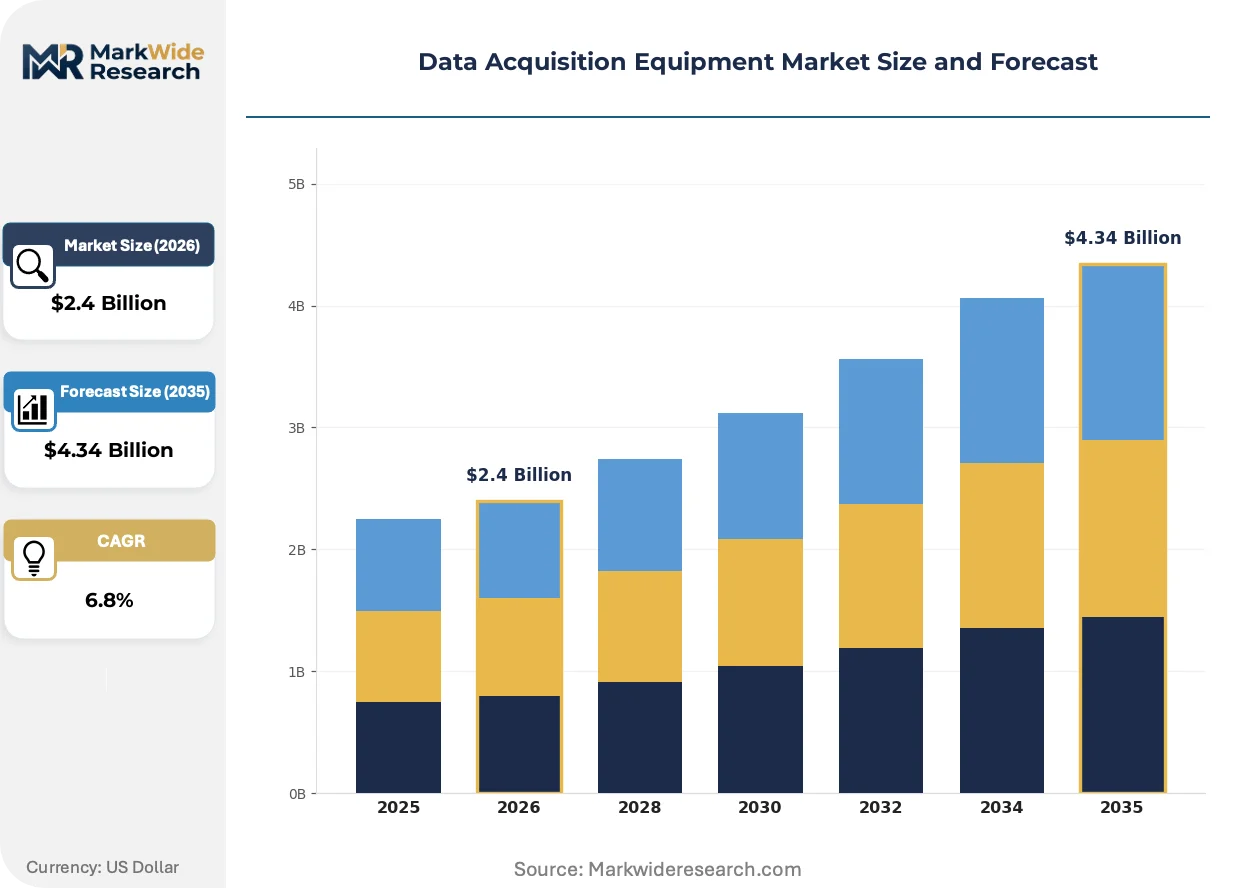
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Acquisition Equipment Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Recorders, Data Loggers, Signal Conditioners, Transducers Technology: Analog, Digital, Wireless, Hybrid End User: Aerospace, Automotive OEMs, Research Institutions, Industrial Automation Application: Environmental Monitoring, Structural Analysis, Medical Research, Automotive Testing |
| Companies Covered | National Instruments, Keysight Technologies, AMETEK Inc., Yokogawa Electric Corporation, Spectris, Teledyne Technologies Incorporated, Advantech Co. Ltd., Schneider Electric, Dewesoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Acquisition Equipment Market Trends and Innovations
Software-defined instrumentation is collapsing the traditional boundary between hardware acquisition layers and post-processing analytics, enabling firmware-upgradable measurement capabilities without physical retrofit.
Time-sensitive networking over Ethernet is collapsing the need for dedicated trigger buses and synchronized clock distribution cables in multi-channel test configurations. Automotive validation labs at KBA-certified facilities in Germany are adopting IEEE 802.1AS time synchronization for distributed brake and suspension testing. This collapse of proprietary interconnect standards is reducing system integration costs while complicating vendor lock-in strategies.
CE marking under the EU Green Deal is tightening lifecycle documentation requirements for sensor calibration chains, forcing manufacturers to embed blockchain-anchored provenance records. Medical device OEMs must now demonstrate REACH-compliant material sourcing and end-of-life recyclability for measurement hardware. The MDR regulatory framework is compressing product update cycles as notified bodies demand continuous software vulnerability monitoring.
Subscription-based hardware access models are displacing capital purchase contracts in mid-sized testing laboratories. German automotive tier-one suppliers now favor operational expenditure structures that bundle sensor maintenance, calibration services, and cloud analytics. This shift is most visible in Bavaria and Baden-Württemberg, where regional equipment lessors are building captive service networks to capture recurring revenue streams.
Data Acquisition Equipment Market Segmentation
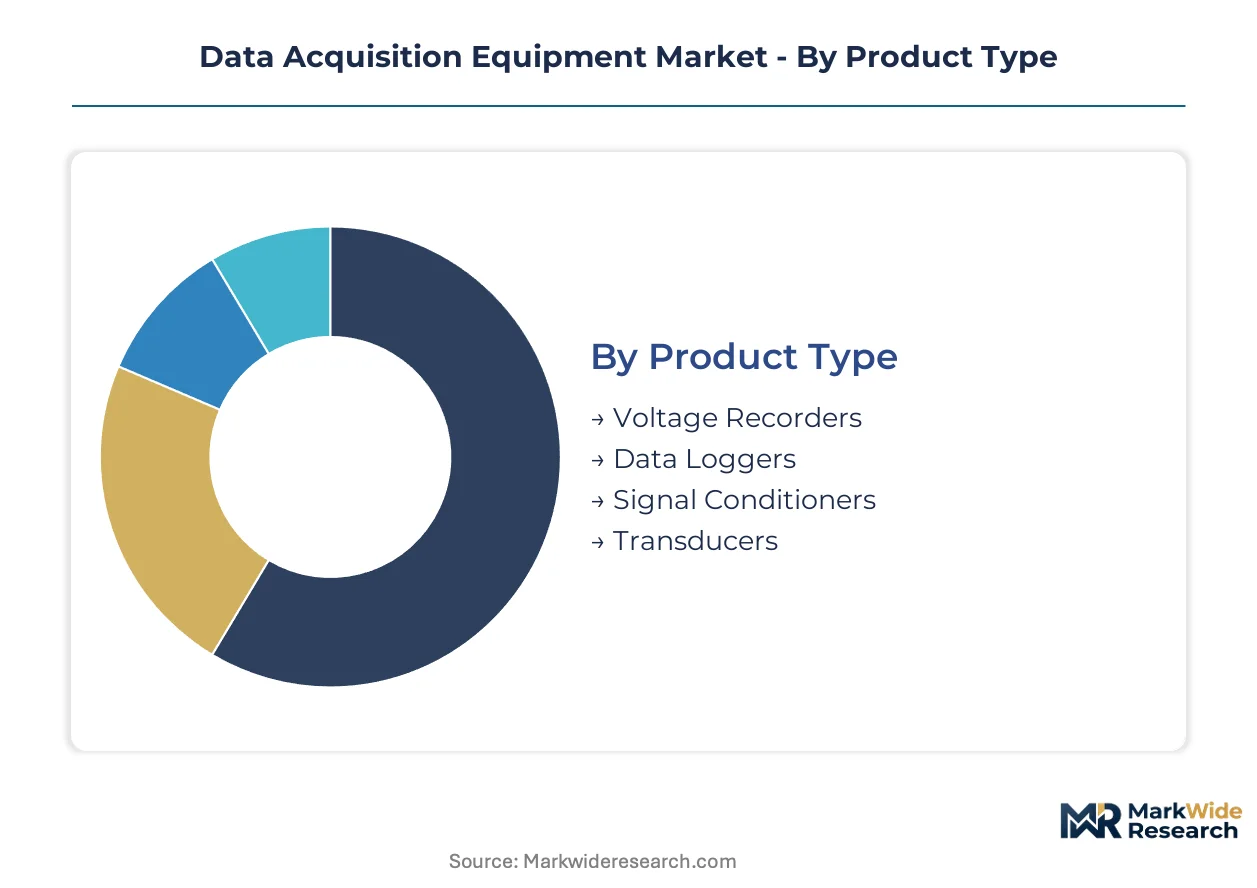
Data acquisition equipment segments diverge sharply in procurement cadence. Automotive validation programs refresh hardware every 18-24 months to match tightening EU AI Act traceability mandates, while cold-chain pharmaceutical data loggers operate on 7-10 year replacement cycles under FDA 21 CFR Part 11 grandfathering provisions.
Product Type:
Voltage recorders and signal conditioners turn over fastest as automotive OEMs chase higher sampling fidelity for electric powertrain validation, whereas data loggers in regulated pharmaceutical distribution exhibit the longest replacement cycles.
- Voltage Recorders:These devices capture transient electrical signals with millivolt-level precision across multi-channel configurations. Stuttgart-based automotive testing laboratories are expanding procurement volumes for battery management system validation, driven by KBA certification requirements for high-voltage safety documentation.
- Signal Conditioners:Hardware modules amplify, filter, and isolate raw sensor outputs before analog-to-digital conversion. Aerospace propulsion test stands in Germany and France command premium positioning here, where thermocouple and strain-gauge signal integrity must survive extreme thermal cycling and REACH-compliant material constraints.
- Data Loggers:Standalone recording devices with embedded storage for temperature, humidity, and pressure telemetry.
- Transducers:Energy-conversion devices translating physical phenomena into measurable electrical signals.
Data loggers anchor the volume base while signal conditioners gain share at the steepest rate.
Technology:
Cost tiering separates mature analog architectures from premium wireless deployments, with hybrid systems occupying the mid-market as laboratories balance legacy infrastructure against edge-computing requirements.
- Wireless:Battery-powered acquisition nodes communicate via LoRaWAN, Bluetooth, or proprietary protocols. Environmental monitoring agencies in Germany deploy these for structural health monitoring of Autobahn bridges, displacing cabled installations where fiber-optic trenching proves cost-prohibitive.
- Digital:Fully digitized signal chains with software-defined processing capabilities. Research institutions in Munich and Dresden favor these for multi-physics experiments requiring real-time FPGA-based computation.
- Analog:Traditional voltage-based measurement architectures with discrete component signal paths.
- Hybrid:Mixed-signal systems combining analog front-ends with digital back-end processing.
Analog systems retain the installed base while wireless configurations are expanding most quickly.
End User:
Customer type determines specification rigor, with aerospace and automotive OEMs demanding full calibration traceability chains while industrial automation buyers prioritize cost-optimized modularity.
- Automotive OEMs:Vehicle manufacturers operate KBA-certified test cells requiring sub-nanosecond sampling resolution for ADAS validation. Munich and Stuttgart industrial clusters anchor procurement volumes as EU AI Act documentation mandates expand instrumentation budgets for algorithmic decision audit trails.
- Aerospace:Airframe and propulsion manufacturers subject to EASA certification protocols. French and German facilities concentrate demand for electromagnetic compatibility testing equipment where CE marking under the EU Green Deal tightens lifecycle documentation requirements.
- Research Institutions:University and national laboratory facilities conducting fundamental science.
- Industrial Automation:Process control and manufacturing execution system integrators.
Industrial automation commands the broadest unit volumes while automotive OEMs drive the steepest specification escalation.
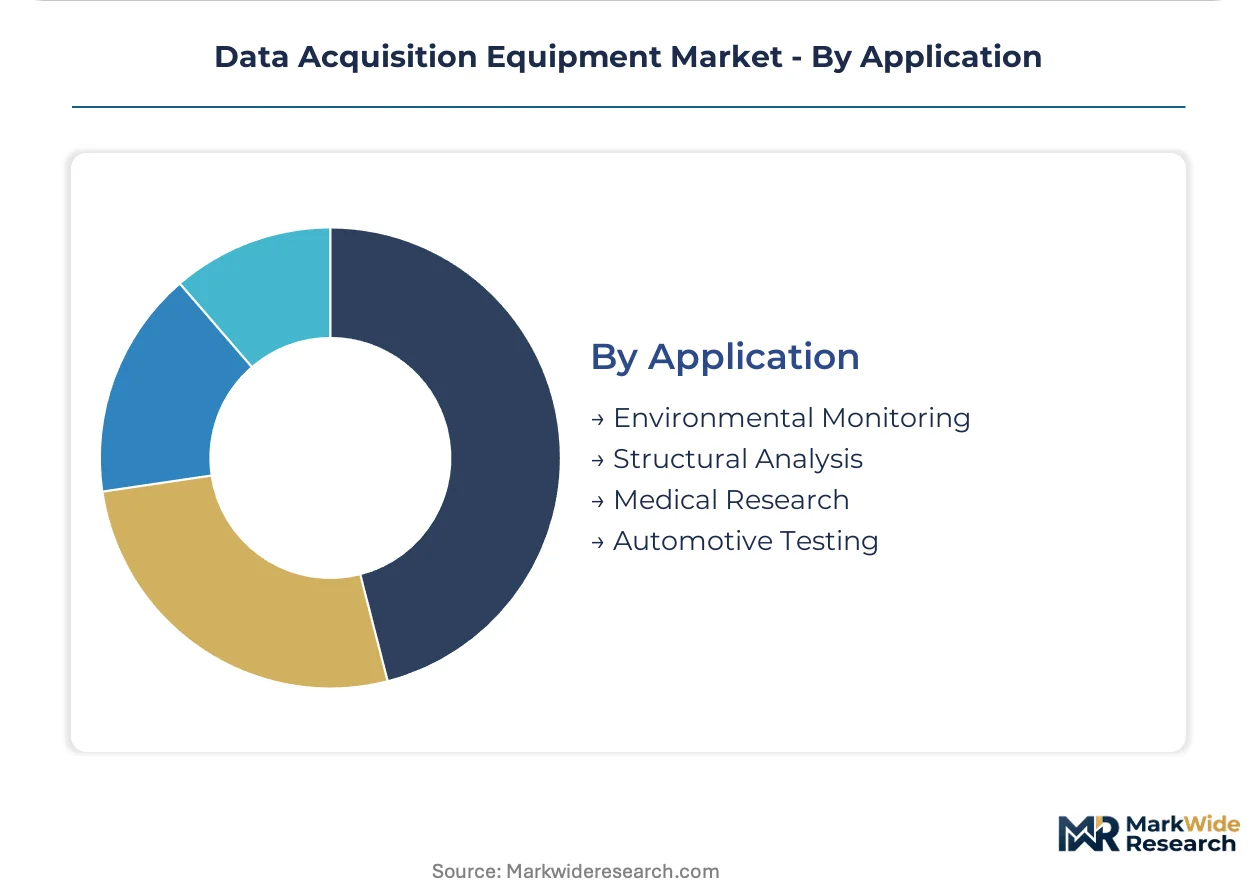
Application:
Application maturity spans decades-old environmental monitoring protocols to emerging medical research requirements under FDA 21 CFR Part 11, with automotive testing occupying the middle ground as electrification reshapes validation priorities.
- Automotive Testing:Powertrain, chassis, and ADAS validation protocols spanning climatic wind tunnels to electromagnetic anechoic chambers. German facilities lead adoption of IEEE 802.1AS time-sensitive networking for distributed brake and suspension testing, collapsing proprietary interconnect standards.
- Medical Research:Clinical trial instrumentation requiring electronic signatures and immutable audit trails. Decentralized patient monitoring trials are expanding portable DAQ procurement as FDA compliance extends beyond traditional hospital settings.
- Environmental Monitoring:Atmospheric, hydrological, and ecological data collection systems.
- Structural Analysis:Civil infrastructure health monitoring for bridges, dams, and buildings.
Environmental monitoring holds the deepest installed base while medical research climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive testing laboratories and industrial automation clusters anchor procurement volumes across concentrated demand centers. KBA-certified facilities in Germany command premium instrumentation specifications. FDA-regulated pharmaceutical distribution networks in the United States sustain long-cycle data logger deployments.
Germany
Stuttgart and Munich industrial clusters drive specification escalation for electric powertrain validation. KBA certification requirements mandate sub-nanosecond sampling resolution for high-voltage safety documentation under EU AI Act traceability mandates. Bavaria-based automotive tier-one suppliers favor operational expenditure structures bundling sensor maintenance and cloud analytics.
United States
Telecommunications equipment manufacturers pull high-speed digitizer demand for 5G millimeter-wave beamforming antenna characterization. FDA 21 CFR Part 11 compliance shapes medical research procurement by mandating electronic signatures and audit-trail capabilities. Greater Boston and Silicon Valley anchor decentralized clinical trial instrumentation expansion.
China
MIIT standards for industrial internet platforms accelerate edge-computing node deployment in smart manufacturing corridors. Dual carbon goals tighten emissions monitoring requirements across steel and cement sectors. Yangtze River Delta clusters concentrate demand for process control instrumentation in semiconductor fabrication.
India
PLI scheme incentives for manufacturing localization create greenfield demand for process control instrumentation. Gujarat and Tamil Nadu industrial automation corridors anchor procurement volumes for textile and automotive component testing. BIS certification requirements tighten sensor calibration standards for export-oriented production.
Japan
METI funding for Society 5.0 infrastructure expands structural health monitoring deployments for aging civil infrastructure. JIS standards govern electromagnetic compatibility testing equipment procurement for automotive and aerospace applications. Nagoya industrial clusters concentrate precision instrumentation demand for robotics validation.
Data Acquisition Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Consolidation concentrates among software-defined platform vendors and precision instrumentation specialists. Three archetypes dominate: vertically integrated test-system integrators, modular hardware specialists, and subscription-based service providers. Strategic moves center on firmware-upgradable measurement capabilities and operational expenditure model transitions.
Within the software-defined platform tier, National Instruments and Keysight Technologies exemplify archetype positioning through firmware-upgradable architectures. Yokogawa Electric Corporation anchors high-speed measurement specialization. These three occupy positions spanning automated test environments through sub-nanosecond sampling applications.
| Leading Market Players |
|---|
| National Instruments |
| Keysight Technologies |
| AMETEK Inc. |
| Yokogawa Electric Corporation |
| Spectris |
| Teledyne Technologies Incorporated |
| Advantech Co. Ltd. |
| Schneider Electric |
| Dewesoft |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's precision instrumentation cluster anchors European supply capacity for high-speed digitizers and signal conditioning modules, translating localized component scarcity into sustained pricing leverage for vendors serving KBA-certified automotive test cells. Cost compression in mid-tier data logger segments intensifies as Indian and Chinese manufacturers scale battery-powered wireless node production, eroding legacy margin pools in environmental monitoring applications.
Pricing Analysis
Cost-plus contracts with semiconductor foundry indexation dominate procurement for precision ADC and FPGA components, embedding raw material volatility directly into vendor pricing. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade signal conditioners with full calibration traceability from industrial automation modules with reduced documentation packages. Price differentiation hinges on certification grade and after-sales service bundling, with FDA 21 CFR Part 11-compliant medical research systems commanding substantial premiums over unvalidated equivalents. Pricing pressure stems from REACH substance restriction compliance costs compressing margins on legacy analog product lines. Industrial automation buyers exhibit highest price sensitivity, while aerospace propulsion test stands demonstrate lowest elasticity due to EASA certification protocol rigidity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for telecommunications equipment manufacturers sourcing high-speed digitizers. Manufacturing concentrates in Germany, Japan, and Taiwan, with specialized foundry capacity for sub-nanosecond sampling resolution components resting on concentrated semiconductor fabrication networks. Raw material dependencies span precision analog front-end chips, high-density interconnect substrates, and REACH-compliant solder alloys. Single-source vulnerability persists for electromagnetic compatibility testing equipment where JIS and CE marking standards limit qualified supplier pools. Distribution runs through authorized technical distributors with calibration service capabilities, particularly for pharmaceutical cold-chain data loggers requiring FDA audit trail documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data acquisition equipment vendors face a structural service-attach opportunity as subscription-based hardware access models expand recurring revenue faster than transactional equipment sales. Cloud analytics bundling and sensor maintenance contracts now generate margin pools that outpace standalone hardware procurement in German automotive testing corridors.
For Market Incumbents: Harden firmware-upgradable platform architectures against software-defined instrumentation entrants by embedding IEEE 802.1AS time synchronization as a default capability. Deepen backward integration into precision ADC supply through captive relationships with Taiwanese foundry partners. Defensive certification investments in IEC 62443 cybersecurity standards extend product validation timelines but create switching costs against modular hardware specialists. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial automation corridors offer underpenetrated white space for process control instrumentation as PLI scheme incentives localize manufacturing capacity. Target decentralized clinical trial instrumentation under FDA 21 CFR Part 11 compliance requirements, where portable wireless DAQ procurement expands beyond traditional hospital settings. Pursue partnership-based go-to-market structures with regional equipment lessors building captive service networks in Bavaria and Baden-Württemberg. For Investors and Strategic Acquirers: Long-term, this sits as a software-attach play because firmware-upgradable measurement capabilities collapse hardware replacement cycles while extending customer lifetime value through recurring analytics subscriptions. Acquisition targets should emphasize modular hardware specialists with embedded FPGA computation capabilities and established calibration service networks. Monitor EU AI Act traceability mandate enforcement intensity as the critical inflection signal for automotive test cell instrumentation budget expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Captures recurring revenue from KBA-certified automotive test cells requiring continuous sensor traceability documentation. |
| Firmware-Defined Platform Migration | Enables IEEE 802.1AS time synchronization upgrades without physical retrofit, collapsing proprietary interconnect lock-in. |
| Wireless Node Portfolio Development | Addresses structural health monitoring demand from German environmental agencies deploying LoRaWAN bridge sensors. |
| Cybersecurity Certification Investment | Accelerates IEC 62443 compliance timelines for operational technology networks in pharmaceutical distribution. |
| Subscription Model Transition | Aligns with Bavarian automotive tier-one supplier preference for operational expenditure structures bundling cloud analytics. |
Research Methodology
Desk research of trade association filings, customs databases, and regulatory submission records preceded structured interviews with automotive test cell engineers, pharmaceutical quality assurance directors, and industrial automation procurement leads. Primary fieldwork encompassed validation discussions with precision instrumentation vendors, calibration service providers, and semiconductor foundry account managers. Secondary sources included KBA certification documentation, FDA 21 CFR Part 11 guidance materials, and EU AI Act implementation texts. Bottom-up unit demand modeling triangulated against top-down market sizing from equipment shipment records.
Forecast assumptions held fixed the current regulatory enforcement trajectory for EU AI Act traceability mandates and FDA audit trail requirements across the projection horizon, while varying edge computing adoption rates and wireless sensor network penetration assumptions. Segmentation dimensions encompassed product type, technology architecture, end-user industry, and geographic production cluster. CAGRs derived from logistic curve fitting to historical equipment refresh cycles, adjusted for electrification-driven automotive validation program acceleration and pharmaceutical data logger replacement cycle extension under grandfathering provisions.
Practitioners should monitor REACH substance restriction scope expansion and MIIT industrial internet platform standard evolution for early signals of supply chain reconfiguration. Forecasts reflect assumptions about continued precision analog component concentration and sustained semiconductor foundry lead time volatility. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Slovakia and Czech Republic Calibration Services Market
Test and Measurement
Radiography Test Equipment Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Onboard Charger and DC Fast-Charging Interoperability Test Equipment Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Rohs Tester Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
PXI SMU Market
Test and Measurement
Moisture Analyzer Market