
 Digital Map Software Market | 2026-2036
Digital Map Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Map Software Market Insights
Sub-meter accuracy specification tiers is unwinding legacy mapping contracts across enterprise accounts. Alphabet anchors its position through cloud-native geospatial APIs that integrate with enterprise data pipelines. HERE Technologies dominates automotive-grade HD mapping for autonomous vehicle programs. Esri specializes in desktop GIS workflows that sustain deep penetration within government agencies and utility operators.
Digital map software comprises geospatial data platforms that render, analyze, and update location information through vector and raster processing engines, typically operating with refresh cycles measured in hours for real-time layers and quarters for base map updates. The technology serves commercial navigation, asset tracking, and spatial analytics across mobile, web, and embedded deployment environments. Mobile Applications now capture the largest share of consumer-facing deployments, while SDKs represent the fastest-expanding segment as developers embed location intelligence into third-party applications. Cloud-Based technology underpins margin expansion by reducing on-premise infrastructure burdens for enterprise clients.
FDA oversight of geospatial health data, FCC rules on broadband mapping accuracy, and GDPR restrictions on location data processing in Europe collectively elevate compliance costs while creating barriers to entry for new platform vendors. The EU AI Act further constrains automated geospatial decision systems deployed within member states. Stakeholders must weigh the trade-off between real-time data granularity and regulatory exposure before committing to next-generation mapping architectures.
Market Dynamics
The migration from monolithic mapping engines to modular, API-first architectures is fragmenting procurement patterns across enterprise accounts. This structural shift forces legacy vendors to unbundle feature sets while enabling specialized entrants to capture niche workflows.
Growth Catalysts
- EU AI Act compliance mandates:Automated geospatial decision systems deployed in member states must now meet algorithmic transparency requirements, creating replacement demand for explainable routing and mapping platforms.
- Fleet electrification programs:Logistics operators require sub-meter elevation data and charging-station-aware routing to optimize battery range across commercial vehicle deployments.
- 5G network densification:Telecommunications infrastructure rollouts demand millimeter-wave propagation maps with building-level geometric accuracy for small-cell placement.
Market Restraints
- Geospatial data storage costs:Petabyte-scale point-cloud archives from mobile mapping fleets impose fixed cost burdens that scale linearly with coverage expansion.
- Sensor hardware concentration:LiDAR and photogrammetric capture equipment relies on specialized semiconductor fabs concentrated in East Asian manufacturing clusters.
- GDPR location data friction:Pseudonymization requirements for raw GPS traces increase processing overhead and limit historical trajectory retention periods.
Strategic Opportunities
- India's smart city infrastructure:Municipal digitization programs under the Ministry of Housing and Urban Affairs create procurement pipelines for integrated mapping and property-tax platforms.
- Digital twin convergence:The intersection of BIM (Building Information Modeling) and real-time sensor feeds enables 4D spatiotemporal visualization for facility management.
- CSRD disclosure requirements:Corporate sustainability reporting mandates geospatial supply-chain traceability, opening enterprise accounts to ESG-aligned mapping vendors.
Industry Challenges
- Geodetic datum migration:The transition from NAD83 to NATRF2022 in North America and ETRS89 updates in Europe forces coordinate-system recalibration across archived datasets.
- Real-time pipeline engineering:Sub-hour vector tile updates require streaming infrastructure that few enterprise IT departments maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Map Software Market |
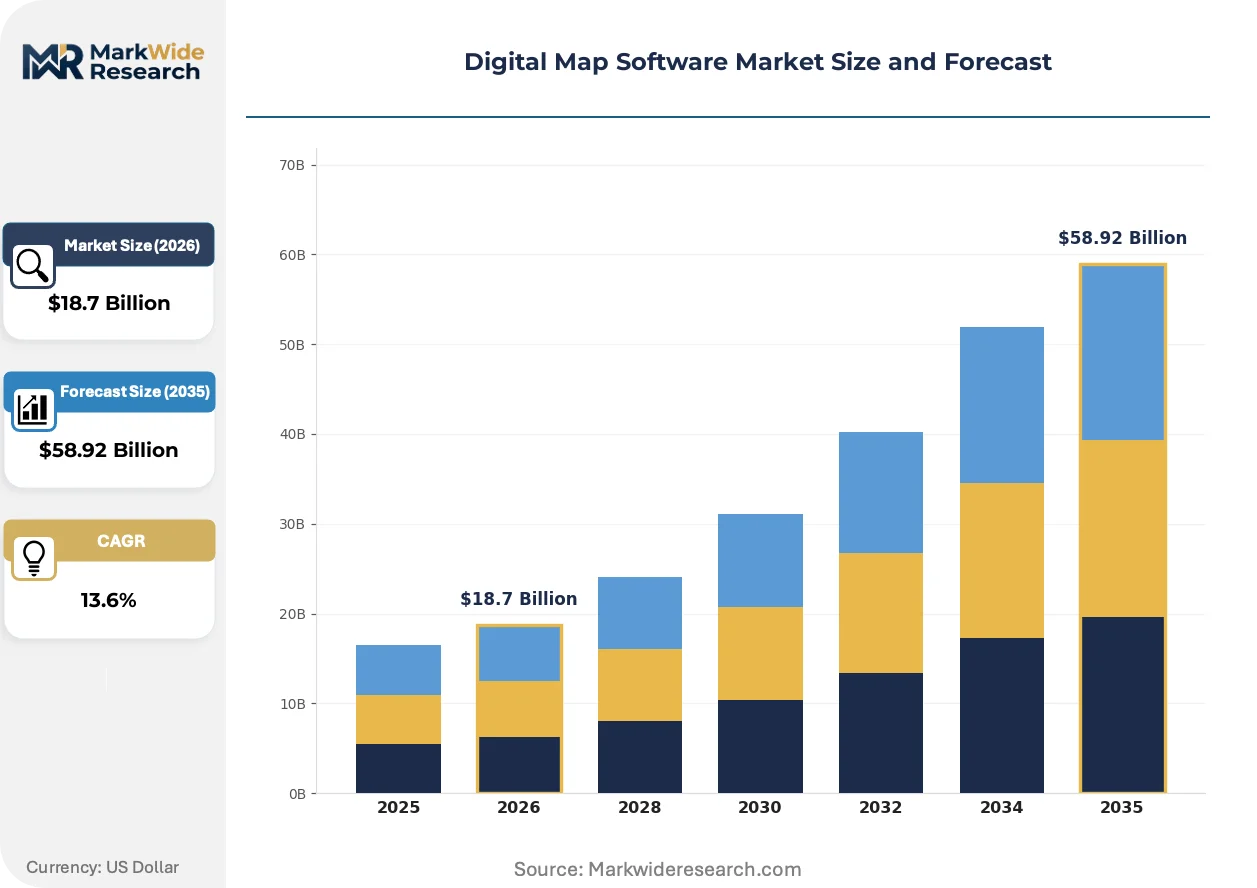
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Mobile Applications, Integrated Solutions, SDKs Use Case: Navigation, Geographic Information System, Real Estate, Urban Planning End User: Government Agencies, Logistics Providers, Retail Companies, Tourism Operators Technology: GIS, GPS, Cloud-Based, Augmented Reality |
| Companies Covered | Esri, Apple (Apple Maps), Alphabet (Google Maps), Maxar Technologies, Maptitude, HERE Technologies, Mapbox, NavInfo, TomTom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Map Software Market Trends and Innovations
Computational approaches to map generation are shifting from batch photogrammetry to continuous, sensor-fusion pipelines. This transformation compresses update cycles while expanding the categories of features that automated systems can extract and classify.
Neural radiance fields (NeRF) for view synthesis is decomposing traditional photogrammetric mesh generation in urban digital twin applications. Property developers and municipal planners now commission immersive 3D environments from sparse camera arrays rather than dedicated aerial survey contracts. The technology is decomposing the price premium historically commanded by high-end surveying firms.
The EU AI Act's risk classification framework for biometric and geospatial inference systems imposes conformity assessment obligations on automated feature extraction. Platform vendors must now document training data provenance and model performance metrics for regulatory file. Automotive OEMs deploying HD maps for conditional automation face the steepest compliance burden.
Enterprise buyers now unbundle base-map subscriptions from analytics tooling, treating geospatial data as a commodity input rather than a platform lock-in. Procurement teams negotiate separate contracts for vector tiles, traffic feeds, and SDK licensing. This pattern is most pronounced in Germany, where automotive suppliers and logistics groups maintain dedicated vendor-management functions for location intelligence.
Digital Map Software Market Segmentation
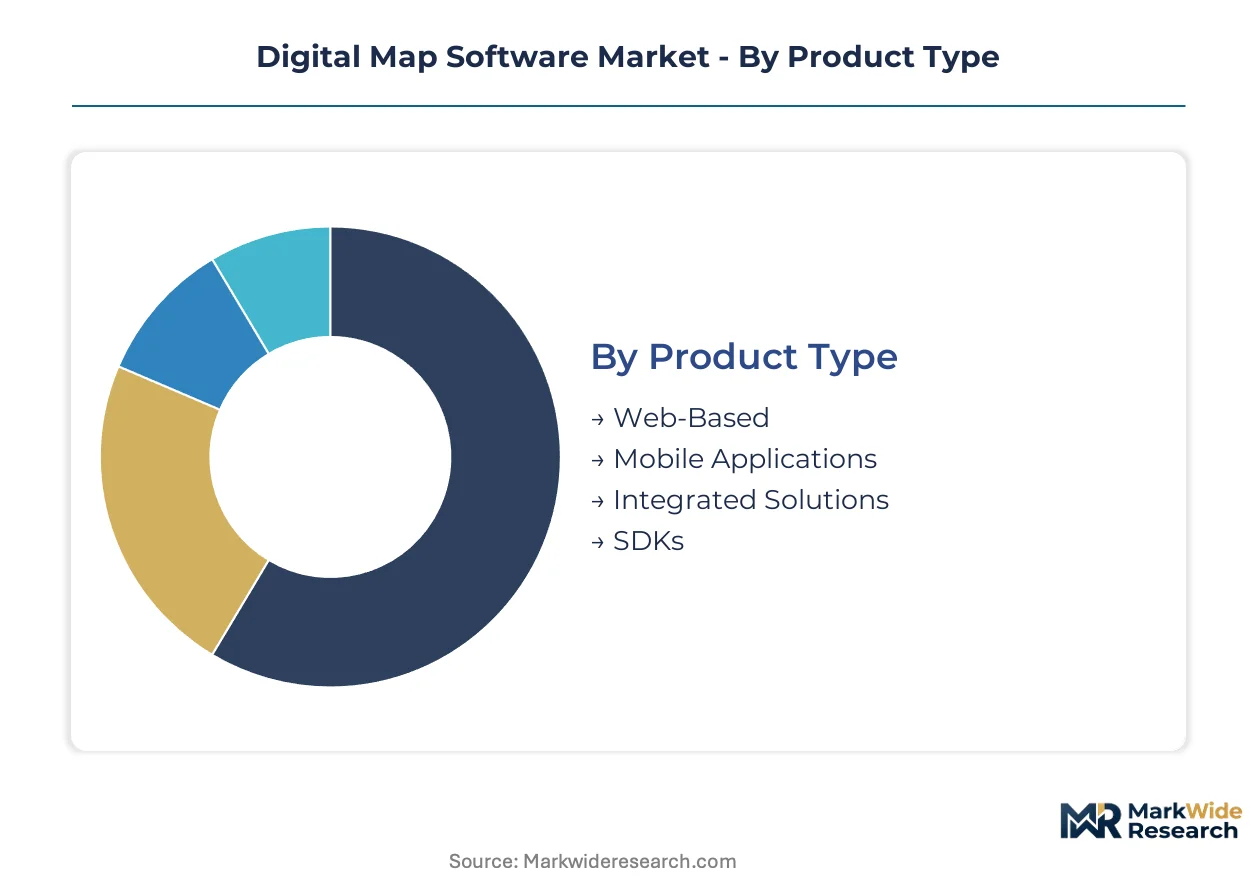
Segmentation in digital map software reveals how procurement patterns fragment across deployment modes, functional requirements, and buyer sophistication. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor positioning.
Product Type:
Substitution pressure runs strongest against legacy web-based platforms as mobile-native architectures and embeddable SDKs displace browser-dependent workflows.
- Web-Based:Browser-rendered mapping interfaces deliver vector tile streaming through standard JavaScript APIs, typically refreshed on quarterly cycles. Municipal governments in Germany and France maintain these deployments for public-facing property and zoning portals, though latency constraints limit real-time use cases.
- Mobile Applications:Native iOS and Android SDKs with offline tile caching and sensor fusion for pedestrian navigation. Logistics providers across the Benelux region now mandate these for last-mile driver applications, driven by EU AI Act requirements for explainable routing decisions on mobile endpoints.
- Integrated Solutions:Pre-configured enterprise stacks combining base maps with fleet telematics or field service modules.
- SDKs:Developer-facing libraries for embedding location intelligence into third-party applications.
Mobile Applications anchors the volume base while SDKs gain share at the steepest rate.
Use Case:
Cost tier stratification separates high-precision navigation contracts from commoditized visualization tools.
- Navigation:Turn-by-turn routing engines with real-time traffic fusion and sub-meter lane-level guidance. Automotive OEMs in Stuttgart and Wolfsburg drive specification upgrades here, compelled by KBA homologation requirements for conditional automation systems.
- Geographic Information System:Desktop and server-based spatial analytics with support for custom coordinate reference systems. Utility operators in France and Spain rely on these for network asset management, particularly through ETRS89 datum transitions.
- Real Estate:Property boundary visualization and cadastral overlay tools.
- Urban Planning:Zoning analysis and development impact simulation platforms.
Navigation commands the highest contract values while Geographic Information System maintains the deepest installed base.
End User:
Customer type determines procurement sophistication and compliance exposure.
- Government Agencies:Public-sector deployments with stringent GDPR and EU AI Act obligations for algorithmic transparency. German municipal governments and French regional authorities dominate this segment, particularly for property tax and infrastructure planning systems.
- Logistics Providers:Fleet-scale routing with electrification-aware optimization and driver-hour regulations.
- Retail Companies:Store locator services and delivery radius optimization.
- Tourism Operators:Point-of-interest discovery and multimodal journey planning.
Government Agencies impose the most complex procurement cycles while Logistics Providers deliver the most predictable expansion trajectory.
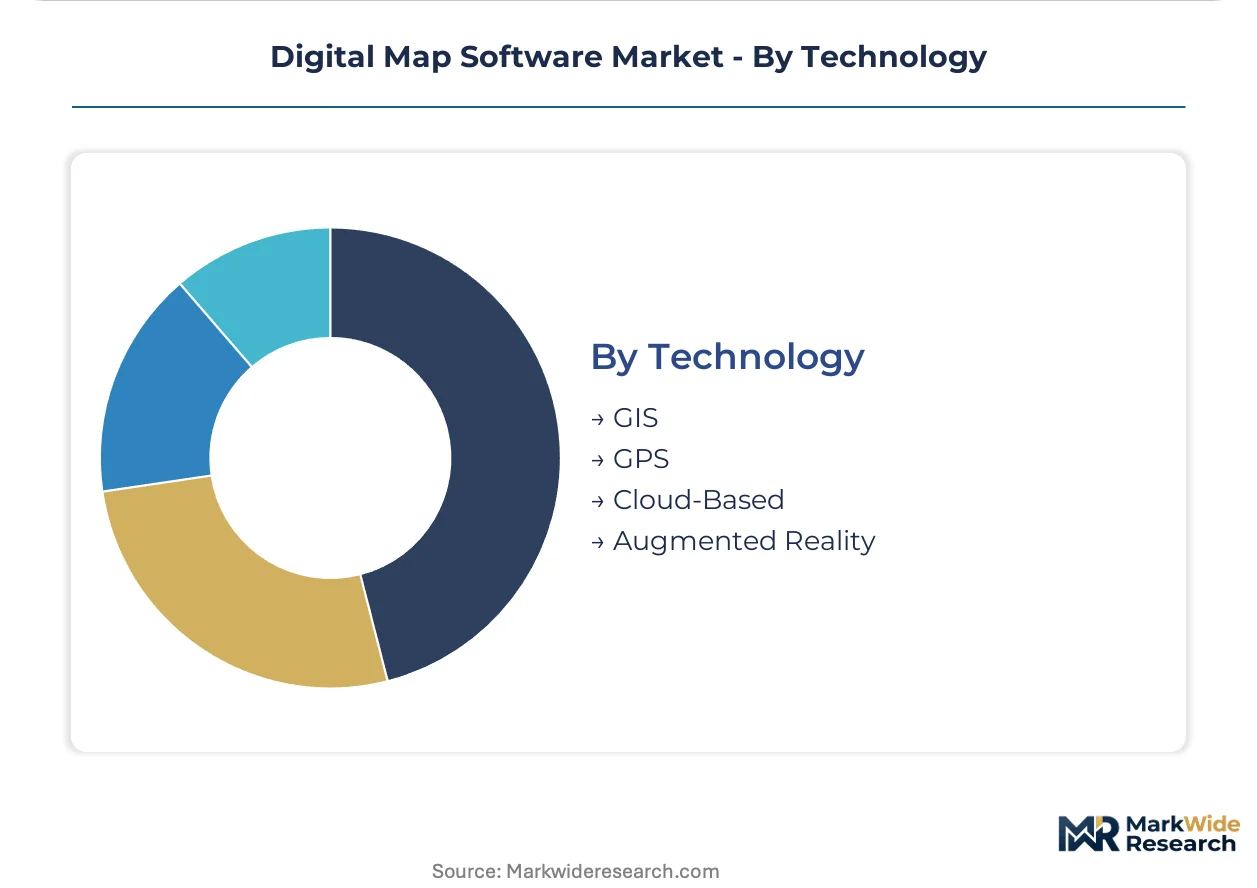
Technology:
Supply concentration in cloud infrastructure reshapes competitive dynamics.
- GIS:Spatial database engines and analytical toolchains for vector and raster processing. European utility operators and environmental agencies in the Netherlands and Denmark anchor demand, constrained by CSRD disclosure requirements for geospatial supply-chain traceability.
- GPS:Satellite positioning augmentation and differential correction services.
- Cloud-Based:Serverless tile rendering and elastic storage for petabyte-scale archives. This architecture underpins margin expansion for enterprise clients by eliminating on-premise infrastructure burdens, though GDPR data residency rules fragment vendor selection.
- Augmented Reality:Camera-overlay spatial alignment for indoor navigation and field maintenance.
Cloud-Based deployments scale most efficiently while Augmented Reality climbs fastest from a smaller base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a substantial trade surplus in automotive-grade mapping technologies, while the United States and China compete for dominance in cloud-native geospatial platforms. Import dependencies for LiDAR sensor hardware concentrate procurement leverage in East Asian manufacturing clusters.
United States
FCC broadband mapping mandates and FDA geospatial health data oversight drive public-sector procurement cycles. The Infrastructure Investment and Jobs Act funds precision mapping for rural connectivity expansion. Silicon Valley cloud providers anchor enterprise API deployments, while Detroit automotive suppliers negotiate HD map contracts for conditional automation systems.
Germany
KBA homologation requirements for autonomous vehicle systems compel sub-meter accuracy specifications from Stuttgart and Wolfsburg OEMs. EU AI Act algorithmic transparency rules reshape municipal procurement in Berlin and Munich. The country's federal property tax digitization program sustains Esri penetration within state-level cadastral agencies.
China
MIIT navigation electronic map licensing restrictions create regulatory moats around domestic platform vendors. Dual carbon goals accelerate fleet electrification programs requiring elevation-aware routing optimization. Shenzhen and Beijing host concentrated development of real-time traffic fusion engines for ride-hailing and logistics applications.
India
Ministry of Housing and Urban Affairs smart city missions generate integrated mapping and property-tax platform demand across 100 municipal jurisdictions. BIS geospatial data standards harmonize procurement specifications for state-level digitization. Bangalore and Hyderabad technology clusters incubate SDK developers serving logistics and delivery radius optimization use cases.
United Kingdom
Ordnance Survey national mapping framework contracts sustain GIS deployment across local authorities and utility operators. CSRD disclosure requirements push London-headquartered multinationals toward supply-chain traceability mapping investments. Cambridge and Oxford research clusters contribute NeRF view-synthesis expertise to property development visualization tools.
Digital Map Software Market Competitive Landscape
Concentration sits with cloud-native platform providers and automotive-grade HD mapping specialists. The vendor base separates into three functional tiers: infrastructure-scale API providers, precision navigation contractors, and desktop GIS incumbents. Competitive positioning hardens around data refresh velocity, regulatory compliance documentation, and SDK embedding flexibility. M&A activity targets sensor-fusion startups and point-cloud processing engines.
Within the infrastructure-scale tier, Alphabet and Mapbox exemplify API-first architectures that unbundle geospatial data from analytics tooling. HERE Technologies occupies a position as the dominant automotive-grade HD mapping contractor for European OEM homologation programs. Esri anchors the desktop GIS segment through deep penetration within government agencies and utility operators requiring custom coordinate reference system support.
| Leading Market Players |
|---|
| Esri |
| Apple (Apple Maps) |
| Alphabet (Google Maps) |
| Maxar Technologies |
| Maptitude |
| HERE Technologies |
| Mapbox |
| NavInfo |
| TomTom |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for LiDAR sensor modules concentrate procurement leverage in East Asian semiconductor fabs, compressing margin buffers for European and North American mapping platform vendors while amplifying pricing power among component suppliers. This structural asymmetry forces downstream software providers to absorb cost volatility or pass through to enterprise buyers in sub-meter accuracy tiers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium HD mapping, standard navigation APIs, and economy base-map subscriptions. Price differentiation hinges on refresh velocity—sub-hour real-time layers command substantial premiums over quarterly base-map cycles—and KBA homologation certification for automotive-grade deployments. Cost compression in standard-tier contracts intensifies as cloud-native entrants unbundle analytics from data feeds. Municipal governments in Germany exhibit highest price sensitivity due to budget-constrained procurement cycles, while Stuttgart and Wolfsburg automotive OEMs prioritize accuracy specifications over unit economics.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for photogrammetric capture equipment sourced from Shenzhen and Taipei manufacturing clusters. LiDAR semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, with sensor assembly tethered to Chinese component ecosystems. Single-source vulnerability runs through specialized CMOS image sensor foundries. Distribution runs through direct enterprise sales for automotive OEM contracts and channel partners for government and utility deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first fragmentation unbundles legacy platform bundles, creating vertical specialization niches for sensor-fusion startups and compliance-focused middleware vendors. The shift from monolithic engines to modular architectures rewards entrants with narrow workflow dominance.
For Market Incumbents: Secure regulatory documentation advantages under EU AI Act conformity assessment frameworks before homologation deadlines tighten. Consolidate point-cloud processing capabilities through targeted acquisitions of NeRF view-synthesis specialists. Automotive OEM defection to cloud-native APIs threatens Esri's government-installed base, demanding accelerated cloud migration investments.
For New Entrants and Emerging Players: Anchor in India's smart city digitization pipeline where BIS standards harmonization creates procurement entry points for integrated property-tax platforms. Municipal governments in Bangalore and Hyderabad present lowest competitive density among high-volume accounts. Developer-facing SDKs for logistics route optimization offer fastest path to recurring revenue without enterprise sales infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across real-time streaming infrastructure as sub-hour vector tile updates demand dedicated edge computing deployments. Five-to-ten-year viability favors vendors with demonstrated GDPR data residency architecture and documented training data provenance. Sensor-fusion startups with automotive OEM validation contracts signal acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| NeRF View-Synthesis Acquisition | Decomposes traditional aerial survey premiums for property developers in Cambridge and Oxford clusters. |
| GDPR Data Residency Architecture | Enables German municipal procurement under EU AI Act algorithmic transparency mandates. |
| Real-Time Traffic Fusion Engine | Powers Shenzhen and Beijing ride-hailing electrification-aware routing optimization. |
| HD Map Homologation Documentation | Satisfies KBA requirements for Stuttgart and Wolfsburg conditional automation systems. |
| SDK Developer Ecosystem Expansion | Captures logistics embedding demand across Benelux last-mile driver applications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler capex disclosures, App Annie mobile SDK penetration data, and EU regulatory filing databases. Conversations with fleet telematics procurement officers, automotive platform engineers, municipal IT directors, and cloud solution architects informed demand-side validation. Bottom-up triangulation against top-down macroeconomic indicators ensures segment-level consistency.
Segmentation dimensions modeled span deployment architecture, end-use vertical, organization scale, integration complexity, and regional regulatory cluster throughout the forecast period. CAGRs derive from elasticity-adjusted adoption curves and replacement cycle analysis. Industry-specific inputs include KBA homologation timeline acceleration and CSRD disclosure mandate implementation pacing.
Decision-makers should treat outputs as directional under assumptions of sustained EU AI Act enforcement continuity and 5G densification capex trajectories; material deviation in automotive OEM automation timelines or geospatial data storage cost curves would warrant model refresh. Recalibration cycles align with material shifts in homologation requirements and smart city procurement award announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market