
 Digital Twin Market | 2026-2036
Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Twin Market Analysis
Cloud infrastructure capacity in North America is shifting toward edge-native digital twin workloads. Siemens Digital Industries Software leverages its industrial software heritage to anchor manufacturing deployments across German automotive clusters. NVIDIA sustains compute leadership through GPU-accelerated physics simulation, while Dassault Systèmes differentiates via integrated CAD-twin platforms for aerospace design cycles.
A digital twin constitutes a virtual representation of a physical asset, system, or process maintained through real-time data synchronization via IoT sensors, APIs, and physics-based models. The construct enables predictive analytics, scenario testing, and operational optimization without disrupting live production environments. Software components capture the dominant margin pool given recurring licensing and update revenue, while cloud-based deployment expands fastest as enterprises abandon capital-intensive on-premises infrastructure. Predictive maintenance applications generate disproportionate ROI visibility, attracting capital from asset-heavy sectors.
The EU AI Act imposes algorithmic transparency requirements on autonomous twin-driven decisions, while GDPR restricts cross-border data flows underlying transnational twin networks. The US FAA and NHTSA develop certification frameworks for safety-critical twins in aviation and autonomous vehicles, shaping vendor R&D priorities. Stakeholders must monitor divergence between European explicability mandates and US performance-based standards when architecting multi-jurisdictional twin deployments.
Market Dynamics
Physics-based simulation fidelity requirements are compressing vendor differentiation, forcing specialization around either high-performance computing infrastructure or vertical-specific ontology libraries as the primary competitive moat.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic explainability requirements for autonomous twin-driven decisions accelerate investment in interpretable physics models and audit-ready data architectures across European manufacturing.
- Predictive maintenance ROI visibility:Asset-heavy sectors including aviation propulsion systems and offshore energy infrastructure deploy twins to compress unplanned downtime and extend capital equipment life cycles.
- German industrial automation corridor:Dense clustering of automotive OEMs and tier-one suppliers in Bavaria and Baden-Württemberg creates network effects accelerating twin adoption through shared supplier ecosystems.
Market Restraints
- GDPR cross-border data friction:Restrictions on transnational data flows fragment twin networks that rely on continuous synchronization across distributed physical assets and centralized cloud infrastructure.
- High-fidelity physics engine licensing costs:Proprietary computational fluid dynamics and finite element analysis packages impose recurring cost burdens that scale non-linearly with model complexity.
- Specialized systems integration talent scarcity:Shortage of engineers capable of bridging IoT sensor architecture, physics modeling, and enterprise IT systems limits deployment velocity for mid-market manufacturers.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Production-linked incentive programs for semiconductor and advanced chemistry cell manufacturing create greenfield deployment opportunities without legacy system integration burdens.
- Edge-native twin architectures:Convergence of 5G private networks and GPU-accelerated edge servers enables sub-10-millisecond latency for safety-critical applications in autonomous vehicles and robotics.
- US IRA clean energy tax credits:Inflation Reduction Act provisions for grid modernization and renewable energy storage drive twin deployments for battery lifecycle optimization and predictive degradation modeling.
Industry Challenges
- FAA airworthiness certification timelines:Safety-critical twins for aviation propulsion and flight control systems face multi-year validation cycles that compress first-mover advantages and strain R&D budgets.
- Interoperability standardization gaps:Absence of unified ontologies for asset description and data exchange forces costly custom integration work between vendor platforms and enterprise ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Twin Market |
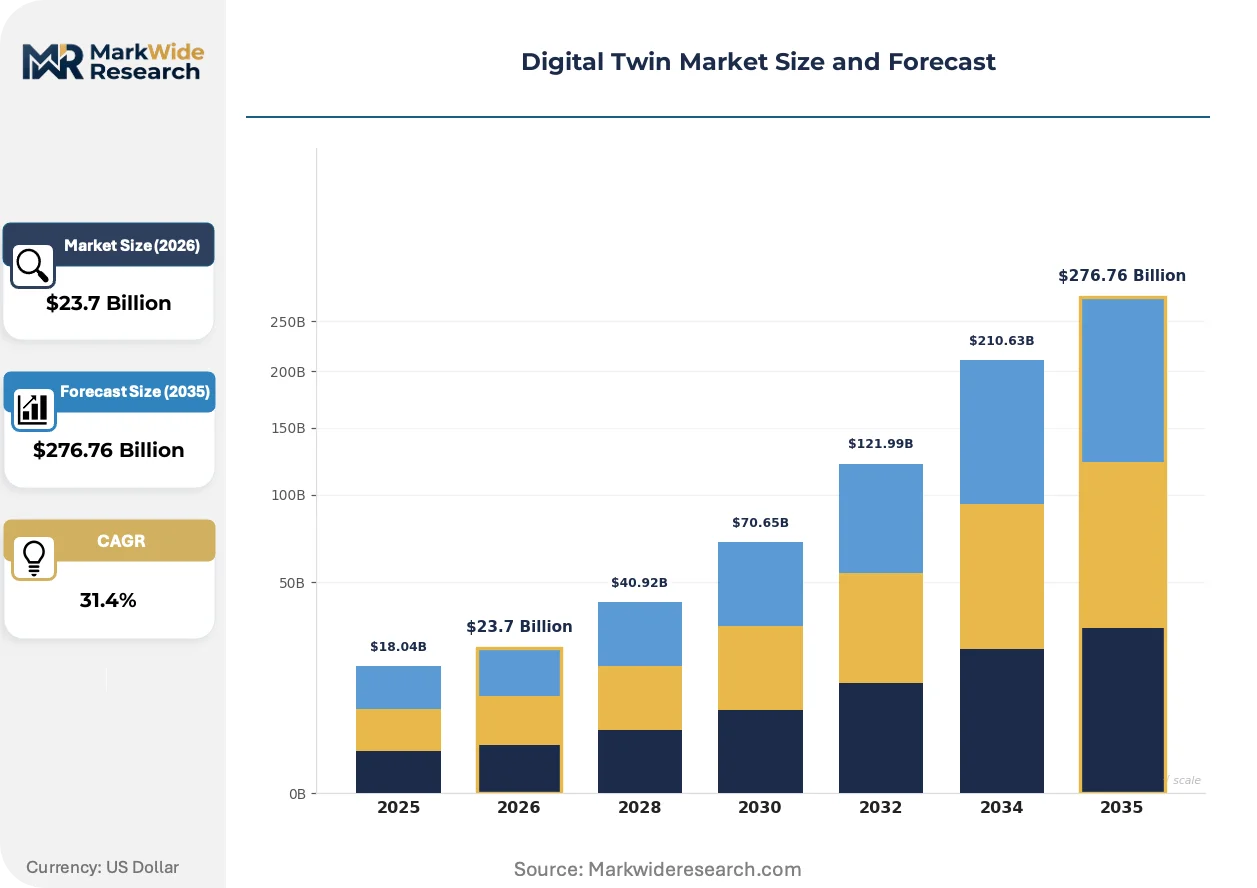
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $276.76 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Software, Hardware, Services, Platforms Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Aerospace, Automotive, Healthcare, Manufacturing Application: Predictive Maintenance, Product Design, Asset Management, Simulation |
| Companies Covered | PTC ThingWorx, Dassault Systèmes, Siemens Digital Industries Software, NVIDIA, Bentley Systems, Microsoft Azure Digital Twins, GE Digital, AVEVA, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Twin Market Emerging Trajectories
Real-time physics simulation is migrating from centralized cloud clusters toward distributed edge infrastructure, compressing latency constraints and enabling closed-loop control applications previously infeasible with round-trip cloud delays.
GPU-accelerated physics engines is consolidating high-fidelity simulation workloads previously distributed across CPU-based finite element packages and specialized CAE tools. Automotive powertrain engineering teams in Stuttgart and Wolfsburg now deploy unified platforms for thermal, structural, and fluid dynamics analysis. This consolidation collapses vendor fragmentation and forces incumbents to integrate or partner for survival.
REACH substance restriction expansions are forcing twin platforms to embed chemical compliance tracking into material selection workflows. Industrial equipment manufacturers must now model substitution pathways for restricted substances across entire supply chains. German automotive suppliers face the steepest adaptation requirements as they reconcile REACH deadlines with existing platform refresh cycles.
Engineering procurement organizations are unbundling perpetual software licenses in favor of consumption-based simulation credits tied to actual compute hours. This shift transfers utilization risk from capital budgets to operating expenditures. Aerospace design houses in Toulouse and Seattle demonstrate the most aggressive migration toward metered access models.
Digital Twin Market Segmentation
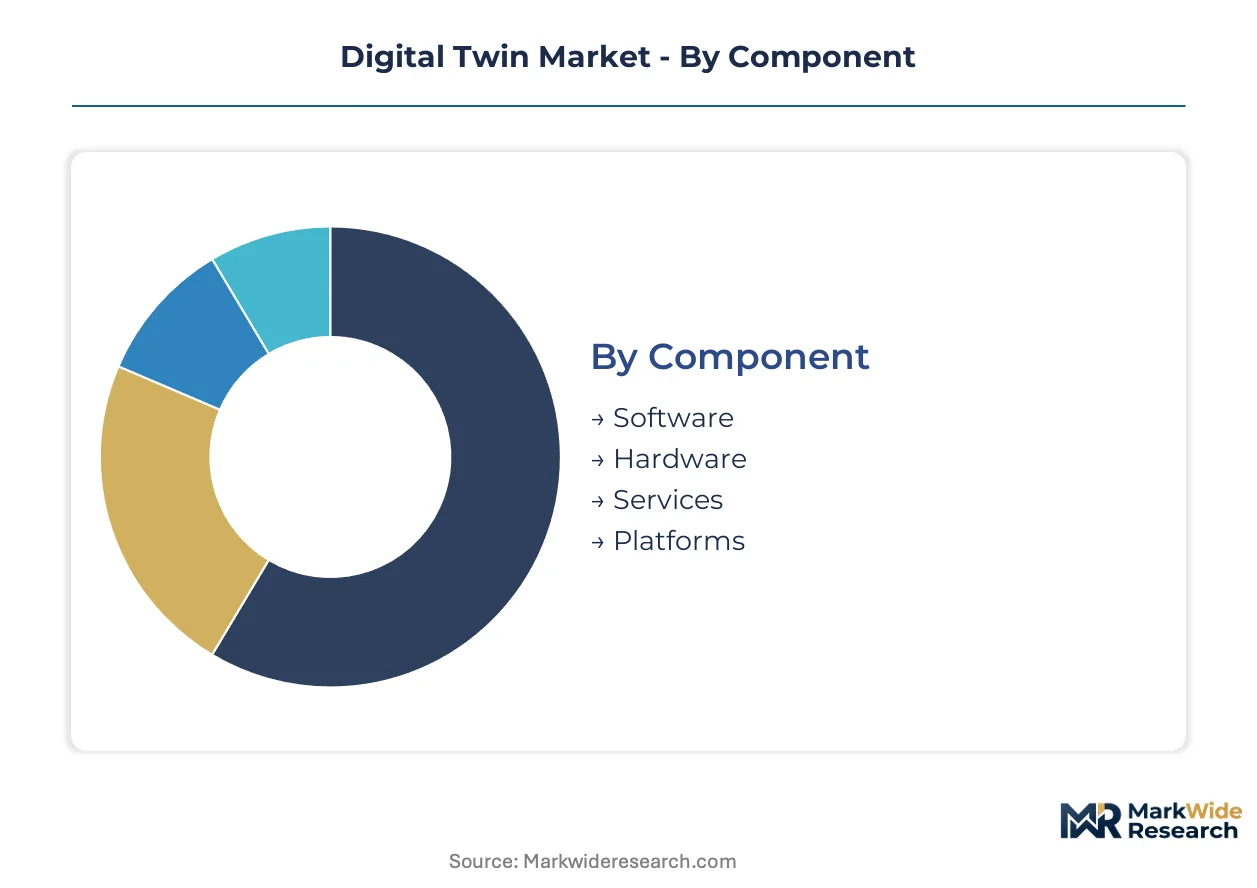
Segmentation reveals where certification burdens concentrate and how compliance costs reshape competitive positioning across the digital twin value chain. Component choices determine recurring licensing exposure, while deployment modes dictate which data sovereignty rules apply.
Component:
FAA airworthiness certification requirements fall most heavily on software and platform segments, while hardware components face FCC electromagnetic interference testing for IoT sensor arrays.
- Software:Physics engines and simulation kernels require algorithmic transparency documentation under EU AI Act mandates. Siemens and Dassault Systèmes anchor demand in Stuttgart and Toulouse aerospace design centers, where perpetual license unbundling toward consumption-based credits accelerates.
- Platforms:Integrated CAD-twin environments demand ISO 27001 certification for enterprise data governance. German automotive OEMs in Wolfsburg and Munich drive platform consolidation as GPU-accelerated workloads disperse across edge nodes.
- Hardware:Edge servers and sensor gateways face NHTSA validation timelines for autonomous vehicle deployments.
- Services:Systems integration and managed twin operations require sector-specific expertise bridging IT-OT convergence.
Software sits at the top of the volume ranking, with platforms climbing the fastest as vendor consolidation collapses fragmented CAE toolchains.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from operating-expenditure cloud models, with hybrid architectures absorbing the highest integration labor.
- Cloud-Based:Multi-tenant infrastructure enables rapid scaling without facility capital, though GDPR cross-border friction fragments networks spanning German assets and US hyperscale regions. REACH compliance tracking for chemical substance workflows adds architectural complexity.
- Edge Computing:Sub-10-millisecond latency requirements for robotics and autonomous vehicle control demand GPU-accelerated local servers. 5G private networks in Bavarian manufacturing corridors anchor the densest deployment cluster.
- Hybrid:Split workloads between sensitive on-premises physics simulation and cloud-based collaboration layers.
- On-Premises:Sovereign data requirements in defense and critical infrastructure sustain legacy capital commitments.
Cloud-based deployments capture the broadest customer base, while edge computing gains share fastest as latency constraints harden for safety-critical applications.
End User:
Application intensity varies sharply by sector physics complexity, with aerospace and automotive presenting the steepest model fidelity requirements.
- Aerospace:Engine lifecycle simulation and flight control certification demand the highest computational fluid dynamics resolution. FAA validation cycles in Seattle and Toulouse compress first-mover advantages for propulsion system twins.
- Automotive:Powertrain thermal and structural analysis consolidates onto unified GPU platforms in Stuttgart engineering centers. KBA type approval requirements for autonomous systems accelerate investment in interpretable physics models.
- Manufacturing:Predictive maintenance ROI visibility drives adoption across asset-heavy production lines.
- Healthcare:Patient-specific organ modeling faces FDA 510(k) clearance pathways for clinical decision support.
Automotive sits at the top of the volume ranking, with aerospace climbing the fastest as multi-year certification timelines eventually yield captive supplier relationships.
Application:
Margin structure diverges between high-frequency operational applications and episodic design-phase simulation, with maintenance workflows generating the most visible ROI documentation.
- Predictive Maintenance:Continuous asset monitoring via IoT sensor streams enables degradation modeling before failure. Offshore energy infrastructure in the North Sea and aviation propulsion systems demonstrate the strongest unplanned downtime compression.
- Simulation:Real-time physics engines for scenario testing require the steepest compute investment. GPU consolidation displaces CPU-based finite element packages across automotive thermal and structural analysis.
- Product Design:Integrated CAD-twin workflows collapse iteration cycles for aerospace airframe development.
- Asset Management:Lifecycle cost optimization spans procurement through decommissioning for capital-intensive equipment.
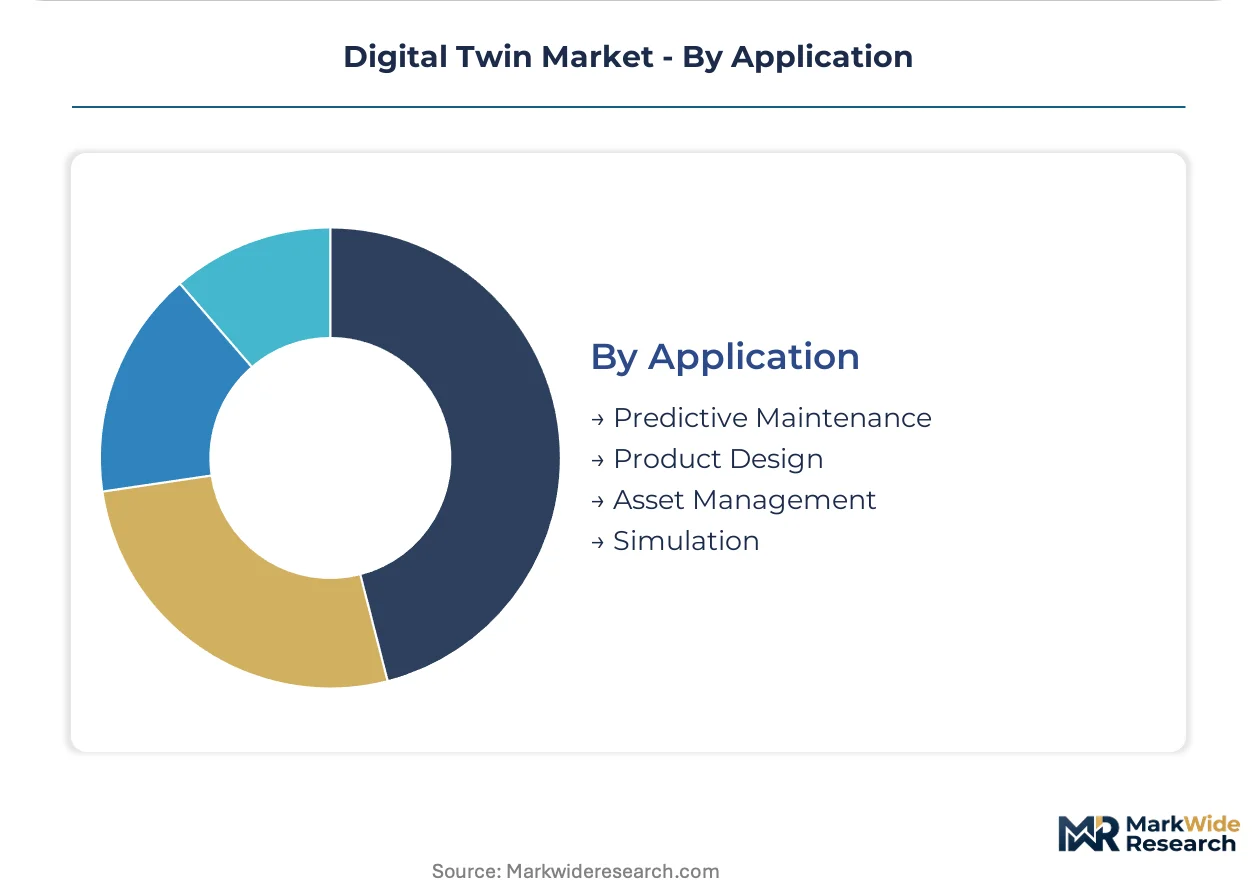
Predictive maintenance sits at the top of the volume ranking, with simulation climbing the fastest as GPU acceleration democratizes high-fidelity physics access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates twin deployment for automotive powertrain engineering while the United States leads aerospace certification cycles. China accelerates greenfield manufacturing integration through state-backed industrial digitization programs. India's production-linked incentives attract first-mover deployments without legacy system burdens.
United States
FAA airworthiness certification for aviation propulsion twins drives multi-year validation investments in Seattle and Wichita engineering centers. The Inflation Reduction Act channels tax credits toward grid modernization twins for battery lifecycle optimization. Boeing anchors the densest aerospace cluster, where flight control system twins face NHTSA parallel validation for autonomous vehicle crossover applications.
Germany
REACH substance restriction expansions force twin platforms to embed chemical compliance tracking into material selection workflows. The EU AI Act mandates algorithmic transparency for autonomous twin-driven decisions across Bavarian manufacturing corridors. Siemens and automotive OEMs in Stuttgart and Wolfsburg anchor the densest adoption cluster, where GPU-accelerated physics engines consolidate previously fragmented CAE toolchains.
China
Dual carbon goals and MIIT industrial digitization directives accelerate twin deployment for energy-intensive process optimization. GB standards for smart manufacturing create regulatory scaffolding for state-backed pilot programs. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou concentrate greenfield twin installations for semiconductor and battery cell production.
India
PLI scheme incentives for semiconductor and advanced chemistry cell manufacturing create deployment opportunities without legacy integration burdens. The country's national industrial regulator promotes smart factory standards through production-linked incentive frameworks. Karnataka and Tamil Nadu engineering corridors attract first-mover twin investments for electronics manufacturing services and automotive component digitization.
France
ECHA chemical compliance requirements intersect with CSRD sustainability reporting mandates for industrial equipment lifecycle documentation. ANSM and CNIL data governance frameworks shape twin architectures for healthcare and aerospace applications. Toulouse aerospace design houses demonstrate aggressive migration toward metered simulation access models, collapsing perpetual license structures.
Digital Twin Market Vendor Landscape
German producers anchor one tier; US specialists hold another through compute infrastructure dominance. The vendor base stratifies between industrial software heritage players and cloud-native platform entrants. Three archetypes define positioning: physics engine specialists, integrated CAD-twin platform providers, and GPU-accelerated simulation infrastructure vendors. M&A activity concentrates on vertical-specific ontology libraries, while strategic partnerships bridge IT-OT convergence gaps.
Among Germany-based industrial software providers, Siemens Digital Industries Software and Dassault Systèmes exemplify integrated platform archetypes. NVIDIA occupies a position as compute infrastructure anchor for GPU-accelerated physics simulation. These three represent distinct competitive vectors: industrial software heritage, integrated design-twin workflows, and underlying simulation hardware acceleration.
| Leading Market Players |
|---|
| PTC ThingWorx |
| Dassault Systèmes |
| Siemens Digital Industries Software |
| NVIDIA |
| Bentley Systems |
| Microsoft Azure Digital Twins |
| GE Digital |
| AVEVA |
| IBM |
| Others |
Supply Flow & Price Mechanics
GPU memory pricing indices cascade through digital twin supply chains, compressing margins for edge server assemblers while concentrating pricing power with NVIDIA and high-bandwidth memory foundries in South Korea. Cloud hyperscalers leverage volume scale to extract SaaS-tiered discounts from physics engine vendors, fragmenting price architecture across deployment modes.
Pricing Analysis
Distributor margins for IoT sensor gateways run 12-18% before value-added integration services, while direct-to-OEM channels for GPU-accelerated edge servers command steeper volume discounts. Pricing stratifies across perpetual license, consumption-based simulation credits, and fully managed SaaS tiers, with certification grade for FAA airworthiness documentation commanding 40-60% premiums over non-certified deployments. Cost compression in mid-market manufacturing segments is intensifying because perpetual license unbundling transfers utilization risk to vendors. Asset-heavy sectors including aviation propulsion and offshore energy demonstrate the lowest price sensitivity due to measurable unplanned downtime reduction.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Siemens and automotive OEMs in Stuttgart, while systems integrators serve mid-market manufacturers lacking in-house IT-OT convergence expertise. GPU fabrication concentrates in Taiwan and South Korea, with high-bandwidth memory supply anchored in South Korean foundries and advanced packaging in Taiwan. The supply chain draws from specialized computational fluid dynamics licensing, precision IoT sensor arrays, and cloud hyperscaler infrastructure. Single-source vulnerability for NVIDIA A100/H100 accelerators creates chokepoint exposure for physics simulation workloads. Distribution runs through vendor-direct enterprise sales teams, channel partners for geographic coverage, and cloud marketplaces for rapid provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates compound demand for interpretable physics models, creating sustained procurement velocity across European manufacturing corridors.
For Market Incumbents: Lock in captive supplier relationships through multi-year FAA certification co-development programs that compress competitor entry timelines. Deepen backward integration into edge server assembly to capture GPU margin compression, while embedding REACH compliance tracking as a platform-native feature to increase switching costs for German automotive OEMs. For New Entrants and Emerging Players: Capture greenfield deployment opportunities in India's PLI scheme corridors for semiconductor and battery cell manufacturing, where legacy system integration burdens are absent. Target consumption-based simulation credit models for mid-market aerospace design houses in Toulouse and Seattle seeking to collapse perpetual license commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical-specific ontology library specialists bridging IT-OT convergence gaps for predictive maintenance applications. Long-term viability centers on platforms demonstrating FDA 510(k) pathway progress for healthcare twins or FAA airworthiness certification traction for aviation propulsion systems. Watch for GPU supply normalization as the inflection signal for margin expansion in edge-native deployment architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidation of fragmented CAE toolchains onto GPU-accelerated unified environments collapses vendor switching costs for Stuttgart engineering centers. |
| Acquisition of Specialist Firm | Vertical-specific ontology libraries for REACH chemical compliance tracking command scarcity premiums from German automotive suppliers facing substitution deadlines. |
| Strategic Partnership | 5G private network deployments in Bavarian manufacturing corridors enable sub-10-millisecond latency for safety-critical robotics control applications. |
| Product Launch | Consumption-based simulation credit models disrupt perpetual license structures for aerospace design houses migrating toward metered access. |
| Geographic Expansion | Edge-native twin architectures in Karnataka and Tamil Nadu engineering corridors exploit India's PLI scheme incentives without legacy integration burdens. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with platform engineering directors, IT procurement officers at automotive OEMs, systems integration specialists, and physics simulation researchers with secondary validation from SEC filings of industrial software vendors, hyperscaler capex disclosures, FAA certification databases, and ECHA REACH substance restriction updates.
Input-output matrices map deployment model adoption rates, component licensing structures, and vertical application intensity across the projection horizon, with segmentation dimensions spanning software-platform-hardware-services, cloud-edge-hybrid-on-premises, aerospace-automotive-manufacturing-healthcare, and predictive maintenance-simulation-product design-asset management. CAGRs derive from regression analysis against technology diffusion curves and regulatory compliance investment cycles, with GPU supply constraints and EU AI Act implementation timelines as specific forecast inputs.
Regulatory enforcement variance, GPU supply normalization trajectories, and REACH substance restriction expansion schedules are the dominant revision risks to base-case projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Global E-Signature Platform Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
France ICT Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Social Networking App Market
Digital Solutions
Digital Clothing Market