
 France Geospatial Analytics Market | 2026-2036
France Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
France Geospatial Analytics Market Insights
Modular subscription tiers for geospatial platforms is recalibrating how French buyers evaluate total cost of ownership against perpetual licensing. Esri France leverages its localized ArcGIS ecosystem to dominate municipal and regional government accounts. Hexagon AB anchors its position through sensor-to-software integration across surveying and autonomous mapping workflows. Thales Alenia Space competes on dual-use satellite constellations that bridge defense and civilian earth observation requirements.
Geospatial analytics encompasses the computational processing of location-referenced data from satellite imagery, aerial sensors, GPS networks, and ground-based IoT feeds to generate spatial intelligence for decision support; systems typically process raster and vector data layers at sub-meter resolution to model terrain, infrastructure, and population dynamics. Remote sensing technology leads current revenue contribution as defense and climate agencies commission high-frequency revisit capabilities from Airbus Defence and Space Intelligence and Safran optical payloads. Big data analytics represents the fastest-expanding segment as energy companies and construction firms ingest petabyte-scale geospatial streams for predictive asset management. Cloud-based deployment now captures the dominant share of new platform rollouts, though hybrid architectures persist where IGN maintains sovereign data custody for sensitive cadastral information.
France's national mapping agency IGN operates under the Ministry of Ecological Transition, enforcing data sovereignty standards that shape vendor qualification for public contracts. The EU AI Act and GDPR impose algorithmic transparency and personal data constraints on location intelligence products, particularly where GPS-derived mobility patterns intersect with individual identification. ANSM and CNIL oversight extends to health-geography applications, limiting how healthcare providers deploy spatial patient analytics. Stakeholders must monitor whether upcoming EU space legislation tightens foreign access restrictions to French earth observation assets.
Market Dynamics
France's geospatial analytics sector is restructuring around sovereign data requirements and cloud-native platform migrations, as public agencies reconcile EU Green Deal mandates with IGN's data custody protocols.
Growth Catalysts
- EU Green Deal biodiversity mandates:Public-sector buyers accelerate platform upgrades to monitor ecosystem health and land-use change across metropolitan France.
- Dual-use satellite constellations:Defense-civilian bridge applications expand procurement budgets for high-frequency earth observation capabilities.
- Paris-Saclay cluster concentration:Aerospace and software engineering competency overlap draws specialized talent and R&D investment to the Île-de-France region.
Market Restraints
- IGN data sovereignty standards:Vendor qualification for public contracts requires costly infrastructure adaptations and compliance verification.
- GDPR algorithmic transparency constraints:Location intelligence products face restrictions where GPS mobility patterns intersect with individual identification.
- Hybrid architecture persistence:Sensitive cadastral information custody requirements slow full cloud migration and inflate operational complexity.
Strategic Opportunities
- Petabyte-scale predictive asset management:Energy companies and construction firms seek new ingestion pipelines for operational geospatial streams.
- EU space legislation tailwinds:Potential foreign access restrictions to French earth observation assets create protected domestic demand.
- Health-geography integration:ANSM and CNIL oversight frameworks open compliant pathways for spatial patient analytics deployment.
Industry Challenges
- Sub-meter resolution processing talent scarcity:Raster and vector data layer expertise concentrates in defense and climate agencies, limiting commercial sector hiring pools.
- Legacy municipal system integration:ArcGIS ecosystem dominance creates switching friction for regional government accounts evaluating alternative platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Geospatial Analytics Market |
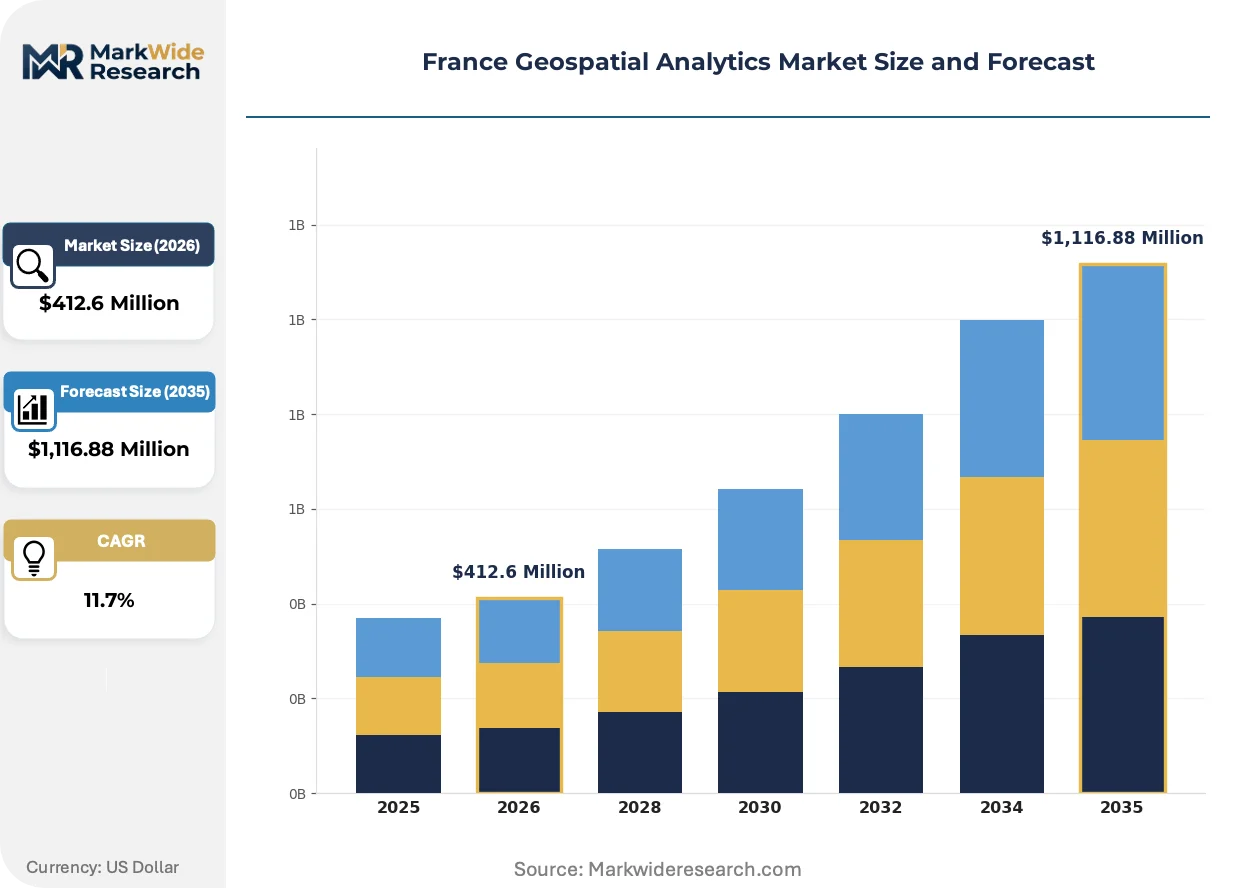
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,116.88 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Monitoring, Transportation Management, Agriculture Optimization Technology: GIS, Remote Sensing, GPS, Big Data Analytics End User: Government Agencies, Healthcare Providers, Construction Firms, Energy Companies Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Solutions |
| Companies Covered | Esri France, Trimble Geospatial, Hexagon AB, Airbus Defence and Space Intelligence, Thales Alenia Space, Bentley Systems, CLS Groupe, Safran, IGN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Geospatial Analytics Market Trends and Innovations
Computational processing of location-referenced data is pivoting from batch analytics to real-time streaming architectures, compressing decision cycles across defense, climate, and infrastructure verticals.
AI-powered feature extraction from satellite imagery is automating terrain classification workflows that previously required manual photointerpretation. French defense agencies and climate monitoring bodies are deploying these systems at operational scale. The technology is automating infrastructure resilience assessments and compressing project timelines from months to days.
France's national mapping agency IGN enforces data sovereignty standards under the Ministry of Ecological Transition that shape vendor qualification protocols. These requirements mandate domestic data residency for sensitive cadastral information. Municipal and regional government accounts respond by specifying hybrid cloud architectures in procurement specifications.
Subscription-based platform evaluation is displacing perpetual licensing as the dominant commercial framework. French buyers now prioritize total cost of ownership calculations over upfront capital expenditure. This shift concentrates in the Paris-Saclay cluster where aerospace and software engineering competencies overlap.
France Geospatial Analytics Market Segmentation
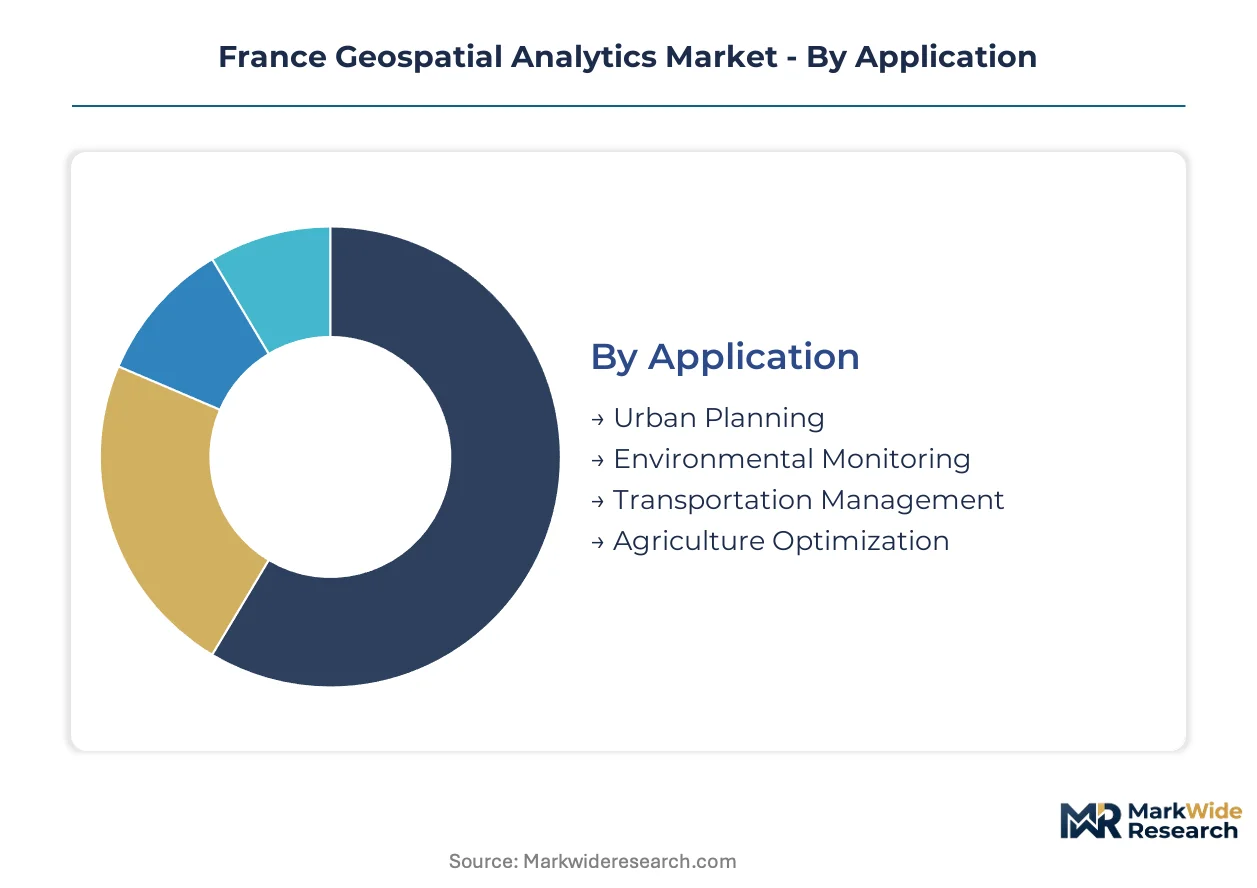
Segmentation in the France geospatial analytics market reveals how buyer priorities diverge across regulatory environments, infrastructure maturity, and data sovereignty requirements. Procurement patterns cluster around application-specific compliance mandates and deployment architecture preferences shaped by IGN custody protocols.
Application:
Buyer investment decisions hinge on regulatory compliance intensity and infrastructure lifecycle requirements.
- Urban Planning:Municipal authorities deploy sub-meter resolution terrain modeling for zoning compliance and infrastructure resilience assessments. Paris-Saclay cluster competencies support metropolitan France's densification projects under EU Green Deal land-use directives.
- Environmental Monitoring:Biodiversity tracking and ecosystem health assessment dominate public-sector procurement. The EU Green Deal mandates accelerate platform upgrades across regional environmental agencies monitoring land-use change.
- Transportation Management:GPS-derived mobility pattern analysis supports logistics optimization and public transit planning. GDPR constraints limit individual identification capabilities in commercial deployments.
- Agriculture Optimization:Precision farming applications ingest satellite imagery for crop health monitoring and yield prediction. French agricultural cooperatives pilot predictive asset management for irrigation and fertilization scheduling.
Volume sits with Urban Planning; growth tilts toward Environmental Monitoring.
Technology:
Technology selection reflects data volume thresholds and processing latency requirements across defense and civilian workflows.
- GIS:Spatial data management platforms process raster and vector layers for cadastral mapping and infrastructure inventory. Esri France's localized ArcGIS ecosystem dominates municipal and regional government accounts through switching friction.
- Remote Sensing:High-frequency satellite revisit capabilities from Airbus Defence and Space Intelligence and Safran optical payloads lead current revenue contribution. Defense and climate agencies commission sub-meter resolution for terrain intelligence.
- GPS:Location-referenced data feeds from ground-based networks enable real-time asset tracking and navigation services. GDPR algorithmic transparency constraints restrict mobility pattern applications intersecting individual identification.
- Big Data Analytics:Petabyte-scale ingestion pipelines for predictive asset management attract energy companies and construction firms. This segment climbs the fastest as operational geospatial streams expand beyond batch processing architectures.
Revenue concentrates in Remote Sensing; capability investment flows toward Big Data Analytics.
End User:
End-user segmentation tracks procurement authority levels and data sensitivity classifications.
- Government Agencies:National mapping agency IGN and Ministry of Ecological Transition buyers enforce sovereign data standards. Public contracts require domestic data residency and costly vendor qualification protocols.
- Healthcare Providers:Spatial patient analytics face ANSM and CNIL oversight limiting deployment scope. Compliant pathway development opens regulated health-geography integration opportunities.
- Construction Firms:Infrastructure project timelines compress through AI-powered feature extraction from satellite imagery. Terrain classification automation reduces photointerpretation from months to days.
- Energy Companies:Predictive asset management for pipeline networks and renewable installations drives petabyte-scale stream ingestion. Operational geospatial analytics support resilience planning against climate-induced infrastructure stress.
Procurement volume favors Government Agencies; commercial expansion targets Energy Companies.
Deployment:
Deployment architecture selection balances operational flexibility against data custody requirements.
- Cloud-Based:Dominant share of new platform rollouts supports scalable compute for real-time streaming architectures. Subscription-based evaluation displaces perpetual licensing in total cost of ownership calculations.
- On-Premise:Sensitive cadastral information custody requirements persist where IGN maintains sovereign data control. Legacy municipal system integration creates switching friction for regional government accounts.
- Hybrid:Municipal and regional procurement specifications increasingly mandate domestic data residency with cloud burst capacity. IGN standards shape vendor qualification through infrastructure adaptation requirements.
- Mobile Solutions:Field-deployable geospatial intelligence supports defense-civilian bridge applications and emergency response coordination. Dual-use satellite constellation data feeds enable disconnected operational environments.
New rollouts concentrate in Cloud-Based; compliance requirements sustain Hybrid architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes geospatial analytics capacity faster than it produces satellite hardware, creating import dependency for optical payloads while domestic software engineering captures platform value. The Paris-Saclay cluster concentrates aerospace and data science competencies that shape national procurement patterns. Regional demand spreads across metropolitan infrastructure agencies, defense buyers, and EU-mandated environmental monitors.
Île-de-France
The Paris-Saclay cluster anchors national demand for sub-meter resolution terrain intelligence and real-time streaming architectures. IGN headquarters in Saint-Mandé enforces data sovereignty standards that shape vendor qualification for public contracts across the region. Aerospace engineering competencies at Saclay and Vélizy-Villacoublay draw specialized talent for defense-civilian satellite constellation development.
Auvergne-Rhône-Alpes
Precision agriculture applications in the Rhône Valley drive satellite imagery procurement for crop health monitoring and irrigation optimization. The EU Green Deal biodiversity mandates accelerate platform upgrades among regional environmental agencies tracking alpine ecosystem change. Grenoble's sensor technology base supports ground-based IoT feed integration into geospatial analytics pipelines.
Provence-Alpes-Côte d'Azur
Maritime surveillance and coastal infrastructure resilience planning dominate public-sector procurement in Marseille and Toulon. The region's defense-civilian bridge applications expand budgets for high-frequency earth observation from Mediterranean-facing ground stations. Sophia Antipolis technology park hosts specialized firms developing AI-powered feature extraction for terrain classification.
Hauts-de-France
Logistics corridor optimization along the Calais-Dunkirk axis generates GPS-derived mobility pattern analysis demand from freight operators. GDPR constraints limit individual identification capabilities in commercial deployments across the Channel transit zone. Lille's metropolitan planning authority pilots hybrid cloud architectures balancing IGN data custody with operational flexibility.
Nouvelle-Aquitaine
Forest carbon monitoring and coastal erosion assessment drive environmental agency platform investment in Bordeaux and La Rochelle. The EU Green Deal land-use directives accelerate biodiversity tracking procurement across the Landes forest and estuarine systems. The region's agricultural cooperatives pilot predictive asset management for vineyard and cereal crop optimization.
France Geospatial Analytics Market Competitive Landscape
The competitive structure tilts toward integrated sensor-to-software providers over pure-play analytics platforms. Defense-civilian dual-use capabilities and sovereign data compliance credentials determine vendor selection for public contracts. Three archetypes dominate: satellite constellation operators with optical payload manufacturing, geospatial platform vendors with municipal ArcGIS integration depth, and surveying equipment specialists with autonomous mapping workflows. Competitive moves concentrate on hybrid cloud architecture certification and AI-powered feature extraction capability acquisition.
Among France-based defense and aerospace specialists, Thales Alenia Space and Airbus Defence and Space Intelligence exemplify the dual-use constellation archetype bridging military and civilian earth observation requirements. Esri France occupies a position representing the platform-centric tier through localized ArcGIS ecosystem dominance in municipal and regional government accounts. Hexagon AB anchors the sensor-integrated workflow segment through surveying and autonomous mapping specialization.
| Leading Market Players |
|---|
| Esri France |
| Trimble Geospatial |
| Hexagon AB |
| Airbus Defence and Space Intelligence |
| Thales Alenia Space |
| Bentley Systems |
| CLS Groupe |
| Safran |
| IGN |
| Others |
Pricing and Supply Chain Analysis
Sentinel-2 optical payload pricing indices cascade through French geospatial supply chains, compressing margins for downstream analytics platforms while amplifying differentiation premiums for IGN-certified sovereign data custody tiers.
Pricing Analysis
Margin tightening in cloud-native platform tiers reflects Airbus Defence and Space Intelligence's orbital revisit rate premiums. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-hybrid deployments from pure-cloud subscriptions. Certification grade under EU AI Act algorithmic transparency mandates commands 15-25% price premiums over uncertified alternatives. Energy companies exhibit lowest price sensitivity due to predictive asset management ROI visibility, while municipal governments face strict budget caps under perpetual-to-subscription transition pressures.
Supply Chain Analysis
IGN data sovereignty mandates reshape sourcing toward domestic cloud infrastructure providers with Saint-Mandé data residency guarantees. Optical payload manufacturing concentrates in France, Germany, and Spain through Airbus and Safran supply networks. Gallium arsenide sensor substrates and precision optics constitute critical input dependencies. Single-source vulnerability persists for sub-meter resolution satellite constellations. Distribution runs through direct public-sector procurement channels and specialized systems integrators serving Paris-Saclay cluster accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's geospatial analytics sector functions as a cost-of-compliance market where EU Green Deal biodiversity monitoring mandates erect regulatory moats favoring incumbent platform vendors with established IGN certification pathways.
For Market Incumbents: Deploy hybrid cloud architecture certification as the primary defensive lever. Esri France and Hexagon AB should deepen ArcGIS-IGN integration protocols to heighten switching friction for municipal accounts. Counter emerging pure-play AI feature extraction entrants by acquiring satellite-to-analytics workflow specialists. Threat vector: cloud-native challengers bypassing sovereign data custody requirements through offshore processing. For New Entrants and Emerging Players: Capture health-geography white space where ANSM and CNIL oversight frameworks have limited incumbent penetration. Precision agriculture cooperatives in Nouvelle-Aquitaine and Auvergne-Rhône-Alpes represent the most penetrable commercial segment. Go-to-market angle: GDPR-compliant patient mobility analytics with pre-certified algorithmic transparency documentation. For Investors and Strategic Acquirers: Distressed-cycle entries favor sensor-to-software integrated mid-caps with established defense-civilian bridge capabilities in Île-de-France. Long-term viability hinges on EU space legislation foreign-access restriction timing. Acquisition target archetype: AI-powered terrain classification specialists with IGN hybrid architecture credentials. Signal to watch: Ministry of Ecological Transition procurement specification shifts toward real-time streaming mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Architecture Certification | IGN data sovereignty compliance unlocks municipal and regional government contract eligibility. |
| AI-Powered Feature Extraction Acquisition | Automated terrain classification compresses project timelines from months to days for construction clients. |
| Dual-Use Satellite Constellation Expansion | Defense-civilian bridge applications expand procurement budgets through Thales Alenia Space channels. |
| Health-Geography Compliance Pathway Development | ANSM and CNIL pre-certification opens regulated spatial patient analytics deployment. |
| Paris-Saclay Cluster Talent Concentration | Aerospace and software engineering overlap draws specialized R&D investment for sovereign analytics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this France geospatial analytics assessment. Primary interviews with satellite payload procurement officers, IGN certification auditors, municipal IT directors, and defense-civilian bridge program managers combined with bottom-up platform deployment tallies and top-down EU Green Deal budget allocation analysis. Secondary sources included EU Space Programme Agency documents, Ministry of Ecological Transition procurement databases, CNIL algorithmic transparency guidance, and Airbus Defence and Space Intelligence contract announcements.
Segmentation granularity modeled deployment architecture at the cloud-hybrid-on-premise level, end-user type at government-commercial split, and application vertical at urban planning-environmental monitoring-transportation-agriculture resolution. Technology trajectories incorporated remote sensing, GIS, GPS, and big data analytics capability maturation curves across the projection horizon. CAGRs derived from subscription pricing trend analysis and public-sector procurement volume tracking. Industry-specific inputs included Sentinel constellation revisit rate improvements and EU AI Act implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU space legislation foreign access restrictions and IGN data sovereignty standard evolution. Forecasts reflect documented assumptions regarding EU Green Deal biodiversity mandate funding continuity and Paris-Saclay cluster talent retention. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market