
 Japan Location-Based Services Market | 2026-2036
Japan Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Location-Based Services Market Insights
Japan is tilting toward precision positioning infrastructure as METI promotes Industry 4.0 integration across manufacturing zones. Google LLC leverages its global mapping corpus to dominate consumer navigation and local search services. SoftBank Group Corp. sustains competitive positioning through telecommunications-anchored IoT platforms and 5G network densification. Kokusai Kogyo Co., Ltd. anchors public-sector demand with surveying and geospatial systems for infrastructure planning.
Location-based services encompass technologies that determine geographic coordinates and deliver contextual information through GPS, Wi-Fi, Bluetooth, and NFC signal processing, with accuracy thresholds ranging from centimeter-grade RTK-GPS for surveying to meter-grade cellular positioning for consumer applications. These systems enable real-time asset tracking, proximity marketing, and spatial analytics across commercial and industrial operations. Navigation and fleet management applications lead current revenue generation due to mature enterprise adoption, while location-based advertising and virtual fitting rooms represent faster-expanding segments as retailers pursue omnichannel engagement. GPS technology dominates hardware deployment, though Bluetooth beacon networks are displacing Wi-Fi for indoor proximity use cases where power efficiency matters.
METI's data governance guidelines intersect with JIS standards for location data interoperability, shaping vendor compliance costs and system architecture choices. The Act on the Protection of Personal Information imposes granular consent requirements that constrain passive geolocation collection and mandate data localization for sensitive movement patterns. Stakeholders must monitor evolving interpretations of anonymization standards and their impact on cross-platform data fusion strategies.
Market Dynamics
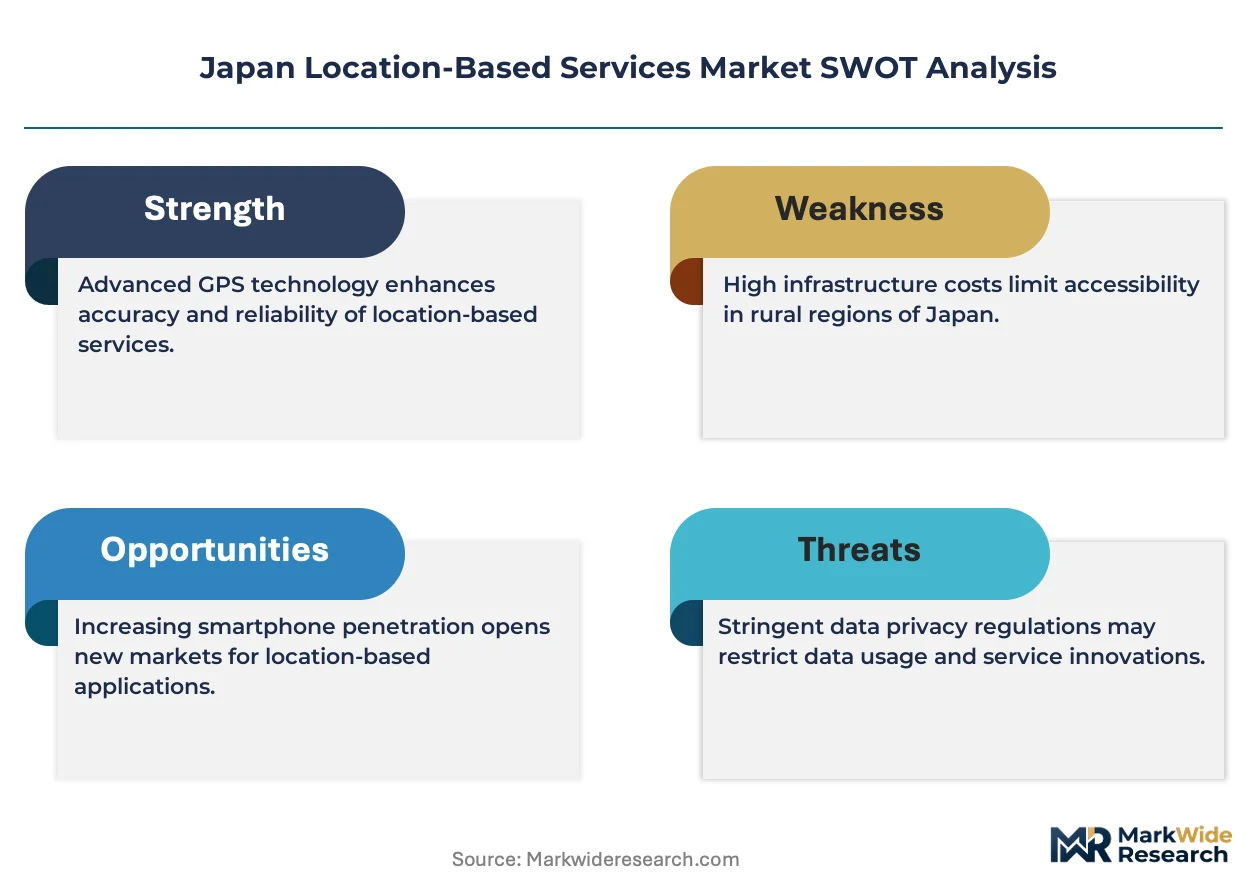
Japan's Location-Based Services market pivots on METI's Industry 4.0 integration mandates, which compel manufacturers to deploy centimeter-grade positioning for automated guided vehicles and robotic process automation across the Kanto and Kansai industrial corridors.
Growth Catalysts
- Act on the Protection of Personal Information revisions:Tightened consent frameworks paradoxically legitimize first-party data collection, enabling retailers to deploy Bluetooth beacon networks for indoor customer analytics with clearer legal boundaries.
- Transportation and logistics corridors:Dense freight movement between Tokyo, Yokohama, Osaka, and Kobe generates sustained demand for fleet management and real-time asset tracking solutions.
- 5G network densification:SoftBank's accelerated base station deployment reduces latency for meter-grade cellular positioning, expanding addressable use cases beyond GPS-dependent outdoor applications.
Market Restraints
- Semiconductor input volatility:Positioning chipsets and Bluetooth SoCs face supply concentration risk from Taiwan and South Korean foundries, compressing hardware margins for domestic system integrators.
- Technical limitation of Wi-Fi fingerprinting:Signal multipath in steel-frame commercial buildings degrades indoor accuracy below retail requirements, forcing expensive infrastructure overlays.
- Data localization mandates:Sensitive movement pattern storage on domestic servers increases operational overhead for multinational platform providers serving Japanese enterprises.
Strategic Opportunities
- Hokkaido and Tohoku underpenetration:Sparse retail and logistics infrastructure in northern prefectures represents greenfield deployment potential for cold-chain asset tracking and agricultural machinery positioning.
- Virtual fitting room convergence:AR-enabled spatial computing in apparel retail merges location data with computer vision, creating premium service tiers for omnichannel merchants.
- JIS standards harmonization:Emerging interoperability protocols for location data exchange reduce vendor lock-in and enable modular system architecture for mid-size manufacturers.
Industry Challenges
- RTK-GPS surveyor skill scarcity:Centimeter-grade deployment requires certified geodetic engineers, with training pipelines failing to match METI's precision agriculture and construction automation timelines.
- Legacy warehouse management integration:Proprietary WMS protocols in established logistics operators resist API standardization, extending implementation cycles for unified fleet-visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Location-Based Services Market |
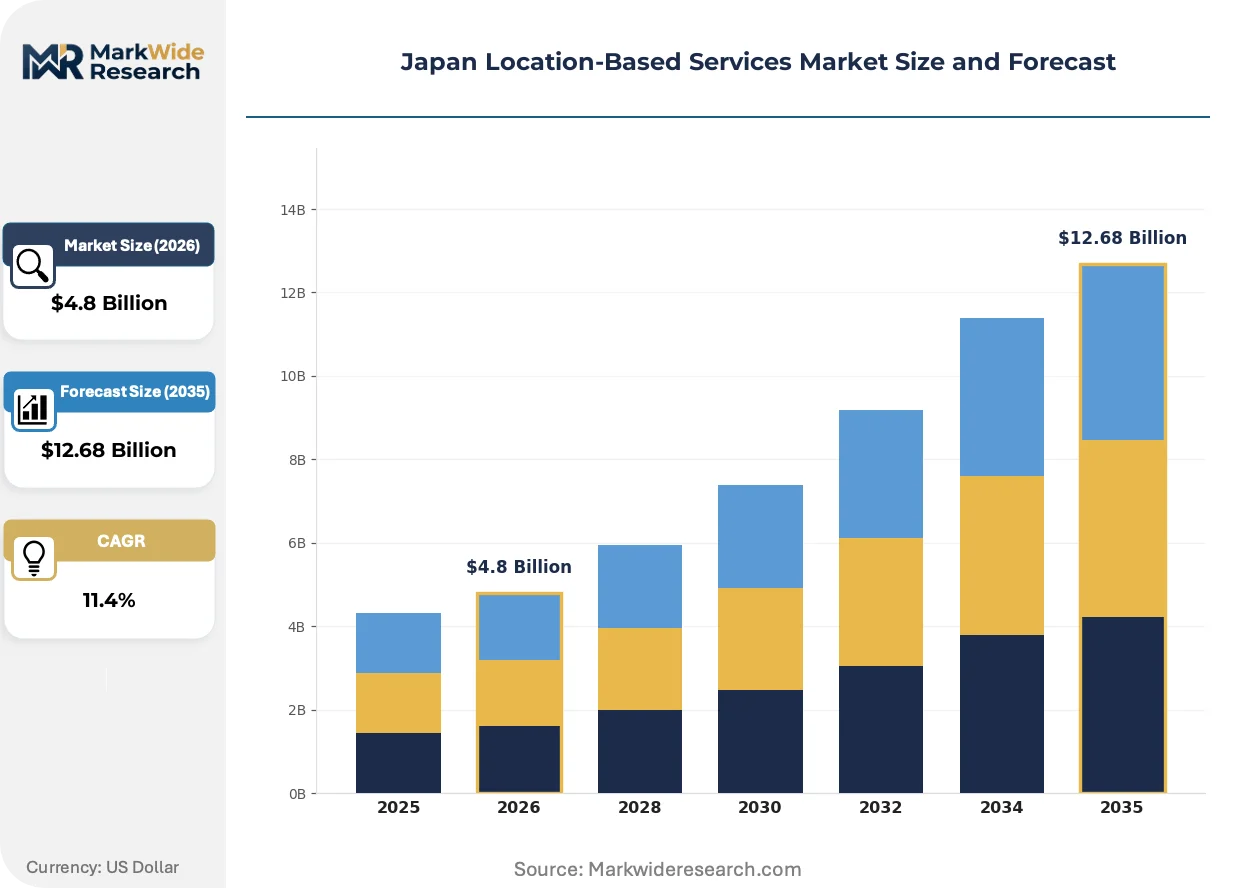
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, Wi-Fi, Bluetooth, NFC Application: Navigation, Asset Tracking, Fleet Management, Location-Based Advertising End User: Retail, Transportation, Healthcare, Hospitality Solution: Mapping Services, Analytics, Geofencing, Virtual Fitting Rooms |
| Companies Covered | Google LLC, Kokusai Kogyo Co., Ltd., Hitachi, Ltd., Waveon Co., Ltd., AGOOP Corp., SoftBank Group Corp., Rakuten, Inc., HERE Global B.V., NEC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Location-Based Services Market Trends and Innovations
Digital twin architectures are virtualizing physical space representation across Japanese manufacturing and retail operations, compressing the gap between geospatial data collection and actionable spatial intelligence.
Ultra-wideband positioning is virtualizing indoor location granularity previously achievable only through expensive camera-based systems. Automotive tier-one suppliers in Nagoya and Hiroshima prefectures are piloting UWB for assembly-line tool tracking at sub-30-centimeter accuracy. This virtualization of spatial context eliminates the infrastructure density requirements that constrained Wi-Fi beacon economics in multistory facilities.
METI's data governance guidelines intersect with amended Act on the Protection of Personal Information enforcement, creating compliance complexity for cross-platform location data fusion. Retail chains must now implement granular consent interfaces before passive geolocation collection, increasing UX friction but reducing regulatory exposure. Department store operators in Ginza and Shinsaibashi are responding with explicit value-exchange programs that trade location permissions for personalized promotional access.
Buyer procurement patterns for location-based services are compressing from multi-year enterprise licenses toward modular SaaS subscriptions with usage-based tiers. Mid-size logistics operators in the Keihin industrial zone now favor month-to-month fleet visibility contracts over capital-intensive hardware ownership. This preference shift pressures traditional system integrators to develop cloud-native positioning platforms or cede share to telecommunications-anchored IoT providers.
Japan Location-Based Services Market Segmentation
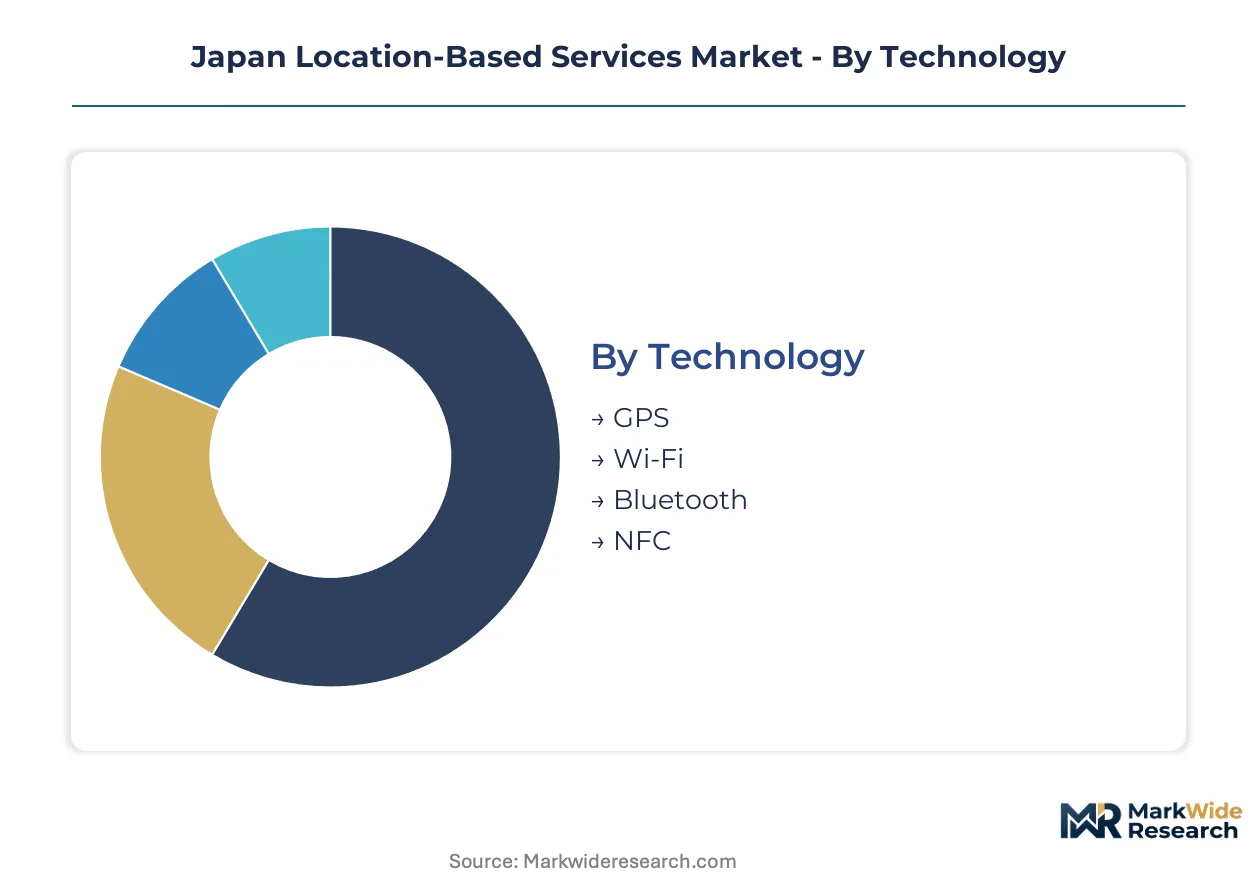
Japan's Location-Based Services market fragments across four distinct dimensions that shape procurement patterns and vendor positioning. Technology choices determine infrastructure investment cycles, while application focus dictates whether providers capture enterprise recurring revenue or consumer transaction fees. End-user verticals impose divergent compliance requirements under the Act on the Protection of Personal Information, and solution types separate platform-scale players from specialized analytics boutiques.
Technology:
Cycle times vary dramatically—GPS hardware refresh spans 5-7 years for industrial receivers, while Bluetooth beacon networks require annual firmware updates and battery replacement schedules.
- GPS:Satellite-based positioning systems deliver meter-grade outdoor accuracy through multi-constellation receivers compatible with Japan's QZSS augmentation. Manufacturing automation in Aichi and Shizuoka prefectures drives demand for centimeter-grade RTK-GPS configurations in automated guided vehicle deployments.
- Wi-Fi:Signal fingerprinting systems leverage existing enterprise access point infrastructure for indoor positioning without dedicated hardware overlays. Multipath interference in Tokyo's steel-frame commercial towers limits accuracy to 3-5 meters, constraining adoption to coarse-grained zone detection rather than precise wayfinding.
- Bluetooth:Low-energy beacon networks enable sub-meter proximity detection with 2-3 year battery lifecycles, powering retail customer analytics in Ginza and Shinsaibashi department stores.
- NFC:Near-field communication tags provide touch-initiated location verification for payment authentication and access control at point-of-sale terminals.
GPS anchors the volume base while Bluetooth gains share at the steepest rate.
Application:
Cost tier separation distinguishes capital-intensive enterprise systems from lightweight consumer-facing deployments.
- Navigation:Turn-by-turn routing and mapping services dominate consumer smartphone engagement through GPS-dependent outdoor positioning. Fleet operators in the Keihin industrial zone integrate navigation with dispatch optimization for last-mile delivery efficiency.
- Asset Tracking:Real-time location monitoring of containers, pallets, and mobile equipment across logistics corridors linking Tokyo, Yokohama, Osaka, and Kobe. Cold-chain operators in Hokkaido deploy cellular-anchored trackers for agricultural product integrity verification.
- Fleet Management:Vehicle telematics combining location, speed, and engine diagnostics for regulatory compliance and fuel optimization. Trucking cooperatives in the Kansai region prioritize driver behavior scoring modules for insurance premium reduction.
- Location-Based Advertising:Proximity-triggered promotional delivery to opted-in smartphone users based on real-time position and dwell-time analysis.
Navigation commands the largest installed base while asset tracking expands most quickly in transportation corridors.
End User:
Customer type determines data sensitivity thresholds and consent interface complexity under METI governance guidelines.
- Retail:Omnichannel merchants deploy indoor positioning for footfall analytics, queue management, and AR-enabled virtual fitting rooms in flagship Tokyo and Osaka locations.
- Transportation:Rail operators and logistics providers integrate location services with scheduling systems and cargo visibility platforms across the Kanto-Kansai freight network.
- Healthcare:Hospitals in urban centers track medical equipment and patient flow while navigating stringent anonymization requirements for movement pattern data.
- Hospitality:Hotel chains and resorts leverage proximity marketing and concierge automation for guest experience personalization.
Transportation anchors enterprise spending while retail drives consumer-facing innovation.
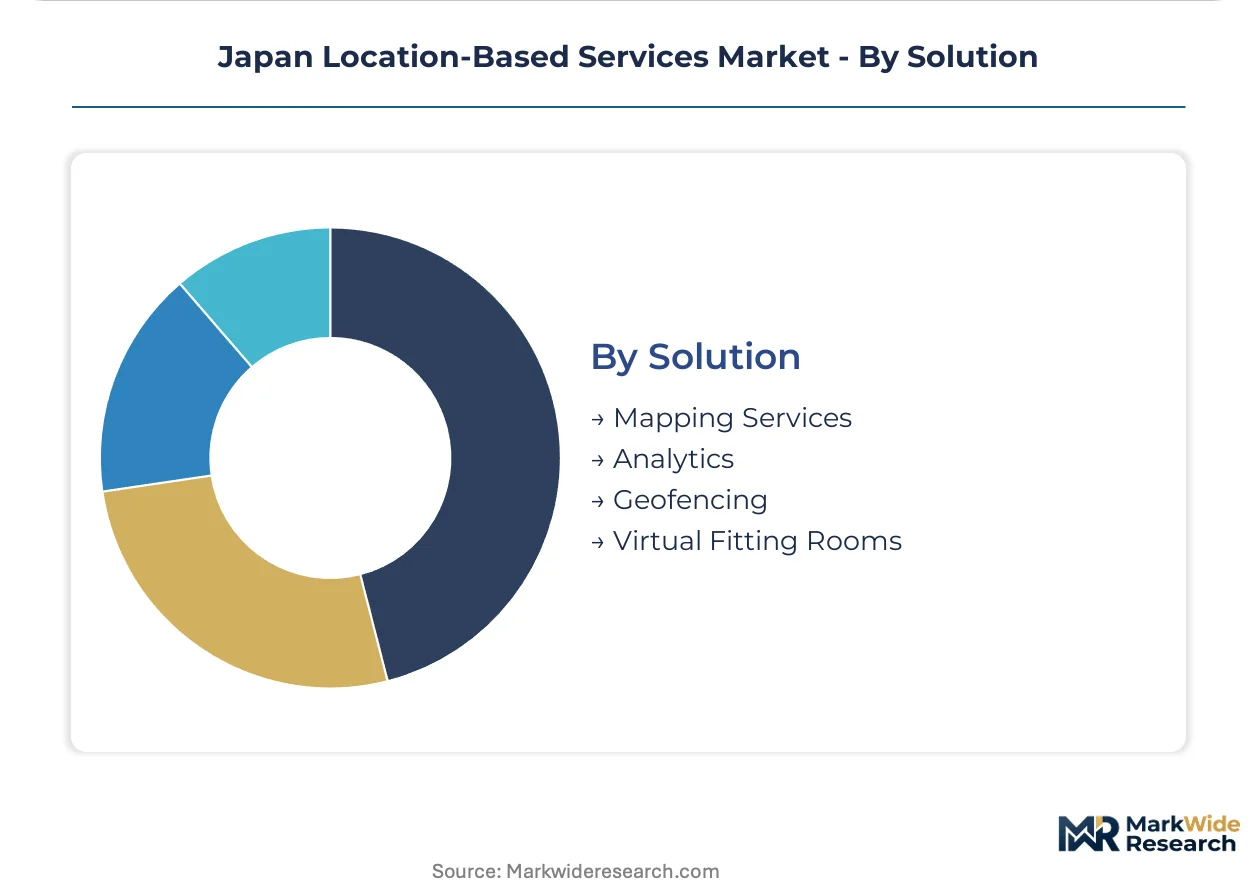
Solution:
Maturity gradients separate established utility services from emerging experiential platforms.
- Mapping Services:Basemap data layers and routing engines underpin navigation applications and enterprise logistics platforms with quarterly update cycles for road network changes.
- Analytics:Spatial intelligence dashboards aggregating movement patterns, dwell-time distributions, and zone transition frequencies for retail and urban planning decisions.
- Geofencing:Virtual perimeter triggers for automated alerts, access control, and workflow initiation when tracked assets cross defined boundaries.
- Virtual Fitting Rooms:AR-enabled apparel visualization combining body scanning, spatial positioning, and real-time rendering for e-commerce integration.
Mapping services anchor infrastructure investment while virtual fitting rooms climb the fastest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors Japan's location-based services governance through Industry 4.0 mandates and data protection frameworks that shape deployment patterns across the archipelago's industrial geography.
Kanto/Tokyo
Retail chains in Ginza and Shibuya deploy Bluetooth beacon networks for footfall analytics under revised Act on the Protection of Personal Information consent protocols. METI's precision manufacturing directives drive RTK-GPS adoption for automated guided vehicles in the Keihin industrial zone linking Tokyo and Yokohama.
Kansai/Osaka
Department store operators in Shinsaibashi implement proximity marketing with explicit value-exchange consent interfaces. The Osaka-Kobe logistics corridor generates sustained demand for fleet management solutions as freight volume concentrates along this western industrial belt.
Chubu/Nagoya
Automotive tier-one suppliers pilot ultra-wideband positioning for assembly-line tool tracking at sub-30-centimeter accuracy. Toyota-supplier ecosystems in Aichi prefecture integrate location services with robotic process automation under METI's smart factory certification schemes.
Hokkaido
Cold-chain operators deploy cellular-anchored trackers for agricultural product integrity verification across sparse logistics infrastructure. Underpenetration in northern prefectures creates greenfield potential for precision agriculture positioning as METI extends Industry 4.0 incentives to primary sectors.
Kyushu
Semiconductor packaging facilities in Kumamoto and Kagoshima leverage indoor positioning for cleanroom asset tracking. JIS standards harmonization efforts in this manufacturing outpost reduce vendor lock-in for mid-size producers integrating spatial analytics with existing MES systems.
Japan Location-Based Services Market Competitive Landscape
Capability concentration sits with telecommunications-anchored platform providers; scale advantage sits with global mapping and consumer navigation specialists. The vendor base organizes around three strategic archetypes: infrastructure-heavy system integrators serving public-sector demand, cloud-native IoT platforms monetizing 5G network densification, and global technology conglomerates leveraging proprietary mapping corpora. Competitive dynamics center on vertical integration into positioning hardware and strategic partnerships with automotive and retail verticals.
Within the telecommunications-platform tier, SoftBank Group Corp. and Rakuten, Inc. exemplify network-anchored competitive positioning. Google LLC occupies a position as the global mapping archetype, while Kokusai Kogyo Co., Ltd. represents the domestic surveying specialist anchored in public-sector infrastructure planning. These three entities collectively illustrate the capability-scale tension shaping procurement decisions across Japanese enterprise and consumer segments.
| Leading Market Players |
|---|
| Google LLC |
| Kokusai Kogyo Co., Ltd. |
| Hitachi, Ltd. |
| Waveon Co., Ltd. |
| AGOOP Corp. |
| SoftBank Group Corp. |
| Rakuten, Inc. |
| HERE Global B.V. |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwanese foundry capacity for positioning chipsets and Bluetooth SoCs directly shapes pricing power across Japanese system integrators, with supply tightness in Hsinchu Science Park feeding through to hardware margin compression for domestic vendors serving METI's Industry 4.0 mandates.
Pricing Analysis
Price spreads between meter-grade cellular modules and centimeter-grade RTK-GPS receivers span an order of magnitude, with premium tiers commanding hardware premiums for QZSS augmentation and surveyor certification. Three-tier pricing structure across premium, standard, and economy levels separates certified geodetic systems from uncertified consumer modules. Cost compression in mid-tier Bluetooth beacon networks is intensifying because annual firmware refresh cycles and battery replacement schedules erode lifetime value. Mid-size logistics operators in the Keihin industrial zone exhibit highest price sensitivity, favoring month-to-month SaaS contracts over capital-intensive ownership models.
Supply Chain Analysis
Tariff exposure between Taiwan and Japan dominates supply chain risk planning for positioning hardware, with foundry concentration in Hsinchu and Tainan creating single-source vulnerability for RTK-GPS chipsets. Component sourcing draws from Taiwan for semiconductor fabrication, South Korea for memory modules, and domestic Aichi prefecture for automotive-grade assembly. Logistics chokepoints at Yokohama and Kobe ports compound lead time volatility for just-in-time manufacturing deployments. Distribution runs through telecommunications-anchored IoT platforms and specialized system integrators serving public-sector infrastructure planning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's location-based services market sits in early-cycle expansion as METI's precision agriculture incentives extend Industry 4.0 adoption beyond manufacturing into primary sectors, creating fresh penetration opportunities across Hokkaido's underdeveloped cold-chain infrastructure.
For Market Incumbents: Entrench positioning through backward integration into QZSS-augmented receiver production and captive supply of RTK-GPS calibration services, countering emerging cloud-native IoT platforms that threaten hardware-centric margins. Deepen certification pipelines for geodetic engineers to preempt skill scarcity bottlenecks that could stall METI's construction automation timelines. Prioritize API standardization partnerships with legacy warehouse management system vendors to compress implementation cycles for unified fleet-visibility platforms. For New Entrants and Emerging Players: Pursue white-space deployment in Hokkaido and Tohoku agricultural machinery positioning, where sparse logistics infrastructure and METI's extended incentives create penetrable greenfield conditions. Target virtual fitting room convergence in Ginza and Shinsaibashi department stores, where AR-enabled spatial computing commands premium service tiers. Anchor go-to-market through explicit value-exchange consent interfaces that trade location permissions for personalized promotional access under revised Act on the Protection of Personal Information protocols. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because 5G network densification and digital twin virtualization compress the gap between geospatial data collection and actionable spatial intelligence across manufacturing and retail operations. Acquisition focus should center on modular SaaS platforms with usage-based tiering capability, displacing traditional system integrators in mid-size logistics procurement. Watch SoftBank's base station deployment cadence as the signal for meter-grade cellular positioning addressable market expansion beyond GPS-dependent outdoor applications.| Strategic Initiative | Industry Significance |
|---|---|
| QZSS Augmentation Integration | Centimeter-grade accuracy for automated guided vehicles in Aichi and Shizuoka manufacturing zones meets METI certification requirements. |
| Bluetooth Beacon Network Deployment | Sub-meter proximity detection powers footfall analytics in Ginza and Shinsaibashi retail locations under tightened consent frameworks. |
| Cloud-Native Platform Migration | Month-to-month SaaS contracts align with Keihin logistics operators' preference shift away from hardware ownership models. |
| Geodetic Engineer Certification Pipeline | Training capacity expansion addresses RTK-GPS skill scarcity constraining precision agriculture and construction automation timelines. |
| Ultra-Wideband Indoor Positioning | Sub-30-centimeter accuracy for assembly-line tool tracking in Nagoya automotive tier-one supplier ecosystems eliminates Wi-Fi infrastructure density constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with IoT platform engineers, telecommunications network planners, retail operations directors, logistics fleet managers, and METI policy officers, cross-referenced against secondary sources including METI Industry 4.0 white papers, JIS standards documentation, Act on the Protection of Personal Information regulatory filings, and hyperscaler capex disclosures for 5G densification programs. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Calibration anchored quantitative outputs to observed procurement patterns across the projection horizon, modeling technology adoption curves for GPS, Bluetooth, Wi-Fi, and ultra-wideband segments alongside application splits in navigation, asset tracking, fleet management, and location-based advertising. CAGRs derived from elasticity-adjusted penetration rates against industrial automation deployment schedules. Forecast inputs incorporated QZSS constellation expansion timelines and METI smart factory certification scheme uptake curves.
Macroeconomic conditions sit as an overlay; deviation in yen-denominated hardware import costs or semiconductor foundry utilization rates would shift the trajectory. Forecasts reflect documented assumptions around 5G network densification pace and JIS harmonization adoption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Location Based Advertising Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
France Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market