
 Russia Geospatial Analytics Market | 2026-2036
Russia Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Geospatial Analytics Market Insights
Open-source geospatial data formats are restructuring procurement economics across Russian government accounts. ScanEx sustains its position through captive ground-station infrastructure for domestic satellite reception. NextGIS leverages its open-source platform to compete for public-sector contracts requiring code transparency. Data East, LLC anchors its business in specialized cartographic production for regional administrations.
Geospatial analytics encompasses the computational processing of location-referenced data through remote sensing, geographic information systems, and spatial statistics to generate actionable intelligence for resource management, infrastructure planning, and situational awareness. The technology requires multi-spectral sensor calibration, orthorectification pipelines, and vector-raster fusion at sub-meter resolution. Software solutions dominate current revenue as agencies prioritize subscription-based GIS platforms over perpetual licenses. Cloud-based deployment is gaining traction fastest among municipal customers seeking to bypass capital-intensive server procurement. Services and consulting retain superior margins where vendors integrate proprietary terrain models with client-specific workflow automation.
Roscosmos licensing requirements and Federal Agency of Air Transport certification standards govern satellite data distribution and precision navigation product quality. The national geospatial data framework mandates interoperability protocols that shape vendor technical roadmaps. Domestic content quotas under Russia's import-substitution program restrict foreign platform participation in sensitive procurement categories. Stakeholders must monitor evolving encryption standards for spatial data transmission and assess whether domestic cloud infrastructure can satisfy latency requirements for real-time analytics workloads.
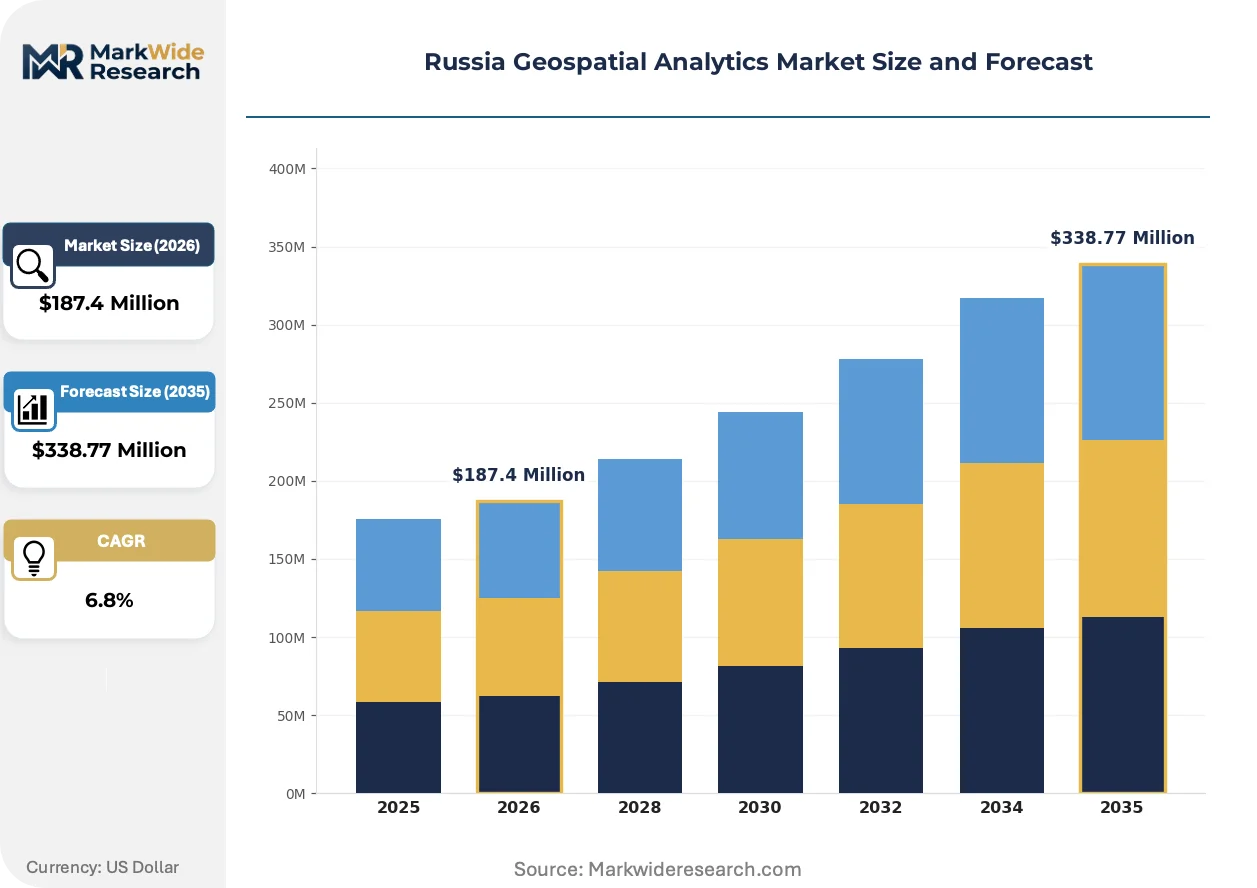
Market Dynamics
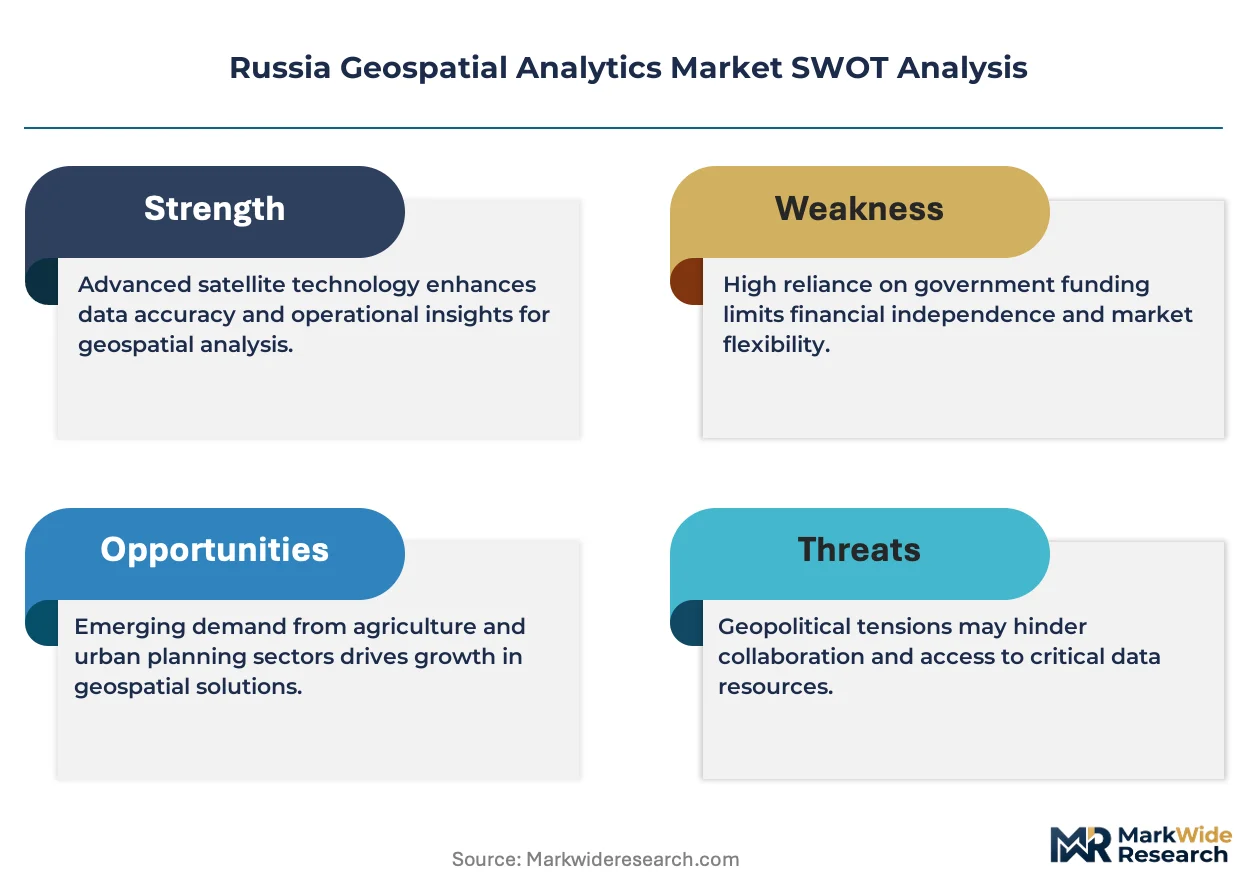
Russia's import-substitution mandates for geospatial software are redirecting procurement toward domestic developers, compressing foreign platform participation while elevating local vendors with captive ground-station infrastructure and code-transparent architectures.
Growth Catalysts
- Roscosmos licensing requirements:Federal mandates for domestic satellite data distribution accelerate procurement of indigenous analytics platforms across defense and intelligence agencies.
- Cloud-based deployment models:Municipal customers adopt subscription GIS platforms to bypass capital-intensive server procurement, expanding addressable markets for software vendors.
- Moscow aerospace cluster concentration:Proximity to specialized engineering talent and Roscosmos facilities concentrates R&D investment and accelerates platform development cycles.
Market Restraints
- Multi-spectral sensor calibration costs:Precision agriculture and defense applications require expensive sub-meter orthorectification pipelines that constrain mid-tier vendor participation.
- Domestic cloud infrastructure latency:Real-time analytics workloads face performance limitations where edge computing nodes remain underdeveloped outside Moscow and St. Petersburg.
- Encryption standard fragmentation:Evolving Federal Security Service requirements for spatial data transmission create compliance overhead and extend procurement timelines.
Strategic Opportunities
- Siberian resource extraction corridors:Underpenetrated mining and pipeline monitoring applications in Krasnoyarsk and Irkutsk regions present first-mover expansion potential for terrain-integrated analytics.
- Open-source platform convergence:Combination of NextGIS transparency protocols with ScanEx ground-station networks enables hybrid offerings for security-conscious public-sector buyers.
- Regional administration digitization:Cartographic production mandates from federal to oblast-level governments create recurring service contracts for specialized workflow automation.
Industry Challenges
- Vector-raster fusion expertise scarcity:Shortage of specialists capable of integrating multi-source geospatial data streams limits vendor execution speed for complex defense contracts.
- Federal Agency of Air Transport certification timelines:Extended precision navigation product approval processes delay revenue recognition for navigation analytics developers.
- Legacy GIS system interoperability:Soviet-era cartographic databases require costly migration protocols that erode margins on municipal modernization projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Geospatial Analytics Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Consulting Deployment: On-premises, Cloud-based, Hybrid, Managed Service End User: Government, Urban Planning, Environmental Agencies, Transportation Technology: Remote Sensing, GIS, GPS, Spatial Data Analysis |
| Companies Covered | EAST VIEW GEOSPATIAL, INC., GISware Integro, Geospatial Agency Innoter, Data East, LLC, NextGIS, 2GIS, AlterGeo, Navigine, ScanEx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Geospatial Analytics Market Trends and Innovations
Computational pipelines for geospatial intelligence are converging around open-source architectures and cloud-native deployment, restructuring how Russian agencies balance data sovereignty against analytical sophistication.
AI-driven feature extraction from satellite imagery is unifying previously separate remote sensing and GIS workflows into single-platform offerings. Defense contractors and resource ministries adopt these integrated systems fastest, consolidating vendor relationships and compressing procurement cycles for standalone photogrammetry tools.
Roscosmos licensing requirements now mandate domestic ground-station reception for classified imagery, reshaping data supply chains. Foreign satellite operators face exclusion from sensitive procurement categories, while ScanEx and comparable vendors expand captive infrastructure to capture redirected demand.
Municipal procurement teams now favor subscription-based SaaS platforms over perpetual software licenses. This preference shift displaces traditional GIS resellers and redirects margin capture toward developers with native cloud architectures, with St. Petersburg and Yekaterinburg municipalities leading adoption curves.
Russia Geospatial Analytics Market Segmentation
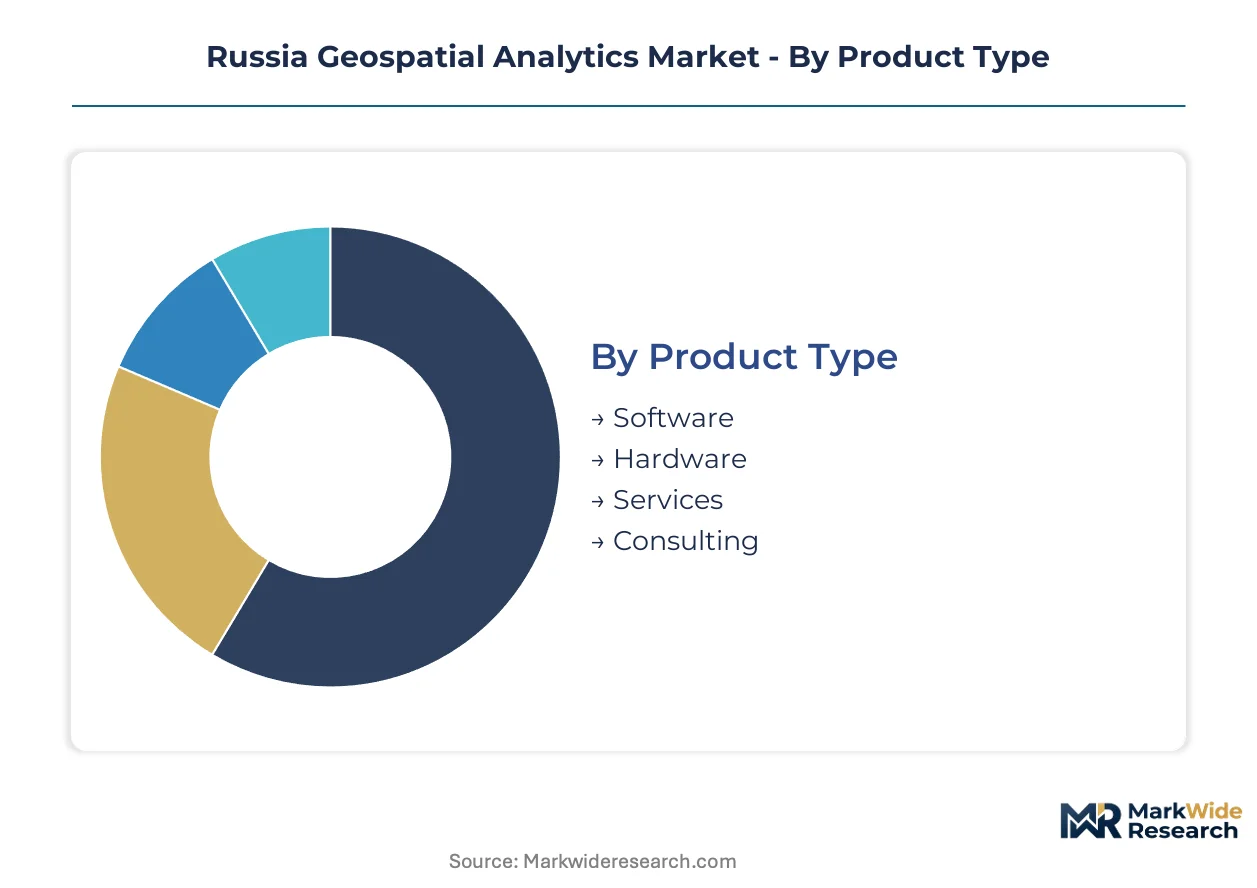
Russia's geospatial analytics market fragments along procurement sophistication lines, with defense and municipal buyers demanding divergent technical specifications and contractual structures. Understanding these segment boundaries clarifies where domestic vendors can command premium positioning versus competing on cost.
Product Type:
Standardized subscription offerings dominate high-volume municipal procurement, while defense contracts demand heavily customized perpetual deployments with source-code escrow provisions.
- Software:Subscription-based GIS platforms with native cloud architectures capture recurring revenue from municipal customers seeking to bypass capital-intensive server procurement. Moscow and St. Petersburg municipalities prioritize these solutions for cadastral management and infrastructure planning workflows.
- Services:Integration of proprietary terrain models with client-specific workflow automation commands superior margins where vector-raster fusion expertise remains scarce. Defense ministries and resource extraction conglomerates in Krasnoyarsk drive demand for these high-touch engagements.
- Hardware:Multi-spectral sensor calibration equipment and orthorectification pipelines serve precision agriculture and defense applications requiring sub-meter resolution.
- Consulting:Specialized cartographic production mandates from federal to oblast-level governments create recurring contracts for legacy system migration and interoperability protocols.
Leading the category by volume: Software. Expanding most quickly: Services.
Deployment:
Latency requirements and data sovereignty concerns split procurement patterns between real-time analytics workloads and archival processing needs.
- Cloud-based:Municipal customers adopt subscription GIS platforms to eliminate upfront capital expenditure, with Yekaterinburg and St. Petersburg leading adoption curves among regional governments.
- On-premises:Federal Security Service encryption requirements for classified spatial data transmission mandate air-gapped installations across defense and intelligence agency facilities.
- Hybrid:Resource ministries balance sensitive subsurface data on local infrastructure with public-facing distribution through domestic cloud nodes.
- Managed Service:Regional administrations lacking specialized IT staff outsource entire geospatial operations to vendors with captive ground-station infrastructure.
Fastest-growing trajectory: Cloud-based. Highest-margin deployments: On-premises.
End User:
Budget scale and technical sophistication separate federal procurement teams from oblast-level administrators with constrained implementation resources.
- Government:Roscosmos licensing requirements and import-substitution mandates redirect defense and intelligence procurement toward domestic analytics platforms with code-transparent architectures.
- Environmental Agencies:Climate monitoring and natural resource compliance drive multi-spectral imagery consumption for tundra degradation and permafrost tracking across Siberian territories.
- Urban Planning:Cadastral modernization and zoning automation concentrate demand in Moscow's aerospace cluster where specialized engineering talent accelerates platform development cycles.
- Transportation:Pipeline monitoring and precision navigation product certification under Federal Agency of Air Transport standards shape vendor technical roadmaps for logistics applications.
Concentrating procurement spend: Government. Steepest expansion trajectory: Environmental Agencies.
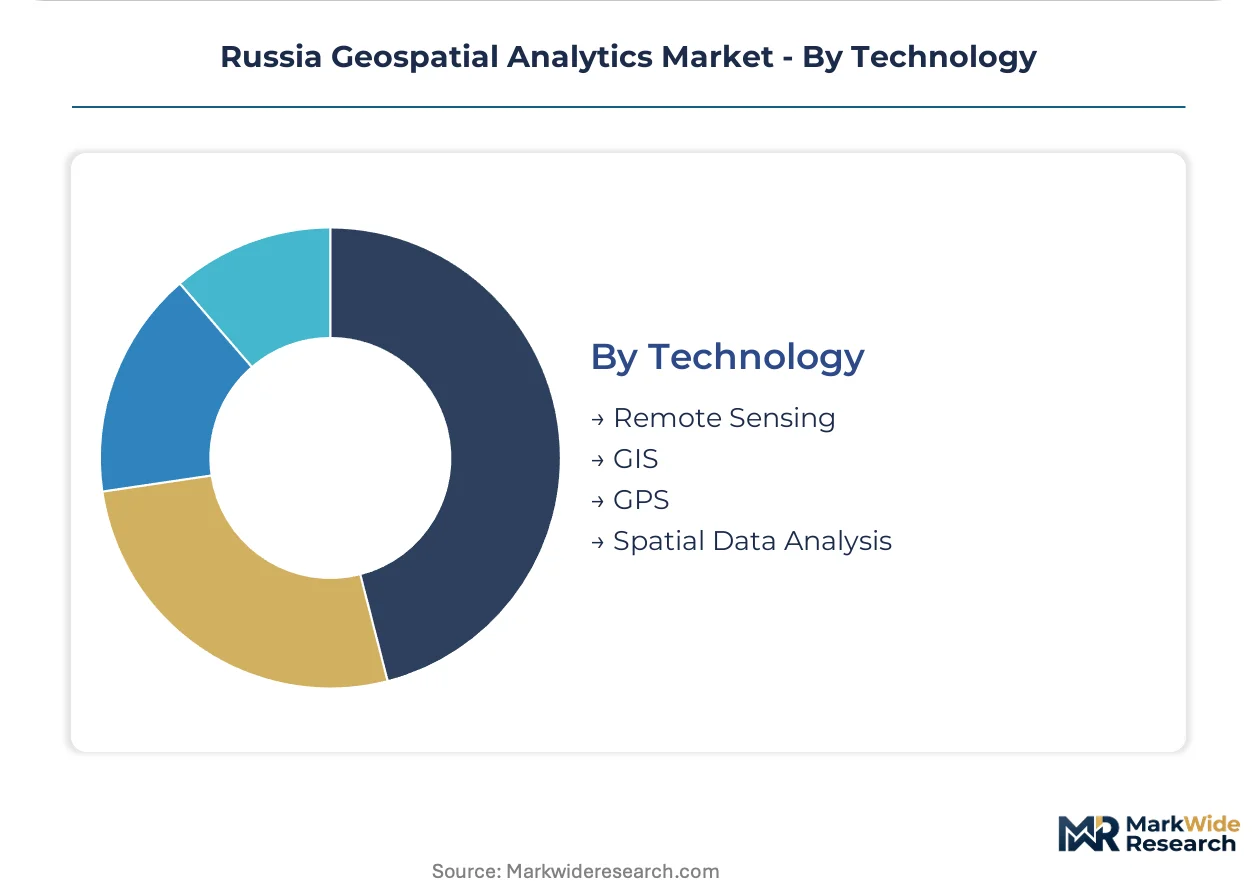
Technology:
Sensor fusion capabilities differentiate vendors capable of unified remote sensing-GIS workflows from point-solution providers facing consolidation pressure.
- Remote Sensing:AI-driven feature extraction from satellite imagery unifies previously separate photogrammetry and analytics workflows into single-platform offerings that defense contractors adopt fastest.
- GIS:Vector-raster fusion at sub-meter resolution underpins municipal cadastral systems and regional administration digitization mandates across Russian federal subjects.
- GPS:Precision navigation products require Federal Agency of Air Transport certification that extends approval timelines and delays revenue recognition for navigation analytics developers.
- Spatial Data Analysis:Computational processing of location-referenced data through spatial statistics generates actionable intelligence for resource management and situational awareness applications.
Dominating current revenue: GIS. Gaining share fastest: Remote Sensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration in Moscow's aerospace cluster drives disproportionate investment allocation, while Siberian resource corridors and regional administration digitization mandates expand addressable markets beyond the capital.
Central Federal District
Roscosmos licensing requirements and Federal Security Service encryption standards concentrate platform development in Moscow's specialized engineering ecosystem. The national geospatial data framework mandates interoperability protocols that shape vendor technical roadmaps. Moscow's aerospace cluster accelerates R&D cycles through proximity to satellite reception infrastructure and classified procurement channels.
Siberian Federal District
Underpenetrated mining and pipeline monitoring applications in Krasnoyarsk and Irkutsk regions present expansion potential for terrain-integrated analytics. Permafrost tracking and tundra degradation monitoring drive multi-spectral imagery consumption across vast territorial administrations. Krasnoyarsk-based resource extraction conglomerates demand high-touch service engagements integrating proprietary subsurface models.
Northwestern Federal District
St. Petersburg municipalities lead cloud-based GIS adoption curves among regional governments seeking subscription platforms over capital-intensive server procurement. The city's specialized IT talent pool supports managed service offerings for administrations lacking in-house geospatial operations. Federal Agency of Air Transport certification timelines for precision navigation products delay revenue recognition for local developers.
Ural Federal District
Yekaterinburg's industrial base generates demand for cadastral modernization and zoning automation workflows. Regional administration digitization mandates from federal to oblast-level governments create recurring service contracts. The city's engineering heritage supports mid-tier vendors competing on cost for municipal modernization projects.
Far Eastern Federal District
Border monitoring and maritime surveillance applications drive specialized procurement across vast coastal territories. Limited domestic cloud infrastructure latency constrains real-time analytics workloads outside major urban centers. Sakha Republic's resource extraction operations require customized terrain-integrated analytics for remote site management.
Russia Geospatial Analytics Market Competitive Landscape
Import-substitution mandates dominate the current landscape, compressing foreign platform participation while elevating domestic vendors with captive infrastructure. The vendor base stratifies between ground-station operators with satellite reception assets and open-source platform developers competing on code transparency. Three archetypes prevail: aerospace-heritage integrators with Roscosmos relationships, municipal-focused SaaS providers, and specialized cartographic houses serving regional administrations. M&A activity remains subdued given state ownership patterns, while strategic partnerships between ground-station operators and software developers accelerate hybrid offering development.
Within the ground-station infrastructure tier, ScanEx anchors its position through captive satellite reception capabilities that satisfy Roscosmos licensing requirements for classified imagery distribution. NextGIS occupies a distinctive niche leveraging open-source transparency protocols to compete for security-conscious public-sector contracts. Data East, LLC exemplifies the specialized cartographic archetype, anchoring its business in recurring production mandates from federal to oblast-level regional administrations. These three entities collectively represent the competitive repositioning under way as procurement redirects toward domestic developers.
| Leading Market Players |
|---|
| EAST VIEW GEOSPATIAL, INC. |
| GISware Integro |
| Geospatial Agency Innoter |
| Data East, LLC |
| NextGIS |
| 2GIS |
| AlterGeo |
| Navigine |
| ScanEx |
| Others |
Pricing and Supply Chain Analysis
Roscosmos licensing requirements for domestic satellite data distribution gate qualified supply access and premium-tier pricing power, compressing foreign platform participation while elevating vendors with captive ground-station infrastructure and Federal Security Service certification.
Pricing Analysis
Volume-municipal procurement concentrates in subscription SaaS tiers with compressed margins, while defense contracts sustain premium pricing through source-code escrow and perpetual licensing. Price differentiation hinges on Federal Security Service encryption certification and Roscosmos domestic content quotas, with certified vendors commanding substantial premiums. Cost compression in municipal tiers intensifies as regional administrations consolidate procurement around standardized platforms. Government buyers exhibit lowest price sensitivity due to mandate-driven procurement timelines, whereas resource extraction conglomerates in Krasnoyarsk negotiate aggressively on terrain-model customization.
Supply Chain Analysis
Direct-to-agency channels handle classified imagery demand, while managed service providers serve municipal buyers lacking in-house geospatial operations. Geographic supply concentrates in Russia, with limited sensor calibration equipment sourced from Germany and precision optics from Japan. Raw material dependencies include multi-spectral sensor arrays, orthorectification processing hardware, and specialized encryption modules. Single-source vulnerability around domestic cloud infrastructure latency constrains real-time analytics deployment outside Moscow and St. Petersburg. Distribution runs through Roscosmos-licensed ground-station operators for sensitive procurement, with commercial channels serving non-classified applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive ground-station infrastructure and open-source code transparency represent the decisive upstream and downstream levers players are consolidating.
For Market Incumbents: Extend ground-station network coverage into Krasnoyarsk and Irkutsk to preempt Siberian resource corridor demand, while deepening source-code escrow capabilities to defend against NextGIS transparency competition. Federal Agency of Air Transport certification timelines threaten revenue recognition delays for navigation analytics developers.
For New Entrants and Emerging Players: Enter via municipal SaaS platforms in Yekaterinburg and St. Petersburg where subscription preferences displace perpetual license resellers, targeting cadastral modernization workflows with native cloud architectures. White-space concentration in oblast-level cartographic production mandates offers recurring service contract potential.
For Investors and Strategic Acquirers: Roscosmos licensing requirement expansion is the leading indicator that ground-station infrastructure scarcity will intensify, signaling long-term viability for aerospace-heritage integrators with satellite reception assets. Acquisition targets should exhibit hybrid software-infrastructure capabilities bridging ScanEx-type reception with NextGIS-type transparency protocols. Vector-raster fusion expertise scarcity signals execution risk for complex defense contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Ground-Station Network Expansion | Captive infrastructure in Krasnoyarsk satisfies Roscosmos licensing for Siberian resource extraction demand. |
| Open-Source Platform Certification | Code transparency protocols unlock Federal Security Service contracts requiring auditability. |
| Cloud-Native SaaS Development | Native subscription architectures capture Yekaterinburg municipal procurement shifting from perpetual licenses. |
| AI-Driven Feature Extraction Integration | Unified remote sensing-GIS workflows consolidate defense contractor vendor relationships. |
| Regional Cartographic Service Contracts | Oblast-level digitization mandates create recurring revenue from federal-to-local workflow automation. |
Research Methodology
Document review covered Roscosmos licensing filings, Federal Security Service encryption standards, and municipal procurement databases, complemented by interviews with platform engineering directors at domestic software developers, procurement officers at regional administrations, ground-station operations managers, and defense ministry technical leads. Secondary validation drew from satellite industry trade publications, customs records for sensor equipment imports, and federal budget allocation disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical procurement patterns against expert panel input anchored the analytical framework across deployment models, end-user sophistication tiers, and technology integration complexity levels. CAGRs derived from trend extrapolation moderated by infrastructure deployment timelines and regulatory approval velocity. Industry-specific forecast inputs included Roscosmos ground-station commissioning schedules and Federal Agency of Air Transport certification pipeline data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Federal Security Service encryption standard fragmentation and domestic cloud infrastructure latency constraints. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market