
 Global Digital Maps Market | 2026-2036
Global Digital Maps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Maps Market Foresight
Modular API bundling is broadening buyer choice as platform providers unbundle core mapping engines from premium analytics overlays. Google leverages its satellite imagery corpus to anchor cloud-native geospatial services. HERE Technologies competes through embedded automotive-grade map stacks that sustain long-term OEM contracts. Esri specializes in enterprise GIS deployments that dominate government and utility sectors.
Digital maps constitute georeferenced spatial databases combining vector geometry, raster imagery, and attribute tables, rendered through coordinate reference systems with sub-meter accuracy for navigation and planning purposes. Satellite imagery and LiDAR technology segments command premium pricing due to capital-intensive sensor deployment and processing infrastructure. Crowdsourced mapping and real-time data layers represent the fastest-expanding technology categories as smartphone penetration and edge computing reduce collection costs.
The Federal Aviation Administration regulates commercial drone operations that feed aerial imagery into mapping platforms, while the European Union's CSRD mandates geospatial disclosure standards for corporate sustainability reporting. China's SAMR enforces data localization rules that restrict cross-border transfer of surveyed coordinates. Stakeholders must monitor divergent national data sovereignty frameworks when architecting multi-territory map delivery pipelines.
Market Dynamics
Autonomous vehicle manufacturers are forcing a structural upgrade in mapping fidelity requirements, compressing refresh cycles from annual to near-real-time and privileging suppliers with embedded automotive validation pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Geospatial AI systems deployed in European mobility applications now require documented training data provenance, accelerating procurement of auditable high-definition map layers from certified providers.
- LiDAR sensor cost curves:Solid-state LiDAR manufacturing scale-up is collapsing aerial survey costs, enabling municipal governments to commission centimeter-grade urban digital twins previously restricted to defense budgets.
- Edge computing diffusion:Smartphone GPU capabilities now support on-device SLAM processing, democratizing real-time map contribution from ride-hail and delivery fleets across Southeast Asian urban corridors.
Market Restraints
- Input concentration in gallium arsenide:Specialty semiconductor substrates for photonic LiDAR emitters face supply bottlenecks from Chinese export licensing, inflating sensor bill-of-materials.
- German KBA type-approval requirements:Automotive-grade map stacks require exhaustive validation against federal motor transport authority standards, extending OEM onboarding timelines by 18-24 months.
- Raster imagery substitution:Synthetic aperture radar satellites now deliver cloud-penetrating surface models that bypass optical mapping value chains in forestry and maritime surveillance segments.
Strategic Opportunities
- Indian smart city mandates:Ministry of Housing and Urban Affairs directives require 3D city models for 100 metropolitan areas, creating procurement volume absent legacy vendor relationships.
- EU CSRD geospatial disclosure:Corporate sustainability reporting standards mandate supply chain emissions mapping, opening enterprise subscriptions for carbon-accounting-integrated location platforms.
- V2X-edge convergence:Vehicle-to-everything communication protocols are merging with roadside LiDAR infrastructure, enabling cooperative perception maps that reduce per-vehicle sensor burdens.
Industry Challenges
- Geodetic surveyor scarcity:Professional licensure pathways for cadastral-grade coordinate certification face 5-year training pipelines, constraining quality assurance capacity for precision agriculture deployments.
- Legacy fleet integration:Container shipping operators require map engines compatible with 15-year-old bridge ECDIS hardware, fragmenting R&D across incompatible rendering pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Maps Market |
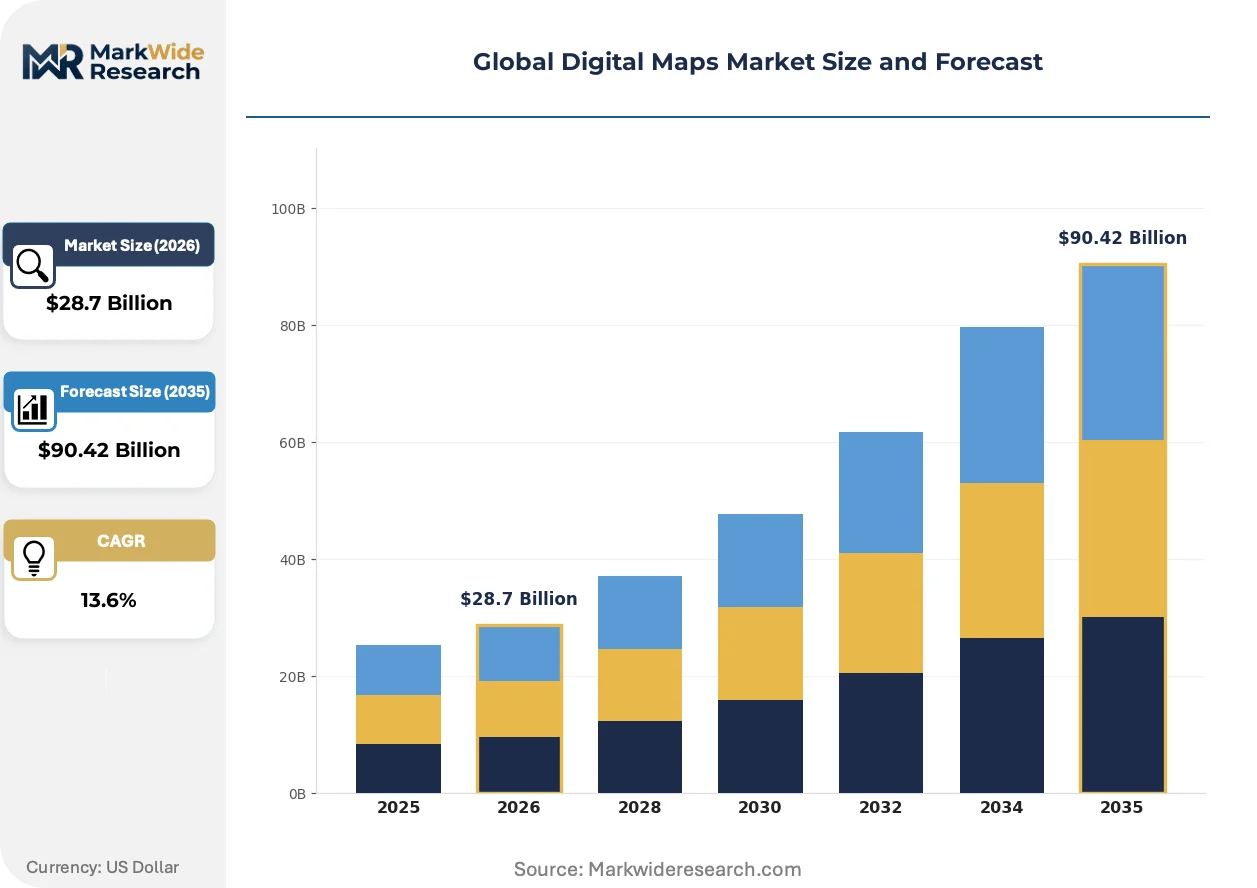
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $90.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Navigation, Urban Planning, Fleet Management, Location-Based Services, Disaster Management Technology: Satellite Imagery, LiDAR, Crowdsourced Mapping, GIS, Real-Time Data End User: Transportation Companies, Government Agencies, Telecommunication Providers, E-Commerce Platforms Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Apps, Web Applications |
| Companies Covered | Apple Inc., Mapbox Inc., Google, Maxar Technologies, Baidu Inc., HERE Technologies, Esri, INRIX Inc., TomTom International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Maps Market Shifts & Advancements
Neural radiance fields and generative scene reconstruction are collapsing the cost structure of 3D environment capture, displacing photogrammetry workflows that dominated the past decade.
Neural radiance field (NeRF) algorithms encode continuous 3D scenes from sparse 2D imagery, reducing survey flight density requirements by 60-80%. Autonomous vehicle perception teams at German and Japanese OEMs are converging with this approach, integrating NeRF-derived synthetic training data to accelerate rare-event simulation. The structural consequence is compression of traditional photogrammetry service margins as software substitution displaces aerial acquisition hours.
The European Union's CSRD mandates geospatial traceability for Scope 3 emissions disclosures, forcing multinational manufacturers to license location-intelligence platforms for supplier mapping. Industrial consequence includes mandatory procurement of carbon-accounting-integrated map stacks by 2027 reporting deadlines. German automotive and French luxury goods conglomerates are most affected, accelerating vendor consolidation around platforms with pre-built emissions factor databases.
Fleet operators are unbundling map subscriptions from telematics hardware contracts, shifting toward API-based consumption priced by query volume. This procurement model change disrupts traditional three-year bundled agreements and privileges cloud-native providers with metered pricing infrastructure. The shift is most visible in North American long-haul trucking, where large fleet managers now maintain multi-provider map stacks to optimize routing cost against real-time traffic accuracy.
Global Digital Maps Market Segmentation
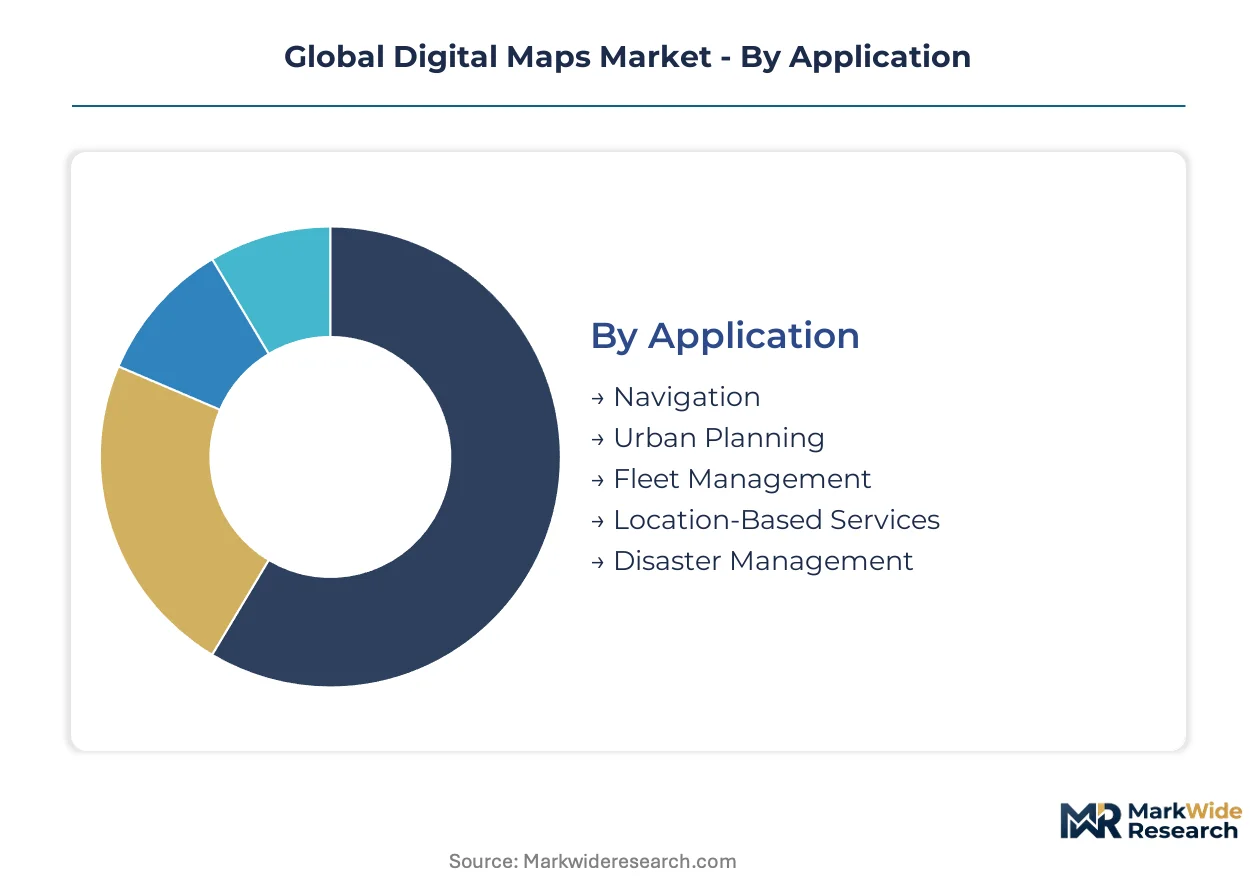
Digital maps serve divergent operational requirements across mobility, governance, and commerce. Segmentation reveals how procurement criteria shift from sub-meter accuracy mandates in autonomous navigation to cost-optimized coverage for consumer applications.
Application:
Fleet operators and municipal buyers prioritize refresh frequency and API reliability over base map aesthetics when selecting providers.
- Navigation:Turn-by-turn routing engines consume vector tilesets with real-time traffic fusion. German automotive OEMs and Japanese Tier-1 suppliers anchor procurement of high-definition layers validated against KBA type-approval protocols.
- Urban Planning:3D city models integrate zoning overlays, utility networks, and demographic raster data. Indian Ministry of Housing and Urban Affairs mandates for 100 metropolitan areas are accelerating procurement of centimeter-grade digital twins.
- Fleet Management:Route optimization platforms consume historical speed profiles and geofenced depot coordinates. North American long-haul trucking operators unbundle map subscriptions from telematics hardware contracts.
- Location-Based Services:Proximity targeting for retail and food delivery depends on point-of-interest accuracy and geocoding precision. Southeast Asian ride-hail platforms drive crowdsourced map contribution through driver smartphone fleets.
- Disaster Management:Rapid damage assessment requires pre-event baseline imagery and post-event change detection. FEMA and analogous civil protection agencies in Japan and Australia maintain priority access contracts with satellite operators.
Navigation leads on scale; Location-Based Services leads on momentum.
Technology:
Capital intensity and collection economics determine whether buyers license proprietary archives or commission custom acquisition.
- Satellite Imagery:Optical and synthetic aperture radar constellations provide global coverage with 24-72 hour revisit cycles. Cloud-penetrating SAR capabilities from European and Canadian operators are displacing optical value chains in forestry and maritime surveillance.
- LiDAR:Solid-state photonic emitters mounted on aerial platforms and vehicle roofs capture centimeter-grade elevation models. Chinese export licensing restrictions on gallium arsenide substrates are inflating sensor bill-of-materials.
- Crowdsourced Mapping:Smartphone GPS traces and user-submitted corrections populate base layers at marginal collection cost. OpenStreetMap foundation and commercial derivative platforms dominate where proprietary coverage gaps persist.
- GIS:Enterprise geospatial information systems layer vector geometry with attribute databases for planning workflows. Esri deployments anchor government and utility sector procurement in the United States and Western Europe.
- Real-Time Data:Probe vehicle feeds and connected infrastructure streams enable dynamic map updates with sub-minute latency. Vehicle-to-everything protocol standardization in Germany and South Korea is enabling cooperative perception architectures.
Satellite Imagery dominates procurement budgets; Real-Time Data is expanding most quickly.
End User:
Compliance requirements and integration legacy shape vendor selection across buyer categories.
- Transportation Companies:Container shipping operators require ECDIS-compatible chart formats for 15-year-old bridge hardware. Automotive manufacturers validate map stacks through exhaustive federal motor transport authority pipelines.
- Government Agencies:Cadastral authorities maintain official coordinate reference systems for property registration and taxation. Professional geodetic surveyor scarcity constrains quality assurance capacity for precision agriculture program rollout.
- Telecommunication Providers:Network planning teams model radio propagation using terrain elevation and building footprint data. 5G small cell densification in urban India and Brazil requires sub-meter accuracy for line-of-sight verification.
- E-Commerce Platforms:Last-mile routing optimization depends on address geocoding accuracy and real-time traffic integration. API-based consumption priced by query volume is displacing bundled three-year agreements.
Transportation Companies commit the largest contract values; E-Commerce Platforms are gaining share fastest.
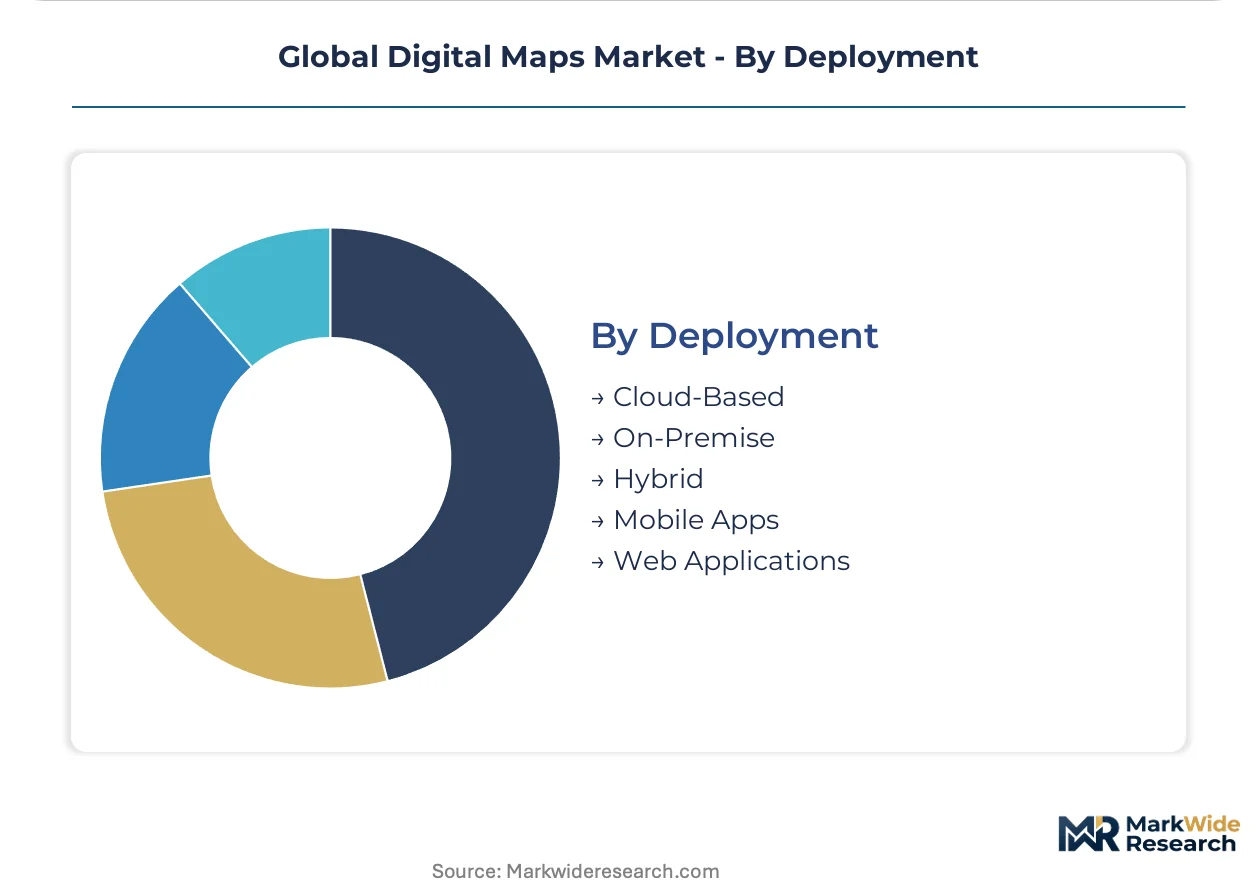
Deployment:
Data sovereignty requirements and latency sensitivity determine architecture choice between centralized and edge-distributed models.
- Cloud-Based:Scalable tile serving and analytics processing leverage hyperscaler infrastructure. China's SAMR data localization rules restrict cross-border transfer of surveyed coordinates for foreign-hosted platforms.
- On-Premise:Air-gapped installations serve defense and intelligence community requirements with classified map layers. German automotive development centers maintain local high-definition map servers for prototype vehicle testing.
- Hybrid:Sensitive base layers reside on-premise while dynamic overlays stream from cloud endpoints. EU GDPR and AI Act compliance documentation favors auditable data provenance chains.
- Mobile Apps:On-device rendering with offline tile caching supports navigation in connectivity-deprived environments. Smartphone GPU capabilities now support SLAM processing for real-time map contribution.
- Web Applications:Browser-based visualization democratizes access for casual users and occasional-use enterprise workflows. Metered API pricing aligns cost with actual query consumption patterns.
Cloud-Based deployments hold the majority position; Hybrid architectures show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital mapping technology achieved commercial scale through early automotive navigation deployments in Germany and Japan, later diffusing through North American consumer platforms and Asia-Pacific smart city programs. Geographic demand patterns now reflect divergent regulatory regimes for geospatial data sovereignty and autonomous vehicle validation standards.
United States
The Federal Aviation Administration governs commercial drone operations feeding aerial imagery into mapping platforms, while the Department of Transportation coordinates V2X infrastructure deployment. Silicon Valley cloud providers anchor enterprise geospatial services, and Detroit-area automotive development centers maintain local high-definition map servers for prototype testing under NHTSA guidelines.
Germany
The Kraftfahrt-Bundesamt enforces exhaustive type-approval protocols for automotive-grade map stacks, extending OEM onboarding timelines by 18-24 months. Stuttgart and Munich host development centers where Tier-1 suppliers validate embedded navigation systems. The EU AI Act compliance mandates accelerate procurement of auditable high-definition layers from certified providers.
China
The State Administration for Market Regulation enforces data localization rules restricting cross-border transfer of surveyed coordinates. Beijing and Shanghai concentrate domestic platform development for smart city and autonomous vehicle applications. SAMR licensing requirements favor state-affiliated entities for precision surveying contracts.
India
The Ministry of Housing and Urban Affairs mandates 3D city models for 100 metropolitan areas, creating procurement volume absent legacy vendor relationships. Bengaluru and Hyderabad anchor domestic geospatial technology development. The Survey of India maintains official coordinate reference systems while opening cadastral data to commercial platforms.
Japan
METI coordinates V2X protocol standardization enabling cooperative perception architectures with roadside LiDAR infrastructure. Nagoya and Tokyo host OEM development centers integrating real-time map updates into advanced driver assistance systems. Domestic suppliers dominate government procurement for disaster management and precision agriculture applications.
Global Digital Maps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data provenance certification and refresh frequency dimensions. The vendor base organizes into three tiers: hyperscale cloud platforms with satellite imagery archives, automotive-grade specialists with embedded validation pipelines, and enterprise GIS incumbents with government relationships. Consolidation pressures concentrate among mid-tier photogrammetry services facing software substitution. Dominant competitive moves include API unbundling from hardware contracts and vertical integration into sensor manufacturing.
Within the automotive-grade tier, HERE Technologies and TomTom International BV occupy positions defined by long-term OEM validation relationships. Google exemplifies the hyperscale cloud archetype through satellite imagery corpus leverage. Esri anchors enterprise GIS deployments across government and utility sectors in Western markets. These three patterns represent the structural alternatives available to procurement buyers.
| Leading Market Players |
|---|
| Apple Inc. |
| Mapbox Inc. |
| Maxar Technologies |
| Baidu Inc. |
| HERE Technologies |
| Esri |
| INRIX Inc. |
| TomTom International BV |
| Others |
Supply & Pricing Matrix
Gallium arsenide substrate pricing volatility cascades through LiDAR sensor manufacturing into three distinct map-data tiers. Automotive OEMs absorbing certified high-definition layers face cost pass-through from photonic emitter supply constraints, while municipal governments commissioning urban digital twins encounter compressed aerial survey quotes from solid-state manufacturing scale-up.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes procurement decisions by certification grade and refresh frequency. Premium tiers anchor on KBA-validated automotive stacks and CSRD-compliant emissions-traceable layers, commanding sustained margins from compliance-locked buyers. Standard tiers serve fleet operators through API-metered consumption displacing bundled hardware contracts. Economy tiers fragment across crowdsourced base layers where OpenStreetMap derivatives compete on marginal collection cost. Price differentiation centers on validation pipeline depth: German automotive procurement tolerates 18-24 month onboarding timelines for certified provenance, while Southeast Asian ride-hail platforms prioritize query-volume economics over accuracy guarantees. Pricing pressure stems from neural radiance field substitution collapsing photogrammetry service margins by 60-80%.
Supply Chain Analysis
Geodetic surveyor scarcity across Germany, Japan, and the United States constrains quality assurance capacity for cadastral-grade certification pipelines. Solid-state LiDAR manufacturing concentrates in Chinese and Taiwanese facilities, drawing from gallium arsenide substrate suppliers subject to export licensing restrictions. Optical sensor assembly rests on precision optic fabrication in German and Japanese precision engineering clusters. Supply chain risk manifests through single-source vulnerability in photonic semiconductor substrates, with Chinese SAMR licensing favoring domestic entities for precision surveying contracts. Distribution runs through hyperscaler cloud infrastructure for dynamic tile serving, while air-gapped on-premise installations serve defense and automotive prototype validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where solid-state LiDAR cost curves intersect with compliance-driven procurement mandates. NeRF-derived synthetic training data substitution compresses legacy photogrammetry margins while opening premium-tier positions for auditable provenance providers.
For Market Incumbents: Cement automotive validation relationships through embedded map stack integration extending beyond navigation into V2X cooperative perception architectures. Invest in backward integration toward solid-state LiDAR sensor manufacturing to capture gallium arsenide supply chain value. Defend against neural radiance field substitution by repositioning photogrammetry services toward rare-event simulation data licensing for autonomous vehicle training pipelines. For New Entrants and Emerging Players: Enter via Indian smart city 3D model mandates where legacy vendor relationships remain unformed and procurement volume exceeds domestic capacity. Target EU CSRD geospatial disclosure compliance as a white-space segment where carbon-accounting-integrated platforms face limited incumbent specialization. Pursue API-first metered pricing architectures to capture fleet operator unbundling from telematics hardware contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where photogrammetry service margins face software substitution and certified provenance capabilities concentrate in automotive-grade specialists. Long-term viability favors platforms with pre-built emissions factor databases and federal motor transport authority validation pipelines. Acquisition target archetypes include mid-tier LiDAR survey operators with municipal digital twin portfolios and carbon-accounting location intelligence platforms serving German automotive and French luxury goods conglomerates. Watch for inflection where V2X protocol standardization accelerates cooperative perception map procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API Unbundling from Hardware Contracts | Fleet operators in North American long-haul trucking now maintain multi-provider map stacks for routing optimization. |
| Backward Integration into Solid-State LiDAR | Captures gallium arsenide substrate value chain amid Chinese export licensing restrictions inflating sensor costs. |
| CSRD Compliance Platform Development | German automotive and French luxury goods conglomerates face mandatory procurement by corporate sustainability reporting deadlines. |
| NeRF-Derived Synthetic Training Data Licensing | Autonomous vehicle perception teams at German and Japanese OEMs converge on rare-event simulation data substitution. |
| Indian Smart City Digital Twin Procurement | Ministry of Housing and Urban Affairs mandates create volume absent legacy vendor relationships in 100 metropolitan areas. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each regional cluster combining structured interviews with automotive platform engineers, municipal GIS procurement officers, LiDAR sensor manufacturing specialists, and fleet telematics managers. Secondary validation draws from FAA drone operation filings, EU CSRD disclosure drafts, Chinese SAMR data localization circulars, and Indian Ministry of Housing smart city tender documents. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Rate-of-change decomposition separates volume expansion from value-mix shifts across navigation, urban planning, fleet management, location-based services, and disaster management applications. Technology segmentation models satellite imagery, LiDAR, crowdsourced mapping, GIS, and real-time data diffusion curves. End-user segmentation captures transportation companies, government agencies, telecommunication providers, and e-commerce platforms. CAGRs derive from installed base growth, replacement cycles, and compliance-driven upgrade mandates. Forecast inputs incorporate LiDAR sensor cost curve trajectories and neural radiance field adoption rates in autonomous vehicle perception teams.
Inputs from automotive OEM development centers, municipal procurement databases, and satellite operator priority access contracts were available through the study window; gaps in classified defense intelligence community requirements introduce uncertainty bands around on-premise deployment projections. Forecasts reflect assumptions regarding V2X protocol standardization velocity and EU AI Act certification pipeline throughput. Material deviation in gallium arsenide export licensing severity or German KBA type-approval timeline compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Global Geospatial Solutions Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Electronic Cartography Market