
 Sales Mapping System Market | 2026-2036
Sales Mapping System Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Mapping System Market Insights
The direct sales channel is narrowing as cloud-based deployment displaces traditional software resale. Salesforce Maps leverages its native CRM integration to dominate enterprise accounts. Badger Maps competes through mobile-first design aimed at field representatives. SPOTIO anchors its position in specialty verticals such as roofing and home services.
A sales mapping system integrates geographic information systems, customer relationship data, and routing algorithms to visualize sales territories, optimize travel sequences, and prioritize prospect engagement based on spatial proximity and account value. Cloud-based deployment leads current uptake among mid-market buyers seeking lower upfront infrastructure commitment. AI-powered technology segments are expanding fastest as predictive models layer demographic and behavioral signals onto traditional geocoding. GIS-based applications retain the largest installed base but face margin compression from commoditized base-mapping services.
The EU AI Act imposes transparency obligations on automated decision systems used for lead ranking and territory allocation, compelling vendors to document algorithmic logic. The US Federal Trade Commission scrutinizes location data collection practices in sales intelligence tools under evolving privacy enforcement frameworks. Stakeholders must monitor whether emerging state-level biometric and geolocation statutes in California and Illinois will trigger product architecture changes or geographic feature restrictions.
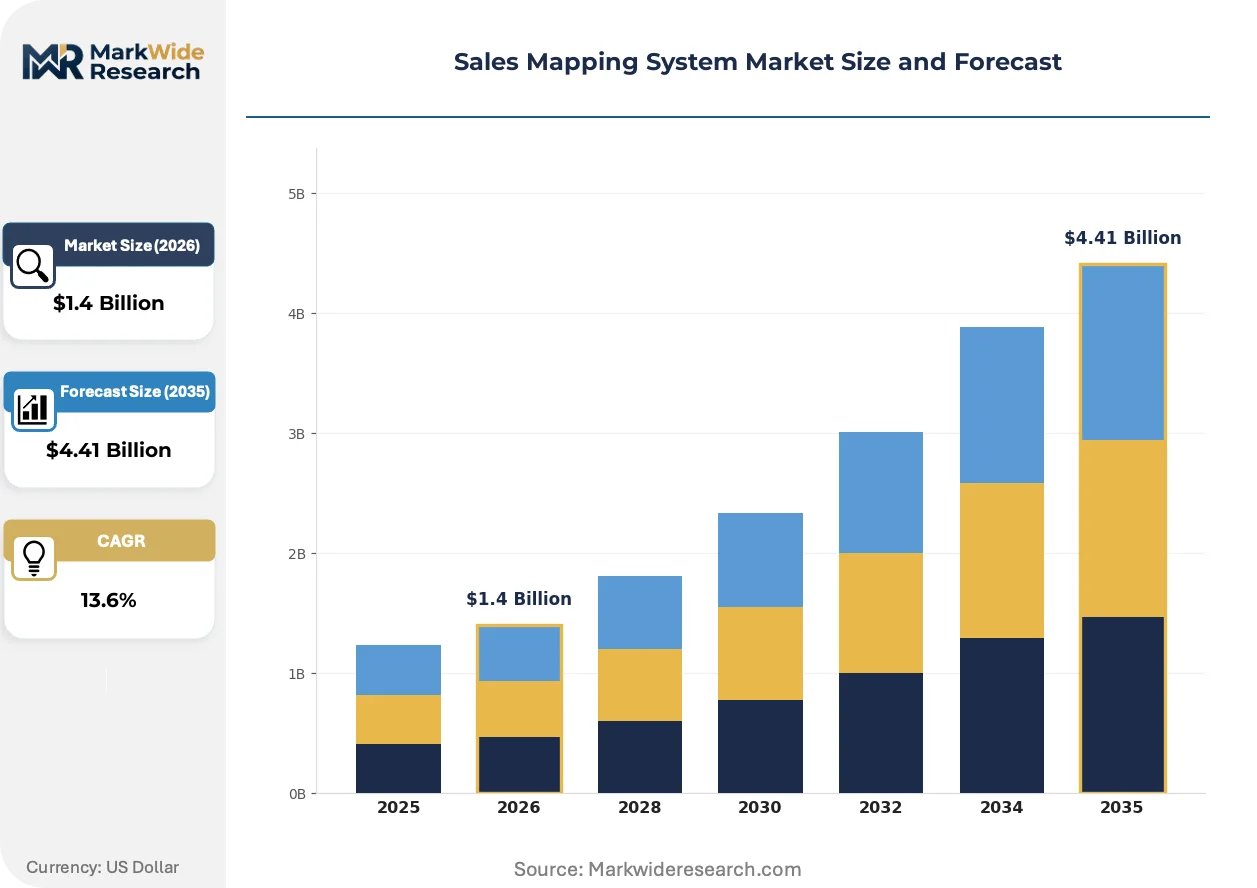
Market Dynamics
Cloud-native architectures are compressing deployment cycles and eroding the traditional software resale channel, forcing incumbent vendors to rebuild their delivery stacks around API-first integrations with enterprise CRM platforms.
Growth Catalysts
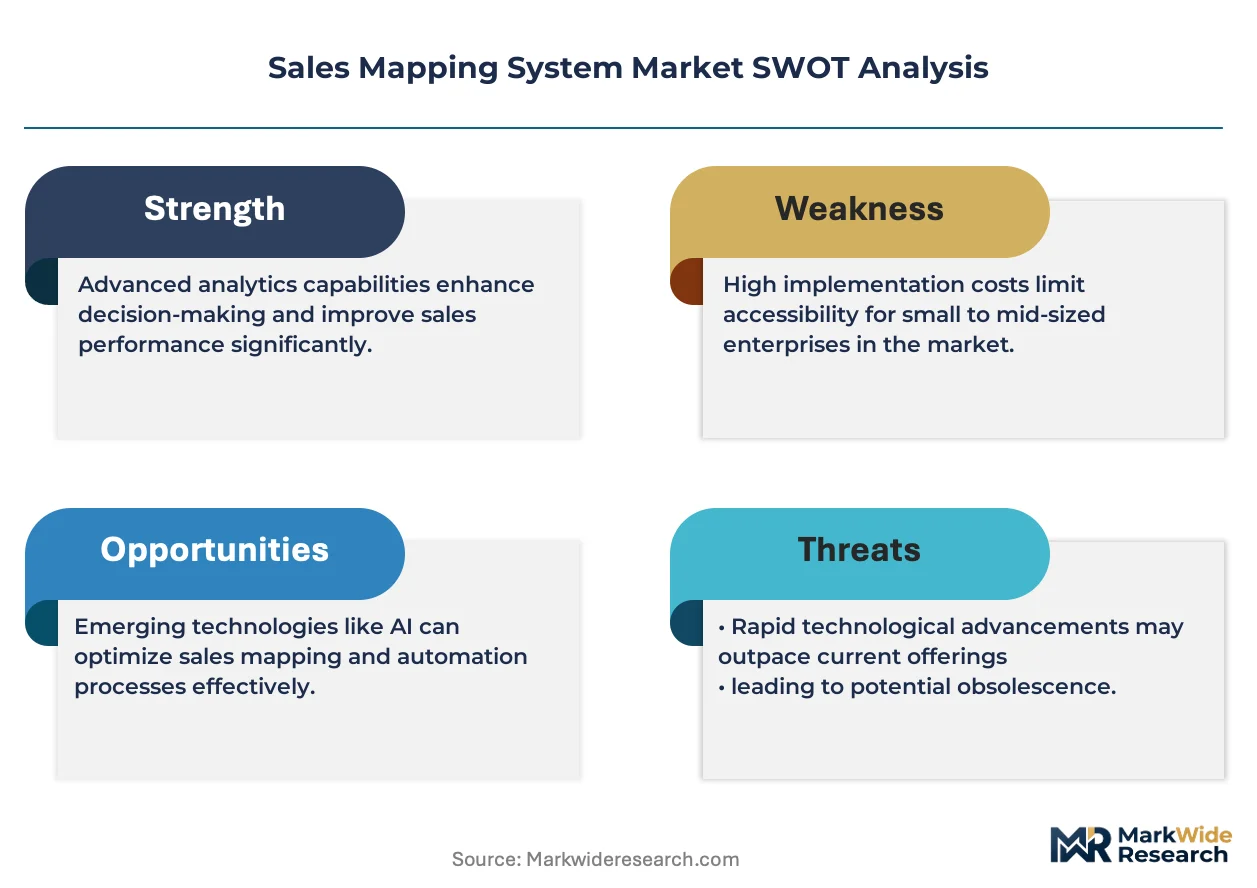
- EU AI Act transparency mandates:Automated lead-scoring systems now require documented algorithmic logic, creating pull for compliant mapping platforms that embed audit trails natively.
- Pharmaceutical field force expansion:Territory optimization tools reduce rep drive time between healthcare facilities, directly improving call frequency metrics in Germany and France.
- Predictive geocoding convergence:Machine learning models layering demographic signals onto base maps enable dynamic territory rebalancing without manual redistricting.
Market Restraints
- Base-mapping commoditization:OpenStreetMap and government geospatial data feeds compress margins for GIS-dependent vendors who lack proprietary enrichment layers.
- Location data privacy friction:The US FTC intensifies scrutiny of geolocation collection practices, forcing architectural changes to consent flows and data retention policies.
- Legacy ERP integration debt:Industrial equipment manufacturers in Germany face multi-year timelines to connect mapping systems with SAP environments, delaying cloud migration.
Strategic Opportunities
- Home services vertical underpenetration:Roofing and HVAC contractors in the US Southeast lack purpose-built tools for seasonal demand surge management and crew dispatch.
- CSRD supply chain mapping:European sustainability disclosure rules mandate geospatial traceability of supplier networks, opening adjacent revenue streams for platform vendors.
- Edge-AI routing on mobile devices:On-device inference eliminates latency for field reps in rural coverage gaps, differentiating premium tier offerings.
Industry Challenges
- Geospatial data science talent scarcity:Vendors compete for engineers with combined expertise in GIS algorithms and enterprise SaaS architecture, inflating compensation costs.
- Cross-border data residency conflicts:German industrial clients require EU-sovereign cloud instances while US headquarters demand unified global dashboards, complicating product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Mapping System Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Edge Customer Type: SMEs, Large Enterprises, Startups, Franchise Technology: GIS, AI, Mobile Apps, Data Analytics Application: Sales Optimization, Market Analysis, Route Planning, Lead Generation |
| Companies Covered | Badger Maps, Salesforce Maps, SPOTIO, eSpatial, Mapline, Maptive, Geopointe, MapBusinessOnline, Map My Customers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Mapping System Market Trends and Innovations
Artificial intelligence is rewiring how sales organizations allocate attention across geographic opportunity surfaces, compressing the cycle between territory design and field execution from quarters to weeks.
Predictive routing engines are migrating from batch-processed overnight optimization to real-time recalculation as reps complete calls. Pharmaceutical field teams in Germany adopt these systems fastest, with 15-minute refresh intervals replacing static daily itineraries. The shift collapses the competitive moat of vendors who rely on pre-computed route files.
The EU AI Act imposes documentation burdens on automated territory allocation algorithms that rank prospects by conversion probability. Vendors serving European pharmaceutical and industrial equipment clients must now expose model weights and feature importance scores to compliance officers. German manufacturers are demanding ISO 42001 AI management system certification as a procurement gate.
Subscription pricing for mapping platforms displaces perpetual license structures among mid-market buyers. Field sales managers prefer operational expenditure treatment that aligns costs with seasonal headcount fluctuations. This preference concentrates in US roofing and home services verticals where contractor hiring surges follow storm seasons and housing permit cycles.
Sales Mapping System Market Segmentation
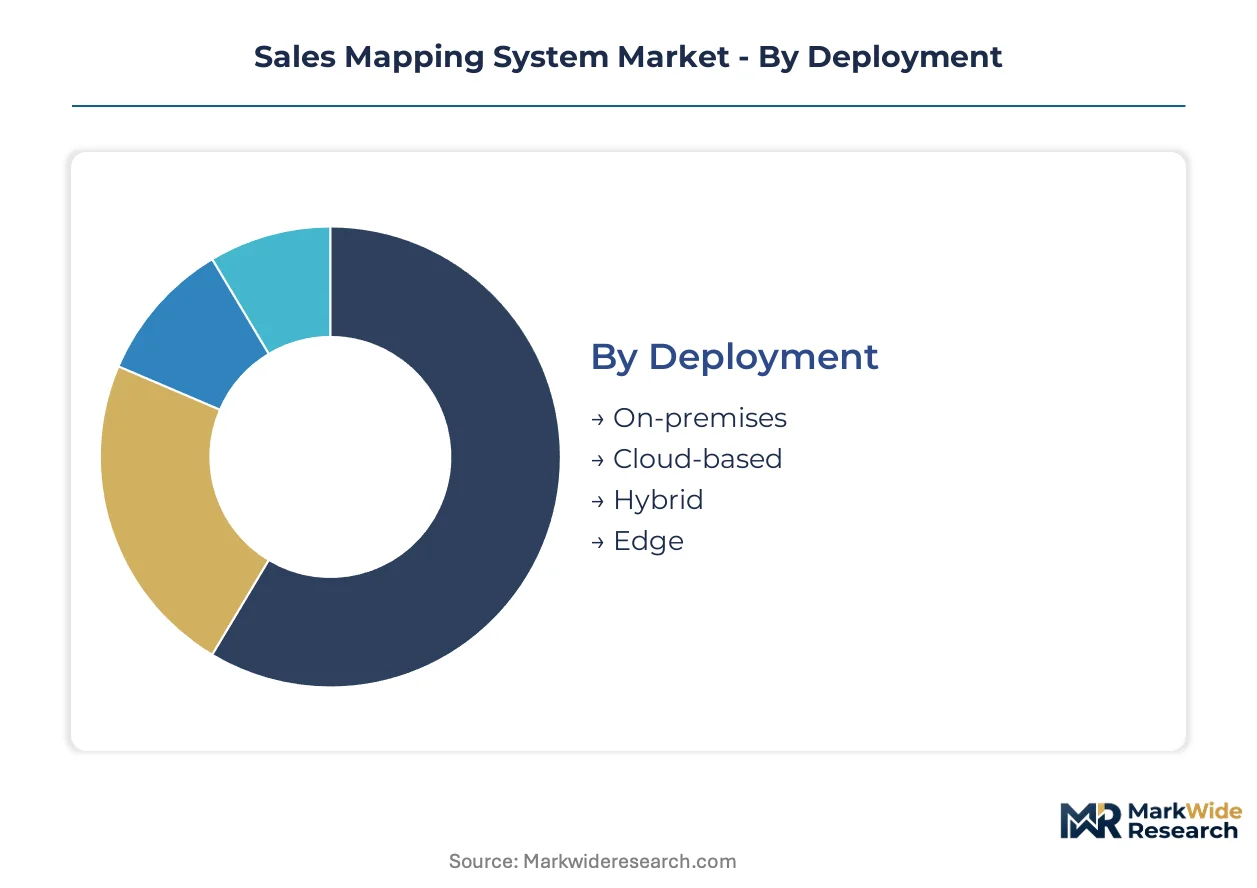
Sales mapping systems serve heterogeneous buyer profiles with divergent infrastructure constraints and workflow integration requirements. Deployment architecture, customer scale, underlying technology, and functional application each create distinct purchasing criteria and vendor selection patterns across the market.
Deployment:
Cost tier determines infrastructure commitment and total ownership economics for mapping platform buyers.
- Cloud-based:Multi-tenant SaaS architectures eliminate server procurement and reduce upfront capital outlay. Pharmaceutical field teams in Germany and France prioritize this model for rapid territory rollout without IT backlog delays.
- On-premises:Licensed software deployed within buyer-controlled data centers maintains full data sovereignty. Industrial equipment manufacturers with existing SAP environments in Germany favor this model for ERP integration control despite longer implementation cycles.
- Hybrid:Sensitive customer records remain on local servers while routing computations execute in cloud instances. Financial services regulators in Switzerland and Germany accept this architecture for geolocation analytics.
- Edge:Inference and route optimization run directly on field representative mobile devices without continuous connectivity. Rural coverage gaps in the US Mountain West and Australian Outback drive adoption among agricultural equipment sales teams.
Cloud-based holds installed capacity. Edge is rotating up the share rankings.
Customer Type:
Application intensity varies sharply by organizational scale and sales motion complexity.
- Large Enterprises:Multi-divisional deployments across thousands of field personnel require API-first integration with incumbent CRM platforms. US-based medical device manufacturers and German automotive suppliers represent concentrated demand for centralized territory governance.
- SMEs:Mid-market buyers prioritize subscription pricing that aligns costs with seasonal headcount fluctuations. US roofing and HVAC contractors in storm-prone Southeast states adopt mobile-first tools for surge crew dispatch.
- Franchise:Distributed ownership structures need territory protection mechanisms and performance benchmarking across units. Quick-service restaurant networks in Canada and Australia use mapping systems to optimize delivery zone allocation.
- Startups:Early-stage companies with lean sales teams seek freemium entry points and rapid scaling without procurement friction. SaaS vendors in Israel and Singapore pilot AI-powered lead generation modules before enterprise commitment.
Large Enterprises anchor current revenue concentration. SMEs are climbing the fastest as subscription pricing displaces perpetual licenses.
Technology:
Margin structure and differentiation potential depend on proprietary data layers versus commodity infrastructure.
- AI:Machine learning models layer demographic and behavioral signals onto base maps for dynamic territory rebalancing. EU AI Act transparency mandates in Germany and France now require documented algorithmic logic for automated lead-scoring systems.
- GIS:Geographic information systems retain the largest installed base through mature geocoding and visualization capabilities. OpenStreetMap commoditization compresses margins for vendors lacking proprietary enrichment layers.
- Mobile Apps:Native iOS and Android interfaces with offline functionality serve field representatives in connectivity-constrained environments. Australian mining equipment sales teams and US agricultural distributors demand ruggedized device support.
- Data Analytics:Business intelligence dashboards aggregate spatial performance metrics for sales operations planning. Japanese industrial distributors integrate these tools with METI-supported digital transformation initiatives.
GIS retains legacy deployment volume. AI is gaining share fastest as predictive routing migrates from batch to real-time recalculation.
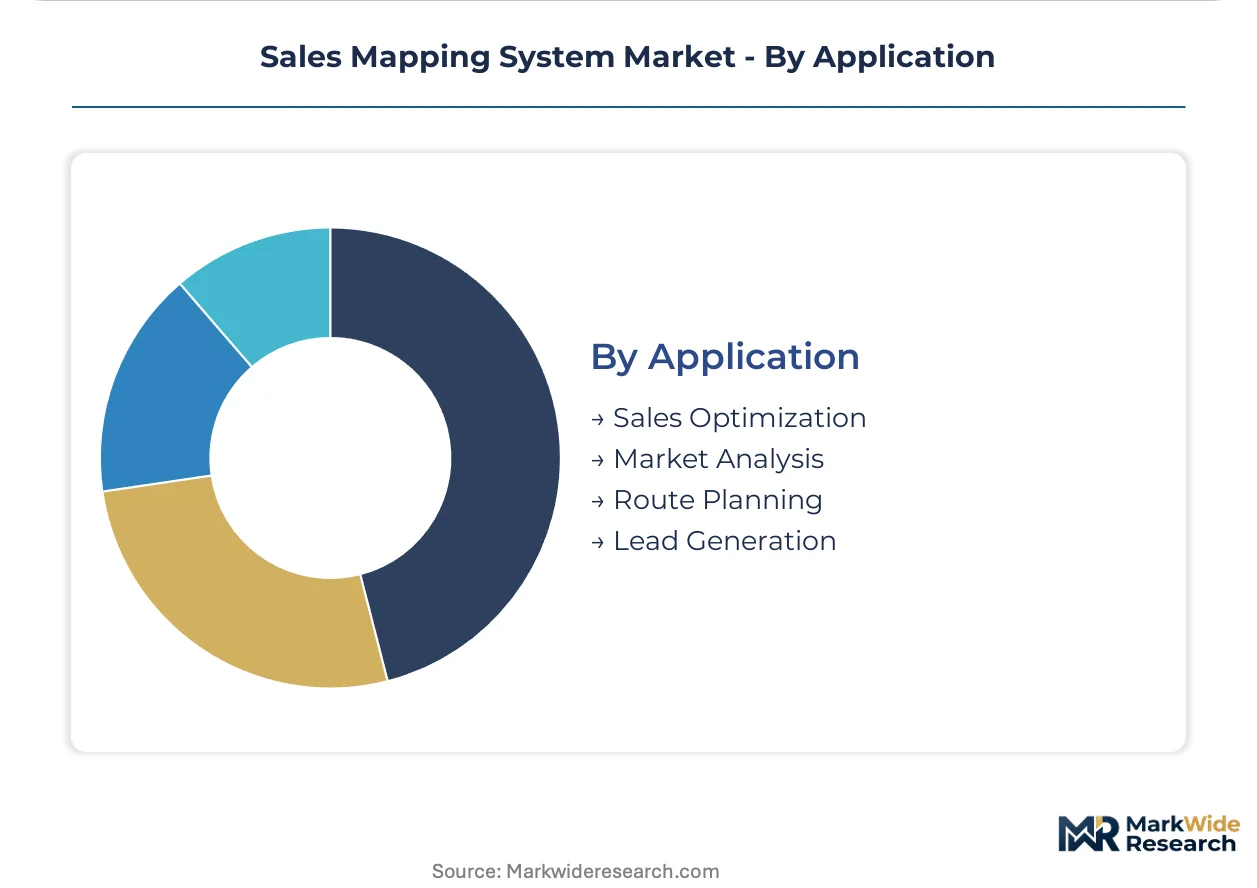
Application:
Functional use case determines integration depth and user workflow embedding.
- Route Planning:Sequencing algorithms minimize drive time between customer locations and compress daily mileage. Pharmaceutical reps in Germany now expect 15-minute itinerary refresh intervals rather than static daily schedules.
- Sales Optimization:Territory design tools balance account potential with travel burden to maximize revenue per rep hour. US medical device manufacturers deploy these systems to align specialist coverage with hospital clustering patterns.
- Lead Generation:Spatial prospecting identifies high-probability targets based on proximity to existing accounts and demographic overlays. Israeli cybersecurity vendors and Singaporean fintechs use these capabilities for geographic market entry.
- Market Analysis:Competitive intelligence mapping visualizes rival presence and whitespace opportunity for strategic planning. German industrial equipment manufacturers combine this with CSRD supply chain traceability requirements.
Route Planning holds current utilization breadth. Sales Optimization is rotating up the share rankings as real-time data feeds enable dynamic territory adjustment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC intensifies scrutiny of geolocation data collection practices in the United States, while the EU AI Act imposes transparency mandates on automated lead-scoring systems across European pharmaceutical and industrial equipment sectors.
United States
Pharmaceutical field sales teams deploy route optimization to compress drive time between healthcare facilities. The FTC examines location data retention policies in sales intelligence tools under evolving privacy enforcement frameworks. Roofing and HVAC contractors in the US Southeast adopt mobile-first mapping platforms for seasonal crew dispatch during storm surges.
Germany
Industrial equipment manufacturers leverage territory design tools to align specialist coverage with complex B2B sales cycles. The EU AI Act requires documented algorithmic logic for automated prospect ranking systems, compelling vendors to expose model weights to compliance officers. Manufacturing clusters in Baden-Württemberg and Bavaria demand ISO 42001 AI management system certification as a procurement gate.
France
Pharmaceutical representatives adopt real-time itinerary recalculation with 15-minute refresh intervals replacing static daily schedules. The CNIL enforces GDPR-aligned consent flows for geolocation analytics in field sales applications. Paris-based medical device distributors integrate mapping systems with centralized territory governance platforms.
United Kingdom
Mid-market buyers prioritize subscription pricing that aligns mapping platform costs with seasonal headcount fluctuations. The Information Commissioner's Office scrutinizes cross-border data transfers in sales intelligence tools post-Brexit. London-based SaaS vendors pilot AI-powered lead generation modules before enterprise commitment.
Japan
Industrial distributors integrate spatial performance dashboards with METI-supported digital transformation initiatives. The country's national data protection authority examines automated decision systems in customer-facing sales tools. Manufacturing sales teams in the Nagoya-Chubu corridor deploy predictive geocoding for dynamic territory rebalancing.
Sales Mapping System Market Competitive Landscape
Enterprise CRM-integrated platforms and mobile-first specialists split the market into distinct service tiers. Cloud-native architectures compress deployment cycles and erode traditional software resale channels. Three archetypes dominate: native CRM extensions, vertical-specific applications, and standalone routing platforms. Incumbent vendors rebuild delivery stacks around API-first integrations, while challengers pursue vertical specialization in underpenetrated home services segments.
Within the native CRM extension tier, Salesforce Maps anchors enterprise account penetration through seamless platform integration. Badger Maps occupies a position in the mobile-first specialist archetype, targeting field representatives with dedicated smartphone workflows. SPOTIO exemplifies vertical specialization, embedding deeply in roofing and home services workflows where seasonal demand surge management creates distinct functional requirements.
| Leading Market Players |
|---|
| Badger Maps |
| Salesforce Maps |
| SPOTIO |
| eSpatial |
| Mapline |
| Maptive |
| Geopointe |
| MapBusinessOnline |
| Map My Customers |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure overcapacity in North America and Western Europe compresses hosting costs for SaaS vendors, enabling aggressive per-seat pricing while forcing legacy on-premises providers into defensive discounting to retain enterprise accounts.
Pricing Analysis
German industrial equipment manufacturers pay premiums of 40-60% above US roofing contractors for equivalent routing functionality due to EU AI Act compliance documentation and ISO 42001 certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates enterprise CRM-integrated suites from mobile-first specialist tools and freemium entry points. Cost compression in the mid-market tier is intensifying because OpenStreetMap commoditization erodes proprietary GIS margins. SMEs in seasonal home services verticals exhibit highest price sensitivity, while pharmaceutical field sales teams in Germany show lowest elasticity due to compliance-driven procurement gates.
Supply Chain Analysis
Extended payment terms from 30 to 90 days now characterize vendor relationships with German automotive suppliers and US medical device manufacturers, reflecting working capital pressure downstream. Cloud infrastructure draws from hyperscale facilities in the United States, Ireland, and Germany, with edge-compute hardware sourcing from Taiwan and South Korea. Base-mapping data feeds from OpenStreetMap, government geospatial agencies, and commercial satellite operators create single-source vulnerability for vendors lacking proprietary enrichment layers. Distribution runs through direct API-first integration with Salesforce and Microsoft CRM platforms, displacing traditional software resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical field force expansion across Germany and France signals early-cycle expansion, with territory optimization tools penetrating less than 30% of addressable sales rep seats despite proven call-frequency improvements.
For Market Incumbents: Harden API integration moats by embedding EU AI Act audit trails natively into Salesforce Maps and competing enterprise platforms. Acquire mobile-first specialists with vertical depth in home services before challengers consolidate roofing and HVAC contractor segments. Invest in ISO 42001 certification infrastructure to defend procurement position in German manufacturing clusters against emerging compliance-native entrants. For New Entrants and Emerging Players: US Southeast roofing and HVAC contractors represent the most penetrable white-space target, with seasonal crew dispatch needs unmet by generic routing tools. Target edge-AI routing capabilities for rural coverage gaps in the Mountain West and Australian Outback where agricultural equipment sales teams lack offline functionality. Pursue freemium land-and-expand tactics with Israeli and Singaporean SaaS startups before enterprise commitment thresholds harden. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment tiers as multi-tenant architectures achieve scale efficiencies. Position for 5-10 year consolidation around vertical-specialist platforms with proprietary data layers that resist OpenStreetMap commoditization. Monitor German industrial procurement mandates for ISO 42001 certification as the inflection signal distinguishing premium-tier vendors from compliance-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Integration | Native audit trail embedding satisfies German pharmaceutical and industrial procurement gates. |
| Vertical Platform Acquisition | Roofing and HVAC specialist tools capture seasonal demand surge management workflows. |
| Edge-AI Routing Development | On-device inference eliminates latency for agricultural reps in rural coverage gaps. |
| ISO 42001 Certification Investment | AI management system credential opens Baden-Württemberg and Bavaria manufacturing accounts. |
| API-First CRM Partnership | Native Salesforce and Microsoft integration displaces traditional software resale intermediaries. |
Research Methodology
Operator-level perspectives from sales operations directors, field force managers, CRM platform engineers, and geospatial data scientists anchored the qualitative base. Primary interviews with territory optimization leads at German pharmaceutical companies and US medical device manufacturers combined with secondary validation from SEC filings, EU AI Act regulatory texts, METI digital transformation disclosures, and hyperscaler capex reports. Bottom-up deployment counts and top-down software spend estimates triangulated market sizing.
Scenario-bracketing around cloud migration velocity and EU AI Act enforcement intensity framed the analytical approach across the projection horizon. Modeled dimensions include deployment architecture, customer scale tier, underlying technology stack, and functional application with industry-specific weighting for pharmaceutical field force adoption patterns and German industrial compliance requirements. CAGRs derived from segment-level growth rate distributions applied to base-year capacity estimates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical acquisition moves by CRM-native platforms or hyperscaler entrants would shift outcomes. Macroeconomic contraction in European manufacturing, delayed EU AI Act enforcement, or breakthrough open-source routing algorithms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Saudi Arabia Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Canada Location-Based Services Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market