
 Mobile Map Market | 2026-2036
Mobile Map Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Map Market Outlook
The EU Green Deal's embedded mobility carbon accounting is recalibrating how fleet operators select map platforms for route optimization. Google leverages its Street View capture infrastructure to sustain data freshness across urban corridors. HERE Technologies anchors automotive-grade mapping through its OEM partnerships with German and Japanese manufacturers. Apple differentiates via privacy-preserving on-device processing that limits server-side location retention.
A mobile map constitutes a digital geospatial representation rendered on handheld or vehicle-embedded devices, combining vector tile databases with real-time sensor fusion from GNSS receivers, inertial measurement units, and camera-based visual positioning systems to deliver navigational guidance and location intelligence. Navigation and real-time traffic applications dominate current revenue pools, while location-based services for retail and logistics represent the fastest-expanding segment as enterprises deploy geofenced workforce management tools. GPS technology leads deployment volumes, though Bluetooth beacons are gaining traction in indoor positioning environments where satellite signals degrade.
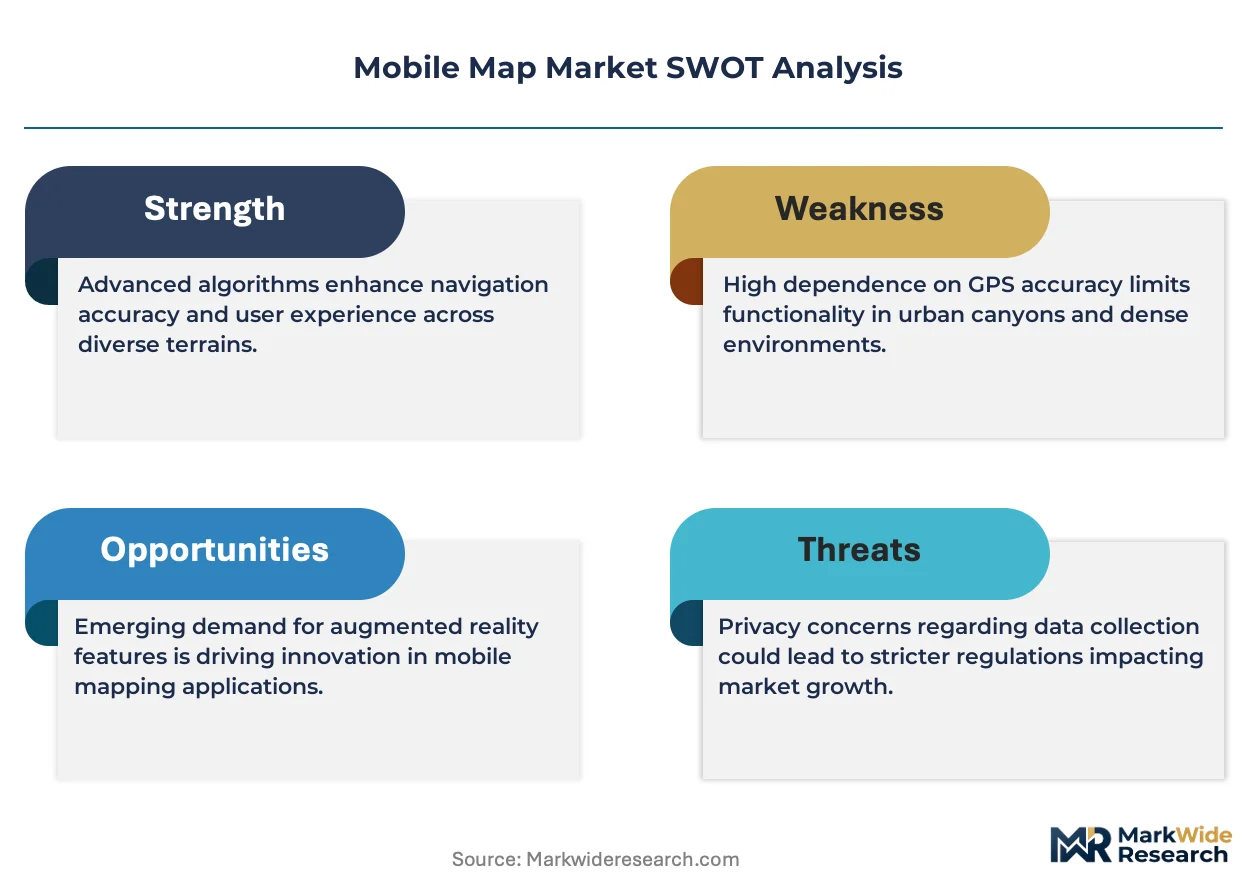
The European Union's GDPR and the EU AI Act impose strict constraints on geolocation data retention and automated decision-making based on movement patterns, compelling providers to redesign data architectures. The US Federal Communications Commission governs spectrum allocation for positioning signals, while the FAA regulates aerial mapping operations that feed mobile map updates. Stakeholders must weigh the capital requirements of proprietary sensor fleets against the regulatory risks of third-party data licensing as precision standards tighten across jurisdictions.
Market Dynamics
Ride-hailing platforms and autonomous vehicle developers are expanding procurement of high-precision mapping layers, compressing refresh cycles from quarterly to near-real-time updates and forcing capital reallocation toward sensor fleet expansion.
Growth Catalysts
- EU AI Act geolocation governance:Compliance mandates are accelerating investment in privacy-preserving data architectures among European map providers.
- Indoor positioning environments:Bluetooth beacon deployments in retail and logistics facilities are extending addressable use cases beyond road networks.
- Carbon accounting integration:Fleet operators under the EU Green Deal are embedding route optimization tools to document emissions reductions for regulatory filings.
Market Restraints
- Proprietary sensor fleet capital intensity:LiDAR-equipped capture vehicles require eight-figure capital commitments per thousand-kilometer coverage expansion.
- GDPR retention constraints:Location data storage limitations prevent historical trajectory analysis that would improve predictive traffic models.
- GNSS signal degradation:Urban canyon environments in dense metropolitan cores degrade satellite positioning accuracy below autonomous vehicle thresholds.
Strategic Opportunities
- German automotive corridor concentration:Stuttgart and Munich host OEM engineering centers seeking co-development partnerships for automotive-grade mapping layers.
- Visual positioning system convergence:Camera-based localization fused with inertial measurement units enables navigation in GPS-denied environments.
- Geofenced workforce management:Enterprise logistics platforms are licensing map APIs for real-time driver dispatch and delivery verification.
Industry Challenges
- Photogrammetry specialist scarcity:The talent pool for processing aerial imagery into vector tile databases remains concentrated among a handful of technical institutes.
- Multi-jurisdiction certification timelines:FAA aerial mapping permits and national aviation authority clearances create six-to-twelve month deployment delays for capture operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Map Market |
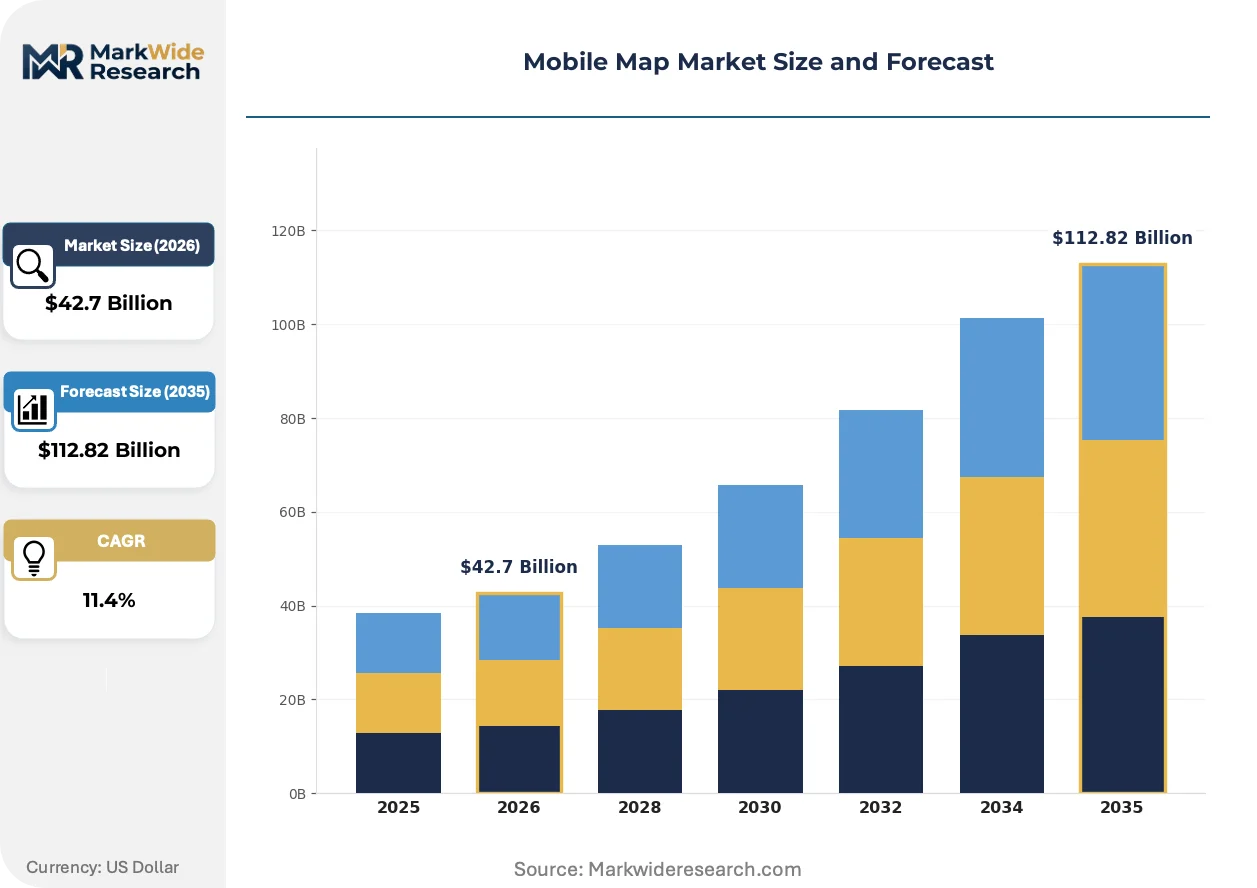
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Navigation, Real-Time Traffic, Location-Based Services, Map Visualization Technology: GPS, Wi-Fi Positioning, Cellular Network, Bluetooth Beacons End User: Individuals, Enterprises, Government Agencies, Third-Party Developers Distribution Channel: Mobile Apps, Web Platforms, OEM Partnerships, Retail |
| Companies Covered | Google, Apple, Trimble Inc., HERE Technologies, TomTom International BV, Microsoft Corporation, Leica Geosystems AG, Topcon Corporation, Teledyne Technologies Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Map Market Strategic Shifts
Real-time sensor fusion architectures are compressing the latency between physical environment changes and digital map updates, enabling dynamic rerouting based on construction, accidents, and weather conditions.
Vector tile databases combined with edge-computing frameworks are unifying previously siloed navigation, traffic, and location-based service functions into single-platform deployments. Automotive OEMs are adopting these consolidated stacks to reduce ECU complexity and software integration costs. The structural consequence is collapsing procurement from multiple point-solution vendors toward integrated platform licensing.
The EU AI Act's automated decision-making provisions are restricting how movement pattern analysis feeds dynamic pricing and predictive routing algorithms. Map providers serving European markets must implement human-in-the-loop review systems for algorithmic outputs affecting user mobility choices. Ride-hailing platforms operating across Germany, France, and the Netherlands are restructuring data pipelines to isolate European user trajectories from centralized analytics engines.
Fleet operators are consolidating vendor relationships around API-first map platforms that bundle navigation, traffic, and geocoding under consumption-based pricing. Traditional perpetual-license enterprise agreements are losing share to metered billing tied to monthly active vehicles or API call volumes. This shift is most pronounced among third-party logistics providers managing multi-country distribution networks across the European Union.
Mobile Map Market Segmentation
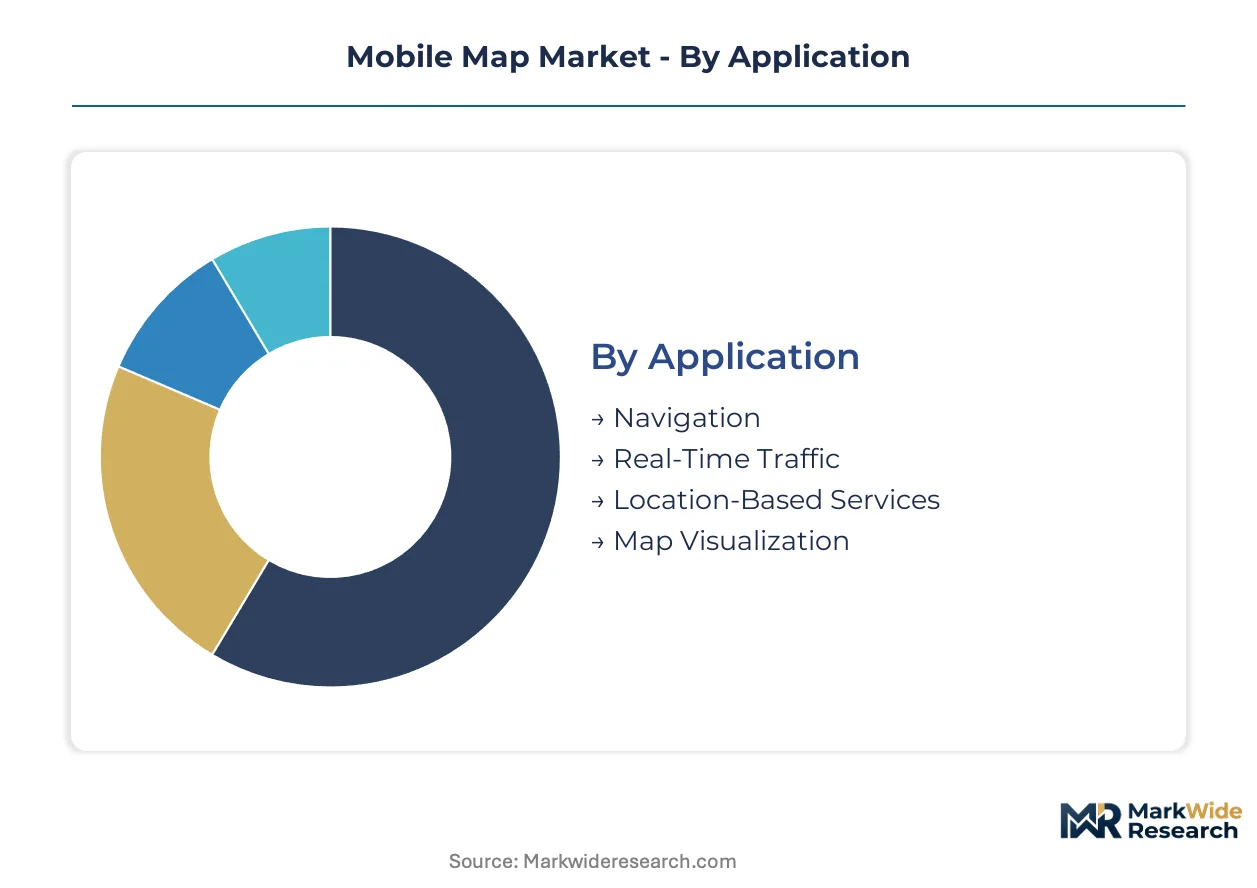
Mobile map providers engineer product architectures around distinct deployment contexts, each imposing unique certification burdens and data governance requirements. Segmentation clarity enables procurement teams to match precision specifications against regulatory constraints and integration complexity.
Application:
GDPR and EU AI Act compliance obligations vary sharply across use cases, with automated navigation systems facing stricter algorithmic transparency mandates than passive visualization tools.
- Navigation:Core routing engines process real-time GNSS signals fused with inertial measurement data to generate turn-by-turn guidance. Fleet operators in Germany's automotive corridor prioritize this segment for embedded OEM deployments requiring KBA certification for driver assistance integration.
- Real-Time Traffic:Dynamic congestion modeling aggregates probe data from connected vehicles and mobile devices to calculate predictive arrival estimates. Ride-hailing platforms compress procurement cycles here as autonomous vehicle developers demand sub-minute latency for path planning.
- Location-Based Services:Geofenced proximity triggers power retail loyalty programs and workforce dispatch systems.
- Map Visualization:Static and interactive cartographic rendering for enterprise dashboards and consumer applications.
Leading the category by volume: Navigation. Growing fastest: Location-Based Services.
Technology:
Positioning infrastructure investments stratify by signal source reliability and indoor penetration requirements, with hybrid architectures commanding premium licensing fees.
- GPS:Satellite-based trilateration using civilian L1/L2 frequencies remains the default outdoor positioning layer. Deployment concentrates in automotive navigation stacks where FCC spectrum allocation governs signal integrity standards.
- Wi-Fi Positioning:Fingerprinting algorithms match detected access point signatures against crowdsourced databases for urban canyon correction. Retail chains in dense metropolitan cores deploy this for indoor wayfinding where satellite signals degrade.
- Cellular Network:Tower triangulation and timing advance measurements provide coarse positioning fallback.
- Bluetooth Beacons:Low-energy beacon grids enable sub-meter accuracy for warehouse automation and museum navigation.
Dominant by deployment scale: GPS. Expanding most quickly: Bluetooth Beacons.
End User:
Data retention policies and API access tiers diverge across customer types, with government contracts imposing sovereign cloud requirements absent from commercial licensing.
- Individuals:Consumer applications prioritize privacy-preserving on-device processing with minimal server-side trajectory storage. GDPR Article 17 erasure requests drive architectural decisions here.
- Enterprises:Fleet management and logistics platforms license bulk geocoding and route optimization APIs under consumption-based contracts. Third-party logistics providers across the European Union consolidate procurement around these metered billing structures.
- Government Agencies:Public sector deployments require compliance with national security frameworks and data localization mandates.
- Third-Party Developers:Independent application builders integrate map SDKs under tiered usage quotas.
Highest revenue concentration: Enterprises. Steepest expansion trajectory: Third-Party Developers.
Distribution Channel:
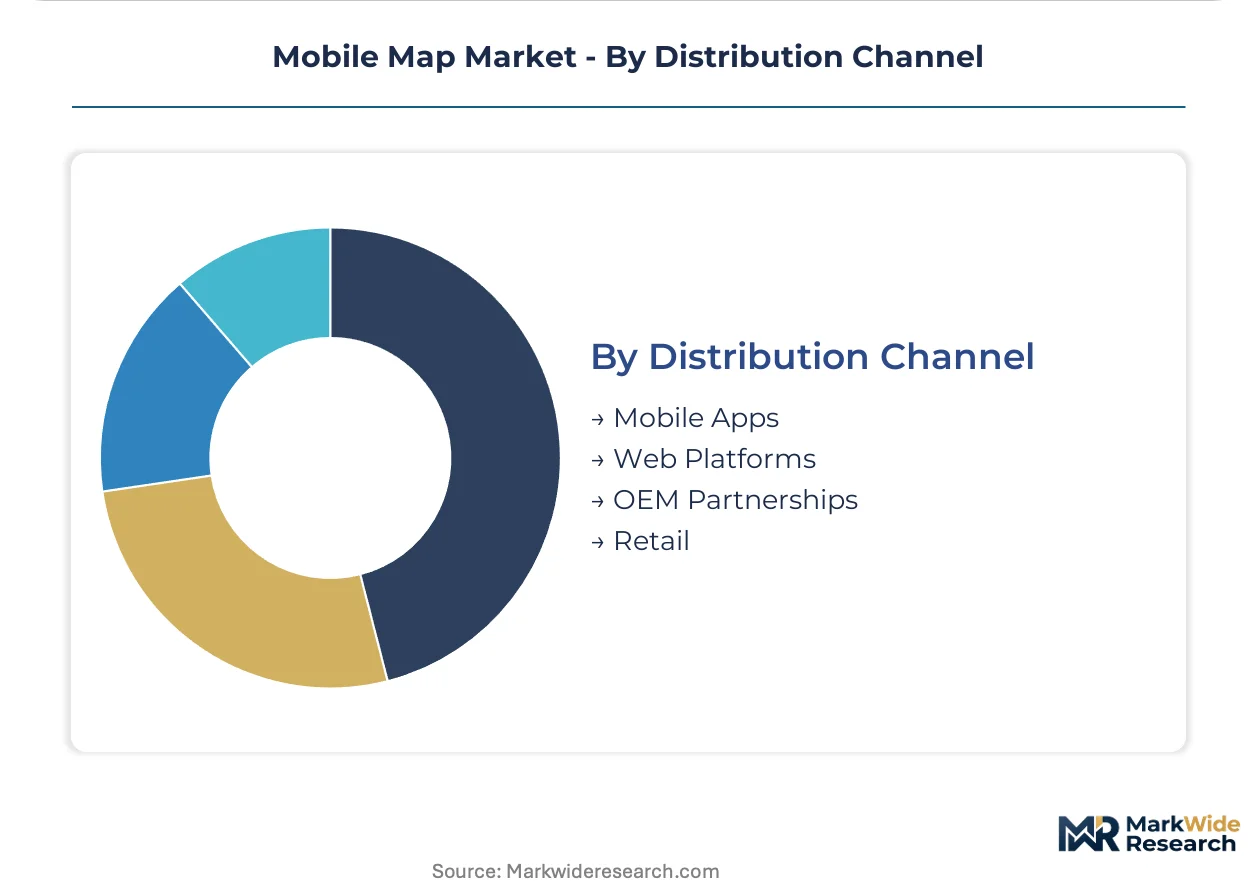
Integration complexity and margin structures vary by delivery mechanism, with OEM partnerships demanding multi-year co-development commitments.
- Mobile Apps:Direct-to-consumer distribution through Apple App Store and Google Play generates advertising-supported and subscription revenue pools. Freemium tiering dominates here with premium features locked behind monthly subscriptions.
- Web Platforms:Browser-based JavaScript APIs serve enterprise dashboards and logistics portals. Procurement teams favor these for rapid deployment without native application development cycles.
- OEM Partnerships:Deep integration into vehicle head units and telematics systems.
- Retail:Physical distribution of dedicated navigation hardware and prepaid service cards.
Largest transaction values: OEM Partnerships. Gaining share fastest: Web Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors the European mobile map procurement landscape through its concentration of automotive OEM engineering centers demanding automotive-grade mapping layers. The EU AI Act's geolocation governance provisions are recalibrating compliance architectures across the continent. Demand clusters trace Germany's automotive corridor south toward Munich.
Germany
HERE Technologies and TomTom International BV anchor procurement relationships with BMW, Mercedes-Benz, and Volkswagen for embedded navigation stacks. KBA certification requirements for driver assistance integration impose multi-year validation timelines on map data providers. Stuttgart and Munich host the densest concentration of OEM engineering centers seeking co-development partnerships for high-precision mapping layers.
United States
Google leverages its Street View capture infrastructure to sustain data freshness across urban corridors, while Apple differentiates via privacy-preserving on-device processing. The FAA regulates aerial mapping operations that feed mobile map updates, creating six-to-twelve month deployment delays for photogrammetry specialists. Silicon Valley and Detroit anchor competing development clusters for consumer and automotive-grade applications respectively.
China
Domestic map providers face MIIT data localization mandates requiring sovereign cloud storage for geolocation trajectories. NMPA oversight extends to navigation systems integrated with connected vehicle platforms. The Yangtze River Delta and Pearl River Delta concentrate autonomous vehicle testing zones driving demand for sub-meter accuracy mapping.
Japan
METI promotes precision positioning infrastructure through QZSS satellite augmentation supporting mobile map accuracy in urban canyon environments. Toyota and Honda procurement specifications prioritize map data fusion with inertial measurement units for lane-level navigation. Nagoya and Tokyo host the primary engineering centers for automotive-grade mapping integration.
United Kingdom
The Information Commissioner's Office enforces GDPR Article 17 erasure requests that constrain historical trajectory analysis for predictive traffic models. London's congestion pricing zone generates probe data demand for real-time traffic optimization. Cambridge and Oxford anchor visual positioning system research clusters addressing GPS-denied navigation.
Mobile Map Market Competitive Environment
The competitive structure tilts toward platform-scale providers with captive sensor fleets. Consolidation pressures favor integrated navigation-traffic-location service stacks over point-solution vendors. Two archetypes dominate: cloud-native platforms leveraging Street View-scale capture infrastructure, and automotive-specialist vendors with OEM partnership lock-in. Strategic moves concentrate on API-first platform consolidation and privacy-preserving data architecture redesign for EU AI Act compliance.
Within the platform-scale tier, Google and Apple exemplify divergent data governance philosophies, with the former maximizing server-side analytics and the latter emphasizing on-device processing. HERE Technologies anchors the automotive-specialist archetype through its German GmbH structure and OEM partnership density. Microsoft Corporation occupies a hybrid position, licensing map APIs to enterprise logistics platforms while avoiding direct consumer navigation competition. These three represent the structural poles around which procurement decisions organize.
| Leading Market Players |
|---|
| Apple |
| Trimble Inc. |
| HERE Technologies |
| TomTom International BV |
| Microsoft Corporation |
| Leica Geosystems AG |
| Topcon Corporation |
| Teledyne Technologies Incorporated |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon accounting mandates gate both qualified supply and premium-tier pricing access, as fleet operators under emissions compliance frameworks demand route optimization APIs bundled with documented environmental impact calculations. Map data providers lacking embedded carbon measurement modules face exclusion from automotive OEM procurement shortlists in Germany's automotive corridor.
Pricing Analysis
Consumption-based pricing tied to monthly active vehicles anchors value capture across enterprise logistics platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by API call volume, data freshness latency, and KBA certification grade for driver assistance integration. Cost compression in standard tiers intensifies because third-party logistics providers consolidate procurement around metered billing structures. Small fleet operators exhibit highest price sensitivity, while autonomous vehicle developers accept premium rates for sub-meter accuracy guarantees.
Supply Chain Analysis
Single-source vulnerability sits with LiDAR sensor fabrication concentrated in Germany, Japan, and the United States. Photogrammetry processing capacity draws from specialized technical institutes in Switzerland, the Netherlands, and the United Kingdom. Supply chain risk centers on FAA aerial mapping permit delays creating six-to-twelve month capture operation backlogs. Distribution runs through API-first platform licensing direct to enterprise fleet operators and embedded OEM partnerships with multi-year co-development commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photogrammetry specialist scarcity props pricing power across high-precision mapping tiers, constraining supply expansion regardless of capital availability. This bottleneck sustains margin premiums for providers with captive technical talent pipelines.
For Market Incumbents: Anchor automotive-grade positioning through exclusive KBA certification partnerships with Stuttgart and Munich OEM engineering centers. Deepen backward integration into LiDAR-equipped capture fleets to defend against emerging cloud-native platforms with Street View-scale infrastructure. Prioritize EU AI Act compliance architecture investments to preempt regulatory displacement of centralized analytics engines.
For New Entrants and Emerging Players: Mid-size third-party logistics providers managing multi-country EU distribution networks represent the most penetrable buyer archetype underserved by legacy perpetual-license vendors. Target geofenced workforce management applications in warehouse automation and retail loyalty programs where Bluetooth beacon integration commands lower certification barriers. Pursue API-first metered billing positioning against entrenched enterprise license incumbents.
For Investors and Strategic Acquirers: FAA permit approval acceleration for aerial mapping operations is the leading indicator that photogrammetry capacity expansion is unlocking, signaling margin compression risk for asset-heavy capture specialists. Long-term viability favors platform-scale providers with diversified sensor fusion architectures spanning GNSS, visual positioning, and inertial measurement. Monitor EU AI Act enforcement actions against centralized trajectory analytics as the signal for privacy-preserving architecture valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Architecture Redesign | EU AI Act compliance isolates European user trajectories from centralized analytics engines. |
| Sensor Fleet Expansion | LiDAR-equipped capture vehicles compress refresh cycles from quarterly to near-real-time updates. |
| API-First Platform Consolidation | Metered billing displaces perpetual licenses among third-party logistics providers. |
| Automotive OEM Co-Development Partnership | KBA certification partnerships lock in embedded navigation stack procurement. |
| Visual Positioning System Convergence | Camera-based localization enables navigation in GPS-denied urban canyon environments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with industry stakeholders and secondary validation. Primary fieldwork engaged fleet operations directors at third-party logistics providers, OEM platform engineers in Stuttgart and Munich, photogrammetry specialists at technical institutes, and API product managers at navigation platform vendors. Secondary sources encompassed KBA type-approval databases, FAA Section 333 exemption records, EU AI Act implementation guidance, and automotive OEM supplier disclosure filings. Bottom-up vehicle registration data triangulated against top-down platform revenue estimates across the analysis window.
Data-stream reconciliation between probe data volume, API call traffic, and embedded navigation unit shipments informed the analytical framework. Segmentation dimensions modeled encompassed application type, positioning technology, end-user archetype, and distribution channel complexity. CAGRs derived from logistic diffusion curves fitted to autonomous vehicle testing zone expansion and EU Green Deal compliance adoption rates. Industry-specific inputs included Street View capture fleet refresh schedules and QZSS augmentation deployment timelines.
Revisions become necessary when FAA regulatory timelines extend, photogrammetry specialist graduation rates shift, or EU AI Act enforcement patterns diverge from draft guidance. Forecasts reflect documented assumptions about sensor cost decline curves and OEM platform standardization decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
France Geospatial Analytics Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Asia Pacific Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market