
 Digital Immune System Market | 2026-2036
Digital Immune System Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Immune System Market Analytics
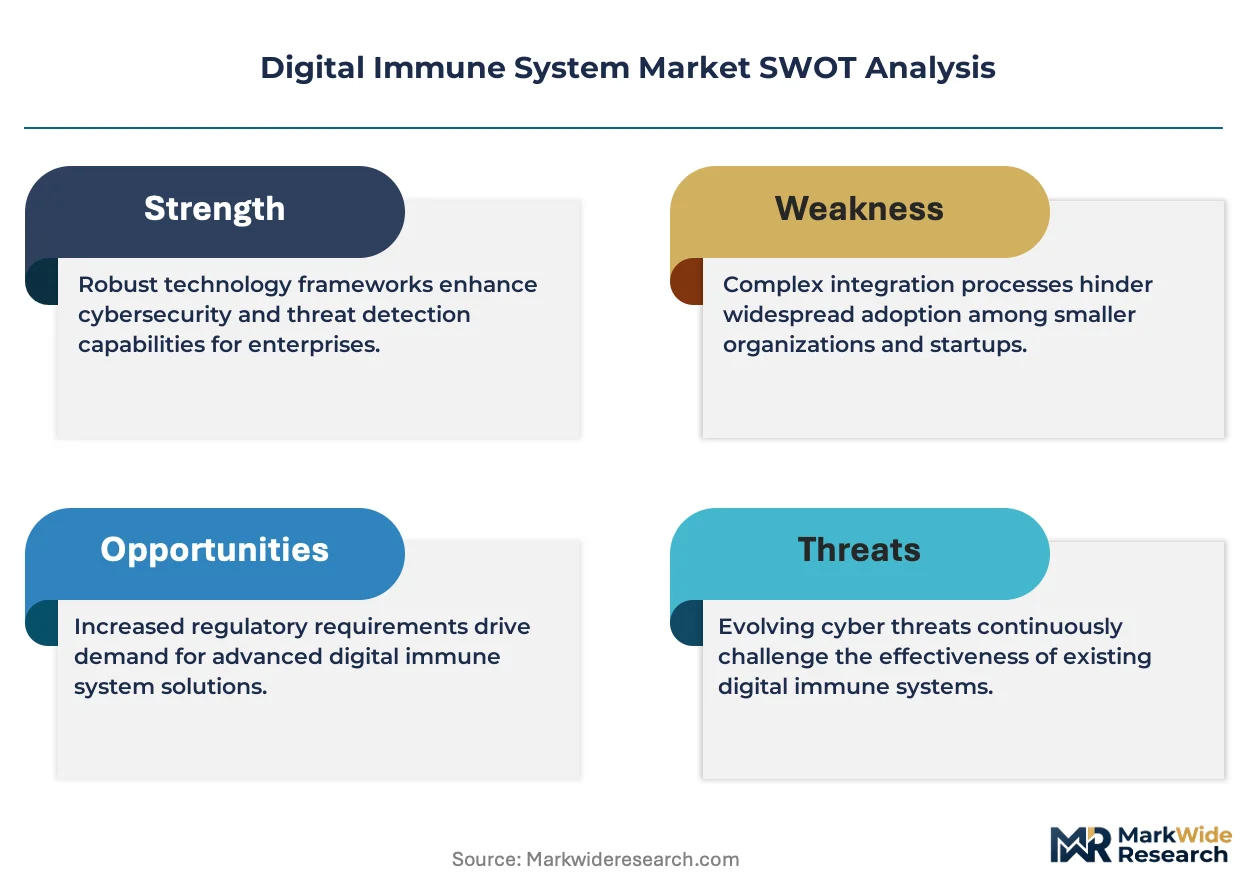
Cloud-native architectures are broadening the attack surface that digital immune systems must defend, forcing vendors to engineer autonomous response capabilities directly into distributed workloads. Palo Alto Networks leverages its platform consolidation strategy to anchor enterprise accounts across hybrid environments. Microsoft Corporation sustains R&D intensity in AI-driven threat detection through its security copilot investments. Check Point Software Technologies Ltd. differentiates via firewall-integrated autonomous remediation that reduces mean-time-to-response for critical infrastructure operators.
A digital immune system combines artificial intelligence, behavioral analysis, and automated incident response to detect, contain, and self-heal from cyber threats without human intervention, operating through continuous telemetry ingestion at sub-second latency thresholds to preserve operational continuity. Solution type segmentation reveals endpoint protection as the most mature revenue pool, while incident response capabilities capture the fastest expansion as organizations prioritize autonomous containment over alert generation. Deployment model dynamics favor hybrid architectures where edge computing nodes process sensitive telemetry locally before cloud correlation, addressing data sovereignty constraints in regulated industries.
The EU AI Act classifies autonomous security decision systems as high-risk AI, mandating human oversight mechanisms that shape product roadmaps for vendors serving European financial services and healthcare end users. In the United States, NIST's zero-trust architecture guidelines and the SEC's cybersecurity disclosure rules create dual compliance pressures that expand procurement budgets for integrated digital immune platforms. Stakeholders must monitor how regulatory fragmentation between jurisdictions affects cross-border deployment architectures and determines which vendors can offer unified compliance automation without regional product forks.
Market Dynamics
Autonomous security decision-making is compressing response latency from minutes to milliseconds, forcing infrastructure redesigns that embed self-healing capabilities directly into workload orchestration layers rather than bolt-on monitoring tools.
Growth Catalysts
- EU AI Act high-risk classification:Mandated human oversight mechanisms for autonomous security systems are accelerating vendor investment in explainable AI interfaces for financial services and healthcare deployments.
- Edge computing telemetry processing:Distributed architectures now handle sensitive data locally before cloud correlation, satisfying data sovereignty constraints in regulated industries and expanding addressable infrastructure.
- Federal zero-trust mandates:United States procurement cycles for self-healing infrastructure have shortened as civilian and defense agencies prioritize continuous verification architectures.
Market Restraints
- Specialized AI/ML engineering talent scarcity:Behavioral analysis model development requires rare expertise in adversarial machine learning, constraining vendor scaling velocity.
- Sub-second latency infrastructure costs:Continuous telemetry ingestion at millisecond thresholds demands premium compute and networking investments that price out mid-market buyers.
- Cross-border data flow restrictions:Divergent sovereignty requirements between United States CLOUD Act provisions and European GDPR localization mandates fragment unified platform architectures.
Strategic Opportunities
- Operational technology convergence:Industrial control systems and critical infrastructure operators present underpenetrated demand for autonomous containment as ransomware targets operational networks.
- Hybrid deployment standardization:Unified management planes spanning on-premises, multi-cloud, and edge environments enable vendors to capture multi-year enterprise transformation budgets.
- SEC cybersecurity disclosure rules:Material incident reporting requirements are expanding procurement authority for integrated digital immune platforms among publicly traded corporations.
Industry Challenges
- Legacy SIEM integration complexity:Existing security information and event management investments require costly API abstraction layers to feed telemetry into autonomous response engines.
- Adversarial AI robustness certification:Lack of standardized testing frameworks for machine learning model resilience against evasion attacks delays enterprise procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Immune System Market |
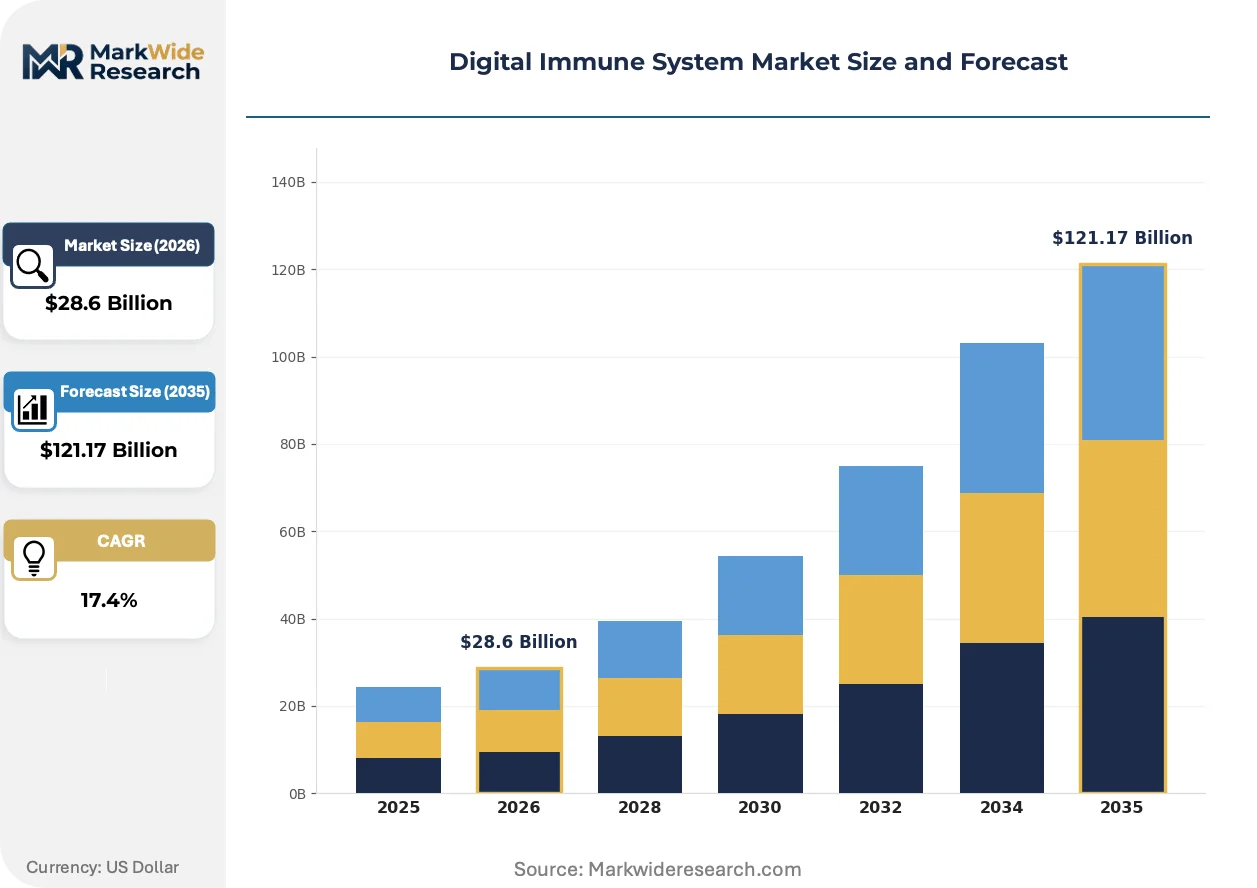
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Machine Learning, Behavioral Analysis, Threat Intelligence Deployment Model: Cloud-based, On-premises, Hybrid, Edge Computing End User: Healthcare, Financial Services, Government, Retail Solution Type: Network Security, Endpoint Protection, Data Loss Prevention, Incident Response |
| Companies Covered | International Business Machines Corporation, Cisco Systems, Inc., McAfee, LLC, FireEye, Inc., Palo Alto Networks Inc, Microsoft Corporation, Trend Micro Incorporated, Check Point Software Technologies Ltd., Broadcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Immune System Market Evolving Landscape
Behavioral analysis engines are supplanting signature-based detection as the primary threat identification mechanism, compressing the window between compromise and containment while demanding new infrastructure investments.
Agentless workload instrumentation is overtaking endpoint agent deployment as the preferred telemetry collection method for containerized and serverless environments. Cloud-native enterprises operating Kubernetes orchestration at scale are adopting eBPF-based kernel instrumentation to capture process behavior without performance degradation. This shift is overtaking traditional endpoint protection platform architectures and forcing incumbent vendors to reengineer data collection layers.
The EU NIS2 Directive expands incident reporting obligations to critical infrastructure operators beyond traditional telecom and energy sectors. Mandatory supply chain security assessments now cover managed service providers and software vendors serving European critical entities. Healthcare delivery organizations and digital infrastructure providers face compressed compliance timelines that favor pre-certified autonomous security platforms.
Security operations centers are consolidating vendor relationships around integrated platforms that unify detection, investigation, and autonomous response. Enterprise buyers are replacing point solutions with unified digital immune systems that reduce swivel-chair analysis and fragmented alert correlation. This consolidation pattern is most pronounced in United States financial services, where operational technology security teams merge with enterprise cybersecurity functions.
Digital Immune System Market Segmentation
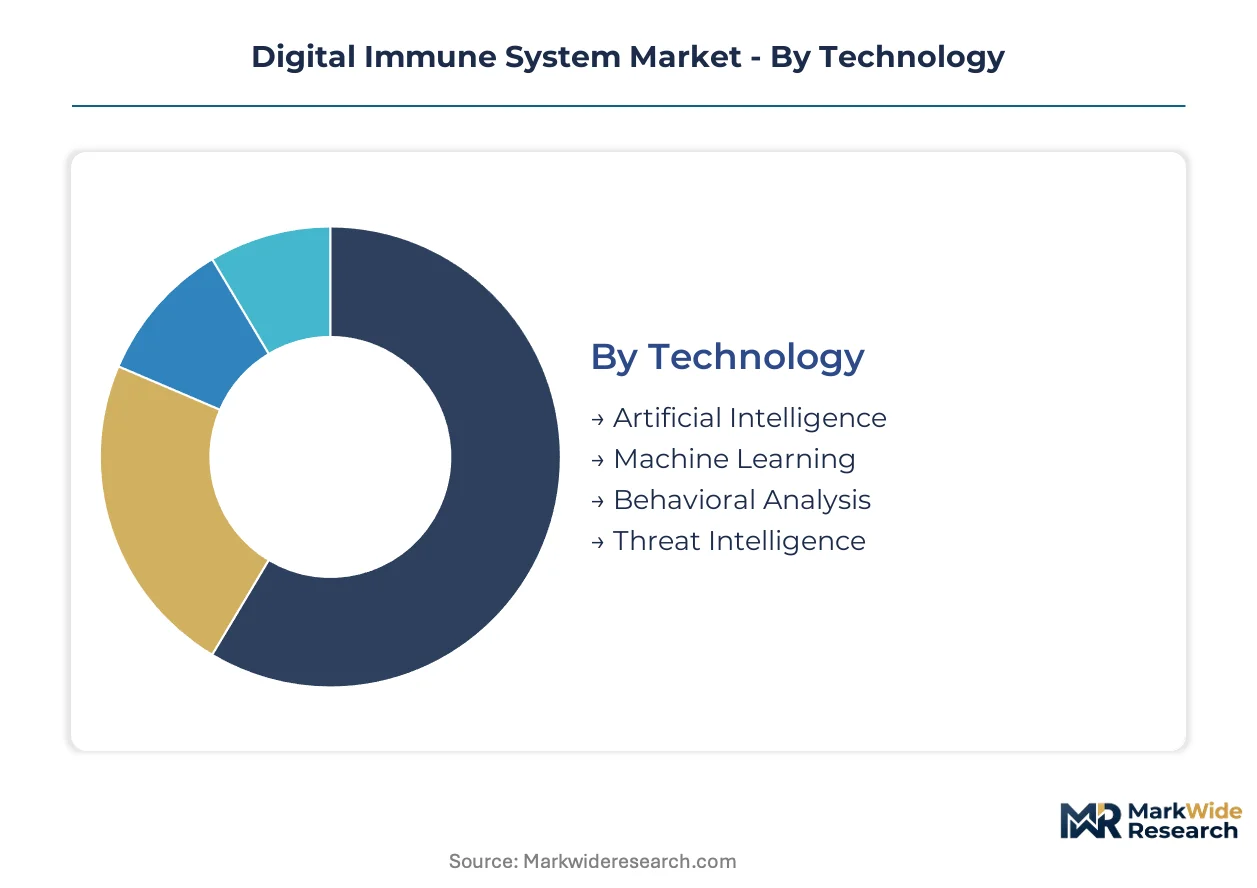
Segmentation in the digital immune system market reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and operational technology convergence. Buyers select technology stacks and deployment architectures based on latency requirements, data sovereignty constraints, and autonomous response thresholds rather than feature checklists alone.
Technology:
Chief information security officers prioritize explainability and adversarial robustness when evaluating core technology investments, particularly as EU AI Act compliance mandates reshape vendor selection criteria.
- Artificial Intelligence:Deep learning models power autonomous decision engines that execute containment actions without human approval. United States federal agencies drive procurement for AI systems meeting NIST AI Risk Management Framework standards, compressing vendor qualification timelines.
- Machine Learning:Supervised and unsupervised algorithms train on behavioral baselines to detect anomalous patterns in network traffic and endpoint activity. Financial services institutions in Frankfurt and London prioritize ML pipelines with documented model lineage for regulatory audit trails.
- Behavioral Analysis:Pattern recognition engines identify deviations from established user and entity behavior profiles. Healthcare delivery organizations deploy these systems to protect patient data repositories against insider threats and compromised credentials.
- Threat Intelligence:External data feeds and indicator-of-compromise repositories enrich detection engines with adversary tactics and infrastructure signatures. Critical infrastructure operators integrate government-sourced intelligence for nation-state threat anticipation.
Artificial Intelligence leads on scale; Behavioral Analysis leads on momentum.
Deployment Model:
Latency tolerance and data residency requirements determine architecture selection, with regulated industries accepting higher capital expenditure for localized processing capabilities.
- Cloud-based:Centralized telemetry ingestion and correlation delivered via software-as-a-service subscription models. Retail chains with distributed point-of-sale networks favor cloud deployment for rapid scaling without infrastructure capital commitment.
- On-premises:Dedicated hardware and software installations within customer-controlled data centers. Defense contractors and classified government facilities mandate on-premises deployment to satisfy air-gapped security requirements.
- Hybrid:Orchestrated workloads spanning private infrastructure and public cloud resources with unified policy enforcement. Manufacturing enterprises with operational technology environments adopt hybrid architectures to segregate IT and OT security domains.
- Edge Computing:Distributed processing nodes deployed at network peripheries to analyze telemetry before cloud transmission. Telecommunications providers building 5G infrastructure deploy edge-based immune systems to meet millisecond response thresholds for network slicing security.
Hybrid architectures capture the largest installed base; Edge Computing is climbing the fastest as 5G and industrial IoT deployments accelerate.
End User:
Sector-specific regulatory pressure and ransomware exposure intensity shape procurement urgency and budget allocation across vertical markets.
- Healthcare:Hospital systems and pharmaceutical manufacturers deploy immune systems to protect electronic health records and clinical trial data. HIPAA breach notification penalties and FDA cybersecurity guidance for medical devices accelerate security modernization programs.
- Financial Services:Banks, insurers, and payment processors represent the steepest expansion trajectory as ransomware syndicates target SWIFT networks and core banking systems. EU Digital Operational Resilience Act compliance deadlines compress procurement cycles for European institutions.
- Government:Civilian agencies and defense departments mandate zero-trust architectures with continuous verification and autonomous response capabilities. United States Executive Order 14028 directs federal agencies to prioritize self-healing infrastructure investments.
- Retail:E-commerce platforms and brick-and-mortar chains protect customer payment data and supply chain systems. PCI DSS 4.0 requirements for automated security testing expand addressable spend for integrated immune platforms.
Financial Services is gaining share fastest; Healthcare maintains the deepest installed base of legacy replacement demand.
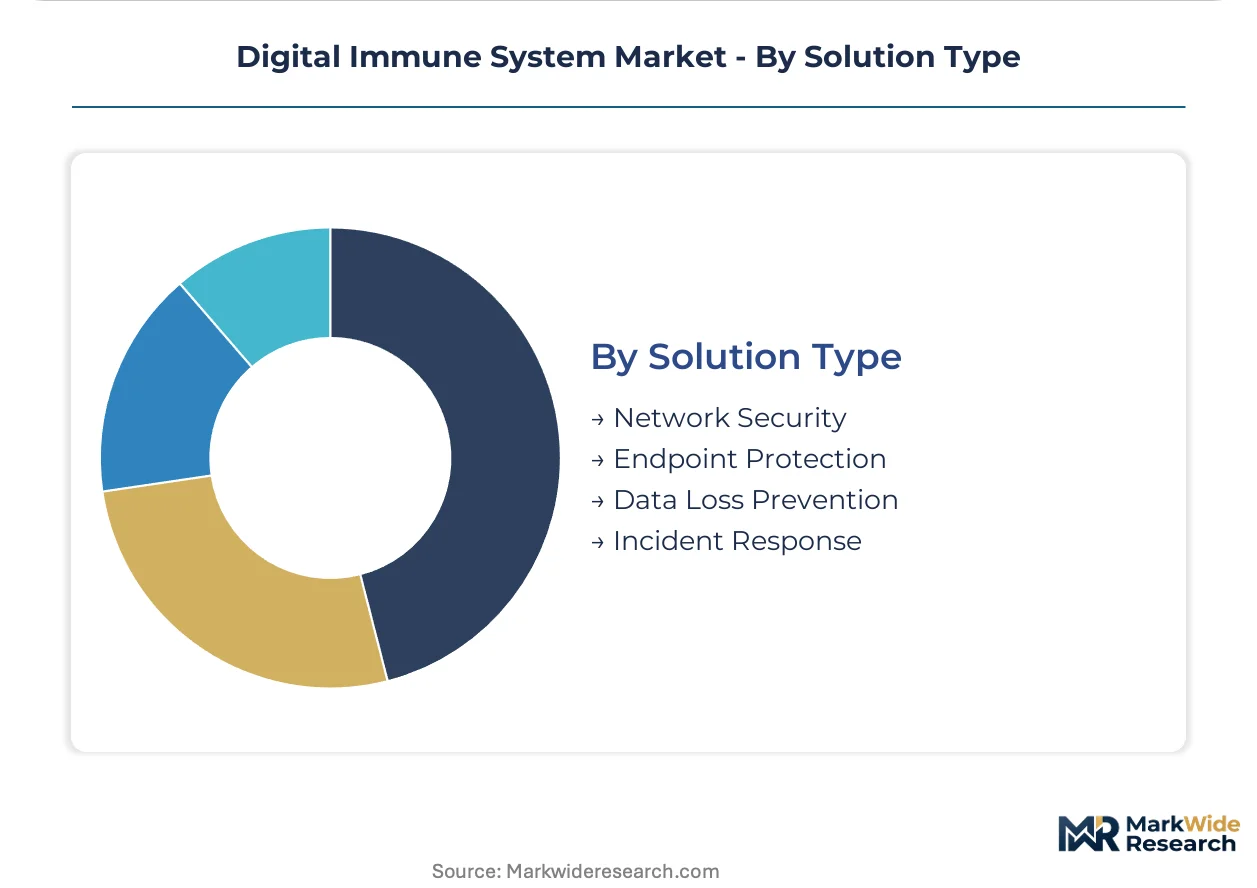
Solution Type:
Enterprise buyers consolidate point solutions into unified platforms, prioritizing autonomous response capabilities over detection-only tools that generate alert fatigue.
- Network Security:Perimeter and east-west traffic inspection with automated segmentation and threat containment. Energy sector operators deploy network-layer immune systems to protect industrial control system communications from lateral movement.
- Endpoint Protection:Device-level telemetry collection and autonomous remediation represent the most mature revenue pool. Agentless instrumentation via eBPF kernel hooks is displacing traditional agent-based deployment in cloud-native enterprises.
- Data Loss Prevention:Content inspection and exfiltration blocking with contextual policy enforcement. Professional services firms handling client intellectual property prioritize DLP integration with immune system autonomous response triggers.
- Incident Response:Automated investigation, containment, and recovery workflows without security operations center intervention. Managed security service providers build multi-tenant incident response platforms to differentiate commodity detection services.
Endpoint Protection dominates current revenue; Incident Response shows the steepest forward trajectory as autonomous containment displaces manual investigation workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal procurement centers anchor demand generation for autonomous security infrastructure, with defense contractors and civilian agencies accelerating zero-trust deployments. Regulatory pressure from Washington and Brussels is fragmenting vendor architectures between compliance regimes. Demand clusters concentrate in financial capitals and technology corridors where ransomware exposure meets stringent data sovereignty requirements.
United States
Defense contractors and civilian agencies drive procurement for self-healing infrastructure under Executive Order 14028 mandates. The SEC's cybersecurity disclosure rules expand budgets for integrated digital immune platforms among publicly traded corporations. Northern Virginia's data center corridor hosts concentrated vendor engineering operations serving federal zero-trust architectures.
Germany
Industrial control system operators in manufacturing and energy sectors prioritize autonomous containment for operational technology networks. The EU NIS2 Directive compresses compliance timelines for critical infrastructure providers beyond traditional telecom and energy boundaries. Frankfurt's financial services cluster demands explainable AI interfaces for regulatory audit trails under EU AI Act high-risk classifications.
United Kingdom
London-based banks and insurers represent steep expansion trajectories as ransomware syndicates target SWIFT networks and core banking systems. The National Cyber Security Centre guidelines shape procurement criteria for autonomous response capabilities in financial services. The Cambridge-Oxford technology corridor anchors behavioral analysis research partnerships between vendors and academic institutions.
Japan
Manufacturing enterprises with operational technology environments adopt hybrid architectures to segregate IT and OT security domains. METI cybersecurity frameworks for critical infrastructure guide vendor qualification standards for autonomous systems. Tokyo's financial district drives demand for sub-second latency incident response to protect payment clearing systems.
India
IT services exporters and digital payment platforms expand procurement for cloud-native immune systems protecting distributed workloads. The RBI's cybersecurity guidelines for banks and non-banking financial companies mandate automated threat response mechanisms. Bangalore's technology corridor concentrates vendor delivery centers serving Asia-Pacific hybrid deployment requirements.
Digital Immune System Market Competitive Landscape
Global majors compete with regional champions across platform integration depth and compliance automation breadth. The vendor base organizes around three tiers: consolidated platform providers spanning detection through autonomous response, specialized incident response automation firms, and regional system integrators with sovereign cloud partnerships. Strategic differentiation concentrates on hybrid architecture standardization and adversarial AI robustness certification. Competitive moves prioritize M&A for behavioral analysis capabilities and strategic partnerships with telecommunications providers for edge computing distribution.
Within the consolidated platform tier, Palo Alto Networks and Microsoft Corporation exemplify scale-driven positioning through security copilot investments and platform consolidation strategies. Check Point Software Technologies Ltd. occupies a specialized position representing firewall-integrated autonomous remediation approaches. These three anchors demonstrate how vendor archetypes align with divergent buyer priorities: unified management planes, AI-driven detection depth, and infrastructure-embedded response latency reduction.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Cisco Systems, Inc. |
| McAfee, LLC |
| FireEye, Inc. |
| Palo Alto Networks Inc |
| Microsoft Corporation |
| Trend Micro Incorporated |
| Check Point Software Technologies Ltd. |
| Broadcom |
| Others |
Value Network & Pricing Analysis
Federal zero-trust procurement mandates in the United States are compressing vendor qualification timelines and forcing supply chains to prioritize NIST-certified components, which elevates pricing power for qualified infrastructure providers while squeezing margins for uncertified alternatives.
Pricing Analysis
Graphics processing unit and specialized AI accelerator costs pass through directly to platform pricing, with three-tier pricing structure across premium, standard, and economy levels differentiated by explainability certification depth and sub-second latency guarantees. Pricing pressure stems from cloud hyperscaler vertical integration into security copilot offerings, which forces independent vendors toward value-based positioning. Mid-market buyers exhibit highest price sensitivity, while defense contractors and financial institutions in Frankfurt and London absorb premium tiers for regulatory audit trail capabilities.
Supply Chain Analysis
EU AI Act local-content requirements for high-risk AI systems are reshaping sourcing patterns, mandating European Union-based data processing nodes for financial services and healthcare deployments. Hardware supply concentrates in Taiwan for advanced semiconductors, South Korea for memory components, and the United States for classified government facilities requiring air-gapped infrastructure. Supply chain risk centers on single-source vulnerability for adversarial ML training datasets and behavioral analysis model development talent. Distribution runs through direct enterprise sales with managed security service provider channel partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Immune System Market functions as a geographic-arbitrage play where vendors can exploit the cost differential between United States federal procurement premiums and European Union compliance-driven specification requirements.
For Market Incumbents: Anticipate hyperscaler platform consolidation by deepening explainable AI investments that satisfy EU AI Act audit requirements while accelerating edge computing partnerships with telecommunications providers. Defensive positioning requires adversarial robustness certification ahead of standardized testing frameworks and captive supply of behavioral analysis engineering talent through targeted university partnerships. For New Entrants and Emerging Players: EU NIS2 Directive in Europe opens a window for autonomous containment specialization targeting healthcare delivery organizations and digital infrastructure providers facing compressed compliance timelines. White-space concentration sits with operational technology security in manufacturing environments, where IT-OT convergence creates procurement authority fragmentation. Go-to-market execution should anchor on managed security service provider multi-tenant platforms rather than direct enterprise sales. For Investors and Strategic Acquirers: Asymmetric upside sits with behavioral analysis engine specialists possessing documented model lineage capabilities for financial services regulatory audits. Long-term viability favors platforms with hybrid architecture standardization spanning sovereign cloud partnerships and edge computing distribution. The inflection signal to monitor is adversarial AI robustness certification adoption rates among Fortune 500 chief information security officers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies detection, investigation, and autonomous response to reduce security operations center swivel-chair analysis for financial services. |
| Strategic Partnership | Telecommunications provider alliances enable edge computing distribution for 5G network slicing security in Japan and Germany. |
| Acquisition of Specialist Firm | Behavioral analysis engine targets accelerate explainable AI roadmap compliance with EU AI Act high-risk classification mandates. |
| Geographic Expansion | European sovereign cloud partnerships address GDPR localization requirements and NIS2 Directive supply chain assessment obligations. |
| Product Launch | Agentless eBPF-based kernel instrumentation displaces traditional endpoint agents for Kubernetes-orchestrated containerized environments. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with chief information security officers, platform engineers, managed security service provider executives, and telecommunications infrastructure planners with secondary validation against SEC cybersecurity disclosure filings, NIST zero-trust architecture guidelines, EU AI Act regulatory texts, and hyperscaler security copilot investment disclosures.
Historical trendline analysis of autonomous security procurement cycles across United States federal agencies and European financial services institutions established baseline penetration patterns. The projection framework segments by deployment model, end-user vertical, solution type, and regional regulatory cluster, with CAGRs derived from elasticity modeling of compliance deadline effects and ransomware incident frequency correlations. Industry-specific forecast inputs include edge computing node deployment trajectories and adversarial ML talent pipeline constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory fragmentation scenarios or breakthrough generative AI evasion techniques. Forecasts reflect documented assumptions regarding zero-trust mandate enforcement consistency and sovereign cloud partnership availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Artificial Intelligence-Based Cybersecurity Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Canada Cybersecurity Market
Cybersecurity
Cloud Security Gateway Market
Cybersecurity
India Network Security and Cyber Risk Management Market
Cybersecurity
Global Bug Bounty Platforms Market
Cybersecurity
Cryptojacking Solution Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
France Cybersecurity Market
Cybersecurity
Big Data Security Market
Cybersecurity
Japan Cybersecurity Market
Cybersecurity
Data Center Logical Security Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
Asia Pacific IoT Security Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Israel Cybersecurity Market