
 Israel Cybersecurity Market | 2026-2036
Israel Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Cybersecurity Market Foresight
Defense procurement channels in Israel are tilting toward automated breach-and-attack simulation tools. Pentera leverages its native red-team automation to anchor government and enterprise accounts. Cato Networks competes through its cloud-native SASE architecture, extending edge security without legacy appliance sprawl. Deep Instinct differentiates by embedding deep learning inference directly on endpoints, reducing reliance on signature updates.
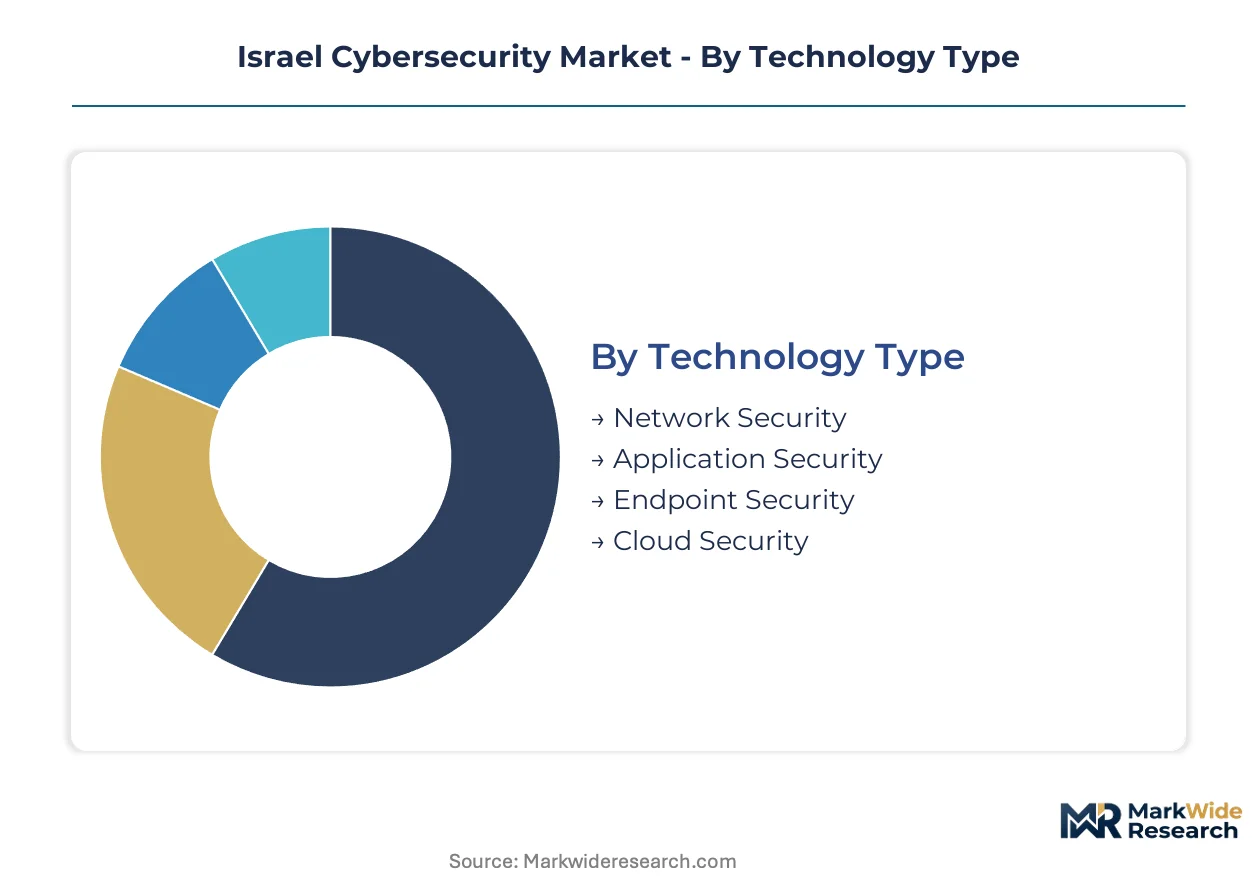
Israel cybersecurity encompasses threat prevention, detection, and response systems engineered to protect digital assets across network, application, endpoint, and cloud layers. These platforms integrate behavioral analytics, zero-trust architectures, and real-time telemetry to neutralize adversaries before lateral movement occurs. Network Security dominates procurement budgets as critical infrastructure operators harden perimeter defenses against state-sponsored intrusion. Cloud Security registers the fastest expansion trajectory, driven by Israeli SaaS startups migrating workloads to distributed environments and demanding native protection. Endpoint Security retains entrenched positions in financial services and healthcare, where device-level containment limits breach propagation.
The Israel National Cyber Directorate mandates incident reporting and baseline security standards for essential service providers, directly shaping vendor product roadmaps and customer procurement criteria. ISO 27001 and NIST frameworks supplement local regulation, filtering market access for foreign suppliers seeking Israeli public-sector contracts. Stakeholders must monitor how the Directorate's evolving critical infrastructure designations expand compliance obligations beyond energy and finance into telecommunications and healthcare delivery networks.
Market Dynamics
The Israel National Cyber Directorate's mandatory incident reporting rules are compressing vendor compliance cycles and forcing product architecture redesigns across the domestic supplier base.
Growth Catalysts
- Critical Infrastructure Mandates:The National Cyber Directorate's tightened reporting timelines for energy and finance operators are expanding procurement budgets for automated detection platforms.
- Military Technology Spin-offs:Tel Aviv's metropolitan corridor concentrates venture capital and defense alumni founding commercial cybersecurity ventures.
- Cloud Migration Acceleration:Israeli SaaS startups are demanding native cloud security, pulling spending from perimeter appliances toward distributed protection architectures.
Market Restraints
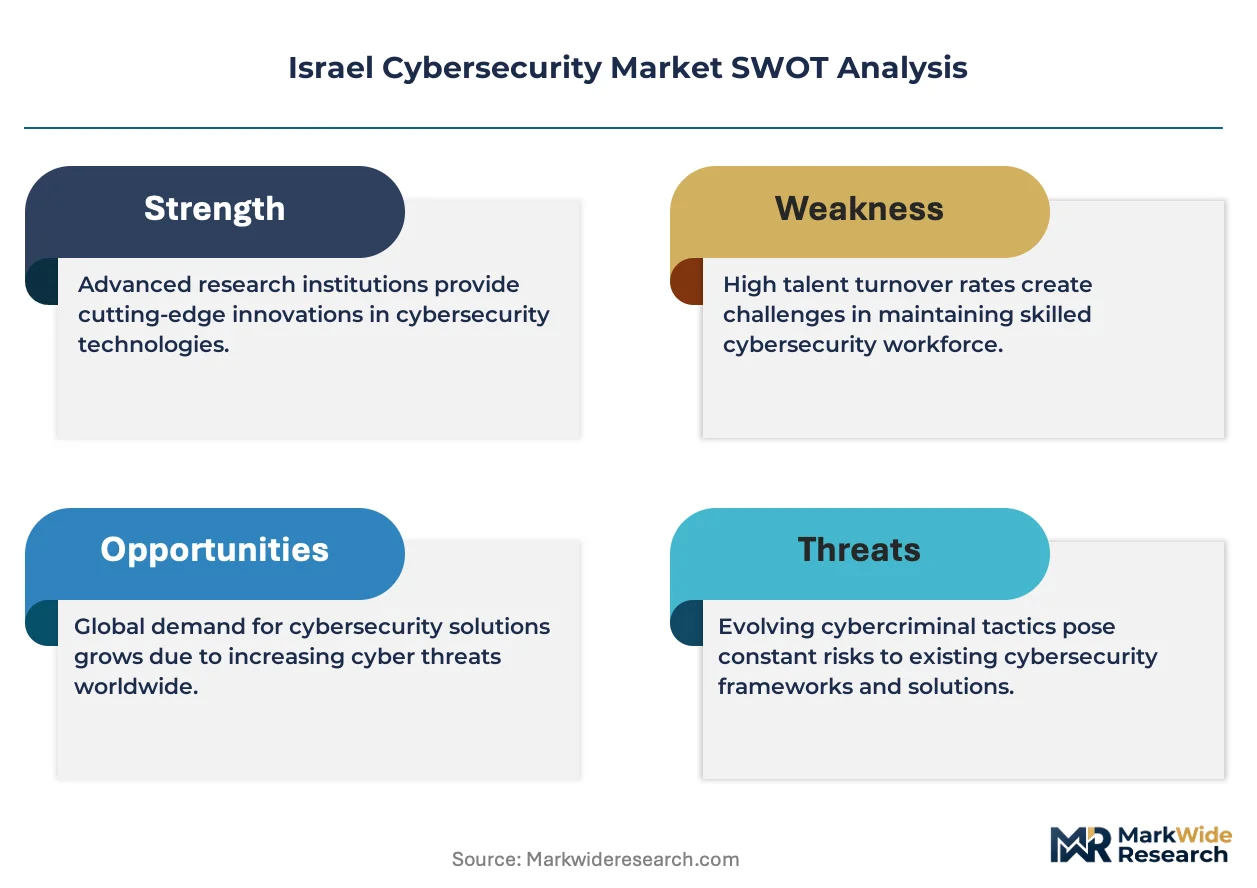
- Specialized Talent Scarcity:Deep learning and adversarial AI expertise concentrates in military units and select academic programs, limiting commercial workforce expansion.
- Input Cost Concentration:Advanced GPU clusters for training behavioral models face supply constraints from Taiwan-based foundries, inflating R&D overhead for domestic vendors.
- Regulatory Friction:ISO 27001 and NIST framework requirements filter foreign supplier access to Israeli public-sector contracts, narrowing competitive pressure.
Strategic Opportunities
- Healthcare Network Expansion:The National Cyber Directorate's evolving critical infrastructure designations are extending compliance obligations into medical delivery networks, opening new vertical demand.
- Telecommunications Hardening:5G core network deployments create attack surfaces requiring real-time threat neutralization before lateral movement.
- Behavioral Analytics Convergence:Endpoint detection and network telemetry fusion enables pre-breach intervention, reducing mean-time-to-containment for enterprise buyers.
Industry Challenges
- Adversarial AI Skill Gap:Red-team automation and generative attack simulation require expertise rarely found outside Unit 8200 alumni networks, constraining vendor scaling.
- Legacy Architecture Integration:Financial services incumbents operate hybrid on-premise and cloud estates, complicating zero-trust rollout timelines and increasing deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Cybersecurity Market |
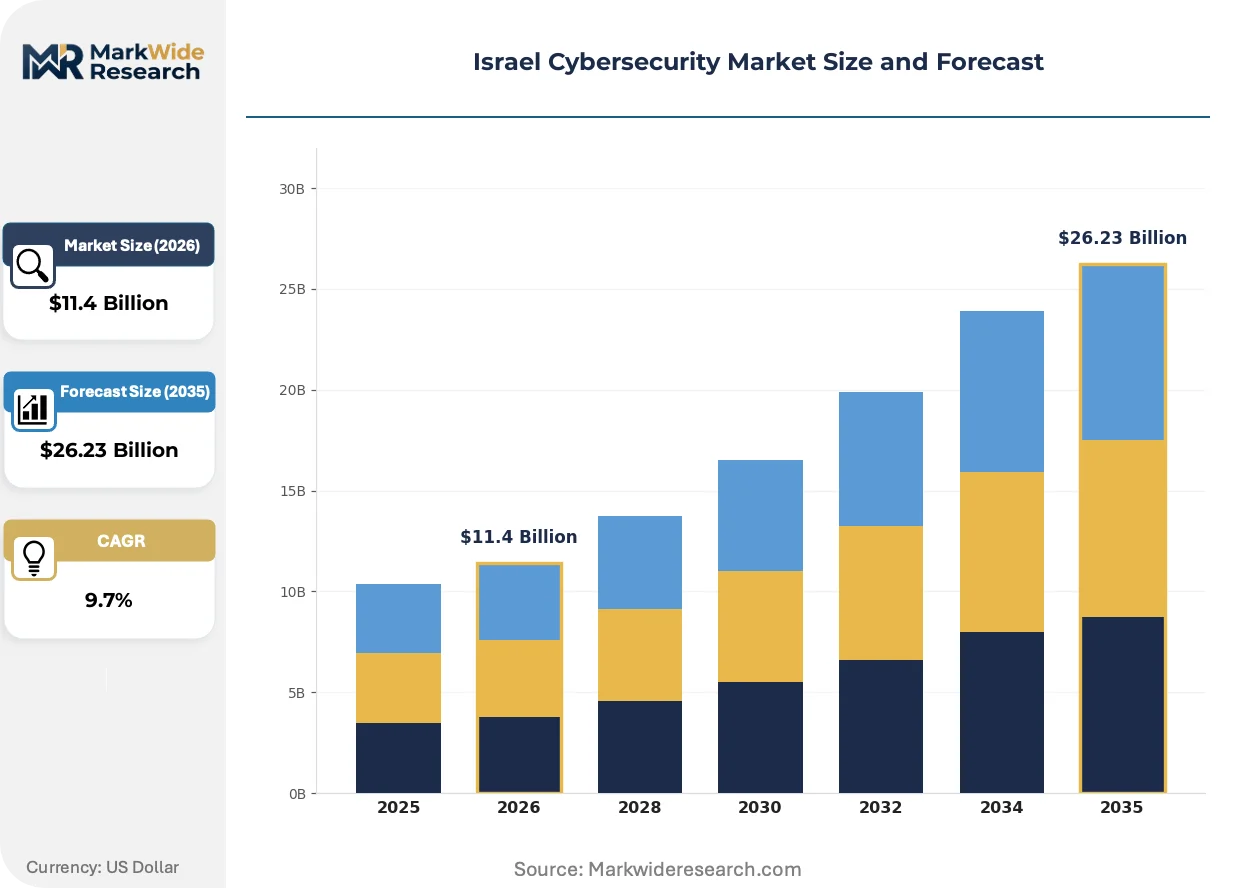
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.23 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Network Security, Application Security, Endpoint Security, Cloud Security End User: Government, Financial Services, Healthcare, Telecommunications Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services Service Type: Consulting, Integration, Support, Training |
| Companies Covered | Pentera, Sygnia, Cato Networks, XM Cyber, Zero Networks, Deep Instinct, Checkmarx, Cynet, Forter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Cybersecurity Market Shifts & Advancements
Behavioral inference engines and autonomous response systems are displacing signature-dependent tools across Israeli enterprise and government deployments.
Deep learning-based endpoint protection is hybridizing deterministic and probabilistic detection methods. Financial services and healthcare providers are adopting these platforms fastest, replacing daily signature updates with pretrained neural models. This convergence is compressing vendor differentiation around inference speed rather than threat database breadth.
The National Cyber Directorate's evolving baseline security standards are mandating automated breach simulation for critical infrastructure operators. Vendors must embed continuous validation into product roadmaps or lose eligibility for government procurement. Energy and water utilities face the steepest compliance curves, driving demand for native red-team automation.
Enterprise buyers are consolidating vendor relationships around integrated platforms rather than point solutions. CISOs at major Israeli banks and insurers now prioritize single-pane telemetry across endpoint, network, and cloud layers. This preference shift favors architecture-native providers over appliance-heavy legacy stacks, most visible in Tel Aviv's venture-backed SaaS sector procurement patterns.
Israel Cybersecurity Market Segmentation
Israeli cybersecurity procurement follows distinct technology maturity curves and regulatory pressure gradients. Understanding segment boundaries reveals where compliance mandates concentrate spending and where architectural shifts open vendor repositioning opportunities.
Technology Type:
Mature perimeter defenses coexist with emerging cloud-native architectures across Israeli enterprise deployments.
- Network Security:Firewalls, intrusion detection systems, and secure access service edge platforms protect traffic flows at organizational boundaries. Critical infrastructure operators in Tel Aviv's metropolitan corridor allocate the largest procurement budgets here due to National Cyber Directorate mandates for energy and finance sectors.
- Cloud Security:Native workload protection, container security, and cloud access security broker platforms secure distributed SaaS environments. Israeli venture-backed startups migrating from on-premise estates drive demand concentration, pulling spending from hardware appliances toward API-integrated controls.
- Application Security:Static and dynamic testing tools, runtime application self-protection, and software composition analysis secure code pipelines.
- Endpoint Security:Device-level detection, response automation, and zero-trust access enforcement protect workstations and mobile assets.
Network Security retains volume leadership; Cloud Security holds the steepest expansion curve.
End User:
Regulatory exposure varies sharply across buyer categories, with compliance timelines dictating procurement urgency.
- Government:Defense procurement channels and civilian agency networks absorb autonomous threat-detection platforms with mandatory breach simulation requirements. The National Cyber Directorate's tightened reporting rules compress vendor compliance cycles for this buyer class.
- Financial Services:Banks, insurers, and payment processors operate hybrid estates complicating zero-trust rollouts. CISOs at major Israeli institutions prioritize single-pane telemetry across endpoint, network, and cloud layers.
- Healthcare:Medical delivery networks face evolving critical infrastructure designations extending compliance obligations beyond traditional HIPAA-style privacy into operational technology security.
- Telecommunications:5G core network deployments create attack surfaces requiring real-time neutralization before lateral movement across subscriber data and signaling infrastructure.
Financial Services commands the largest absolute spending; Healthcare is climbing the fastest as regulatory designations expand.
Deployment Model:
Cost-to-control tradeoffs shape architecture choices, with labor scarcity pushing buyers toward externalized operations.
- On-Premise:Hardware appliances and self-managed software stacks within organizational data centers. Legacy financial services incumbents maintain substantial on-premise footprints, though new procurement tilts toward cloud alternatives.
- Managed Services:Outsourced security operations centers and managed detection and response functions. Deep learning and adversarial AI expertise concentrates in military units and select academic programs, making external talent acquisition attractive for commercial buyers lacking Unit 8200 alumni networks.
- Cloud-Based:Fully externalized control planes with no local infrastructure ownership.
- Hybrid:Split workloads across on-premise and cloud environments with unified policy enforcement.
On-Premise retains installed base dominance; Managed Services is expanding most quickly amid specialized talent scarcity.
Service Type:
Customer lifecycle positioning determines margin capture, with upstream advisory commanding premium pricing.
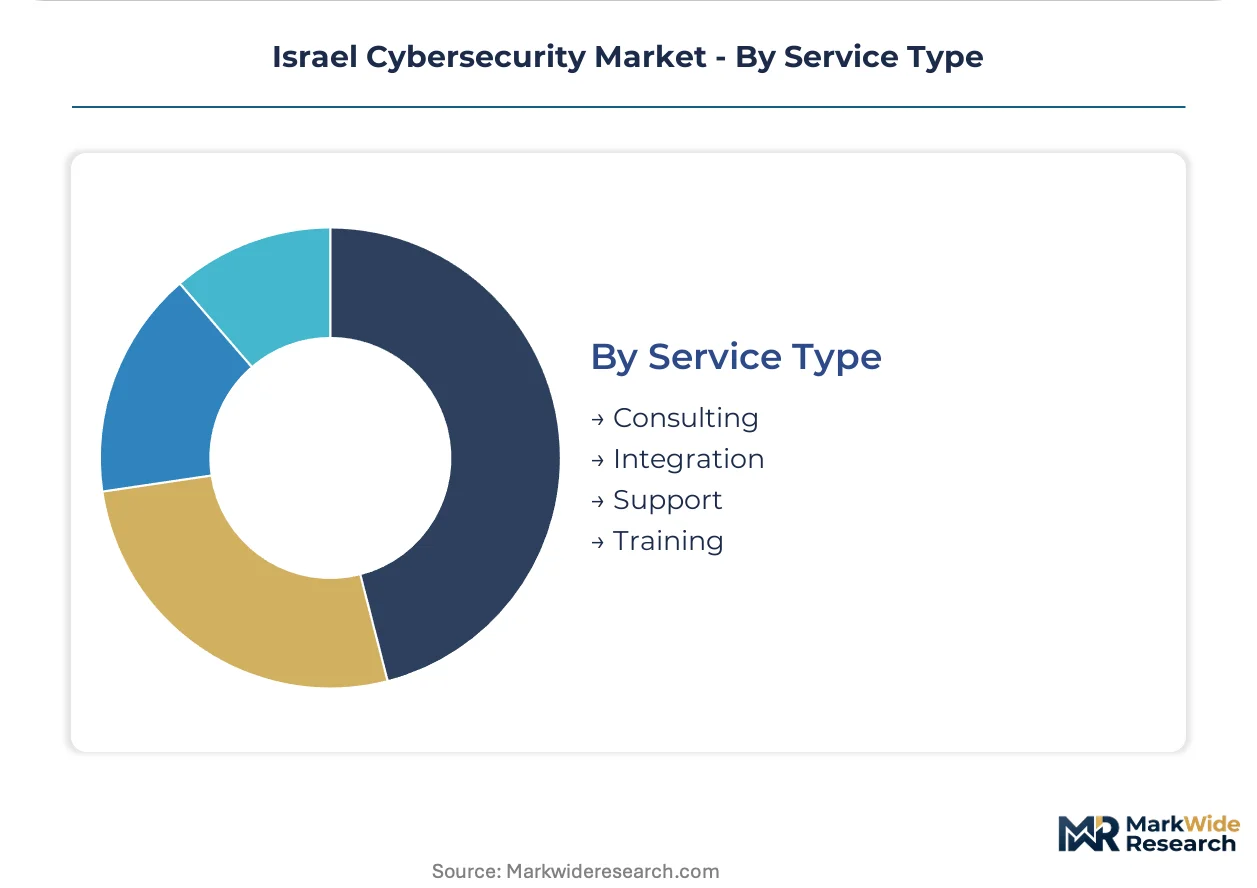
- Consulting:Risk assessment, architecture design, and compliance readiness services. ISO 27001 and NIST framework requirements filter foreign supplier access to Israeli public-sector contracts, creating protected demand for domestic advisory practices.
- Integration:Deployment engineering, legacy migration, and multi-vendor orchestration. Behavioral analytics convergence across endpoint detection and network telemetry requires sophisticated integration work for pre-breach intervention capabilities.
- Support:Break-fix maintenance, patch management, and technical assistance.
- Training:Workforce certification, red-team skill development, and security awareness programs.
Consulting captures the highest margins; Integration is gaining share fastest as architectural complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Israel National Cyber Directorate anchors regulatory pressure across the domestic market. Mandatory incident reporting rules compress compliance timelines for critical infrastructure operators. Venture capital clusters in Tel Aviv concentrate military spin-off formation.
Tel Aviv Metropolitan Corridor
Defense procurement channels and venture capital overlap drives autonomous threat-detection platform development. The National Cyber Directorate's tightened reporting rules apply most stringently to energy and finance operators headquartered here. Tel Aviv's Rothschild Boulevard corridor hosts the densest concentration of Unit 8200 alumni-founded cybersecurity ventures.
Jerusalem
Government agency networks and defense ministry facilities generate demand for breach-and-attack simulation tools. The National Cyber Directorate coordinates baseline security standards from offices in the capital. Jerusalem's technology park near Har Hotzvim incubates startups serving public-sector procurement channels.
Haifa
Industrial control system security demand concentrates around petrochemical and port infrastructure. The National Cyber Directorate's critical infrastructure designations include Haifa's energy and water utilities. The Matam technology park houses R&D centers developing operational technology protection for heavy industry.
Beer Sheva
CyberSpark technology park and Ben-Gurion University anchor southern Israel's cybersecurity ecosystem. The Israel Defense Forces' technology units maintain presence here, feeding talent pipelines into commercial ventures. Beer Sheva's desert location supports secure data center and testing facility operations.
Herzliya Pituach
Multinational corporate R&D centers and Israeli headquarters for global technology firms cluster in this coastal business district. Financial services cybersecurity procurement concentrates among banks and insurers maintaining offices here. Herzliya's marina district hosts venture capital firms funding Series A and B cybersecurity rounds.
Israel Cybersecurity Market Competitive Landscape
Autonomous red-team specialists and cloud-native platform providers split the market between offense-simulation and perimeter-less architectures. The vendor base concentrates in Tel Aviv's metropolitan corridor with limited geographic dispersion. Three strategic archetypes dominate: military spin-offs with Unit 8200 pedigree, venture-backed SaaS scale-ups, and integrated platform consolidators. Competitive moves center on embedding continuous validation into product roadmaps and consolidating point solutions into unified telemetry layers.
Within the autonomous breach-simulation tier, Pentera and XM Cyber exemplify red-team automation anchored to government procurement eligibility. Cloud-native specialists include Cato Networks, which occupies a position representing distributed edge protection without legacy appliance dependencies. Deep Instinct sits within the deep learning tier, anchoring endpoint protection through pretrained neural models rather than signature-dependent approaches. These three archetypes illustrate how compliance mandates and architectural shifts reshape vendor positioning.
| Leading Market Players |
|---|
| Pentera |
| Sygnia |
| Cato Networks |
| XM Cyber |
| Zero Networks |
| Deep Instinct |
| Checkmarx |
| Cynet |
| Forter |
| Others |
Supply & Pricing Matrix
Tel Aviv's metropolitan corridor concentrates venture capital and defense alumni talent, creating supply-side scarcity that elevates pricing power for Unit 8200-linked vendors serving government procurement channels. This geographic clustering compresses talent acquisition costs for established players while forcing price premiums for buyers lacking direct military pipeline access.
Pricing Analysis
Subscription-based SaaS tiers dominate Israeli cybersecurity procurement, with pricing stratifying across enterprise, mid-market, and government levels. Certification under the National Cyber Directorate's baseline standards and ISO 27001 compliance tiers drive substantial price differentiation between eligible and non-eligible vendors. Pricing pressure stems from cloud-native competitors reducing deployment friction and compressing implementation margins. Mid-market financial services buyers exhibit highest price sensitivity due to hybrid estate complexity, while defense procurement channels show lowest sensitivity given mandate-driven urgency.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard practice as Israeli vendors navigate Taiwan-based GPU foundry dependencies for training behavioral models. Advanced semiconductor components and specialized cloud compute instances draw from concentrated sources in Taiwan, South Korea, and the United States. Single-source vulnerability around NVIDIA's data center GPU allocation creates procurement bottlenecks for deep learning vendors. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations, with managed security service providers gaining channel share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's cybersecurity market functions as a regulatory-moat arena where National Cyber Directorate eligibility creates entrenched switching costs for incumbent vendors. This structural advantage compounds through mandatory breach-simulation requirements that embed vendors deeply into critical infrastructure operator workflows.
For Market Incumbents: Pre-empt cloud-native displacement by embedding continuous validation capabilities into existing platform architectures before Cato Networks-style SASE competitors capture hybrid estate budgets. Acquire adversarial AI talent from Unit 8200 alumni networks to maintain red-team automation leadership against XM Cyber challengers. Prioritize healthcare network expansion as the Directorate extends critical infrastructure designations beyond energy and finance. For New Entrants and Emerging Players: Build out managed detection and response offerings targeting mid-market financial services incumbents struggling with hybrid on-premise and cloud complexity. Telecommunications 5G security presents the most penetrable vertical given real-time neutralization requirements that legacy perimeter vendors cannot satisfy. Lead with API-integrated controls rather than appliance-heavy deployments to bypass established vendor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because enterprise buyers are consolidating vendor relationships around integrated platforms rather than point solutions. Target acquisition archetypes include deep learning endpoint specialists with pretrained neural model differentiation and autonomous red-team automation vendors holding Directorate procurement eligibility. Watch for National Cyber Directorate designations expanding into medical delivery networks as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Validation Integration | Embedding breach simulation satisfies National Cyber Directorate procurement eligibility requirements. |
| Deep Learning Talent Acquisition | Unit 8200 alumni recruitment secures adversarial AI capabilities competitors cannot replicate. |
| Healthcare Network Expansion | Critical infrastructure designation extension opens compliance-driven demand in medical delivery. |
| Cloud-Native SASE Architecture | Distributed edge protection captures SaaS startup migration without legacy appliance dependencies. |
| Behavioral Analytics Convergence | Endpoint-network telemetry fusion enables pre-breach intervention for enterprise consolidation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with CISOs at Israeli banks and insurers, National Cyber Directorate compliance officers, venture capital partners funding Series A cybersecurity rounds, and managed security service provider technical directors. Secondary validation drew from SEC filings of Israeli cybersecurity vendors, hyperscaler marketplace transaction disclosures, Directorate procurement eligibility databases, and ISO 27001 certification registries. Bottom-up segment sizing triangulated against top-down market aggregation across the analysis window.
Calibration anchored projections to observed procurement velocity in energy and finance verticals under tightened reporting mandates. Segmentation dimensions modeled include technology type, end user vertical, deployment model, and service type alongside integration complexity tiers. CAGRs were derived from regression analysis of historical spending patterns and forward-looking compliance obligation expansion. Forecast inputs incorporated GPU supply constraints from Taiwan foundries and military talent pipeline throughput rates.
The forecast holds incumbent behavior within observed patterns; aggressive platform consolidation moves by cloud-native challengers would shift outcomes beyond projected ranges. Macroeconomic contraction in venture capital availability, regulatory relaxation of mandatory reporting timelines, or breakthrough adversarial AI capabilities from non-Israeli competitors would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Content Delivery Network (CDN) Security Market
Cybersecurity
Cryptojacking Solution Market
Cybersecurity
Cyber Security and Big Data Analytics Market
Cybersecurity
Cyber Security in Energy Market
Cybersecurity
China Ransomware Protection Market
Cybersecurity
Smart Grid Cyber Security Market
Cybersecurity
Cyber Security As a Service Market
Cybersecurity
Cognitive Security Market
Cybersecurity
Thailand Cybersecurity Market
Cybersecurity
Canada Cybersecurity Market
Cybersecurity
M2M Network Security Market
Cybersecurity
5G Security Market
Cybersecurity
Cloud-Based IDS IPS Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
ASEAN Cyber Security Market
Cybersecurity
Managed SIEM Service Market