
 India Network Security and Cyber Risk Management Market | 2026-2036
India Network Security and Cyber Risk Management Market Size, Share, and Industry Trends Forecast 2026-2036
India Network Security and Cyber Risk Management Market Insights
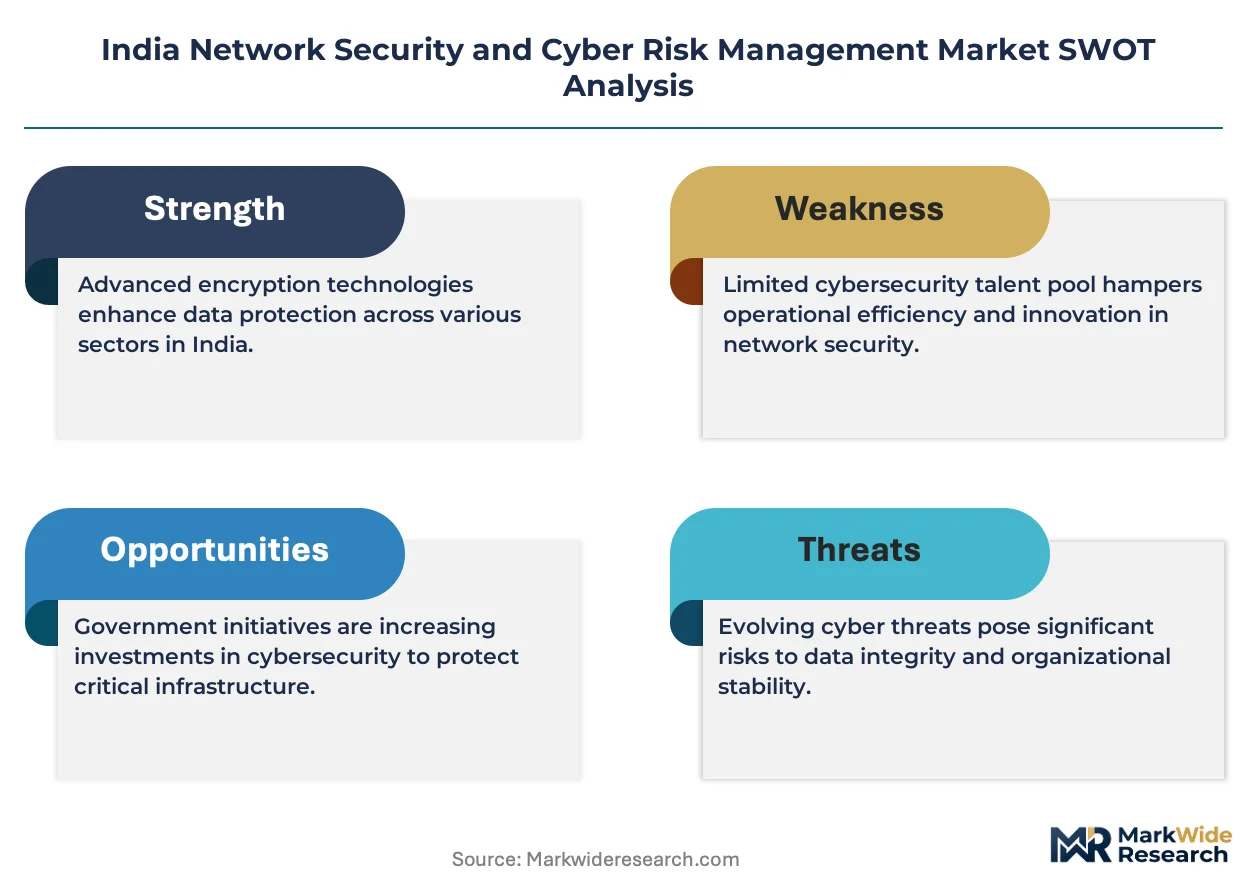
ISO 27001 certification cycles for managed security service providers is unwinding competitive access across India's enterprise segment. Palo Alto Networks sustains technology leadership in next-generation firewall architectures tailored for cloud migration patterns. Tata Consultancy Services anchors its position through captive delivery of incident response and managed detection services. Quick Heal Technologies specializes in endpoint security priced for India's mid-market manufacturing and government verticals.
Network security and cyber risk management encompasses hardware, software, and service layers engineered to protect data integrity, confidentiality, and availability across interconnected systems through packet inspection, behavioral analytics, and encryption protocols operating at throughput rates exceeding 100 Gbps. The discipline serves critical infrastructure, financial networks, and government communications by intercepting unauthorized access, containing lateral movement, and ensuring regulatory audit trails. Firewall and IDS/IPS solutions occupy mature margin pools where hardware refresh cycles and AI-enhanced threat detection command premium pricing. Cloud-based and hybrid deployment models represent the fastest-expanding architecture category as RBI-mandated data localization pushes financial institutions toward sovereign cloud configurations. Managed services within the service type dimension capture recurring revenue streams as skills scarcity drives outsourcing of 24/7 security operations center functions.
CERT-In directives, RBI cybersecurity guidelines for urban cooperative banks, and BIS information security standards collectively mandate incident reporting timelines, baseline control frameworks, and third-party audit obligations that shape procurement specifications. These regulatory instruments force product redesign toward automated compliance dashboards and localized data processing architectures. Stakeholders must monitor evolving PLI scheme incentives for domestic semiconductor and security hardware manufacturing that could reshape vendor economics and supply chain sourcing decisions.
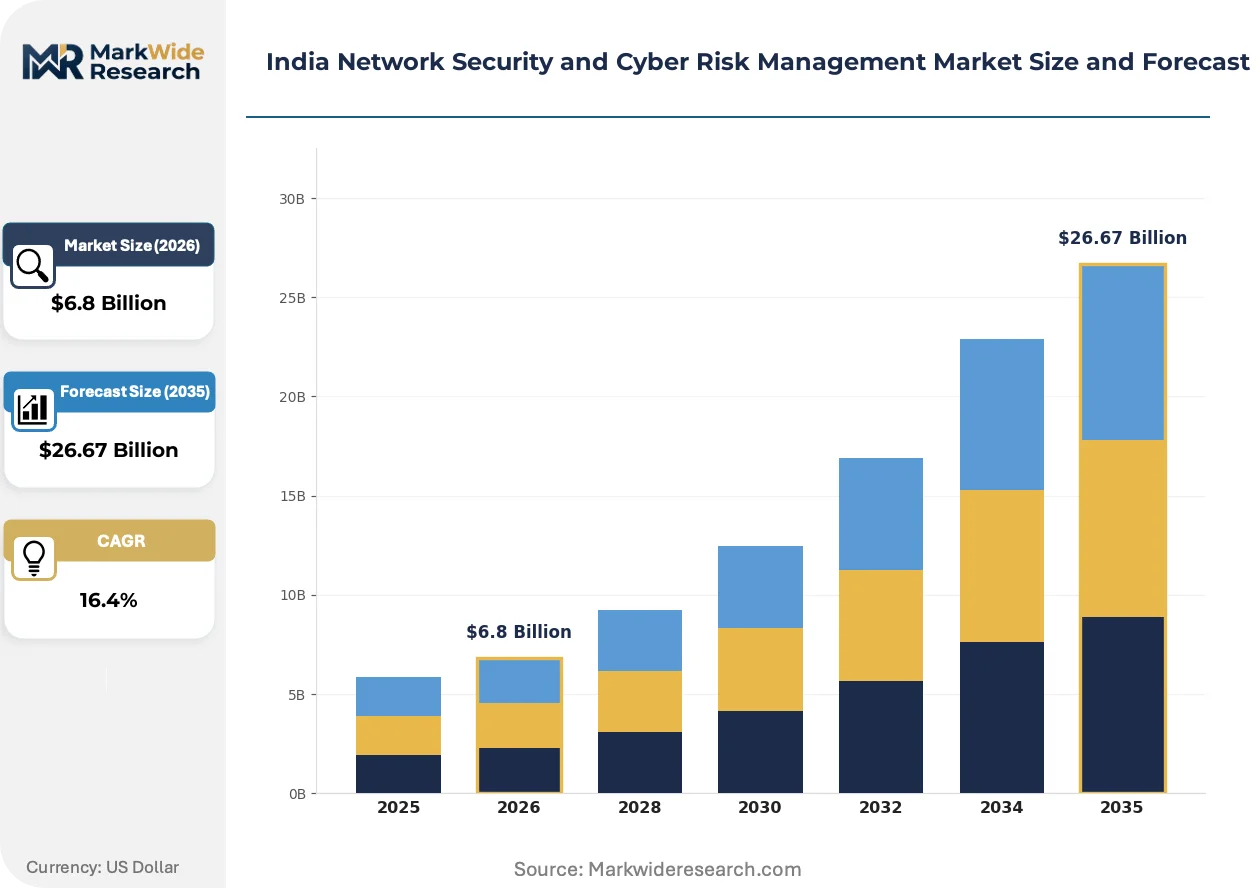
Market Dynamics
RBI-mandated data localization and CERT-In incident reporting timelines are compressing procurement cycles for sovereign cloud security architectures across Indian financial institutions.
Growth Catalysts
- CERT-In Directives:Mandatory incident reporting within six hours for critical infrastructure operators is forcing automated security orchestration deployments across banking and telecom networks.
- Urban Cooperative Banks:RBI cybersecurity guidelines issued for this segment are unlocking compliance-driven procurement of managed detection and response services in tier-2 and tier-3 cities.
- PLI Scheme Incentives:Production-linked incentives for domestic semiconductor and security hardware manufacturing are redirecting vendor sourcing toward indigenous firewall and encryption appliance production.
Market Restraints
- Skills Scarcity:Certified security operations center analysts command premium wages that inflate managed service delivery costs beyond mid-market enterprise budgets.
- Import Dependency:Specialized packet inspection chipsets and high-throughput encryption processors concentrate supply with Taiwan and South Korea foundries, exposing vendors to geopolitical disruption.
- Legacy Infrastructure:Decades-old core banking systems in public sector banks resist API-native security integration, forcing expensive middleware layers.
Strategic Opportunities
- MSME Segment:Underpenetrated manufacturing clusters in Gujarat and Tamil Nadu lack dedicated security operations, creating white space for modular, pay-as-you-grow managed services.
- Convergence of AI and Zero Trust:Behavioral analytics engines combined with microsegmentation architectures enable real-time threat containment without perimeter-dependent appliances.
- State Data Centers:MeitY's cloud infrastructure expansion into Rajasthan and Uttar Pradesh creates sovereign hosting demand requiring localized threat monitoring capabilities.
Industry Challenges
- Certification Bottlenecks:ISO 27001 and RBI cyber audit compliance timelines stretch 12-18 months, delaying product launches and service rollouts for new market entrants.
- Integration Complexity:Hybrid cloud deployments require seamless policy orchestration between on-premise firewalls, sovereign cloud instances, and SaaS security controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Network Security and Cyber Risk Management Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Firewall, IDS/IPS, VPN, Anti-Virus Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed End User: Government, BFSI, Healthcare, Manufacturing Service Type: Consulting, Training, Incident Response, Managed Services |
| Companies Covered | Cisco Systems, Palo Alto Networks, IBM Corporation, Tata Consultancy Services, Check Point Software Technologies, Trend Micro, Quick Heal Technologies, Fortinet, Infosys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Network Security and Cyber Risk Management Market Trends and Innovations
Agentless workload protection and AI-augmented threat hunting are compressing the traditional managed security service delivery model across Indian enterprise buyers.
Agentless cloud workload protection platforms are displacing agent-based endpoint detection across containerized financial applications. Large private banks in Mumbai and Bengaluru are piloting these architectures for microservices environments. This shift is displacing legacy antivirus licensing models that dominated enterprise procurement through 2023.
RBI's data localization guidelines for payment system operators are mandating in-country processing of transaction logs and audit trails. Cloud service providers are rearchitecting multi-tenant platforms to satisfy these requirements. Urban cooperative banks in Maharashtra and Karnataka face the steepest compliance deadlines and are accelerating sovereign cloud migrations.
Outcome-based security service contracts tied to mean-time-to-detect metrics are replacing seat-based pricing in enterprise procurement. Manufacturing conglomerates in Tamil Nadu and pharmaceutical clusters in Telangana are demanding performance guarantees from managed security providers. This purchasing pattern is most visible in long-term outsourcing agreements where internal security operations center buildouts failed.
India Network Security and Cyber Risk Management Market Segmentation
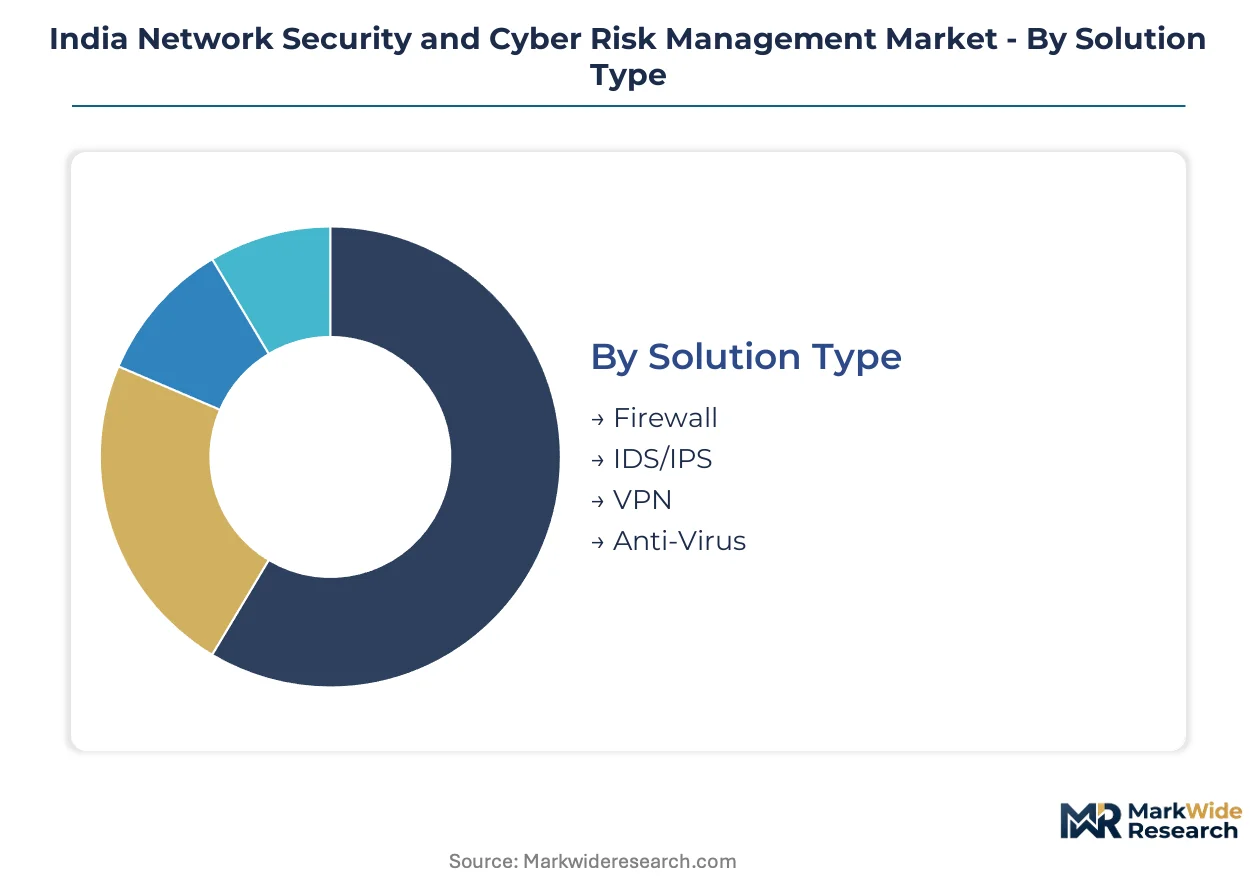
Segmentation in India's network security market reveals how regulatory pressure and infrastructure maturity create divergent procurement patterns across solution architectures and buyer types. Understanding these divides exposes where vendors can capture premium pricing versus competing on volume.
Solution Type:
Margin pools concentrate in AI-enhanced inspection engines where throughput specifications above 100 Gbps command hardware refresh premiums, while commoditized signature-based tools face pricing compression from open-source alternatives.
- Firewall:Next-generation architectures with integrated application awareness and SSL decryption capabilities dominate enterprise procurement in Mumbai and Bengaluru data centers. RBI-mandated data localization pushes financial institutions toward sovereign cloud-optimized firewall instances that maintain policy consistency across hybrid estates.
- IDS/IPS:Behavioral analytics engines processing netflow telemetry at carrier-grade scale anchor critical infrastructure deployments. Telecom operators in Maharashtra and Karnataka are replacing signature-only systems with machine learning-augmented intrusion detection to meet CERT-In's six-hour incident reporting windows.
- VPN:Zero-trust network access replacements are displacing legacy IPsec concentrators in government remote access programs.
- Anti-Virus:Endpoint detection and response bundles are eroding standalone antivirus licensing in mid-market manufacturing clusters.
Firewall holds installed capacity. IDS/IPS is rotating up the share rankings.
Deployment Model:
Customer type determines architecture selection, with regulated financial institutions prioritizing sovereign control while cost-constrained manufacturers favor operational expenditure models.
- Cloud-Based:Multi-tenant security service edge platforms deliver elastic capacity for fintech scale-ups in Bengaluru's Koramangala and HSR Layout corridors. RBI data localization guidelines force these architectures toward in-country points of presence, creating infrastructure partnerships between global vendors and domestic telecom carriers.
- Hybrid:Policy orchestration layers synchronizing on-premise firewalls with sovereign cloud instances address the dominant architecture challenge facing public sector banks with decades-old core systems. Tamil Nadu's manufacturing conglomerates are piloting these configurations to segment operational technology networks from enterprise IT.
- On-Premises:Air-gapped deployments persist in defense and nuclear facilities with classified network requirements.
- Managed:Twenty-four by seven security operations center functions delivered under subscription contracts unlock compliance for urban cooperative banks lacking internal analyst benches.
On-Premises retains legacy footprint. Cloud-Based is climbing the fastest.
End User:
Application criticality shapes security spending intensity, with payment system operators and critical infrastructure operators facing mandatory control frameworks that smaller manufacturers escape.
- BFSI:Payment aggregators and small finance banks in Maharashtra face the steepest CERT-In compliance deadlines, driving automated security orchestration procurement. Private sector banks in Mumbai's Bandra-Kurla Complex are consolidating vendor relationships around integrated platforms that reduce integration tax across firewall, identity, and endpoint layers.
- Government:State data center expansions in Rajasthan and Uttar Pradesh under MeitY's cloud infrastructure program create sovereign hosting demand requiring localized threat monitoring. National critical information infrastructure protection mandates force central ministries toward certified managed security service providers with domestic delivery centers.
- Healthcare:Hospital information system vendors are embedding encryption modules to address patient data protection requirements.
- Manufacturing:Gujarat's automotive component suppliers and Tamil Nadu's textile exporters lack dedicated security operations, creating white space for modular managed services.
BFSI commands premium pricing. Government is gaining share fastest.
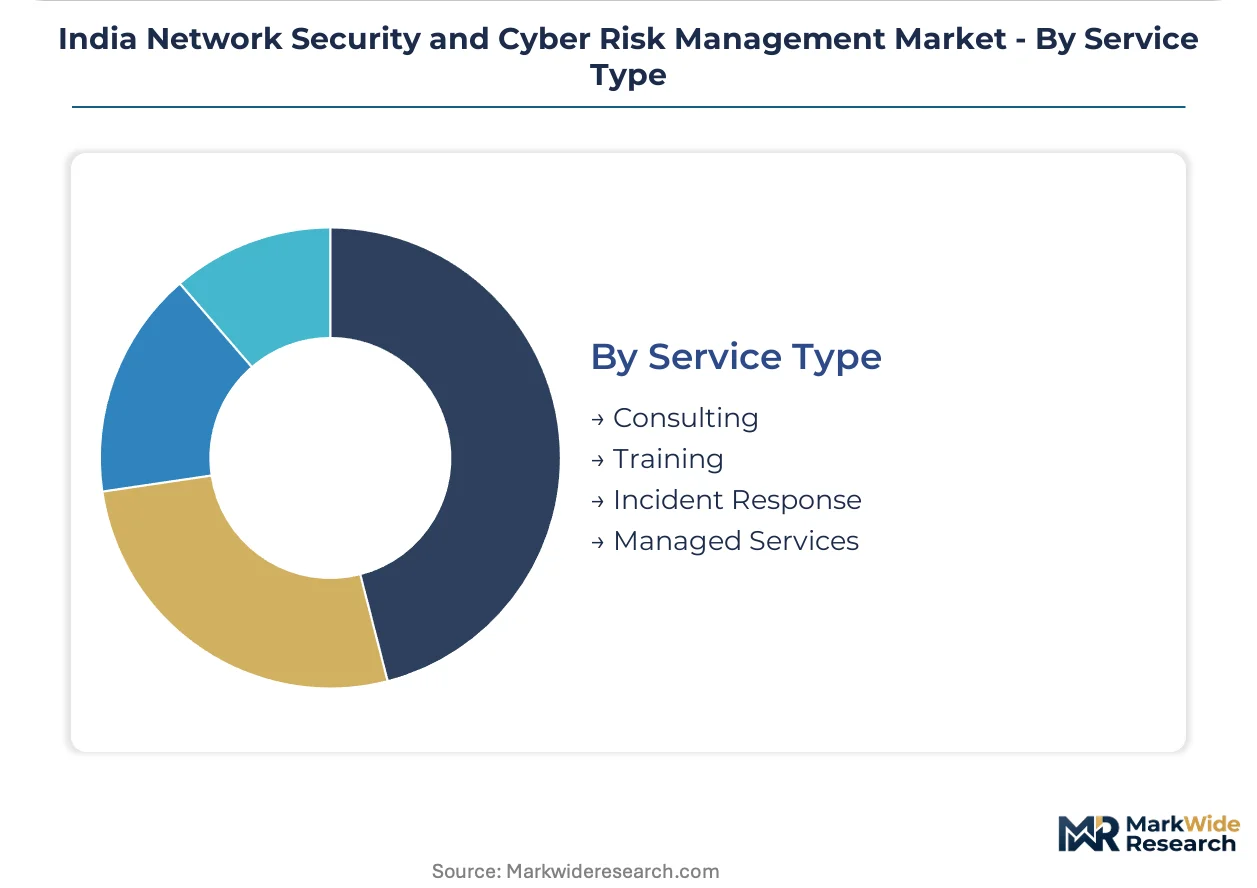
Service Type:
Maturity gradients separate established compliance advisory from emerging outcome-based contracting models where vendors assume detection performance risk.
- Managed Services:Twenty-four by seven security operations center functions delivered from captive Indian delivery centers anchor recurring revenue streams for IT services majors. Skills scarcity for certified SOC analysts inflates delivery costs, pushing mid-market enterprises toward co-managed models where internal staff retain tier-one triage.
- Incident Response:Retainer contracts with guaranteed response time service level agreements are replacing hourly consulting arrangements among pharmaceutical clusters in Telangana and Hyderabad's Genome Valley. These contracts specify mean-time-to-contain metrics that align vendor compensation with operational outcomes.
- Consulting:RBI cyber audit preparation and CERT-In compliance gap assessments dominate advisory demand.
- Training:Certification programs for ISO 27001 lead auditors address pipeline constraints in the assessor workforce.
Consulting holds established practice scale. Managed Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration clusters around financial institutions in Mumbai and Bengaluru, government data centers in emerging states, and manufacturing exporters in southern industrial corridors. Each sub-region exhibits distinct procurement patterns shaped by regulatory deadlines and infrastructure maturity.
Maharashtra
Private sector banks in Mumbai's Bandra-Kurla Complex drive consolidated platform procurement for firewall and identity integration. RBI cybersecurity frameworks for urban cooperative banks compress compliance timelines for tier-2 city branches. Payment aggregators in Pune's Hinjewadi tech corridor accelerate automated security orchestration deployments.
Karnataka
Fintech scale-ups in Bengaluru's Koramangala and HSR Layout corridors demand elastic cloud security service edge capacity. CERT-In's six-hour incident reporting mandate forces machine learning-augmented intrusion detection pilots among telecom operators. State data center expansion under MeitY's cloud infrastructure program creates sovereign hosting demand in Mysuru.
Tamil Nadu
Manufacturing conglomerates in Chennai's Sriperumbudur industrial belt pilot hybrid architectures segmenting operational technology from enterprise IT. Skills scarcity for certified SOC analysts pushes mid-market automotive suppliers toward co-managed service models. Pharmaceutical exporters in Hyderabad-adjacent clusters demand outcome-based contracts with mean-time-to-detect guarantees.
Telangana
Genome Valley pharmaceutical clusters in Hyderabad drive retainer contracts with guaranteed response time SLAs replacing hourly consulting. RBI-mandated data localization pushes payment system operators toward in-country transaction log processing. Cybersecurity training providers address ISO 27001 lead auditor pipeline constraints for regional assessor workforce expansion.
Gujarat
Automotive component suppliers in Ahmedabad and Sanand lack dedicated security operations, creating white space for modular pay-as-you-grow managed services. PLI scheme incentives for domestic semiconductor manufacturing redirect vendor sourcing toward indigenous firewall production. Textile exporters in Surat face compliance gaps addressed by advisory services for CERT-In gap assessments.
India Network Security and Cyber Risk Management Market Competitive Landscape
Player mix skews toward diversified IT services majors with captive delivery centers and specialized cybersecurity pure-plays with certified domestic operations. The vendor base concentrates around three strategic archetypes: global platform vendors with sovereign cloud partnerships, domestic IT services firms with integrated managed detection offerings, and endpoint specialists priced for mid-market verticals. Competitive moves center on automated compliance dashboard development and localized data processing architecture redesign.
Within the global platform tier, Palo Alto Networks and Cisco Systems exemplify next-generation firewall architectures tailored for RBI-mandated data localization. Among domestic delivery anchors, Tata Consultancy Services occupies a position representing integrated incident response and managed detection services. Quick Heal Technologies sits within the specialized endpoint segment, exemplifying pricing strategies oriented toward government and manufacturing verticals.
| Leading Market Players |
|---|
| Cisco Systems |
| Palo Alto Networks |
| IBM Corporation |
| Tata Consultancy Services |
| Check Point Software Technologies |
| Trend Micro |
| Quick Heal Technologies |
| Fortinet |
| Infosys |
| Others |
Pricing and Supply Chain Analysis
Ninety-day chipset lead times from Taiwan foundries compress margin buffers for domestic firewall assemblers while amplifying pricing power among distributors holding buffer inventory. This supply-chain rigidity forces Indian vendors toward annual cost-plus contracts indexed to semiconductor spot markets, embedding volatility into enterprise security procurement cycles.
Pricing Analysis
Cost-plus contracts with quarterly indexation to Taiwan semiconductor spot markets dominate hardware procurement for next-generation firewalls. Three-tier pricing structure across premium, standard, and economy levels separates RBI-certified appliances with localized data processing from uncertified imports and open-source alternatives. Pricing pressure stems from PLI scheme incentives redirecting public sector tenders toward indigenous assembly, compressing import-dependent vendor margins. Urban cooperative banks in tier-2 cities exhibit highest price sensitivity, while Mumbai-based private banks prioritize certification tier over unit cost.
Supply Chain Analysis
Inbound logistics costs from Singapore and Hong Kong ports face container availability constraints that extend hardware delivery windows by three to four weeks. Specialized packet inspection chipsets and high-throughput encryption processors concentrate supply with Taiwan and South Korea foundries, exposing vendors to geopolitical disruption. Raw material dependencies span silicon wafers, FPGA modules, and precision cooling components. Distribution runs through domestic IT distributors with regional stocking points in Mumbai, Bengaluru, and Delhi-NCR.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CERT-In's six-hour incident reporting mandate creates a high-growth disruption, forcing automated security orchestration procurement across banking and telecom networks regardless of macroeconomic headwinds.
For Market Incumbents: Compound platform consolidation advantages by integrating firewall, identity, and endpoint layers into unified policy orchestration. Deepen captive SOC delivery capacity in Maharashtra and Karnataka to offset skills scarcity inflation. Acquire ISO 27001 certification pipelines to compress 12-18 month compliance timelines threatening product launches. For New Entrants and Emerging Players: RBI cyber audit fast-track programs for urban cooperative banks unlock tier-2 and tier-3 city procurement previously captured by incumbent IT services majors. Gujarat's automotive component suppliers and Tamil Nadu's textile exporters lack dedicated security operations, creating white space for modular pay-as-you-grow managed services. Lead with co-managed SOC models that split tier-one triage between internal staff and vendor analysts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified IT services majors seeking to monetize non-core cybersecurity divisions. Long-term viability hinges on sovereign cloud partnership depth with domestic telecom carriers. Watch for PLI scheme incentive expansions into security hardware assembly as inflection signal for indigenous vendor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Compliance Dashboard Development | RBI-mandated data localization forces real-time audit trail visualization for sovereign cloud architectures. |
| Localized SOC Delivery Center Expansion | Captive Indian operations address certified analyst scarcity inflating managed service delivery costs. |
| Zero Trust Architecture Integration | Microsegmentation combined with behavioral analytics enables threat containment without perimeter appliances. |
| Indigenous Hardware Assembly Partnership | PLI scheme incentives redirect public sector procurement toward domestic firewall production. |
| Outcome-Based Service Contract Structuring | Mean-time-to-detect metrics replace seat-based pricing in pharmaceutical and manufacturing outsourcing agreements. |
Research Methodology
The analysis maps next-generation firewalls, IDS/IPS platforms, VPN architectures, and managed security services, each validated through CISO interviews, SOC operations directors, RBI compliance officers, and IT procurement leads at financial institutions. Primary fieldwork combined with secondary validation against CERT-In directive filings, RBI cybersecurity framework updates, BIS information security standards, and vendor SEC disclosures. Bottom-up deployment model sizing triangulates with top-down regulatory mandate impact assessments.
Consistency checks against hyperscaler sovereign cloud expansion disclosures and domestic telecom carrier partnership announcements validated projection outputs across the modeling period. Segmentation dimensions modeled include solution type, deployment architecture, end-user vertical, and service delivery model. CAGRs derived from regression analysis of historical procurement velocity against regulatory deadline compression. Industry-specific forecast inputs incorporate PLI scheme incentive trajectories and state data center expansion timelines under MeitY's cloud infrastructure program.
Decision-makers should treat outputs as directional under assumptions of sustained RBI enforcement intensity and PLI scheme continuity; material deviation would warrant model refresh. Specific risks include geopolitical disruption to Taiwan semiconductor supply, delays in urban cooperative bank compliance deadlines, and skills scarcity acceleration beyond projected wage inflation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
India Cybersecurity Market
Cybersecurity
Europe Cloud DLP Market
Cybersecurity
Web Application Firewall Market
Cybersecurity
Application Security Market
Cybersecurity
Nordics Cybersecurity Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Cognitive Security Market
Cybersecurity
North America IoT Security Market
Cybersecurity
Cloud DLP Market
Cybersecurity
North America Extended Detection and Response Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
New Zealand Cybersecurity Market
Cybersecurity
Network Sandboxing Market
Cybersecurity
Multi-Cloud Data Protection Market
Cybersecurity
Morocco Cybersecurity Market