
 Canada Cybersecurity Market | 2026-2036
Canada Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cybersecurity Market Outlook
The capability gap between cloud-native platform investments and legacy perimeter defenses is unwinding competitive dynamics across Canadian cybersecurity. IBM Canada leverages its Watson-powered threat intelligence and federal consulting footprint to anchor large enterprise accounts. eSentire competes through its pure-play managed detection and response model purpose-built for mid-market financial institutions. Arctic Wolf differentiates by controlling a channel-heavy go-to-market that sustains recurring revenue density in distributed geographic markets.
Canada cybersecurity encompasses technologies, services, and governance frameworks designed to protect digital assets, networks, and data repositories from unauthorized access, disruption, or exfiltration across on-premises, cloud, and hybrid infrastructures. Core functional parameters include real-time threat detection latency measured in milliseconds, encryption key management spanning AES-256 and post-quantum standards, and automated incident response orchestration through SOAR platforms. Cloud security and managed services represent the fastest-expanding margin pools as Canadian enterprises accelerate migration from on-premises data centers to multi-cloud environments. Network security maintains mature revenue stability within financial institutions and utilities where legacy OT-IT convergence demands specialized segmentation protocols.
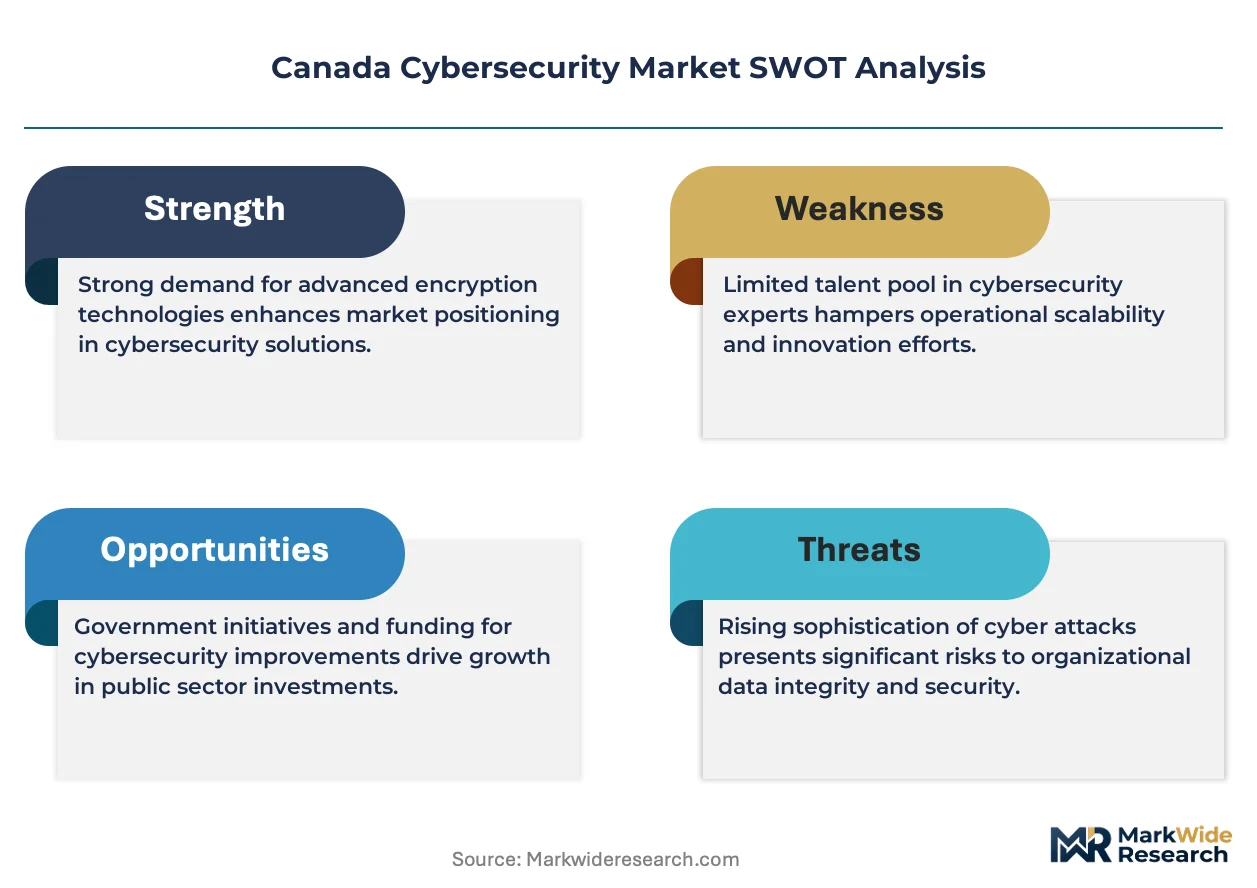
Health Canada collaborates with the Communications Security Establishment to enforce baseline cyber hygiene across healthcare delivery organizations, while the Office of the Superintendent of Financial Institutions mandates reporting timelines for material cyber incidents that compress vendor response obligations. The Canadian Centre for Cyber Security publishes threat assessments that directly shape procurement specifications for federal departments and crown corporations. Stakeholders must monitor how forthcoming amendments to the Personal Information Protection and Electronic Documents Act recalibrate liability frameworks for SaaS providers handling cross-border data flows.
Market Dynamics
Zero-trust architecture mandates from Ottawa are forcing enterprise infrastructure rebuilds across Canadian financial and telecom operators, collapsing traditional perimeter-based procurement cycles and reconfiguring vendor qualification criteria.
Growth Catalysts
- Bill C-26 Compliance Deadlines:Mandatory cybersecurity standards for finance and telecom sectors are accelerating replacement of legacy access controls with continuous verification frameworks.
- Critical Infrastructure Designation:Energy utilities and transportation operators face new reporting obligations that expand security operations center staffing and managed service contracts.
- Post-Quantum Cryptography Transition:Federal research investments through the Canadian Centre for Cyber Security are driving early pilot deployments of quantum-resistant encryption in crown corporations.
Market Restraints
- Concentrated Cloud Provider Dependence:Three hyperscalers control over eighty percent of Canadian enterprise cloud infrastructure, creating systemic resilience risks and limited negotiation leverage for security add-ons.
- Specialized Talent Scarcity:Domestic supply of cloud security architects and SOAR platform engineers falls short of demand from Toronto-Waterloo corridor expansion.
- Legacy OT-IT Integration Costs:Manufacturing and utility sectors face prohibitive capital requirements to segment industrial control systems from corporate networks without operational disruption.
Strategic Opportunities
- Atlantic Canada Data Center Buildout:Halifax and Moncton emerging as secondary cloud regions creates demand for localized security operations and sovereign data handling capabilities.
- Healthcare Cyber Hygiene Enforcement:Health Canada-CSE collaboration opens recurring revenue streams for managed detection services in provincial hospital networks currently underprotected.
- Cross-Border Data Flow Certification:Anticipated PIPEDA amendments position Canadian SaaS providers to capture compliance-sensitive clients seeking alternatives to US-based infrastructure.
Industry Challenges
- Security Operations Center Staffing:Burnout rates among Tier-1 analysts exceed thirty percent annually, forcing vendors into unsustainable compensation escalation or automation trade-offs that degrade detection quality.
- Federal Procurement Cycle Length:Crown corporation security tool evaluations routinely extend eighteen to twenty-four months, compressing vendor cash conversion and straining mid-tier service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cybersecurity Market |
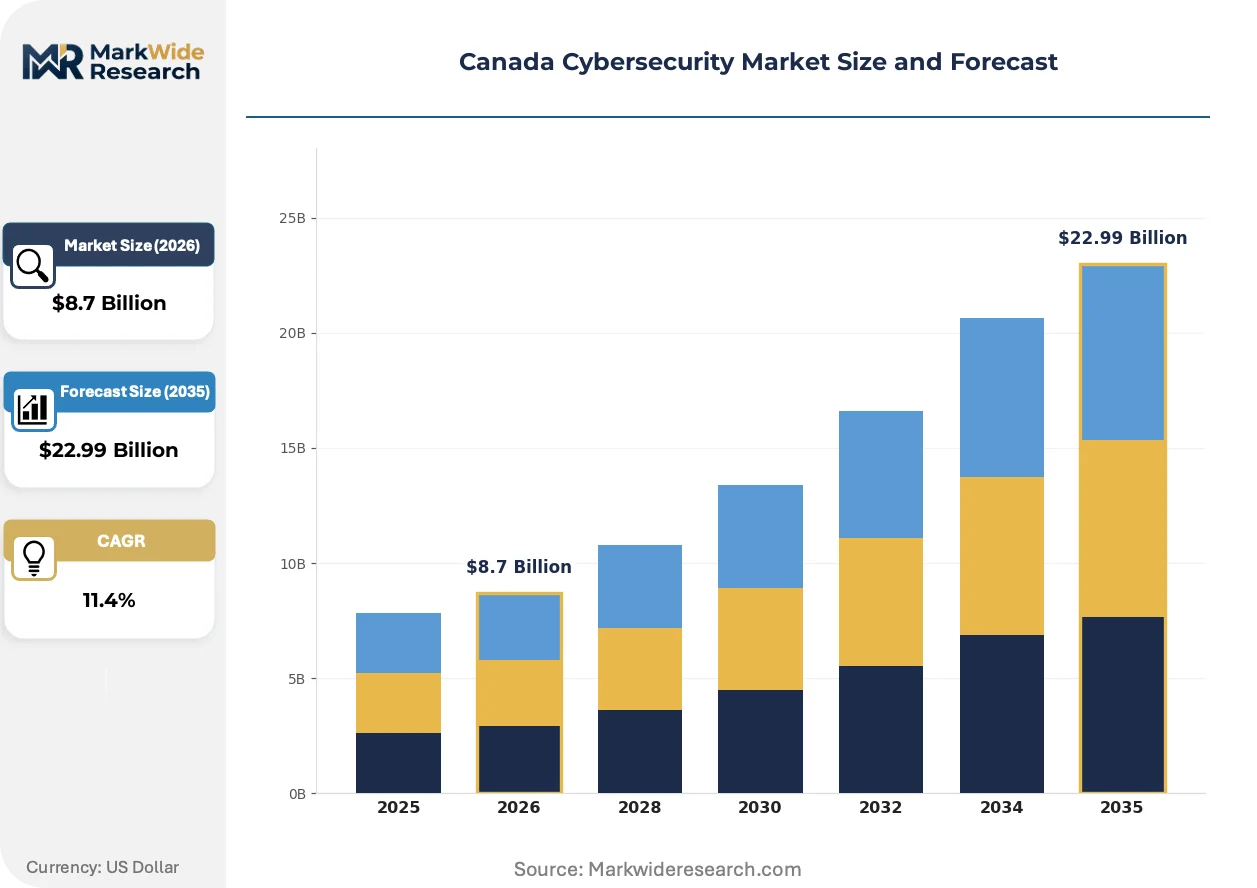
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Security, Network Security, Cloud Security, Application Security End User: Healthcare, Financial Institutions, Government, Utilities Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Industry Vertical: Retail, Manufacturing, Telecommunications, Transportation |
| Companies Covered | 1Password, Absolute Software, eSentire, IBM Canada, DeepStrike, Arctic Wolf, CyberArk, Beauceron Security, Telus Security, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cybersecurity Market Strategic Shifts
Extended detection and response platforms are collapsing the distinction between endpoint and network security layers, forcing Canadian enterprises to consolidate vendor relationships and renegotiate multi-year enterprise licensing structures.
Extended detection and response architectures aggregate telemetry across endpoints, cloud workloads, and identity systems into unified threat investigation workflows. Mid-market financial institutions in Toronto are adopting these platforms fastest, displacing standalone endpoint detection tools and compressing procurement decisions from twelve-vendor evaluations to three-platform shortlists. This consolidation is displacing regional security resellers who lack XDR engineering depth, channeling revenue toward vendors with native SOAR integration.
Health Canada collaborates with the Communications Security Establishment to enforce baseline cyber hygiene across healthcare delivery organizations. The resulting technical standards compel provincial health authorities to replace fragmented point solutions with integrated security service edge architectures. Ontario and British Columbia health networks are responding fastest, embedding zero-trust network access into electronic medical record infrastructure refresh cycles.
Canadian enterprises are unbundling security professional services from product licenses, demanding consumption-based pricing tied to actual incident response hours and threat intelligence enrichment volume. This procurement model shift disrupts traditional value-added reseller margins and elevates pure-play managed detection providers. The pattern concentrates in Quebec manufacturing and Alberta energy sectors, where CFO scrutiny of security spend has intensified following public ransomware disclosures.
Canada Cybersecurity Market Segmentation
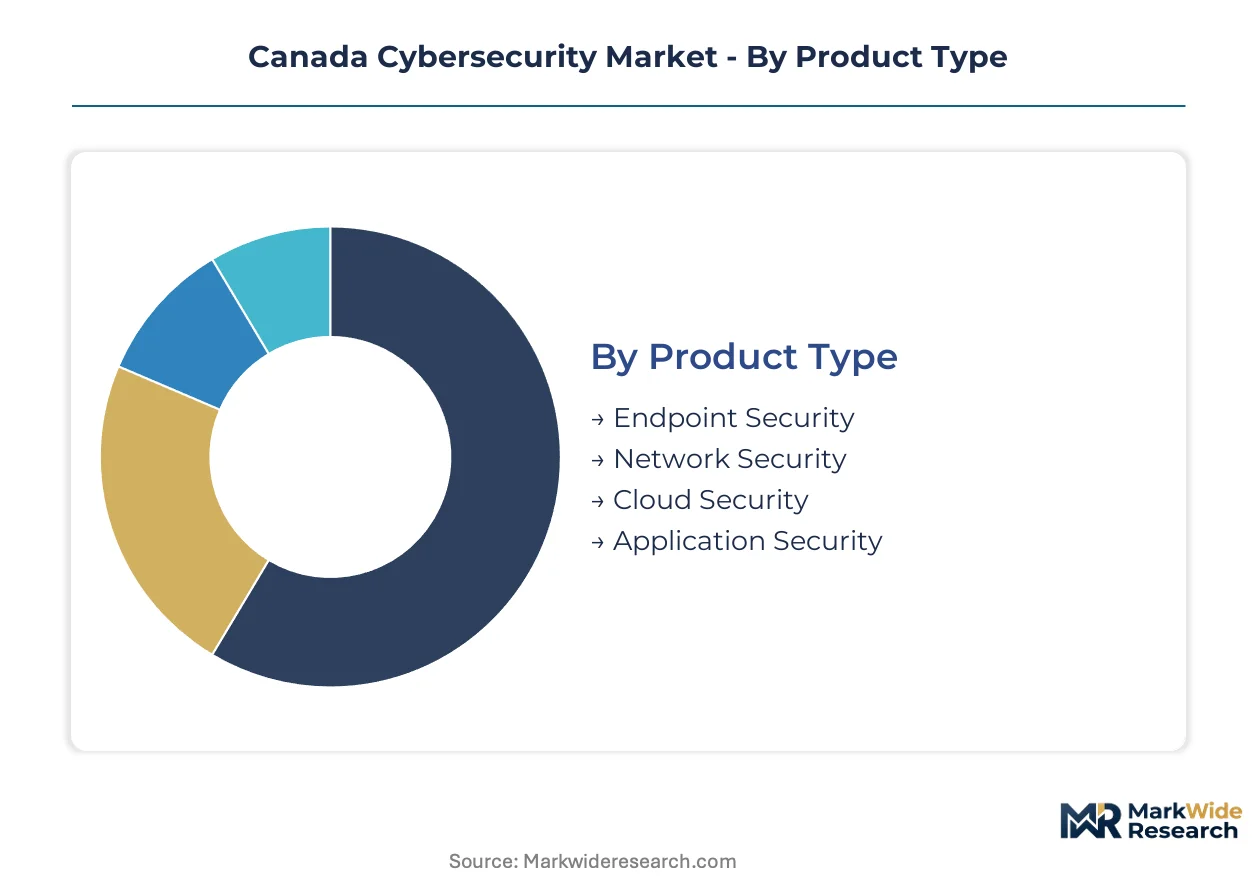
Segmentation in Canadian cybersecurity reveals how regulatory mandates reshape procurement patterns across federal, provincial, and private sector buyers. Distinct compliance timelines and operational technology environments create divergent technology requirements that vendors must address through specialized product configurations.
Product Type:
Health Canada and the Communications Security Establishment enforce divergent technical standards that elevate certain product categories above others in federal and healthcare procurement cycles.
- Cloud Security:Native protection for multi-tenant environments spans container runtime defense, cloud workload protection platforms, and infrastructure-as-code scanning. Toronto-Waterloo corridor enterprises migrating from on-premises data centers to Azure and AWS regions drive concentrated demand, with Bill C-26 compliance deadlines compressing procurement timelines for continuous verification frameworks.
- Network Security:Perimeter and internal segmentation controls include next-generation firewalls, secure access service edge, and microsegmentation platforms. Financial institutions in Toronto maintain mature spending here as legacy OT-IT convergence in utilities demands specialized industrial protocol inspection capabilities that cloud-native alternatives cannot replicate.
- Endpoint Security:Device-level protection through EDR, antivirus, and mobile threat defense.
- Application Security:Code scanning, runtime application self-protection, and API security testing tools.
Established volume favors Network Security; emerging adoption favors Cloud Security.
End User:
Procurement authority and budget scale vary dramatically across end-user categories, with federal mandates cascading unevenly through provincial and private sector implementations.
- Financial Institutions:Banks, credit unions, and insurance carriers operating under Office of the Superintendent of Financial Institutions supervision face mandatory reporting timelines for material cyber incidents. The resulting compressed vendor response obligations accelerate replacement of legacy access controls with automated incident response orchestration through SOAR platforms.
- Government:Federal departments and crown corporations purchasing through Public Services and Procurement Canada channels. Ottawa-Gatineau tech cluster concentration creates localized demand for vendors with federal security clearance and bilingual service delivery capabilities.
- Healthcare:Provincial hospital networks and health authorities responding to Health Canada-CSE technical standards.
- Utilities:Energy and water operators designated as critical infrastructure under evolving federal frameworks.
Procurement scale concentrates with Government; compliance urgency concentrates with Financial Institutions.
Deployment:
Capital availability and internal technical staffing determine deployment model selection across Canadian enterprise segments.
- Managed Services:Outsourced security operations center functions delivered through multi-year contracts with defined service level agreements. Mid-market financial institutions lacking Tier-1 analyst benches turn to pure-play MDR providers, while Alberta energy sector CFO scrutiny of security spend intensifies preference for consumption-based pricing tied to actual incident response hours.
- Hybrid:Split architectures maintaining sensitive workloads on-premises while leveraging cloud for elasticity. Manufacturing and utility sectors facing prohibitive legacy OT-IT integration costs adopt this model to segment industrial control systems without full operational disruption.
- Cloud-Based:Fully SaaS-delivered security tools with browser-based management consoles.
- On-Premises:Appliance and software deployments within customer-controlled data centers.
Recurring revenue density favors Managed Services; transitional flexibility favors Hybrid.
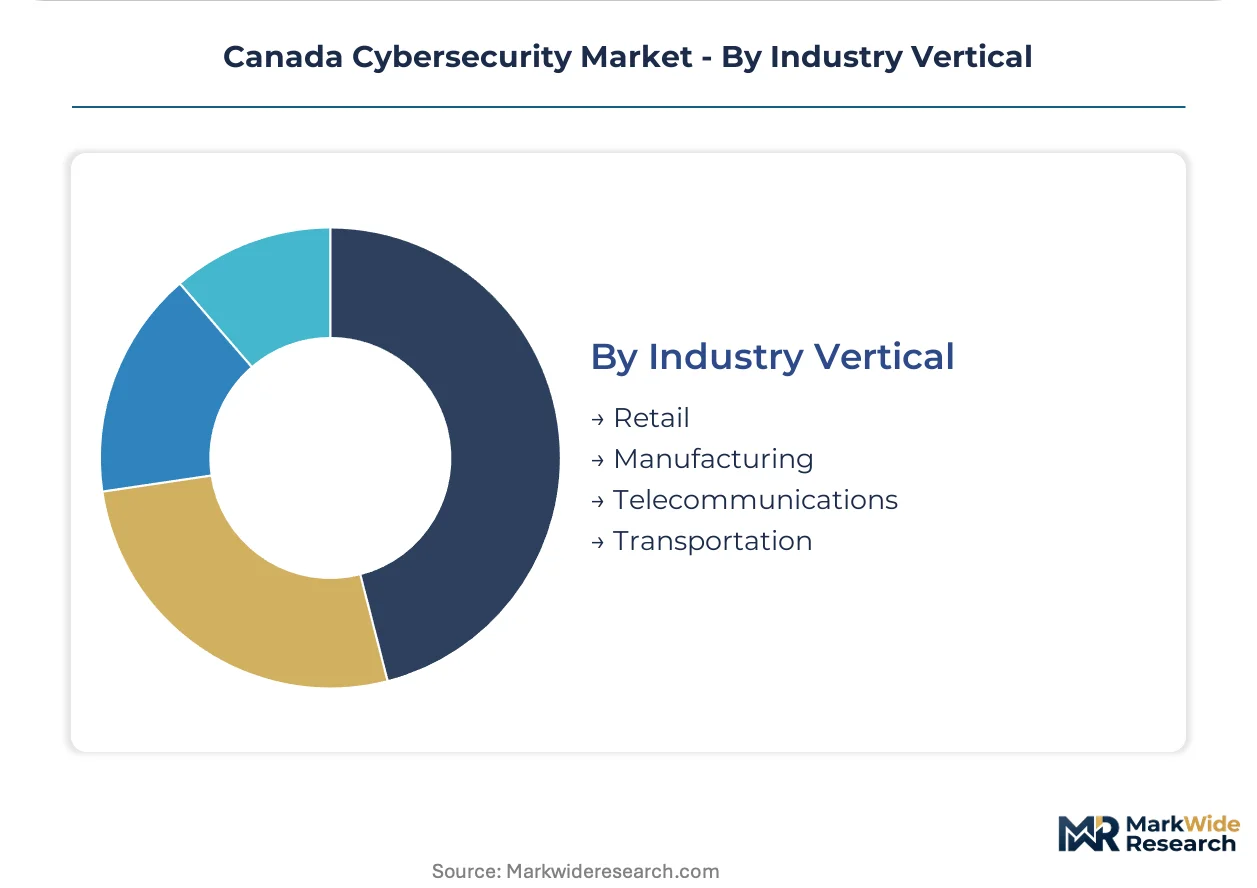
Industry Vertical:
Operational technology exposure and supply chain complexity create distinct risk profiles across vertical markets.
- Telecommunications:Carriers subject to Bill C-26 mandatory cybersecurity standards face infrastructure rebuild requirements that collapse traditional perimeter-based procurement cycles. Zero-trust architecture mandates from Ottawa force continuous verification framework adoption across subscriber-facing and internal network layers.
- Manufacturing:Discrete and process industries with converged OT-IT environments. Quebec manufacturing bases show expanding demand for managed detection services as ransomware disclosures intensify board-level security governance.
- Retail:Point-of-sale and e-commerce protection for merchant card data environments.
- Transportation:Logistics operators and carriers facing critical infrastructure designation considerations.
Regulatory pressure concentrates with Telecommunications; serviceable addressable market expands fastest in Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cybersecurity procurement intensity varies sharply across Canadian provinces, with Ontario and Quebec driving cloud-native platform adoption while Western Canada concentrates on critical infrastructure protection and Atlantic Canada builds sovereign data handling capabilities.
Ontario
Toronto-Waterloo corridor enterprises migrating from on-premises data centers to multi-cloud environments drive concentrated demand for continuous verification frameworks. Bill C-26 compliance deadlines accelerate replacement of legacy access controls across financial institutions supervised by the Office of the Superintendent of Financial Institutions. Ottawa-Gatineau tech cluster creates localized demand for vendors with federal security clearance and bilingual service delivery capabilities.
Quebec
Manufacturing bases in Montreal and Quebec City show expanding demand for managed detection services as ransomware disclosures intensify board-level security governance. The province's language requirements and distinct procurement regulations shape vendor qualification criteria differently than federal channels. Quebec City hosts specialized security operations supporting provincial crown corporations and hydroelectric utility infrastructure.
Alberta
Energy sector CFO scrutiny of security spend intensifies preference for consumption-based pricing tied to actual incident response hours following public ransomware disclosures. Critical infrastructure designation for oil and gas operators expands security operations center staffing and managed service contracts. Calgary anchors demand for OT-IT segmentation protocols in upstream and midstream operations.
British Columbia
Vancouver technology sector and provincial health networks respond fastest to Health Canada-CSE technical standards, embedding zero-trust network access into electronic medical record infrastructure refresh cycles. Port and transportation operators face emerging critical infrastructure reporting obligations. The province's Asia-Pacific trade connections elevate supply chain security assessment requirements.
Atlantic Canada
Halifax and Moncton emerging as secondary cloud regions creates demand for localized security operations and sovereign data handling capabilities. Federal research investments through the Canadian Centre for Cyber Security drive early pilot deployments of quantum-resistant encryption in regional crown corporations. Atlantic Canada data center buildout attracts compliance-sensitive clients seeking alternatives to centralized infrastructure.
Canada Cybersecurity Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with pure-play managed detection providers occupying distinct positioning from channel-heavy platform vendors. The market structure reflects procurement bifurcation between federal departments demanding comprehensive consulting footprints and mid-market enterprises seeking consumption-based service models. Two strategic archetypes dominate: integrated technology-service hybrids anchoring large enterprise accounts, and specialized managed security providers capturing recurring revenue density in distributed geographic markets. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and geographic expansion through channel partner networks.
Within the integrated tier, IBM Canada leverages its federal consulting footprint and threat intelligence capabilities to anchor large enterprise accounts. eSentire exemplifies the pure-play managed detection archetype purpose-built for mid-market financial institutions. Arctic Wolf occupies a position within the channel-heavy go-to-market segment, sustaining recurring revenue density across distributed geographic markets. These three anchors represent the competitive positioning spectrum visible across Canadian cybersecurity procurement.
| Leading Market Players |
|---|
| 1Password |
| Absolute Software |
| eSentire |
| IBM Canada |
| DeepStrike |
| Arctic Wolf |
| CyberArk |
| Beauceron Security |
| Telus Security |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud capacity utilization above eighty percent across Canadian enterprise infrastructure creates asymmetric scale economies that compress price floors for security add-ons while concentrating procurement leverage among three dominant platform providers. This concentration simultaneously elevates managed service premiums and squeezes standalone product margins as buyers bundle security spend within cloud migration budgets.
Pricing Analysis
Managed detection and response contracts drive lifetime value through multi-year service tier commitments with defined incident response SLAs. Three-tier pricing structure across premium, standard, and economy levels segments by analyst coverage hours and threat intelligence enrichment depth. Cost compression in standard-tier MDR is intensifying because mid-market financial institutions demand consumption-based pricing tied to actual event volume. Alberta energy sector CFOs exhibit highest price sensitivity following public ransomware cost disclosures, while federal crown corporations show lowest sensitivity due to eighteen-to-twenty-four-month procurement cycles that prioritize security clearance over unit cost.
Supply Chain Analysis
Silicon wafer fabrication chokepoints in Taiwan and South Korea underpin hardware security module availability for Canadian financial institutions deploying post-quantum cryptography. Semiconductor supply draws from TSMC and Samsung foundries, cryptographic processor IP from ARM and RISC-V architectures, and rare earth elements from Chinese processing facilities. Single-source vulnerability concentrates in quantum-resistant algorithm implementations where NIST-standardized libraries remain limited. Distribution runs through Toronto-Waterloo corridor value-added resellers with federal security clearance, channeling product through bilingual service delivery networks into Ottawa-Gatineau procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward mid-market financial institutions consolidating vendor relationships from twelve-platform evaluations to three-platform shortlists, fragmenting incumbent reseller margins while elevating pure-play MDR providers with native SOAR integration.
For Market Incumbents: Shield federal consulting footprints by deepening bilingual service delivery capabilities in Ottawa-Gatineau and accelerating zero-trust architecture certifications ahead of Bill C-26 compliance deadlines. Arctic Wolf's channel-heavy model demonstrates how geographic density sustains recurring revenue against IBM Canada's Watson-powered threat intelligence consolidation. Vertical integration into SOAR platform development represents the critical lever for margin defense as standalone EDR tools face displacement. For New Entrants and Emerging Players: Atlantic Canada data center buildout in Halifax and Moncton exposes an under-served sovereign data handling gap where localized security operations lack established MDR presence. Quebec manufacturing bases show expanding managed detection demand as ransomware disclosures intensify board-level governance, with French-language service capabilities creating qualification barriers for non-regional entrants. A channel partnership strategy targeting provincial crown corporations with quantum-resistant encryption pilots captures early-mover positioning ahead of federal procurement standardization. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pure-play MDR providers purpose-built for mid-market financial institutions with consumption-based pricing flexibility. Long-term viability across the projection horizon favors vendors controlling native XDR engineering depth over resellers dependent on third-party platform licenses. Acquisition targets should demonstrate Health Canada-CSE technical standard compliance for healthcare vertical expansion. The signal to monitor is PIPEDA amendment finalization, which would recalibrate liability frameworks for cross-border data flow certification.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | Bill C-26 compliance deadlines collapse traditional perimeter-based procurement cycles across financial and telecom operators. |
| SOAR Platform Integration | Native orchestration capabilities displace standalone EDR tools in Toronto-Waterloo corridor consolidation trends. |
| Atlantic Canada Geographic Expansion | Halifax and Moncton data center buildout creates localized security operations demand absent established MDR presence. |
| Post-Quantum Cryptography Pilot Deployment | Canadian Centre for Cyber Security research investments drive early crown corporation adoption ahead of standardization. |
| Bilingual Service Delivery Investment | Quebec procurement regulations and federal channels mandate French-English capability for vendor qualification. |
Study Parameters
The analysis maps cloud security, network security, endpoint security, and application security sub-sectors, each validated through chief information security officers, federal procurement officers at Public Services and Procurement Canada, managed security service provider executives, and provincial health authority IT directors. Primary interview findings triangulate against Communications Security Establishment threat assessments, Office of the Superintendent of Financial Institutions incident reporting guidelines, Canadian Centre for Cyber Security procurement specifications, and hyperscaler capex disclosures. Bottom-up product adoption curves reconcile with top-down federal budget allocation patterns across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including federal IT spending plans, provincial health network security refresh cycles, and critical infrastructure operator SOC staffing projections. The analytical framework models deployment model, organization size, vertical risk profile, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic infrastructure investment patterns. Forecast inputs incorporate Bill C-26 implementation timelines and Health Canada-CSE technical standard enforcement trajectories.
Material uncertainties — regulatory amendment timing, hyperscaler market entry into adjacent security services, and quantum computing advancement curves — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding federal procurement cycle stability and mid-market financial institution cloud migration velocity. Practitioners should keep alternative scenarios live as PIPEDA amendment negotiations and critical infrastructure designation expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
North America Software Defined Perimeter Market
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Global IoT Digital Forensics Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
UK Cybersecurity Market
Cybersecurity
IoT Security Market
Cybersecurity
Middle East Cybersecurity Market
Cybersecurity
Mexico Cybersecurity Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
Brazil Cybersecurity Market
Cybersecurity
Corporate Web Security Market
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Russia Cybersecurity Market
Cybersecurity
Global Cyber Threat Intelligence Market
Cybersecurity
India Ransomware Protection Market