
 Africa Cybersecurity Market | 2026-2036
Africa Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Cybersecurity Market Outlook
Market Context
The capability gap between capital-heavy platform vendors and lean regional specialists is redrawing competitive boundaries across African cybersecurity. IBM Corporation leverages its Watson security stack and pan-African partner network to anchor enterprise contracts in Johannesburg and Lagos. Cisco Systems Inc. competes through hardware-integrated security fabrics that dominate telecom infrastructure upgrades on the continent. Hera Group differentiates by embedding local regulatory fluency—particularly POPIA and Nigeria's NDPR—into managed services for mid-market clients.
Technical Definition and Structural Segments
Africa cybersecurity encompasses the technologies, services, and governance frameworks that protect digital assets, networks, and data across the continent's heterogeneous IT infrastructure, spanning everything from legacy on-premises systems in mining operations to containerized cloud workloads in Nairobi's tech hubs. The field operates through continuous threat monitoring, encryption protocols, identity verification, and incident response orchestration designed to counter region-specific attack vectors including mobile money fraud and state-sponsored intrusions. Network security maintains the largest installed base due to entrenched enterprise hardware cycles, yet cloud security registers the fastest expansion as AWS, Azure, and local providers build data centers in South Africa, Nigeria, and Kenya. Managed services capture disproportionate margin pools because African enterprises face acute skills shortages and prefer operational expenditure models over capital-intensive security stack ownership.
Regulatory Frame and Outlook
South Africa's Information Regulator enforces POPIA compliance with escalating penalties, while Nigeria's National Information Technology Development Agency administers the NDPR framework; Kenya's Office of the Data Protection Commissioner adds a third enforcement layer through the Data Protection Act. These bodies collectively shape product certification requirements, cross-border data flow restrictions, and breach notification timelines that vendors must embed into regional offerings. Stakeholders should monitor how the African Union's anticipated Malabo Convention ratification will harmonize—or fragment—cybersecurity standards across member states.
Market Dynamics
The convergence of mobile-first financial infrastructure and fragmented regulatory enforcement across African jurisdictions is compressing deployment timelines while elevating compliance complexity for security vendors.
Growth Catalysts
- Nigeria's NDPR framework:Mandatory data protection audits for financial institutions are forcing systematic security procurement cycles in Lagos and Abuja.
- Mobile money platforms:Safaricom's M-Pesa ecosystem and its competitors require real-time fraud detection architectures that expand addressable security spend.
- Cloud data center buildouts:AWS, Microsoft Azure, and Teraco are establishing presence in Johannesburg, Cape Town, and Lagos, creating immediate demand for cloud-native security tooling.
Market Restraints
- Foreign exchange volatility:Nigerian naira and South African rand depreciation inflates the landed cost of imported security appliances and SaaS subscriptions denominated in dollars.
- Skills concentration in Johannesburg:Certified security architects cluster in South Africa's economic hub, leaving Nairobi, Lagos, and Accra dependent on expensive expatriate labor or remote support.
- Limited local threat intelligence:Most African enterprises rely on feeds calibrated for North American or European attack patterns, reducing detection efficacy for region-specific mobile malware and SIM-swap fraud.
Strategic Opportunities
- Ethiopia's banking liberalization:The gradual opening of the financial sector to private and foreign investment will create first-mover advantages for security vendors establishing relationships with emerging digital banks.
- Zero-trust architecture adoption:Remote work normalization post-pandemic is pushing South African enterprises toward identity-centric security models that replace perimeter-based hardware.
- Managed detection and response:Mid-market enterprises across Kenya and Ghana are outsourcing security operations to avoid building in-house SOCs, favoring subscription revenue models for regional service providers.
Industry Challenges
- Certified incident responder scarcity:GIAC and EC-Council qualified personnel command premium salaries that exhaust mid-market security budgets in secondary cities.
- Multi-jurisdictional compliance mapping:Enterprises operating across Kenya, Nigeria, and South Africa must reconcile divergent breach notification timelines and cross-border data transfer rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Cybersecurity Market |
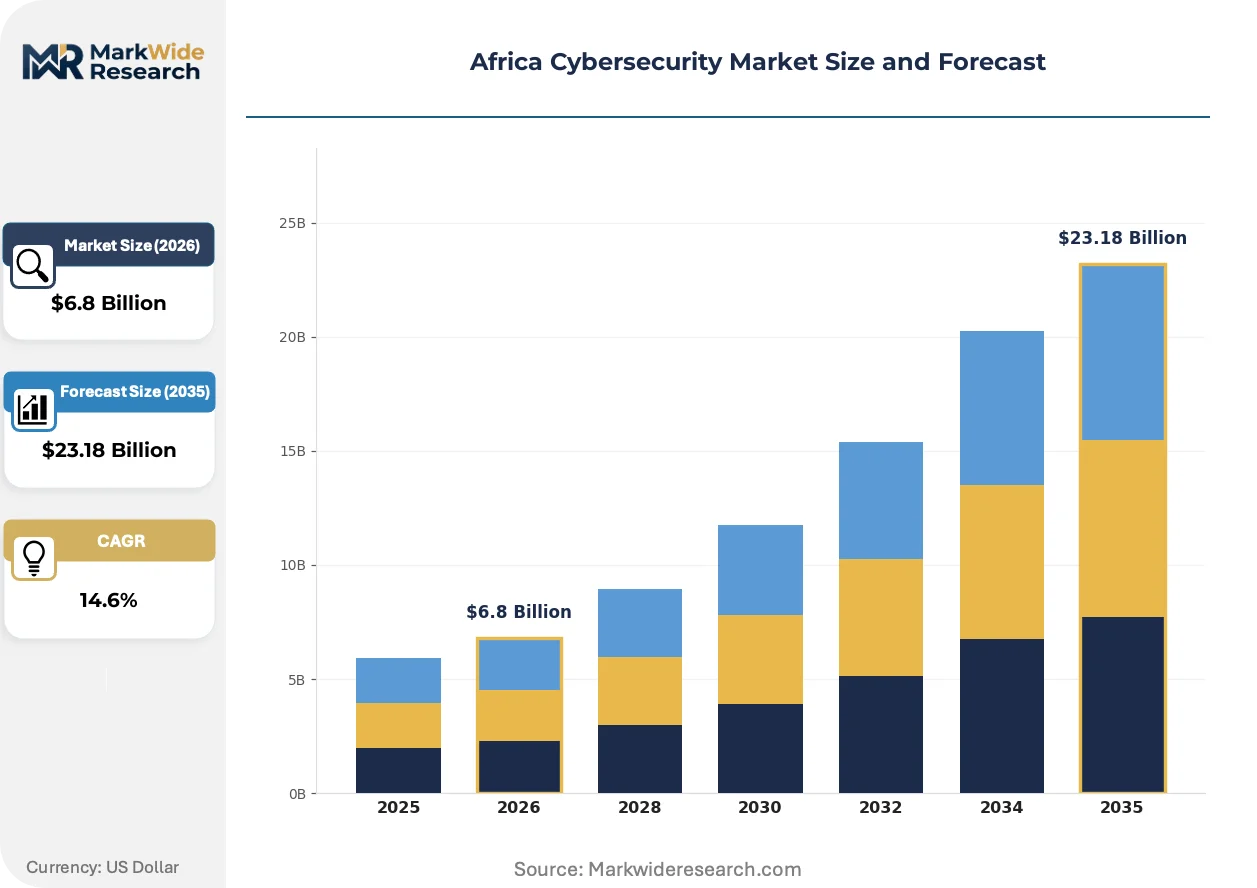
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Endpoint Security, Network Security, Cloud Security, Application Security Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Government, Financial Services, Healthcare, Telecom Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | IBM Corporation, Dell Technologies, Cisco Systems Inc., Trend Micro Inc., Broadcom Inc., Fortinet Inc., Check Point Software Technologies Ltd., Hera Group, Palo Alto Networks Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Cybersecurity Market Strategic Shifts
Security architecture decisions across Africa are increasingly driven by the tension between cloud-native agility and legacy infrastructure persistence, with procurement patterns diverging sharply by enterprise maturity and sector.
Extended detection and response platforms are consolidating endpoint, network, and cloud telemetry into unified analyst workflows. South African banks and Nigerian fintechs are deploying these tools at scale to reduce mean-time-to-response for mobile fraud incidents. The technology is bifurcating the market between enterprises with integrated security operations centers and those reliant on fragmented point solutions.
Kenya's Data Protection Act enforcement by the Office of the Data Protection Commissioner is tightening consent management and data localization requirements. Financial services and healthcare providers face mandatory privacy impact assessments that extend procurement cycles by four to six months. Cloud service providers are responding by certifying local data residency options in Nairobi to preempt regulatory friction.
Subscription-based security consumption is displacing perpetual license purchases among mid-market enterprises. Managed service providers in Lagos and Johannesburg are bundling detection, response, and compliance reporting into fixed monthly fees that convert capital expenditure to operational expenditure. Kenyan manufacturing and agricultural exporters are adopting this model most aggressively to satisfy international buyer cybersecurity audit requirements without dedicated internal security teams.
Africa Cybersecurity Market Segmentation
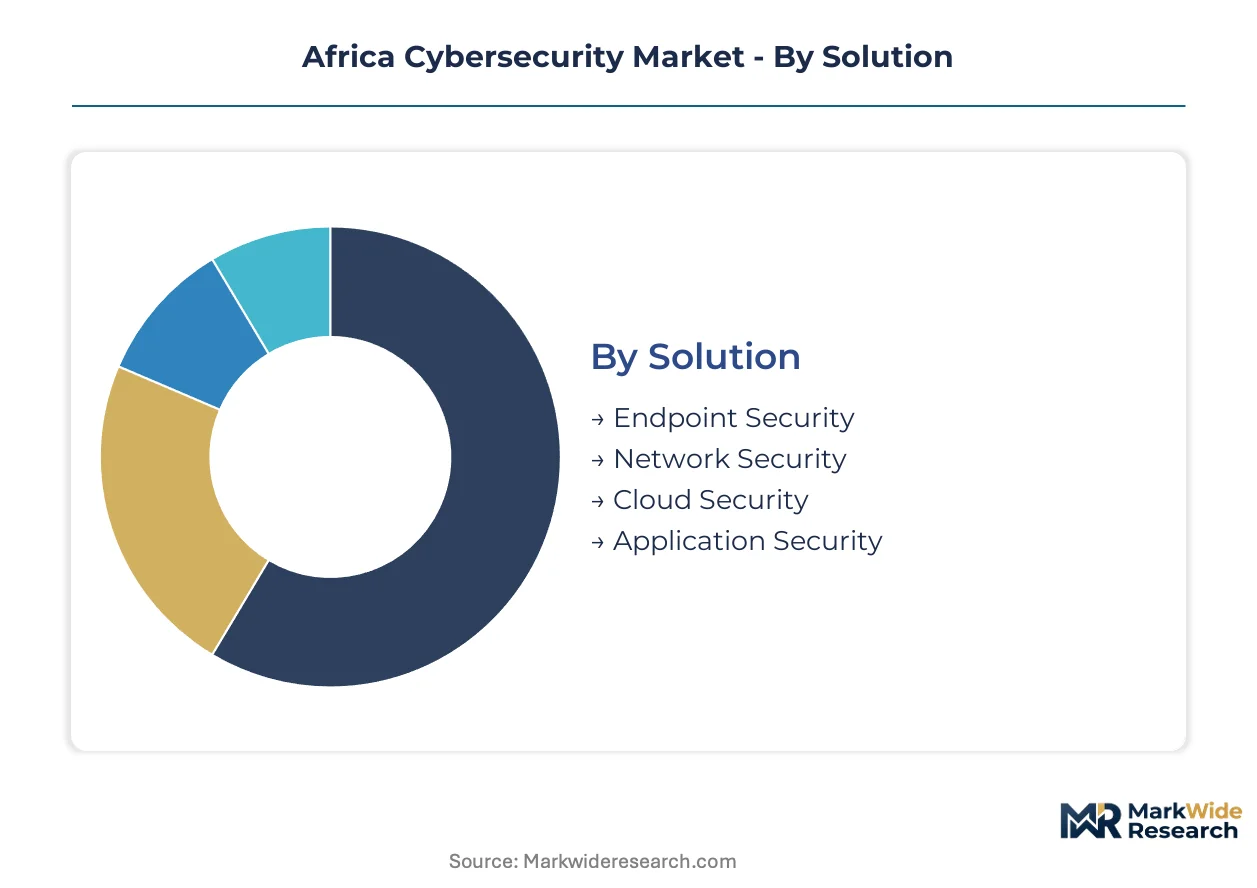
Cybersecurity procurement across Africa diverges sharply by enterprise maturity and regulatory exposure, with channel preferences determining which solution architectures gain traction in Lagos fintech corridors versus Johannesburg mining headquarters.
Solution:
Channel mix varies by solution complexity, with hardware-integrated network security flowing through systems integrators while cloud-native offerings reach buyers via direct vendor relationships and hyperscaler marketplaces.
- Network Security:Firewalls, intrusion detection systems, and secure access service edge platforms form the backbone of enterprise perimeter defense. Demand clusters in South African mining conglomerates and Nigerian banking headquarters upgrading legacy MPLS infrastructure to SD-WAN architectures with embedded security. Foreign exchange volatility inflates appliance procurement costs, pushing buyers toward subscription-based firewall-as-a-service models.
- Cloud Security:Workload protection, cloud access security brokers, and container security tools address multi-cloud deployments across AWS, Azure, and Teraco data centers. Kenyan fintechs and South African retailers adopting cloud-native infrastructure drive disproportionate growth, though skills shortages force reliance on managed service overlays.
- Endpoint Security:Endpoint detection and response platforms with anti-malware and device control capabilities protect distributed workforces.
- Application Security:Static and dynamic application security testing tools secure software development pipelines in Nairobi and Lagos tech hubs.
By volume, Network Security leads. By growth pace, Cloud Security is ahead.
Deployment:
Cost tier segmentation separates capital-constrained mid-market buyers from enterprises with balance sheet capacity for owned infrastructure, with operational expenditure models capturing margin in foreign-exchange-volatile environments.
- Managed Services:Outsourced security operations centers delivering 24/7 monitoring, threat hunting, and incident response through subscription contracts. Nigerian and Ghanaian enterprises lacking certified security architects rely on Johannesburg-based providers for remote SOC support, with POPIA and NDPR compliance reporting bundled into monthly fees.
- Cloud-Based:SaaS-delivered security tools requiring no on-site hardware deployment or maintenance. Kenyan Data Protection Act data localization mandates accelerate demand for in-country cloud instances with certified residency controls.
- On-Premises:Hardware appliances and perpetual-licensed software maintained within enterprise data centers.
- Hybrid:Architectures combining on-premises controls with cloud-delivered analytics and policy management.
By installed base, On-Premises retains dominance. By contract velocity, Managed Services is expanding most quickly.
End User:
Application-driven segmentation maps security spend to regulatory pressure intensity, with breach notification mandates and mandatory audit cycles determining procurement urgency across sectors.
- Financial Services:Banks, insurers, and mobile money operators deploying real-time fraud detection and transaction monitoring systems. Nigeria's NDPR mandatory audits and South Africa's POPIA enforcement create systematic procurement cycles, while M-Pesa ecosystem expansion drives Safaricom and competitors toward behavioral biometrics and SIM-swap detection.
- Government:National and provincial agencies securing critical infrastructure and citizen data registries. Kenya's Huduma Namba digital identity program and South Africa's e-government initiatives elevate sovereign cloud security requirements with local data residency mandates.
- Healthcare:Hospitals and health information exchanges protecting patient records and medical device networks.
- Telecom:Mobile network operators defending signaling infrastructure and subscriber databases against SS7 and Diameter protocol attacks.
By absolute spend, Financial Services commands the largest allocation. By regulatory momentum, Government procurement is climbing fastest.
Service Type:
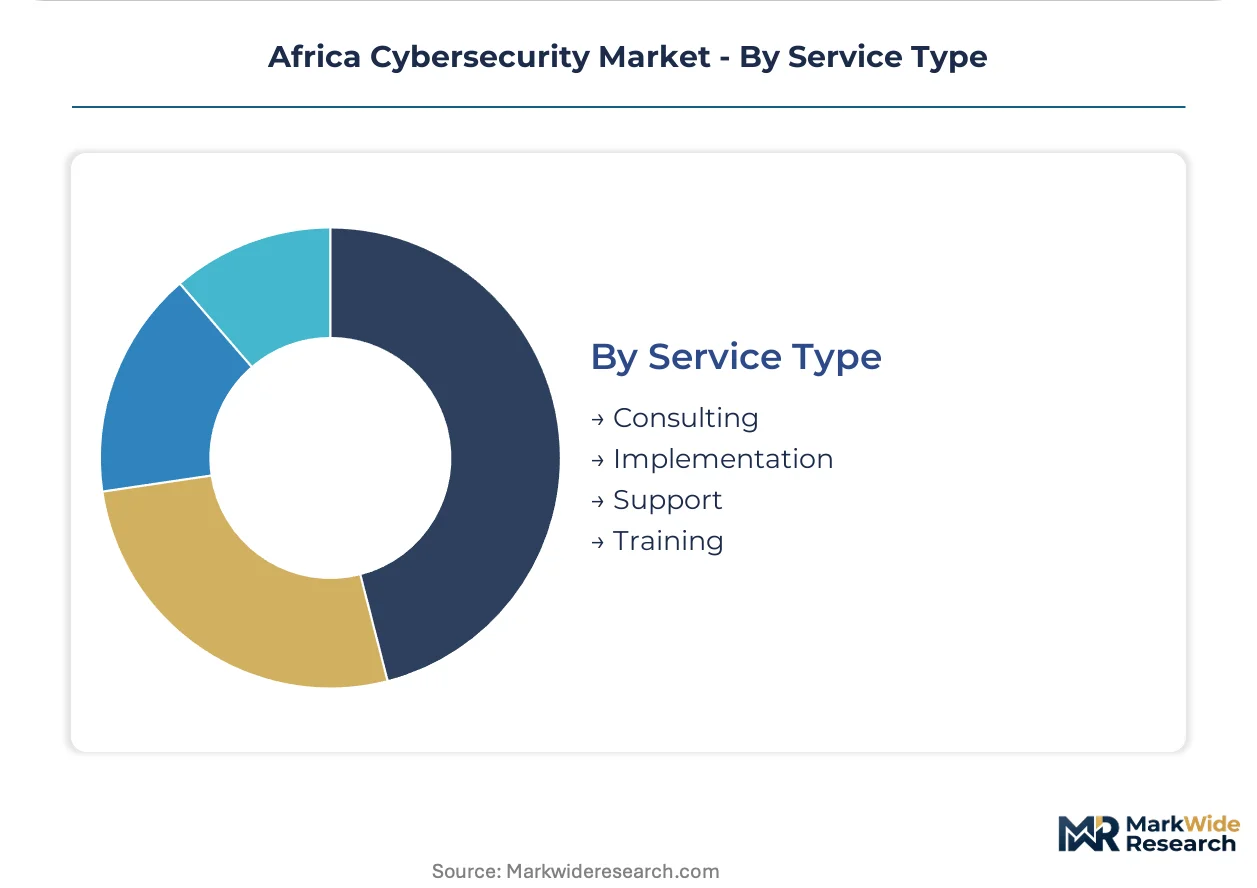
Customer maturity determines service mix, with early-stage buyers prioritizing implementation and training while sophisticated enterprises shift spending toward strategic consulting and advanced support tiers.
- Consulting:Risk assessments, security architecture design, and compliance gap analyses delivered by specialist firms. POPIA and NDPR readiness projects dominate Johannesburg and Lagos advisory pipelines, with multi-jurisdictional operators requiring cross-border data flow mapping across Kenya, Nigeria, and South Africa.
- Implementation:Deployment, configuration, and integration services for security technology stacks. Skills scarcity in Nairobi and Accra drives premium pricing for certified engineers, with vendors embedding remote implementation capabilities to bypass travel-dependent delivery models.
- Support:Technical maintenance, patch management, and break-fix services.
- Training:Certification programs and security awareness education for internal teams.
By revenue concentration, Consulting captures premium pricing. By contract frequency, Implementation services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Johannesburg and Lagos while Nairobi and Accra operate at persistent cost disadvantages due to skills scarcity and currency volatility. South African enterprises command vendor discounts through scale procurement, whereas Nigerian buyers absorb dollar-denominated premiums. Kenyan mid-market firms face the steepest total-cost-of-ownership escalations.
South Africa
Johannesburg anchors enterprise security spend through mining conglomerates and financial services upgrading SD-WAN infrastructure. The Information Regulator enforces POPIA with escalating penalties, compressing vendor selection timelines. Cape Town's tech corridor attracts cloud-native security deployments as AWS and Azure expand local data center presence.
Nigeria
Lagos fintechs drive cloud security procurement as digital banking platforms scale transaction volumes. The National Information Technology Development Agency administers NDPR mandatory audits for financial institutions, systematizing procurement cycles. Abuja government agencies are deploying sovereign cloud architectures with local data residency requirements.
Kenya
Nairobi's M-Pesa ecosystem demands real-time fraud detection architectures from mobile money operators. The Office of the Data Protection Commissioner enforces Data Protection Act consent management and localization mandates, extending procurement cycles. Mombasa port logistics operators are adopting subscription-based security operations to satisfy international buyer audit requirements.
Ghana
Accra banking sector modernization creates demand for managed detection and response services as institutions avoid in-house SOC construction. The country's data protection regulator tightens breach notification timelines, elevating compliance urgency. Tema manufacturing exporters purchase bundled security subscriptions to meet European buyer cybersecurity standards without dedicated internal teams.
Ethiopia
Addis Ababa's gradual banking liberalization generates first-mover opportunities for vendors establishing relationships with emerging digital banks. The central bank's forthcoming cybersecurity framework will mandate systematic security procurement. Industrial parks outside the capital are attracting foreign manufacturing investment with elevated data protection requirements.
Africa Cybersecurity Market Competitive Environment
Concentration sits with platform vendors possessing pan-African partner networks and local regulatory certification capabilities. IBM Corporation leverages Watson security stacks to anchor enterprise contracts, while Cisco Systems Inc. competes through hardware-integrated fabrics dominating telecom infrastructure. The vendor base stratifies between capital-heavy global platforms, regional specialists embedding POPIA and NDPR fluency, and lean managed service providers converting capital expenditure to operational expenditure. Dominant competitive moves include hyperscaler marketplace partnerships and compliance-forward service bundling.
Among the platform tier, IBM Corporation and Cisco Systems Inc. represent archetypes of hardware-integrated and AI-augmented security stacks respectively, each occupying positions shaped by entrenched enterprise relationships. Hera Group exemplifies the regional specialist archetype, embedding local regulatory knowledge into managed services for mid-market clients. Fortinet Inc. sits within the network security appliance segment, serving South African mining and Nigerian banking infrastructure upgrade cycles.
| Leading Market Players |
|---|
| IBM Corporation |
| Dell Technologies |
| Cisco Systems Inc. |
| Trend Micro Inc. |
| Broadcom Inc. |
| Fortinet Inc. |
| Check Point Software Technologies Ltd. |
| Hera Group |
| Palo Alto Networks Inc. |
| Others |
Value Chain & Pricing Dynamics
Subscription-based security consumption displacing perpetual license purchases simultaneously redraws supply geography toward Johannesburg-based managed service providers and compresses pricing economics for hardware-integrated vendors facing naira and rand depreciation.
Pricing Analysis
The customization-premium spread separates standard SaaS-tiered subscriptions from configured-to-order managed detection and response bundles. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with POPIA and NDPR compliance certification commanding premium positioning. Pricing pressure stems from foreign exchange volatility inflating dollar-denominated appliance costs, forcing mid-market Nigerian enterprises toward operational expenditure models. Financial services in Lagos show least price sensitivity due to mandatory audit cycles, while Ghanaian manufacturing exporters absorb steepest total-cost-of-ownership escalations.
Supply Chain Analysis
Skills scarcity in certified security architects creates a chokepoint that constrains delivery capacity across Nairobi, Accra, and secondary African cities. Hardware supply concentrates in South Africa, the United Arab Emirates, and direct vendor shipments from the United States and European manufacturing hubs. Semiconductor components, encryption modules, and threat intelligence feeds constitute critical input dependencies. Single-source vulnerability runs through Johannesburg-based systems integrators controlling pan-African distribution. Distribution runs through hyperscaler marketplaces and certified local partners with regulatory compliance credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of GIAC and EC-Council certified personnel across African markets elevates premium capture for vendors possessing credentialed delivery capacity, while compressing margins for competitors dependent on expatriate labor or remote support models.
For Market Incumbents: Shield enterprise relationships in South African mining and Nigerian banking by embedding POPIA and NDPR compliance automation into renewal contracts, while adding Johannesburg-based training academies to reduce reliance on expensive expatriate security architects facing visa and mobility constraints.
For New Entrants and Emerging Players: Differentiate on sovereign cloud security with certified data residency controls targeting Kenya's Data Protection Act localization mandates and Ethiopia's forthcoming banking liberalization, using fixed-monthly-fee managed services to bypass capital expenditure barriers in foreign-exchange-volatile environments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed managed service providers possessing pan-African compliance credentials and Johannesburg-centric delivery footprints. Long-term viability hinges on consolidation plays that aggregate scarce certified talent pools. Watch Ethiopia's central bank cybersecurity framework issuance as inflection signal for systematic procurement cycle activation.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Platform Launch | POPIA and NDPR audit readiness reduces procurement friction for Johannesburg and Lagos financial institutions. |
| Local Data Center Certification | Kenya's Data Protection Act residency mandates accelerate demand for Nairobi-based cloud security instances. |
| Managed Detection and Response Expansion | Subscription revenue models convert capital expenditure to operational expenditure for Ghanaian mid-market enterprises. |
| Security Operations Center Acquisition | Certified analyst pools in Johannesburg command premium valuations due to regional skills scarcity. |
| Hyperscaler Marketplace Partnership | AWS and Azure African data center presence creates immediate cloud-native security tooling distribution channels. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, hyperscaler capex disclosures, and trade data. Primary interviews engaged CISOs at Nigerian banks, South African mining conglomerates, and Kenyan fintechs; compliance officers navigating POPIA, NDPR, and Data Protection Act requirements; and channel partners distributing through Johannesburg and Lagos. Secondary sources included NITDA audit guidelines, Information Regulator enforcement actions, and AWS and Azure African infrastructure announcements. Bottom-up contract analysis and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled span solution type, deployment mode, end-user vertical, and service tier across the analysis window. The analytical framework projects expansion rates by correlating regulatory enforcement intensity, cloud data center buildout timelines, and mobile money platform transaction growth. CAGRs derive from weighted scenario analysis incorporating foreign exchange volatility assumptions and skills scarcity premiums. Forecast inputs include mandatory audit cycle frequencies and sovereign cloud procurement patterns.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement, stable foreign exchange regimes, or continued hyperscaler investment would require recalibration. Forecasts reflect documented assumptions about compliance timeline adherence and certification pipeline expansion. Practitioners should keep alternative scenarios live as Ethiopian banking liberalization pace and African Union Malabo Convention ratification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Application-Level Encryption Market
Cybersecurity
UK Cybersecurity Market
Cybersecurity
Asia Pacific IoT Security Market
Cybersecurity
Asia Pacific Cybersecurity Market
Cybersecurity
United Kingdom Ransomware Protection Market
Cybersecurity
Cyber Security and Big Data Analytics Market
Cybersecurity
Global Sandboxing Market
Cybersecurity
Micro Segmentation Technology Market
Cybersecurity
Cyber Security in Energy Market
Cybersecurity
Education Data Security Market
Cybersecurity
Post-Quantum Cryptography Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
Australia Cybersecurity Market
Cybersecurity
Sweden Cybersecurity Market
Cybersecurity
Data Exfiltration Techniques Market