
 Big Data Security Market | 2026-2036
Big Data Security Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Security Market Intelligence
The fragmentation of the buyer base from a few large enterprises to a diverse set of SMEs is restructuring security solution delivery models. Microsoft leverages its Azure cloud infrastructure to offer integrated security tools for this expanding customer set. IBM specializes in enterprise-grade compliance and threat intelligence platforms for highly regulated industries. Palo Alto Networks competes with advanced, automated security operations designed for complex, multi-cloud data environments.
Big data security encompasses the policies and technologies used to protect large-volume, high-velocity datasets from cyber threats. Its primary purpose is to ensure data confidentiality and integrity across distributed systems like Hadoop or NoSQL databases. Cloud-based deployment models show significant momentum over traditional on-premises installations, offering greater scalability. Among solution types, threat intelligence and data encryption represent foundational investments for most large enterprises seeking comprehensive protection.
Data privacy regulations such as the EU's GDPR and the California Consumer Privacy Act (CCPA) establish strict requirements for data protection. In parallel, national frameworks like China's Cybersecurity Law influence data localization and cross-border data transfer rules. Vendors must now engineer solutions that address these divergent compliance mandates without compromising system performance or analytical capabilities.
Market Dynamics
The central dynamic in the big data security market is the tension between the drive for data-driven business intelligence and the escalating complexity of regulatory compliance. This forces organizations to seek solutions that enable data utilization without compromising security or violating mandates like GDPR.
Growth Catalysts
- Regulatory Mandates:Frameworks like Europe's GDPR and the US's HIPAA impose strict data protection requirements, compelling organizations in sectors from finance to healthcare to invest in advanced security solutions to avoid severe penalties.
- IoT Data Proliferation:The explosion of Internet of Things (IoT) devices across industrial and consumer applications generates immense volumes of data, creating a vast new attack surface that requires specialized security to protect endpoints and data streams.
- BFSI Sector Demand:Financial institutions are prime targets for cyberattacks, driving their continuous investment in big data security to protect sensitive customer information, perform real-time fraud analytics, and comply with financial regulations.
Market Restraints
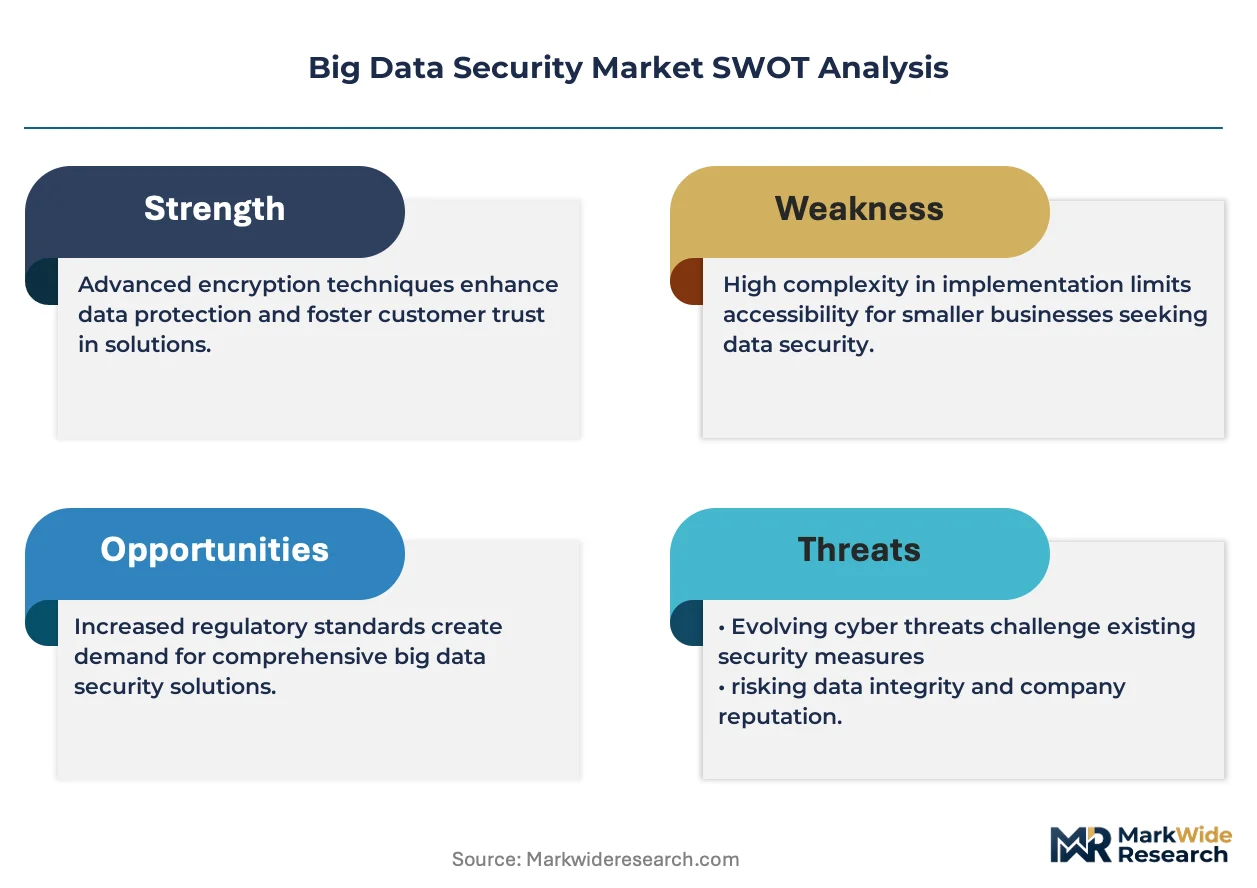
- High Implementation Cost:The significant upfront investment required for enterprise-grade security platforms, coupled with the cost of integration and skilled personnel, acts as a substantial barrier for many small and medium-sized enterprises (SMEs).
- Performance Overhead:Intensive security processes like real-time data encryption and continuous monitoring can introduce latency and degrade the performance of big data analytics platforms, creating a trade-off between security and analytical speed.
- Talent Scarcity:A persistent shortage of cybersecurity professionals who possess specialized skills in both big data technologies like Hadoop and advanced security protocols limits the ability of organizations to effectively deploy and manage these complex systems.
Strategic Opportunities
- Edge Computing Security:Securing data at the network edge presents a significant opportunity, as processing moves closer to IoT devices and creates demand for lightweight, distributed security solutions beyond the central data center.
- AI-Powered Threat Intelligence:The convergence of artificial intelligence with security platforms offers a major growth avenue, enabling predictive threat detection and automated response capabilities that can identify novel attacks faster than human analysts.
- Underpenetrated Geographies:Markets in Southeast Asia and Latin America, where digitalization is accelerating but cybersecurity infrastructure is less mature, offer substantial growth potential for vendors that can provide scalable, cloud-based security services.
Industry Challenges
- Integration with Legacy Systems:A primary operational challenge involves integrating modern big data security tools with aging, heterogeneous IT infrastructures, which can be complex, time-consuming, and prone to creating new security vulnerabilities during the transition.
- Navigating Compliance Fragmentation:Vendors and enterprises face the difficulty of designing and managing security architectures that can simultaneously adhere to divergent and sometimes conflicting data sovereignty regulations, such as China's Cybersecurity Law and the EU's GDPR.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Security Market |
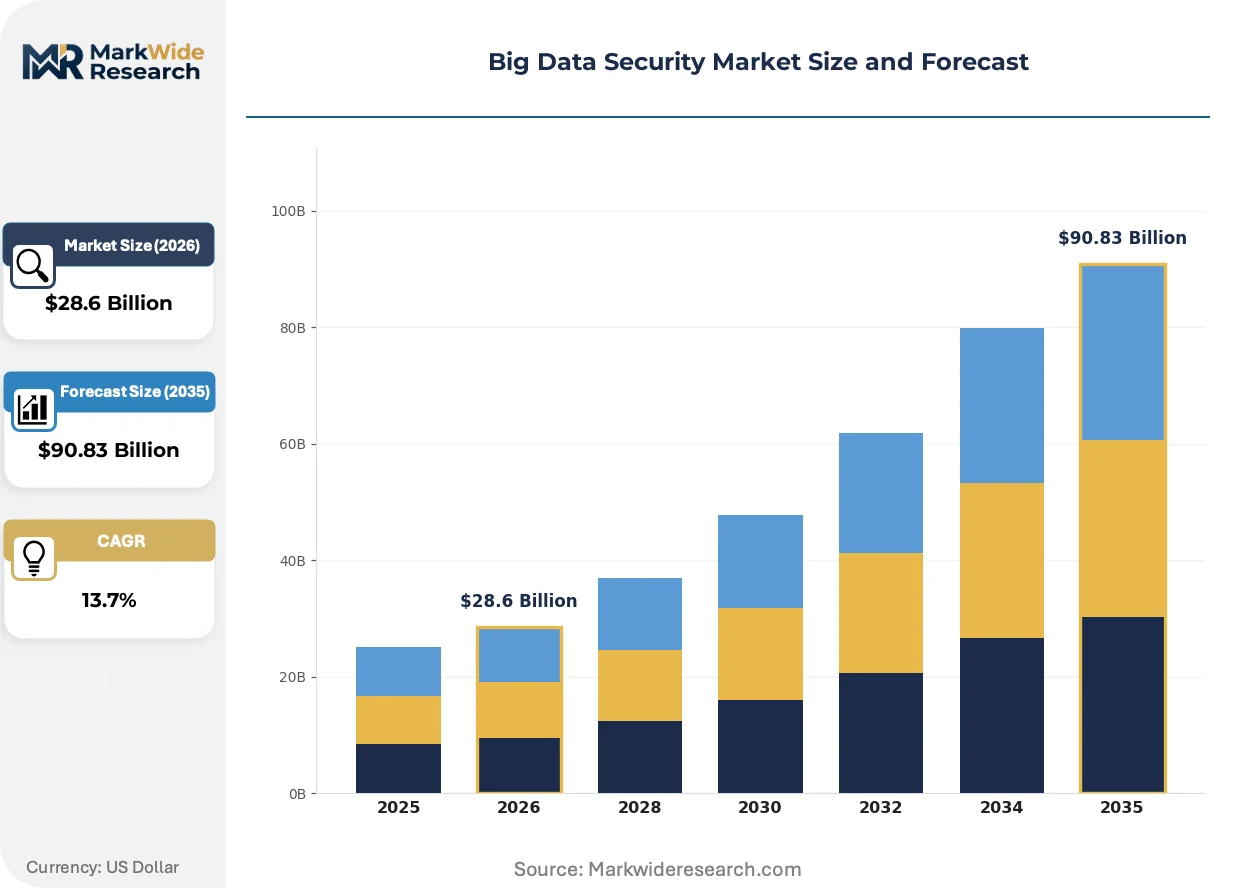
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Encryption, Access Management, Intrusion Detection, Threat Intelligence, Identity Authentication, Compliance Monitoring Deployment Mode: On-Premises, Cloud-Based, Hybrid, Managed Security Service, Virtual Appliance Application: BFSI, Telecommunications, Government, Energy & Utilities, Manufacturing, Media & Entertainment End User: Large Enterprises, SMEs, IT Service Providers, Data Centers, Research Institutions |
| Companies Covered | Amazon Web Services, IBM, Microsoft, Oracle, Palo Alto Networks, Broadcom, Cisco Systems, Check Point Software Technologies, Fortinet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Security Market Strategic Shifts & Innovations
The market is defined by a fundamental shift away from traditional perimeter-based defense toward a more granular, data-centric security paradigm. This evolution prioritizes the protection of data itself, regardless of its location within distributed cloud or on-premises environments.
Homomorphic encryption represents a significant technological advancement, allowing for direct computation on encrypted datasets. Highly regulated sectors like healthcare and financial services are beginning to adopt this technology for sensitive data analysis. This technology is expanding into complex, multi-party computation scenarios, enabling collaborative analytics between organizations without ever exposing the underlying raw data to either party.
Regulatory frameworks like China's Cybersecurity Law create distinct market requirements centered on data localization. The law compels multinational corporations to store specific types of data generated within China on local servers. Consequently, this affects global data governance strategies, forcing firms to re-architect their cloud infrastructure and security policies to ensure regional compliance, often through segregated data environments.
A notable behavioral change is the enterprise pivot from perpetual software licenses toward subscription-based Security-as-a-Service (SaaS) models. This transition from large, upfront capital expenditures to predictable operational spending is displacing the sale of traditional on-premises security appliances. This trend is most prominent among small and medium-sized businesses seeking access to enterprise-grade security without the corresponding overhead.
Big Data Security Market Segmentation
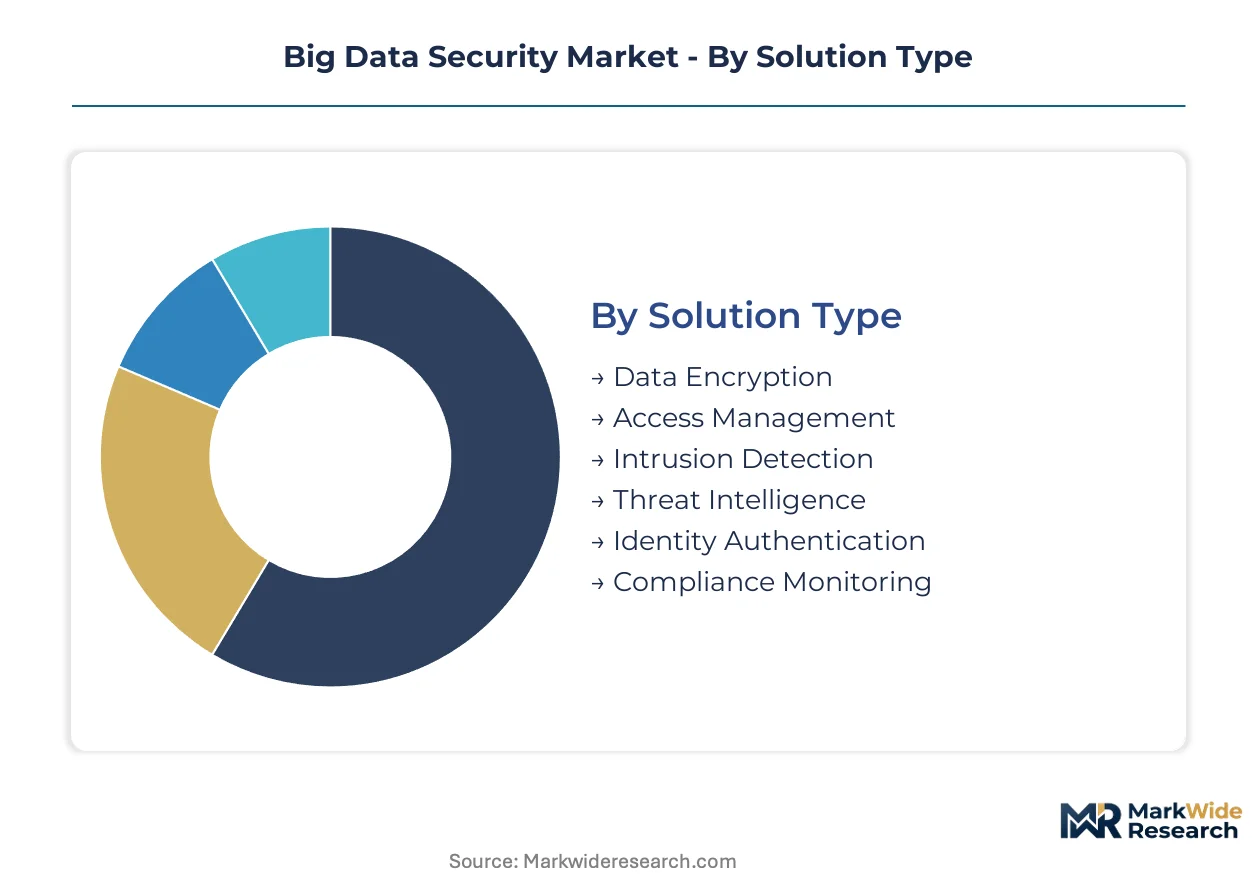
The big data security market exhibits diverse segmentation, reflecting the varied needs and technological landscapes across industries. Understanding these distinct segments allows vendors to tailor solutions precisely, addressing specific cyber threats and compliance requirements for different organizational profiles.
Solution Type:
The technological sophistication of big data security solutions dictates their application and efficacy against evolving threats.
- Threat Intelligence:This solution involves collecting and analyzing information about potential or actual cyber threats to help organizations make informed decisions about their security posture. Most large enterprises prioritize threat intelligence platforms for proactive defense against sophisticated, persistent attackers.
- Data Encryption:Data encryption transforms information into a secure format, preventing unauthorized access even if the data is compromised. Highly regulated sectors like financial services and healthcare widely adopt advanced encryption to protect sensitive customer data and comply with strict privacy mandates like GDPR.
- Access Management:Access management controls who can access specific data resources and under what conditions.
- Intrusion Detection:Intrusion detection systems monitor network and system activities for malicious actions or policy violations.
- Identity Authentication:Identity authentication verifies the identity of users attempting to access big data systems.
- Compliance Monitoring:Compliance monitoring tools continuously assess systems and data processes against regulatory standards.
Mature deployment sits with Data Encryption. Newer deployment is concentrated in Threat Intelligence.
Deployment Mode:
The operational models for big data security are shaped by organizational infrastructure preferences and scalability needs.
- Cloud-Based:Cloud-based solutions leverage public or private cloud infrastructure for security services, offering scalability and reduced on-premises hardware requirements. Small and medium-sized enterprises increasingly favor cloud-based deployments for cost efficiency and ease of management.
- Managed Security Service:Managed security services involve third-party providers overseeing and managing an organization's big data security operations. This model is particularly attractive to organizations facing talent scarcity in cybersecurity and seeking expert oversight.
- On-Premises:On-premises deployments involve installing and managing security software and hardware within an organization's own data centers.
- Hybrid:Hybrid deployment combines elements of both on-premises and cloud-based security solutions.
- Virtual Appliance:Virtual appliances are pre-configured software packages that run on virtualized environments to provide security functions.
The shift towards operational expenditure models means Managed Security Service is gaining share fastest, while On-Premises installations continue to see declining relative adoption.
Application:
Specific industry applications drive distinct requirements for big data security solutions, reflecting varying data types and regulatory pressures.
- BFSI:The Banking, Financial Services, and Insurance sector handles vast amounts of sensitive financial data, making it a prime target for cyberattacks and mandating robust security for fraud detection and regulatory compliance under HIPAA and GDPR.
- Government:Government agencies manage critical national infrastructure data and classified citizen information, requiring advanced security for national defense and public service integrity against state-sponsored threats.
- Telecommunications:Telecommunications firms protect extensive customer data and network infrastructure from breaches and service disruptions.
- Energy & Utilities:This sector safeguards operational technology and critical infrastructure from cyber threats.
- Manufacturing:Manufacturing companies secure intellectual property, supply chain data, and industrial control systems.
- Media & Entertainment:Media and entertainment entities protect digital content, subscriber information, and intellectual property.
Data privacy regulations like Europe's GDPR heavily influence investments within the BFSI sector. The increasing digitalization of public services is driving demand in the Government sector.
End User:
Big data security adoption varies significantly across different organizational types, influenced by scale, resources, and specific operational needs.
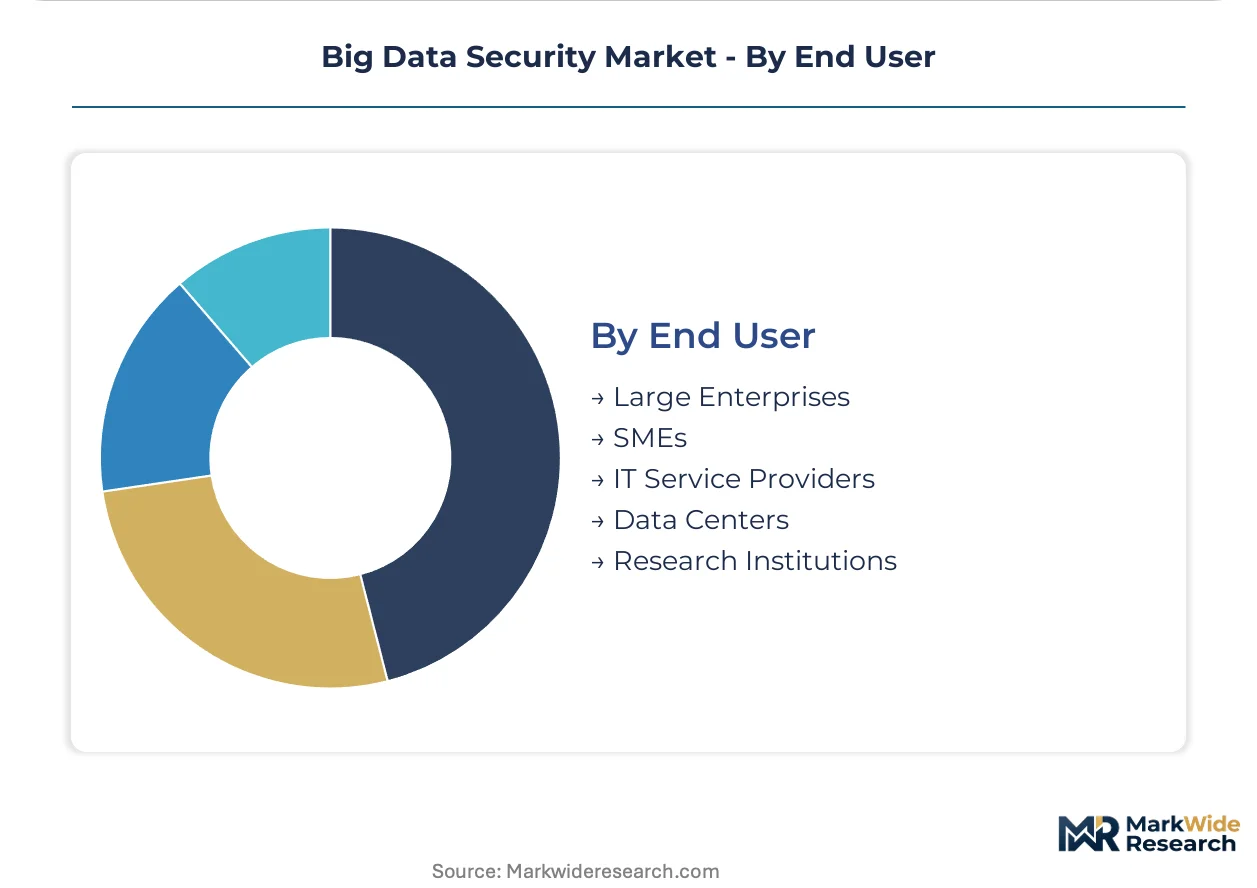
- Large Enterprises:Large enterprises possess extensive data ecosystems and complex IT infrastructures, necessitating comprehensive, integrated security platforms for global operations and stringent regulatory adherence.
- SMEs:Small and medium-sized enterprises face budget constraints and limited in-house security expertise, driving demand for scalable, subscription-based security-as-a-service models.
- IT Service Providers:IT service providers offer security solutions as part of their broader service portfolios to multiple clients.
- Data Centers:Data centers require robust security to protect the physical and virtual infrastructure hosting vast amounts of client data.
- Research Institutions:Research institutions secure sensitive research data, intellectual property, and academic networks.
The fragmentation of the buyer base means SMEs are increasingly adopting big data security, while Large Enterprises maintain high investment levels for complex requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for big data security solutions concentrates in regions with advanced digital infrastructure. The United States leads in solution adoption due to its large technology and financial services industries. Regulatory mandates further compel investment across diverse global economies.
United States
United States demand for big data security is driven by its expansive technology and financial services sectors. HIPAA mandates strict data handling in healthcare, compelling significant security investments. Silicon Valley and Wall Street remain critical innovation hubs, continuously developing advanced security platforms for sensitive data.
Germany
Germany's industrial IoT and automotive sectors necessitate robust big data security solutions. GDPR imposes stringent data protection rules across all industries, particularly impacting data processing. Munich and Berlin are active centers for cybersecurity research, fostering new solutions for complex data environments.
China
China's rapid digitalization of public services and e-commerce growth fuel demand for data protection. The country's Cybersecurity Law influences data localization and cross-border data transfer rules. Shanghai and Shenzhen host significant cloud infrastructure, requiring advanced security for massive datasets.
India
India's expanding BFSI sector and widespread digital transformation initiatives drive substantial big data security needs. The country's evolving data protection frameworks are increasingly mandating secure data handling practices. Bengaluru and Hyderabad are key IT hubs, fostering a growing ecosystem of cybersecurity talent and services.
United Kingdom
United Kingdom financial services and government digital initiatives demand sophisticated big data security. The UK GDPR and other financial regulations enforce stringent data privacy and integrity requirements. London's financial district actively invests in advanced security for high-volume transactional data.
Big Data Security Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized cloud-native security and AI-powered threat intelligence. The market exhibits a tiered structure, with large platform providers alongside niche cybersecurity specialists. Strategic archetypes include integrated cloud solution providers, enterprise compliance experts, and advanced threat detection specialists. Dominant competitive moves involve portfolio diversification into adjacent security services and strategic partnerships for broader market reach.
Integrated cloud solution providers, such as Microsoft, represent a significant archetype, leveraging their extensive infrastructure to offer comprehensive security tools. IBM exemplifies the enterprise-grade compliance and threat intelligence specialist, catering to highly regulated industries with robust platforms. Palo Alto Networks anchors the advanced, automated security operations segment, focusing on complex multi-cloud data environments. These firms continually evolve their offerings to address the escalating complexity of cyber threats and regulatory mandates, ensuring data confidentiality and integrity across distributed systems.
| Leading Market Players |
|---|
| Amazon Web Services |
| IBM |
| Microsoft |
| Oracle |
| Palo Alto Networks |
| Broadcom |
| Cisco Systems |
| Check Point Software Technologies |
| Fortinet |
| Others |
Cost & Logistics Intelligence
Vertically integrated technology giants like Microsoft and IBM drive pricing discipline through bundled offerings, influencing the supply of integrated security solutions. Their extensive cloud infrastructure shapes both the delivery models and cost structures for big data security.
Pricing Analysis
The volume-vs-margin split in big data security shows strong competition in foundational services, while specialized solutions command higher premiums. Subscription-based SaaS models dominate pricing, offering predictable operational spending for enterprises. Price differentiation stems from the level of customization required for complex data environments and the depth of managed security services provided. Pricing softness reflects competition among cloud providers offering integrated security tools. Small and medium-sized enterprises exhibit the highest price sensitivity, seeking cost-efficient cloud-based deployments.
Supply Chain Analysis
Cloud-based platforms and managed security services form the primary distribution model for big data security solutions. Supply concentration centers on major technology hubs like the United States, Germany, and China, where innovation and infrastructure development are robust. The market relies on a continuous supply of highly skilled cybersecurity professionals and advanced cloud computing resources. Regulatory fragmentation across diverse national frameworks, such as China's Cybersecurity Law and Europe's GDPR, presents a structural supply chain risk for vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The big data security market is a vertical-integration race, with major players pursuing deeper integration into cloud infrastructure and AI-powered threat intelligence. This strategy aims to offer comprehensive, end-to-end security solutions for diverse customer needs.
For Market Incumbents: Deepen integration of AI-powered threat intelligence into core security platforms to counter evolving cyber threats. Diversify security portfolios to include specialized edge computing solutions, addressing the proliferation of IoT data and new attack surfaces. Leverage existing cloud infrastructure to offer integrated, comprehensive security tools, protecting market share against niche cloud-native specialists. Investment in talent development programs also mitigates the persistent skill scarcity.
For New Entrants and Emerging Players: Europe's GDPR opens a window for specialized compliance monitoring solutions, particularly for multi-cloud data environments. Target underpenetrated geographies like Southeast Asia with scalable, cloud-based security services tailored for rapid digitalization. Focus on small and medium-sized enterprises (SMEs) by offering subscription-based security-as-a-service models. This approach allows access to enterprise-grade security without significant upfront capital expenditure.
For Investors and Strategic Acquirers: The widespread adoption of homomorphic encryption in financial services is the leading indicator that advanced data protection is moving mainstream. The market offers long-term viability, driven by continuous data proliferation and evolving regulatory mandates. Target specialized cloud-native security firms or AI-powered threat intelligence developers for their innovative capabilities. This strategy addresses the escalating complexity of cyber threats and compliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI into Threat Detection | Enhances predictive threat detection and automated response capabilities for novel cyberattacks. |
| Expand Managed Security Services | Addresses talent scarcity for organizations seeking expert oversight of complex big data security operations. |
| Develop Edge Computing Security | Secures data closer to IoT devices, supporting distributed processing and reducing latency at the network edge. |
| Offer Subscription-Based SaaS Models | Provides cost-efficient, scalable security solutions for small and medium-sized enterprises. |
| Achieve Multi-Jurisdictional Compliance | Enables vendors to address divergent data sovereignty regulations like GDPR and China's Cybersecurity Law. |
Research Approach
SEC filings, cybersecurity industry reports, and academic research formed the secondary backbone for this market analysis. Primary interviews with Chief Technology Officers, IT procurement officers, security architects, and compliance managers provided qualitative insights. This approach integrated both bottom-up and top-down data triangulation to validate market sizing and growth projections. The analysis combined these diverse data points for a comprehensive market view.
Historical trendline analysis informed the initial market projections, supplemented by statistical modeling across the analysis window. The market was segmented by solution type, deployment mode, application, end user, and regional regulatory environment for granular forecasting. Compound annual growth rates were derived from established historical growth patterns and anticipated market shifts. Key forecast inputs included cyberattack frequency and global regulatory enforcement levels.
Caveats apply where rapid technological disruption or unforeseen regulatory shifts could materially shift the outlook. Forecasts reflect a specific set of assumptions regarding market evolution and adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cyber Security As a Service Market
Cybersecurity
Network Detection and Response Market
Cybersecurity
Latin America IoT Security Market
Cybersecurity
Austria Cybersecurity Market
Cybersecurity
Global Email Encryption Market
Cybersecurity
Indonesia Cybersecurity Market
Cybersecurity
South Korea Cybersecurity Market
Cybersecurity
Multi-Cloud Data Protection Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Network Edge Security Solutions Market
Cybersecurity
Europe Cybersecurity Market
Cybersecurity
V2X Cybersecurity Market
Cybersecurity
North America Data Exfiltration Market
Cybersecurity
Chile Cybersecurity Market
Cybersecurity
Data-Centric Security Market
Cybersecurity
Data Center Security Market