
 Digestive Health Drinks Market | 2026-2036
Digestive Health Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Digestive Health Drinks Market Intelligence
The Generally Recognized as Safe (GRAS) notification process managed by the US FDA is redrawing the competitive landscape for probiotic ingredients, favoring companies with substantial R&D capabilities. Danone SA leverages its extensive portfolio of patented bacterial strains to secure broad market access. Yakult Honsha sustains its formidable position through a focused strategy on its single-strain probiotic drink. Nestle SA competes by integrating its functional beverages, like kombucha and kefir, into broader consumer wellness platforms.
Digestive health drinks are functional beverages formulated to support gastrointestinal wellness and balance the gut flora. These products often contain live microorganisms, with probiotic variants specified by Colony-Forming Unit (CFU) counts, or include prebiotics and digestive enzymes for synergistic effects. Probiotic beverages command the largest share of the product type segment, driven by extensive consumer education and clinical validation. Within end users, health enthusiasts represent the fastest-growing demographic, seeking products for proactive wellness rather than just symptomatic relief.
Regulatory scrutiny over health claims is a defining market feature, with bodies like the European Food Safety Authority (EFSA) setting stringent evidence requirements for market entry. In parallel, agencies such as India's FSSAI are establishing specific standards for probiotic foods, influencing formulation and labeling practices. Navigating the disparate and evolving criteria for substantiating gut health benefits remains the central challenge for brand-level strategic planning.
Market Dynamics
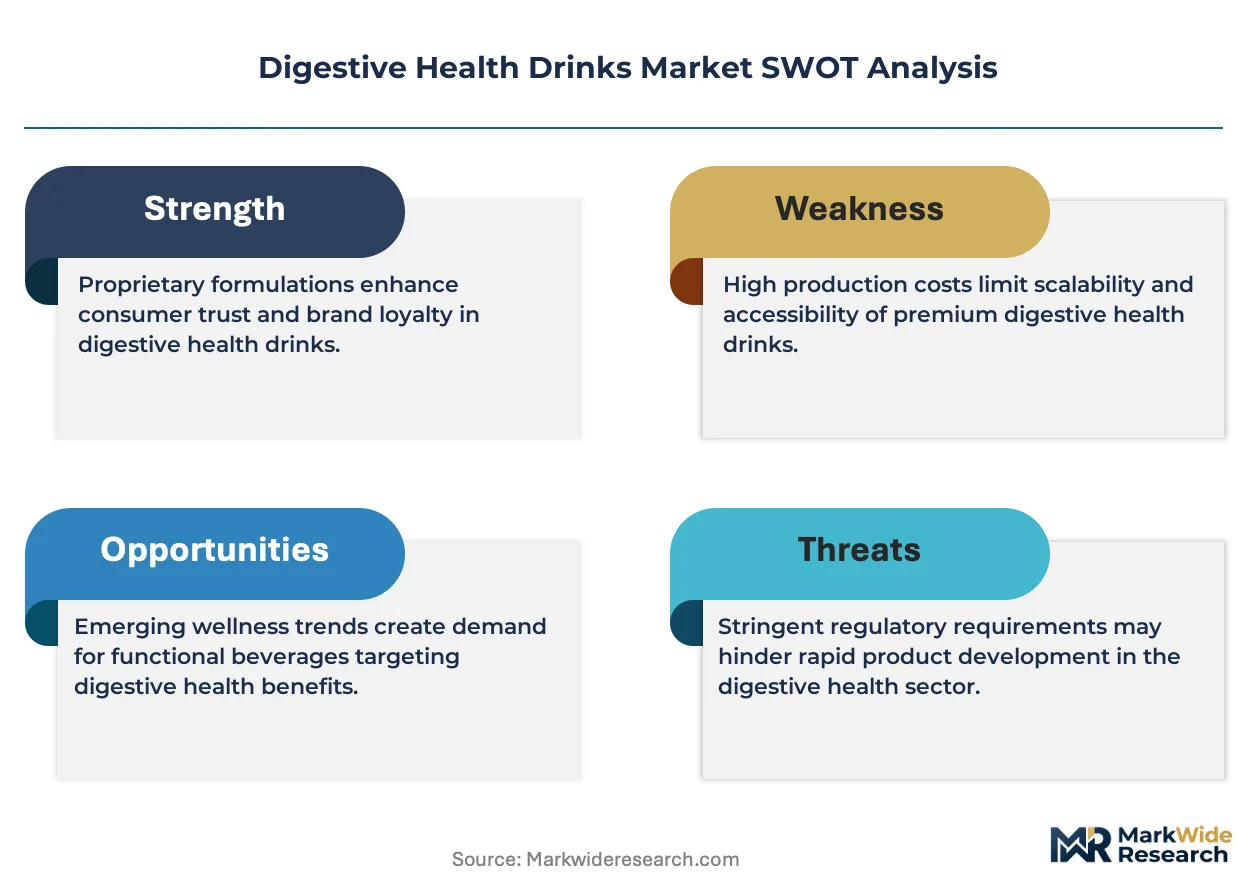
The primary structural force is the tension between stringent regulatory requirements for health claims, particularly from the EFSA, and consumer demand for accessible, preventative wellness products, which is forcing formulation and marketing strategy alignment.
Growth Catalysts
- Precision Fermentation:This technology enables the development of novel, highly targeted probiotic strains, expanding product efficacy and differentiation potential beyond generics.
- Athlete Demand:Demand from athletes and sports nutrition channels is a significant vector, seeking products that aid gut microbiota regulation for improved performance and recovery.
- Government Health Initiatives:Proactive wellness policies, particularly in China, are prioritizing preventative health and boosting consumer spending on functional beverages as part of health strategies.
Market Restraints
- Regulatory Fragmentation:Disparate and evolving criteria for substantiating gut health claims between bodies like the EFSA and the US FDA creates high compliance costs.
- Cold-Chain Dependency:The requirement for refrigerated supply chains to maintain the viability of live cultures adds cost and complexity, limiting distribution reach.
- Ingredient Cost Volatility:The price and availability of specialized prebiotic fibers and patented probiotic strains fluctuate, impacting manufacturer margins and final product pricing.
Strategic Opportunities
- Synbiotic Formulations:Developing products that combine specific probiotics with synergistic prebiotics creates a new premium product tier for educated consumers.
- Personalized Nutrition Platforms:Integrating digestive health drinks into digital health ecosystems that offer personalized strain recommendations based on user data is a key value-add opportunity.
- Expansion in Southeast Asia:Markets with a tradition of fermented foods but low commercial penetration, such as Vietnam and Indonesia, offer growth for localized product offerings.
Industry Challenges
- Claim Substantiation:The rigorous, time-consuming, and expensive clinical trials required by regulators like the EFSA to validate specific health claims is a key hurdle.
- Consumer Education Complexity:Communicating the scientific distinctions between different probiotic strains and CFU counts to a mass audience without causing confusion is a marketing challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestive Health Drinks Market |
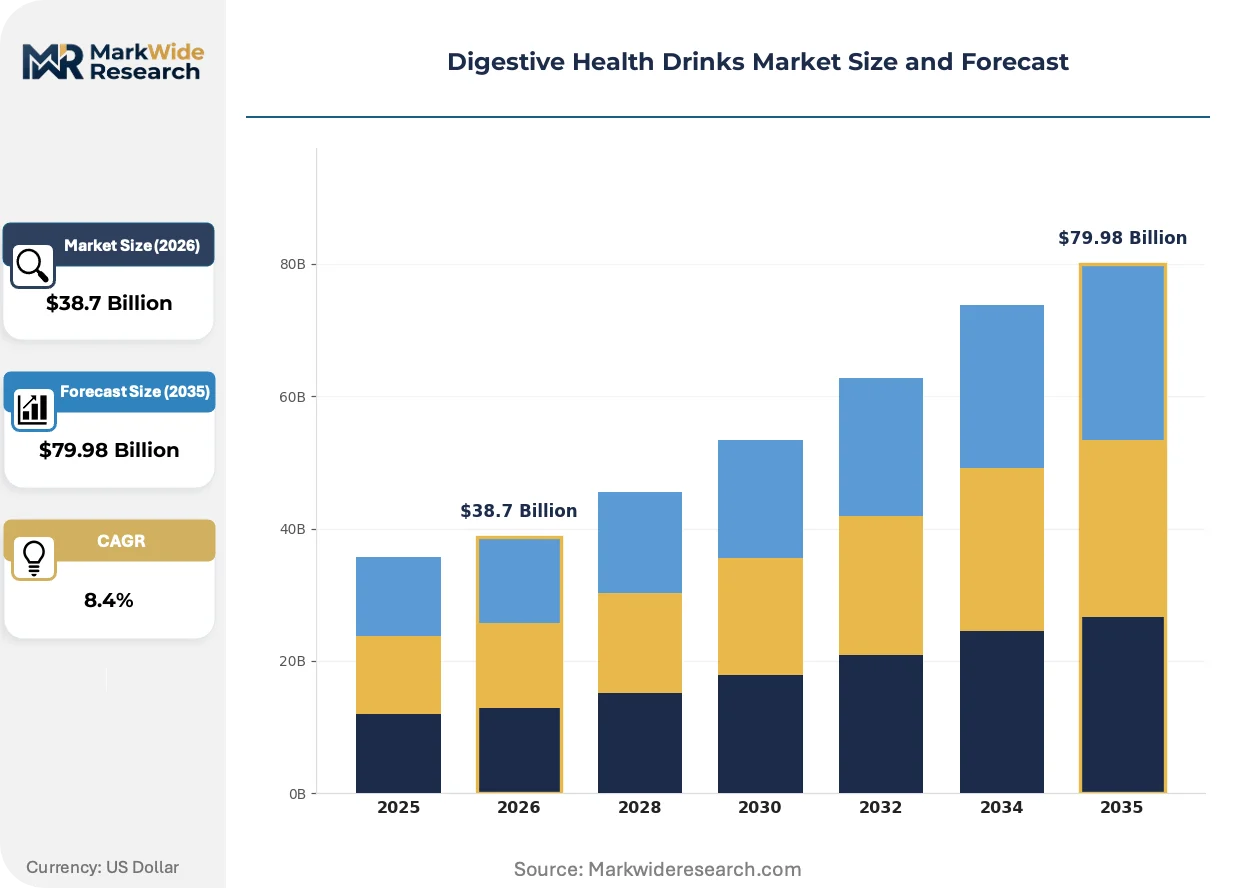
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Beverages, Prebiotic Drinks, Herbal Infusions, Fermented Juices, Enzyme Enhanced Drinks Application: Dyspepsia Relief, Constipation Management, Gut Microbiota Regulation, Irritable Bowel Syndrome Support, Digestive Enzyme Supplementation End User: Health Enthusiasts, Senior Citizens, Athletes, Pediatric Consumers, Wellness Clinics Distribution Channel: Supermarkets & Hypermarkets, Online Retailers, Specialty Health Stores, Pharmacies, Convenience Stores |
| Companies Covered | PepsiCo, Arla Foods, Danone SA, Chobani, Lifeway Foods, Nestle SA, Coca-Cola, GT's Living Foods, Yakult Honsha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestive Health Drinks Market Strategic Shifts & Innovations
The market is maturing as scientific validation and targeted functionality displace generic wellness claims. This evolution is driven by innovations in biotechnology, stricter labeling mandates, and a more discerning consumer base seeking specific health outcomes.
Precision fermentation designs probiotic strains with highly specific metabolic functions for specific benefits. Specialized nutraceutical developers and biotech firms are rapidly adopting this for high-value applications. The technology is bifurcating the product landscape between mass-market, general wellness drinks and clinically-validated, high-potency, targeted formulations.
New labeling rules from agencies like India's FSSAI are mandating greater transparency for probiotic foods, requiring clear strain designation and viable cell counts at the end of shelf life. This regulation compels manufacturers to invest heavily in stability testing and quality control. The dairy-based yogurt and drinkable yogurt segments are most impacted, requiring reformulation.
Consumers are evolving from a general interest in "gut health" toward seeking products that address specific needs such as immunity support, stress reduction, or athletic performance. This shift fragments the mass market and creates opportunities for niche brands. This demand for specificity is prominent among health-conscious consumers in North America.
Digestive Health Drinks Market Segmentation
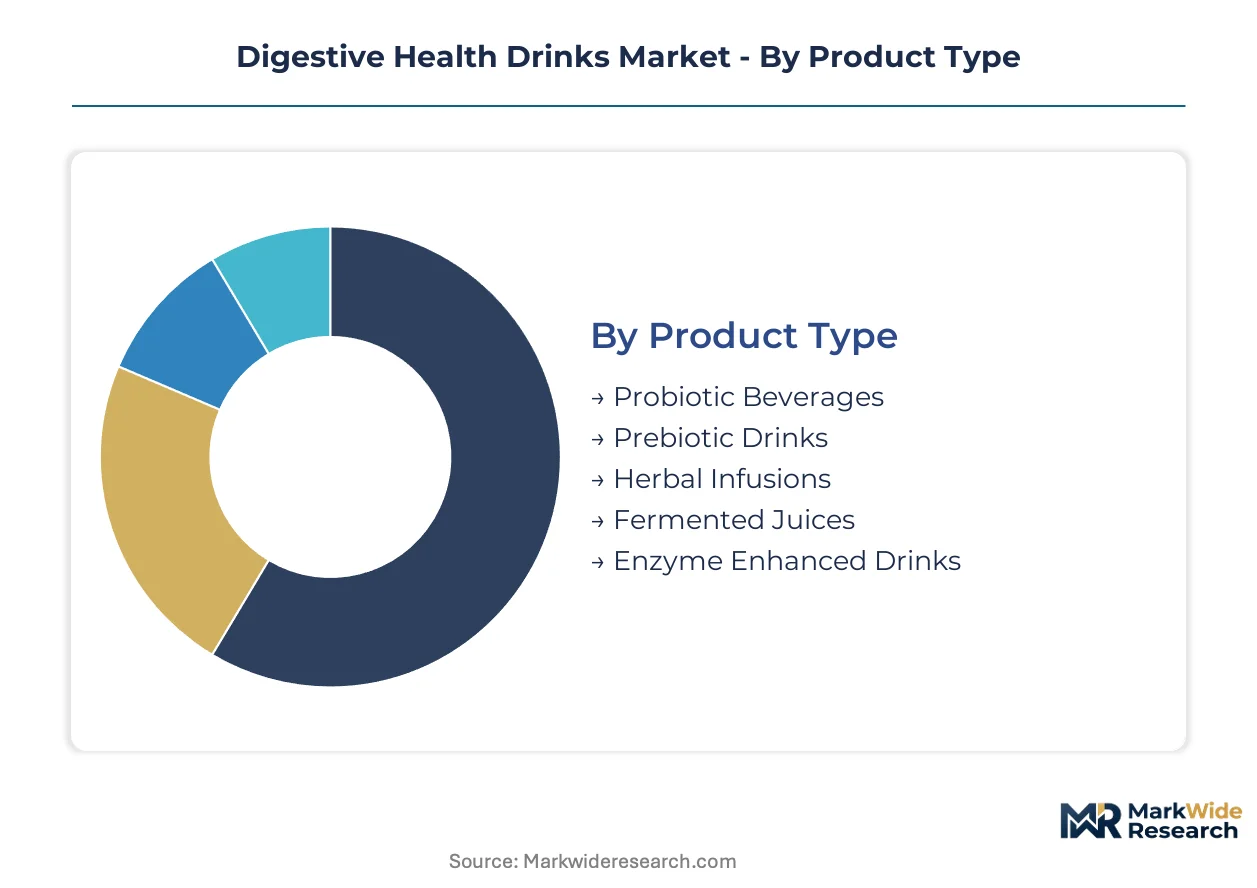
Understanding the segmentation of the digestive health drinks market provides crucial insights into consumer preferences and strategic positioning for manufacturers. This granular analysis reveals where specific product innovations and distribution strategies yield the highest returns, guiding targeted market penetration efforts.
Product Type:
Margin pools within the product type segment often concentrate around specialized, clinically validated formulations that command premium pricing.
- Probiotic Beverages:These functional drinks contain live microorganisms, often specified by Colony-Forming Unit (CFU) counts, designed to support gut flora balance. Demand concentrates widely, driven by extensive consumer education and clinical validation in markets like the US and Japan.
- Prebiotic Drinks:Formulated with non-digestible fibers that nourish beneficial gut bacteria, these beverages support a healthy microbiome. Demand is concentrating as consumers seek synbiotic formulations, often integrated into personalized nutrition platforms.
- Herbal Infusions:These drinks leverage traditional botanical ingredients known for digestive benefits, appealing to consumers seeking natural remedies.
- Fermented Juices:Natural fermentation processes create these beverages, offering diverse nutrient profiles and beneficial compounds for gut health.
- Enzyme Enhanced Drinks:These products include digestive enzymes to assist in breaking down food, targeting consumers with specific digestive challenges.
The dominant share belongs to Probiotic Beverages, while Prebiotic Drinks are closing the gap fastest.
Application:
Volume drivers within application segments are increasingly tied to preventative health and specific condition management, reflecting a shift from general wellness to targeted solutions.
- Gut Microbiota Regulation:Products in this category aim to balance the gut flora for overall digestive wellness and systemic health benefits. Demand is high among athletes and health enthusiasts seeking proactive wellness and improved physiological function.
- Dyspepsia Relief:These drinks are formulated to alleviate symptoms of indigestion, heartburn, and general stomach discomfort. Demand is notable among an aging population and individuals with specific dietary sensitivities in Western Europe.
- Constipation Management:Formulations rich in fiber or mild laxatives provide gentle relief for occasional or chronic constipation.
- Irritable Bowel Syndrome Support:Targeted probiotic strains or specific ingredients address symptoms associated with Irritable Bowel Syndrome (IBS).
- Digestive Enzyme Supplementation:These applications focus on aiding the breakdown and absorption of nutrients, particularly for individuals with enzyme deficiencies.
This segment sees Gut Microbiota Regulation as a foundational requirement, with Irritable Bowel Syndrome Support representing a rapidly expanding niche.
End User:
Customer types within the end user segment reflect a broad spectrum from proactive wellness seekers to those requiring specific therapeutic support for digestive issues.
- Health Enthusiasts:This demographic actively seeks products for proactive wellness, immunity support, and specific health outcomes beyond symptomatic relief. Demand is prominent among health-conscious consumers in North America seeking personalized nutrition platforms.
- Athletes:Athletes use these drinks for gut microbiota regulation, which aids performance, recovery, and immune function, especially within sports nutrition channels. Demand from this group is a significant growth vector.
- Senior Citizens:This demographic seeks products to address age-related digestive issues and maintain overall gut health.
- Pediatric Consumers:Formulations for children focus on gentle digestive support and immunity, often with specific flavor profiles.
- Wellness Clinics:These institutions recommend or prescribe specialized digestive health drinks as part of broader treatment plans.
The consumer base is anchored by Health Enthusiasts, while Athletes shows the most dynamic expansion.
Distribution Channel:
Supply concentration within distribution channels is bifurcating between broad accessibility for mass-market products and specialized consumer engagement for premium offerings.
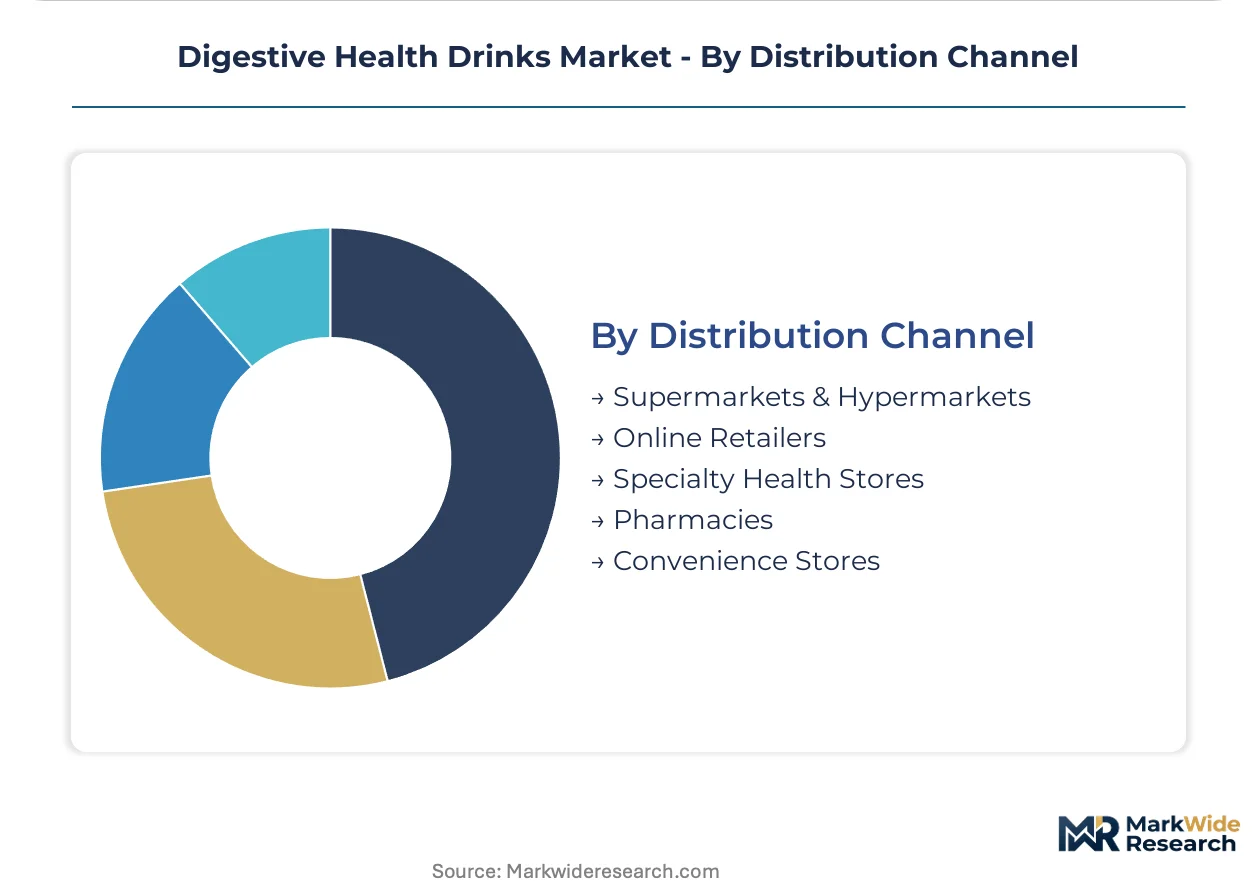
- Supermarkets & Hypermarkets:These channels provide broad accessibility and high volume sales for mass-market digestive health drinks. They serve as primary points of purchase for daily consumption items across China and Europe.
- Online Retailers:E-commerce platforms offer convenience, a wider product selection, and direct-to-consumer models for specialized or subscription-based products. This channel is capturing significant new engagement from younger demographics globally.
- Specialty Health Stores:These outlets cater to informed consumers seeking curated selections and expert advice on functional beverages.
- Pharmacies:Trusted environments like pharmacies distribute digestive health drinks, often those with specific health claims or recommended by professionals.
- Convenience Stores:These stores offer grab-and-go options, providing quick access for impulse purchases of single-serve digestive drinks.
Traditional sales through Supermarkets & Hypermarkets still dominate, but digital channels like Online Retailers are capturing significant new engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health enthusiasts and athletes represent significant buyer archetypes, driving demand across diverse geographies for digestive health drinks. Proactive wellness and performance enhancement motivate consumers to seek functional beverages. Regulatory frameworks are evolving, shaping market access and product development.
China
An expanding middle class and government health initiatives drive significant demand for preventative wellness products in China. Proactive wellness policies boost consumer spending on functional beverages as part of broader health strategies. Major urban centers like Shanghai and Beijing concentrate consumption, with local manufacturers adapting formulations for regional preferences.
United States
Health-conscious consumers in the United States seek products for immunity support and personalized nutrition platforms. The US FDA's GRAS notification process significantly influences market entry and competitive positioning for probiotic ingredients. California's health and wellness hubs lead in adopting targeted functional beverage formulations.
Japan
Extensive consumer education and a strong cultural emphasis on gut health underpin demand for probiotic beverages in Japan. The MHLW sets standards for Foods with Function Claims, impacting product development and labeling. Tokyo and Osaka remain key centers for innovation, particularly in single-strain probiotic drinks from established players.
India
Preventative health trends and a growing awareness of gut benefits drive demand for health drinks across India. India's FSSAI establishes specific standards for probiotic foods, influencing formulation and labeling practices for manufacturers. Metropolitan areas like Mumbai and Delhi show rising consumption of dairy-based probiotic drinks.
Vietnam
A tradition of fermented foods combined with low commercial penetration offers significant growth potential in Vietnam. The MOH regulates food safety and health claims for functional beverages, guiding market entry for new products. Ho Chi Minh City and Hanoi present key urban centers, where localized product offerings can capture new consumer segments.
Digestive Health Drinks Market Key Industry Players
Player mix skews toward established food and beverage conglomerates alongside specialized functional drink producers. The market structure exhibits a tiered consolidation, with large-scale players dominating mass-market segments and niche brands capturing specific consumer needs. Strategic archetypes include diversified portfolios from global giants, single-product focus from heritage brands, and agile innovation from biotech-driven startups. Companies extensively engage in portfolio diversification and strategic partnerships, alongside focused R&D investments, to expand their market reach and secure intellectual property.
On the premium-tier vector, Danone SA exemplifies a diversified approach, leveraging an extensive portfolio of patented bacterial strains to secure broad market access. Yakult Honsha, in contrast, represents a highly focused strategy, sustaining its formidable position through a single-strain probiotic drink, demonstrating the power of brand loyalty. Nestle SA occupies a position integrating its functional beverages, like kombucha and kefir, into broader consumer wellness platforms, showcasing comprehensive portfolio diversification and market penetration.
| Leading Market Players |
|---|
| PepsiCo |
| Arla Foods |
| Danone SA |
| Chobani |
| Lifeway Foods |
| Nestle SA |
| Coca-Cola |
| GT's Living Foods |
| Yakult Honsha |
| Others |
Cost & Logistics Intelligence
Refrigerated inventory days, often exceeding 60-90 days for live culture products, heavily influence both supply chain design and final product pricing power. This cold-chain dependency necessitates specialized logistics and storage, directly impacting operational costs and market accessibility.
Pricing Analysis
Cost-plus contract patterns, often with raw material indexation for specialized ingredients, govern sourcing for many manufacturers. Pricing stratifies across premium, standard, and economy tiers, driven by factors like Colony-Forming Unit (CFU) counts and patented bacterial strains. Clinical validation and specific health claims also enable higher price points. Pricing softness impacts mass-market offerings due to intense competition and ingredient cost volatility. Health enthusiasts exhibit lower price sensitivity for targeted, clinically validated formulations, contrasting with the higher sensitivity of general wellness consumers.
Supply Chain Analysis
China and Japan anchor the supply of specialized probiotic strains and advanced fermentation technologies for digestive health drinks. Raw material dependencies center on patented probiotic strains, specialized prebiotic fibers, and aseptic packaging solutions. Cold-chain dependency represents a significant structural risk, limiting distribution reach and increasing logistics costs, particularly in warmer climates. Distribution runs through broad accessibility channels like supermarkets for mass-market products, while online retailers capture significant engagement for niche and premium offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with personalized nutrition platforms offering strain recommendations expanding faster than core product sales.
For Market Incumbents:Secure intellectual property for novel probiotic strains through sustained R&D investment and robust patent portfolios. Leverage extensive clinical trial capabilities to gain regulatory approvals for specific health claims, especially from bodies like the EFSA. This counters the threat from agile biotech startups offering targeted formulations. Further reinforce existing distribution networks in high-volume channels like supermarkets and hypermarkets.
For New Entrants and Emerging Players:Differentiate on targeted functionality for specific health outcomes, such as stress reduction or athletic performance, moving beyond generic gut health claims. Develop personalized nutrition platforms that integrate user data for tailored strain recommendations, appealing to health-conscious consumers in North America. Target underpenetrated markets in Southeast Asia, such as Vietnam and Indonesia, with localized product offerings and direct-to-consumer models.
For Investors and Strategic Acquirers:Long-term, this sits as a health-tech integration play because digital health ecosystems are increasingly merging with functional food and beverage offerings. Target specialized nutraceutical developers with expertise in precision fermentation and clinical validation capabilities. The signal to watch is the adoption rate of personalized strain recommendation services within broader digital health platforms, indicating market acceptance of integrated solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Precision Fermentation R&D | Develops novel, highly targeted probiotic strains for specific metabolic functions. |
| Pursue EFSA Health Claim Approvals | Establishes clinical validation and market credibility for premium product offerings in Europe. |
| Expand Personalized Nutrition Platforms | Integrates digestive health drinks into digital ecosystems for tailored consumer recommendations. |
| Enhance Cold-Chain Logistics | Improves product stability and expands distribution reach for live culture beverages in emerging markets. |
| Form Strategic Partnerships in Southeast Asia | Leverages local market knowledge and distribution networks in high-growth regions like Vietnam. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, scientific literature, and industry reports. Primary interviews engaged R&D directors, regulatory affairs leads, brand managers, and supply chain logistics specialists across key geographies. This approach ensures bottom-up data validation and top-down market sizing for comprehensive analysis.
The analytical framework models segmentation dimensions including product type, application, end user, distribution channel, and strain specificity over the projection horizon. Compound annual growth rates are derived from historical growth patterns, market share shifts, and future demand projections. Industry-specific forecast inputs include consumer health spending trends and regulatory approval timelines for novel ingredients.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or rapid advancements in competing health technologies would require recalibration. Forecasts reflect assumptions documented throughout the study. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Water Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Keto Ice Cream Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Non-GMO Verified Sports Drink Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Europe Functional Beverages Market