
 Europe Functional Beverages Market | 2026-2036
Europe Functional Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Functional Beverages Market Foresight
Asset-light contract manufacturing and co-packing arrangements is narrowing the capital barrier for mid-sized entrants in the Europe functional beverages space. Danone SA leverages its dairy fermentation infrastructure to dominate probiotic liquid formats. Nestlé SA anchors its position through deep R&D pipelines in personalized nutrition. Red Bull GmbH sustains premium pricing through event marketing and controlled distribution networks.
Europe functional beverages comprise non-alcoholic drinks fortified with bioactive compounds, live cultures, or performance-enhancing substrates formulated to deliver specific physiological benefits beyond basic hydration. Probiotic beverages require controlled cold-chain distribution and specified colony-forming unit counts at consumption to maintain viability. Energy drinks command the largest revenue pool, though herbal teas and functional waters are accelerating fastest as consumers migrate from synthetic stimulants. Sports drinks occupy a mature position with concentrated margin battles among established brands. Health food stores and online retail channels capture expanding margin pools as direct-to-consumer subscription models reduce intermediary costs.
EFSA health claims regulation, EU MDR for novel ingredients, and national food safety authority enforcement collectively determine which functional claims survive on European labels. EFSA's strict substantiation requirements for gut health and immunity claims have forced reformulation toward clinically validated strains and dosages. Stakeholders must monitor evolving novel food approvals under EFSA and adapt ingredient sourcing as REACH chemical restrictions expand into food contact materials.
Market Dynamics
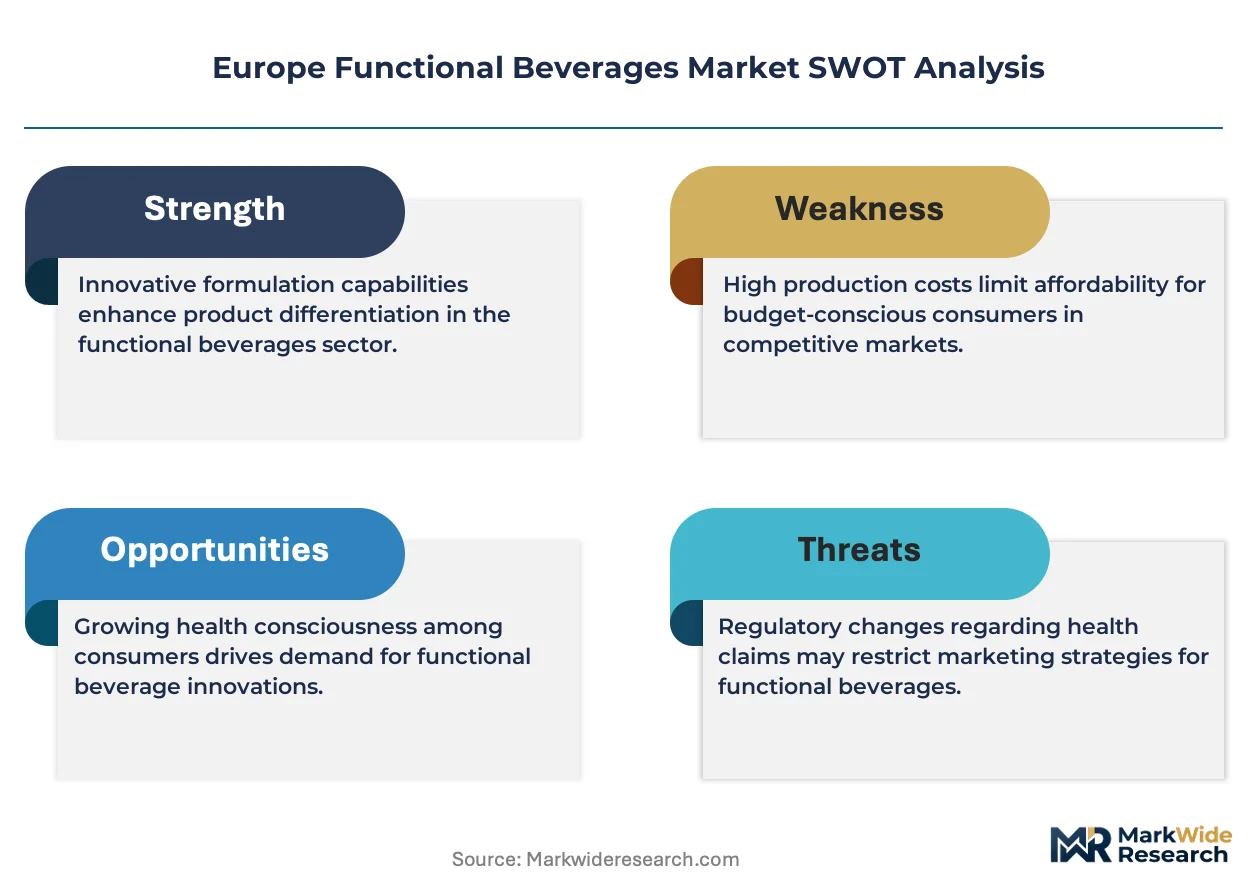
EFSA's substantiation requirements for gut health claims are compressing formulation cycles across Europe. Brands must now secure clinical validation before label deployment, reshaping R&D timelines and ingredient sourcing priorities.
Growth Catalysts
- EFSA Article 13.1 health claims framework:Validated probiotic strains command shelf preference as consumers demand transparency. Manufacturers reformulate around approved bacterial cultures to secure competitive positioning.
- Clean-label migration in Germany and France:Synthetic additive rejection drives natural nootropic and adaptogenic ingredient adoption. Brands pivot from artificial stimulants to botanical extracts.
- Cold-chain infrastructure densification:Live culture viability requirements expand refrigerated logistics networks. Probiotic beverages penetrate convenience retail previously limited to ambient-stable formats.
Market Restraints
- Novel food approval timelines under EU MDR:Unapproved bioactive ingredients face 18-24 month safety evaluation windows. Innovation pipelines stall pending EFSA novel food opinions.
- Lactic acid bacteria supply concentration:Three fermentation technology providers dominate European probiotic strain supply. Ingredient buyers face limited negotiation leverage on pricing and exclusivity terms.
- Aluminum can and rPET input cost volatility:Packaging materials constitute 35-40% of finished goods COGS for functional waters. Margin compression forces trade-offs between sustainable materials and unit economics.
Strategic Opportunities
- Poland and Romania convenience channel underpenetration:Functional beverage per capita consumption trails Western Europe by 60-70%. Localized flavor profiles and price-tiered portfolios capture emerging middle-class demand.
- Direct-to-consumer subscription models:Personalized nutrition algorithms match consumer microbiome profiles to tailored probiotic formulations. Brands bypass traditional retail margin extraction.
- EU Green Deal packaging mandates:Mandatory recycled content thresholds accelerate rPET and aluminum recycling infrastructure investment. Early compliance secures preferential retail listing terms.
Industry Challenges
- Microbiology and formulation science talent scarcity:Strain stabilization expertise commands premium compensation. Smaller brands struggle to attract specialists from pharmaceutical and dairy fermentation sectors.
- Multi-jurisdiction label compliance complexity:National food safety authorities in Italy, Spain, and the Netherlands impose supplemental notification requirements beyond EU baseline. Product launches require parallel regulatory pathways.
- Legacy ERP integration with traceability systems:Batch-level ingredient provenance tracking demands real-time data architecture upgrades. Mid-sized manufacturers face six-figure system implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Functional Beverages Market |
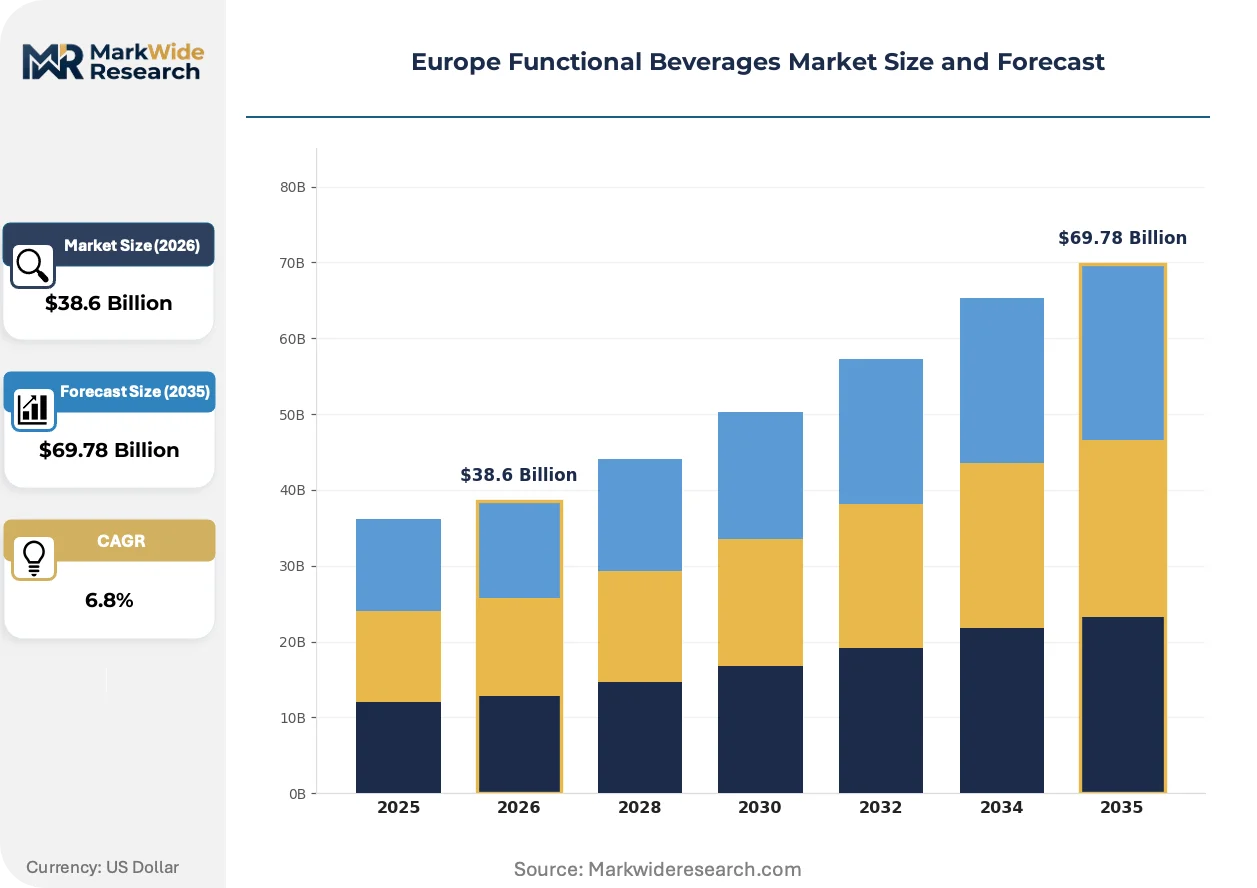
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Energy Drinks, Sports Drinks, Probiotics, Herbal Teas End User: Health-Conscious Consumers, Athletes, Seniors, Busy Professionals Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Ingredient Type: Vitamins, Minerals, Antioxidants, Electrolytes |
| Companies Covered | Danone SA, Nestlé SA, PepsiCo, Suntory Holdings Limited, Keurig Dr Pepper, The Coca-Cola Company, Monster Beverage Corporation, Glanbia PLC, Red Bull GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Functional Beverages Market Shifts & Advancements
Live culture viability monitoring is digitizing quality assurance across European production networks. Real-time colony-forming unit tracking replaces retrospective lab testing, compressing release timelines and reducing spoilage rates.
Blockchain-enabled supply chain verification is digitizing ingredient provenance documentation for probiotic strains. German and Dutch manufacturers deploy distributed ledger systems to satisfy EFSA traceability requirements. Retailers and export markets demand immutable batch records, forcing technology adoption across tier-two suppliers.
REACH chemical restrictions expansion into food contact materials is reshaping packaging material specifications. ECHA substance evaluation lists now capture bisphenol analogues and perfluorinated compounds used in can linings. Brands accelerate migration to epoxy-phenolic and polyester alternatives, with Scandinavian markets enforcing the strictest compliance deadlines.
Health food store buyers are consolidating purchase decisions around clinically substantiated SKUs. Independent retailers in the United Kingdom and France reduce SKU counts by 30-40%, privileging products with EFSA-approved claims. Direct-to-consumer platforms capture displaced volume through subscription bundling and personalized recommendation engines.
Europe Functional Beverages Market Segmentation
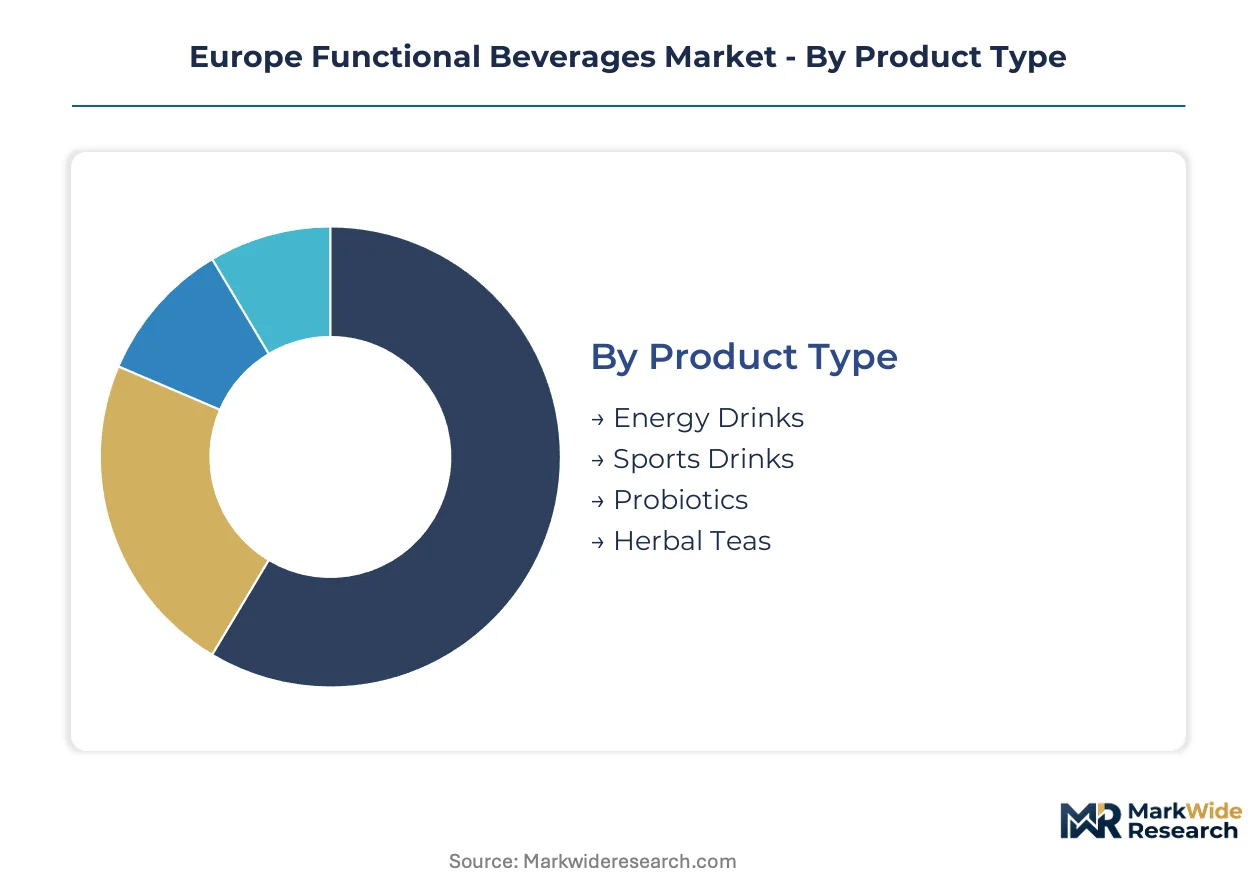
Segmentation in Europe's functional beverages market reveals divergent growth mechanics across consumption occasions and channel economics. Product formulation requirements vary sharply between live-culture probiotic formats and shelf-stable energy drinks, while distribution infrastructure determines viable price positioning.
Product Type:
Consumption occasions span acute performance demands to daily wellness rituals, with formulation science requirements escalating across the spectrum.
- Energy Drinks:Caffeine and taurine formulations dominate immediate consumption channels. German and UK convenience retail accounts for concentrated volume, though synthetic stimulant scrutiny under EFSA guidelines pressures reformulation toward natural alternatives.
- Probiotics:Live culture beverages require controlled cold-chain distribution with specified colony-forming unit viability at consumption. French and Dutch health food stores capture premium pricing as consumers prioritize gut health substantiation under EFSA Article 13.1 frameworks.
- Sports Drinks:Electrolyte replacement formulations serve athletic hydration needs with established penetration in fitness club vending.
- Herbal Teas:Botanical infusions with adaptogenic properties attract clean-label migrators seeking stimulant-free functional benefits.
Established volume favors energy drinks; emerging adoption favors probiotics.
End User:
Purchasing behavior fragments across demographic cohorts with distinct efficacy expectations and price sensitivity thresholds.
- Health-Conscious Consumers:Label literacy drives preference for EFSA-validated claims and transparent ingredient sourcing. German households demonstrate highest willingness-to-pay for clinically substantiated formulations.
- Busy Professionals:Convenience-seeking urban workers prioritize portable formats with immediate cognitive or energy benefits. London and Paris metropolitan areas concentrate demand for on-the-go functional shots and premium energy formulations.
- Athletes:Performance-oriented users demand precise electrolyte ratios and recovery-optimized macronutrient profiles.
- Seniors:Age-related health maintenance focuses on bone density, immunity, and digestive support with softer flavor profiles.
Health-conscious consumers anchor premium pricing; busy professionals drive format innovation.
Distribution Channel:
Channel selection determines margin extraction potential and consumer education depth.
- Supermarkets:Mass-market volume flows through centralized retail with standardized shelf placement fees and promotional calendar dependency. UK and French hypermarket chains enforce strict EFSA compliance documentation for functional claim placement.
- Online Retail:Direct-to-consumer platforms enable personalized subscription models and microbiome-matched probiotic recommendations. Logistics infrastructure investments in Poland and Romania expand addressable markets beyond traditional retail footprints.
- Health Food Stores:Curated SKU selection privileges clinically validated products with trained staff consultation.
- Convenience Stores:Impulse-driven energy drink and functional water purchases concentrate in urban transit corridors.
Supermarkets capture volume scale; online retail captures margin expansion.
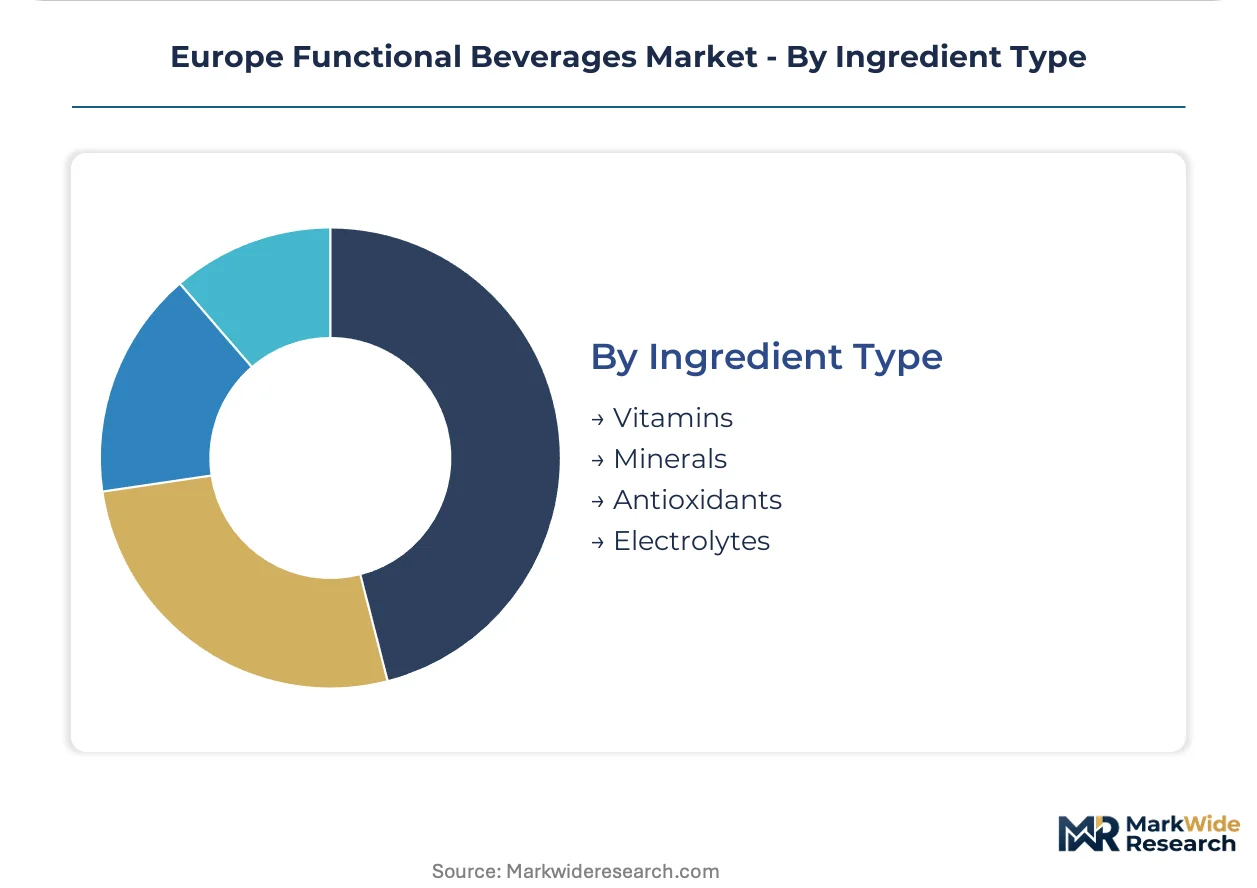
Ingredient Type:
Active compound selection shapes regulatory pathway complexity and substantiation burden.
- Vitamins:Water-soluble and fat-soluble micronutrient fortification requires stability engineering against degradation in liquid matrices. German manufacturers lead encapsulation technology for extended shelf-life vitamin retention.
- Electrolytes:Sodium, potassium, and magnesium formulations serve hydration science with established safety profiles and rapid absorption claims. Sports nutrition applications in Spain and Italy drive Mediterranean market concentration.
- Minerals:Calcium, zinc, and iron fortification addresses deficiency-prevention positioning with bioavailability optimization challenges.
- Antioxidants:Polyphenol and carotenoid extraction from botanical sources demands supply chain traceability under EU Green Deal sustainability mandates.
Vitamins anchor formulation familiarity; antioxidants face the steepest substantiation climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows within Europe favor intra-regional trade over external sourcing, with German and Dutch ports serving as consolidation hubs for probiotic cultures and botanical extracts. Cold-chain logistics investments in Eastern Europe are redirecting distribution patterns away from Western European bottlenecks.
Germany
Health-conscious households in Bavaria and North Rhine-Westphalia drive premium probiotic consumption with strong label literacy. EFSA Article 13.1 health claims enforcement has compressed formulation cycles, forcing brands toward clinically validated strains. Berlin-Brandenburg hosts dense contract manufacturing clusters serving pan-European private label programs.
France
Paris metropolitan demand concentrates on clean-label functional waters and adaptogenic herbal teas with provenance transparency. ANSM notification requirements for novel botanical extracts add regulatory layers beyond EU baseline. The Lyon-Grenoble corridor anchors natural ingredient extraction and fermentation technology R&D.
United Kingdom
London's busy professional cohort sustains premium energy shot and nootropic beverage adoption despite post-Brexit import friction. Divergence from EFSA alignment creates parallel substantiation burdens for brands serving both UK and EU markets. Manchester and Birmingham distribution centers handle increasing direct-to-consumer fulfillment volumes.
Netherlands
Rotterdam port infrastructure supports probiotic strain importation from specialist fermentation houses across the Rhine corridor. REACH chemical restrictions on food contact materials accelerate packaging migration timelines. The Eindhoven region concentrates aseptic filling technology providers serving Benelux functional water brands.
Poland
Warsaw and Krakow emerging middle-class consumers show 60-70% per capita consumption gaps versus Western Europe, creating expansion headroom. EU Green Deal packaging mandates drive rPET recycling infrastructure investment ahead of compliance deadlines. Localized flavor development centers in Wrocław adapt global formulations for regional palate preferences.
Europe Functional Beverages Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in strain development and extraction technology. The vendor base organizes around three strategic archetypes: dairy-derived probiotic platforms, synthetic stimulant energy portfolios, and botanical wellness specialists. Consolidation pressure concentrates among mid-sized brands lacking cold-chain infrastructure or EFSA substantiation capabilities. Dominant competitive moves include co-packing partnerships to bypass capital-intensive manufacturing and microbiome personalization licensing to capture subscription revenue.
Within the dairy fermentation platform tier, Danone SA and Nestlé SA exemplify scale-driven vertical control over live culture supply. Red Bull GmbH occupies a distinct position through event marketing architecture and controlled distribution networks that sustain premium pricing outside commodity energy drink brackets. These three anchors demonstrate how divergent capability foundations—dairy infrastructure, R&D pipelines, and marketing ecosystems—produce non-overlapping competitive moats despite shared category participation.
| Leading Market Players |
|---|
| Danone SA |
| Nestlé SA |
| PepsiCo |
| Suntory Holdings Limited |
| Keurig Dr Pepper |
| The Coca-Cola Company |
| Monster Beverage Corporation |
| Glanbia PLC |
| Red Bull GmbH |
| Others |
Supply & Pricing Matrix
Undercapacity in Eastern European cold-chain infrastructure drives divergent supplier behavior and pricing posture across the Europe functional beverages market. German and Dutch fermentation houses exploit tight live-culture logistics capacity to command premium supply terms, while Polish and Romanian buyers absorb elevated landed costs for refrigerated distribution.
Pricing Analysis
Health-conscious consumers anchor a three-tier pricing structure across premium, standard, and economy levels. EFSA-validated probiotic strains with Article 13.1 claims command brand premiums alongside certified organic botanical inputs. Cost compression in economy-tier energy drinks intensifies because aluminum can and rPET input volatility squeezes COGS. Price-sensitive convenience channel buyers in Southern Europe resist premium migration, while German health food store patrons demonstrate lowest price elasticity.
Supply Chain Analysis
Tariff exposure between post-Brexit United Kingdom and EU member states dominates supply chain risk calculus for pan-European brands. Probiotic strain supply concentrates in Germany, Denmark, and the Netherlands, with botanical extract dependencies drawing from France and Italy. Single-source vulnerability in lactic acid bacteria fermentation technology creates bottleneck exposure. Distribution runs through Rotterdam and Hamburg port consolidation hubs into specialized cold-chain networks serving health food and convenience retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as probiotic penetration in Eastern Europe trails Western benchmarks by substantial margins. Clean-label migration across German and French consumer cohorts accelerates adoption velocity for clinically substantiated formats.
For Market Incumbents: Harden cold-chain infrastructure control through captive distribution investments in Poland and Romania. Secure exclusive strain licensing from Danish and Dutch fermentation specialists to forestall competitor formulation access. EFSA novel food approval timelines represent the critical regulatory threat requiring preemptive clinical trial expenditure.
For New Entrants and Emerging Players: Direct-to-consumer subscription models in the United Kingdom and Germany represent the most penetrable entry point for microbiome-personalized probiotic offerings. Localized flavor development for Polish and Romanian convenience channels captures emerging middle-class demand with limited incumbent saturation. Co-packing partnerships with Berlin-Brandenburg contract manufacturers minimize capital-intensive production buildout.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer probiotic subscription platforms with microbiome-matching algorithms. Long-term viability across the analysis window favors asset-light brands with EFSA substantiation capabilities and cold-chain logistics partnerships. Watch EFSA novel food approval velocity as the signal for ingredient innovation pipeline inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Substantiation | Article 13.1 validation secures shelf placement in German and French health food retail. |
| Cold-Chain Infrastructure Expansion | Refrigerated logistics investments in Poland and Romania unlock per capita consumption gaps. |
| Direct-to-Consumer Platform Launch | Subscription models bypass traditional retail margin extraction in United Kingdom and Netherlands. |
| Sustainable Packaging Transition | EU Green Deal rPET compliance secures preferential listing terms with Scandinavian retailers. |
| Microbiome Personalization Licensing | Algorithm-driven strain matching captures recurring revenue from health-conscious German households. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers, category buyers at health food retailers, cold-chain logistics operators, and fermentation technology specialists and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain planners at German and Dutch probiotic manufacturers alongside regulatory affairs leads navigating EFSA novel food pathways. Secondary sources encompassed EFSA health claims registers, EU MDR submission databases, customs trade flow records, and Nielsen retail audit data across analyzed geographies. Bottom-up volume modeling triangulated against top-down category spend estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type, end-user demographic, distribution channel, and ingredient category alongside regional regulatory cluster differentiation. CAGRs were derived through regression analysis of historical consumption patterns against penetration rate assumptions. Forecast inputs incorporated EFSA approval timeline probabilities and cold-chain infrastructure buildout schedules.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and aluminum commodity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA regulatory velocity and Eastern European retail modernization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Keto Diet Market
Functional Food and Beverage
Low Carb and Low Fat Diet Market
Functional Food and Beverage
GCC Functional Food & Beverage Market
Functional Food and Beverage
South America Functional Beverages Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Reduced Sugar Food and Beverages Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Fermented Protein Market