
 Keto Ice Cream Market | 2026-2036
Keto Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Keto Ice Cream Market Insights
California-based dairy alternative producers is repositioning toward high-fat, low-carbohydrate frozen dessert formats that bypass traditional sugar alcohol limitations. Halo Top leverages its established light-ice-cream infrastructure to anchor a parallel keto product line without dedicated plant investments. Rebel Creamery dominates the ultra-premium segment through specialized erythritol and monk fruit formulations that sustain price premiums above conventional frozen desserts.
Keto ice cream denotes a frozen dessert category formulated with elevated fat content, restricted net carbohydrates, and alternative sweeteners such as erythritol, allulose, or stevia to maintain ketogenic metabolic compliance. The product relies on modified churning processes and stabilizer systems to achieve creamy mouthfeel without sucrose-induced freezing point depression. Dairy-free options are capturing accelerated shelf space allocations as coconut cream and avocado bases resolve texture deficiencies in earlier plant-based iterations. Multipack configurations concentrate margin pools through unit economics that offset higher ingredient costs against conventional single-serve impulse purchases.
FDA nutrition labeling mandates and USDA organic certification pathways shape product development timelines and retail access conditions for emerging entrants. EFSA novel food assessments govern allulose adoption trajectories across European import channels, creating asynchronous regulatory windows between jurisdictions. Stakeholders must monitor sweetener GRAS status revisions and evolving state-level cottage food exemptions that determine small-scale production legality.
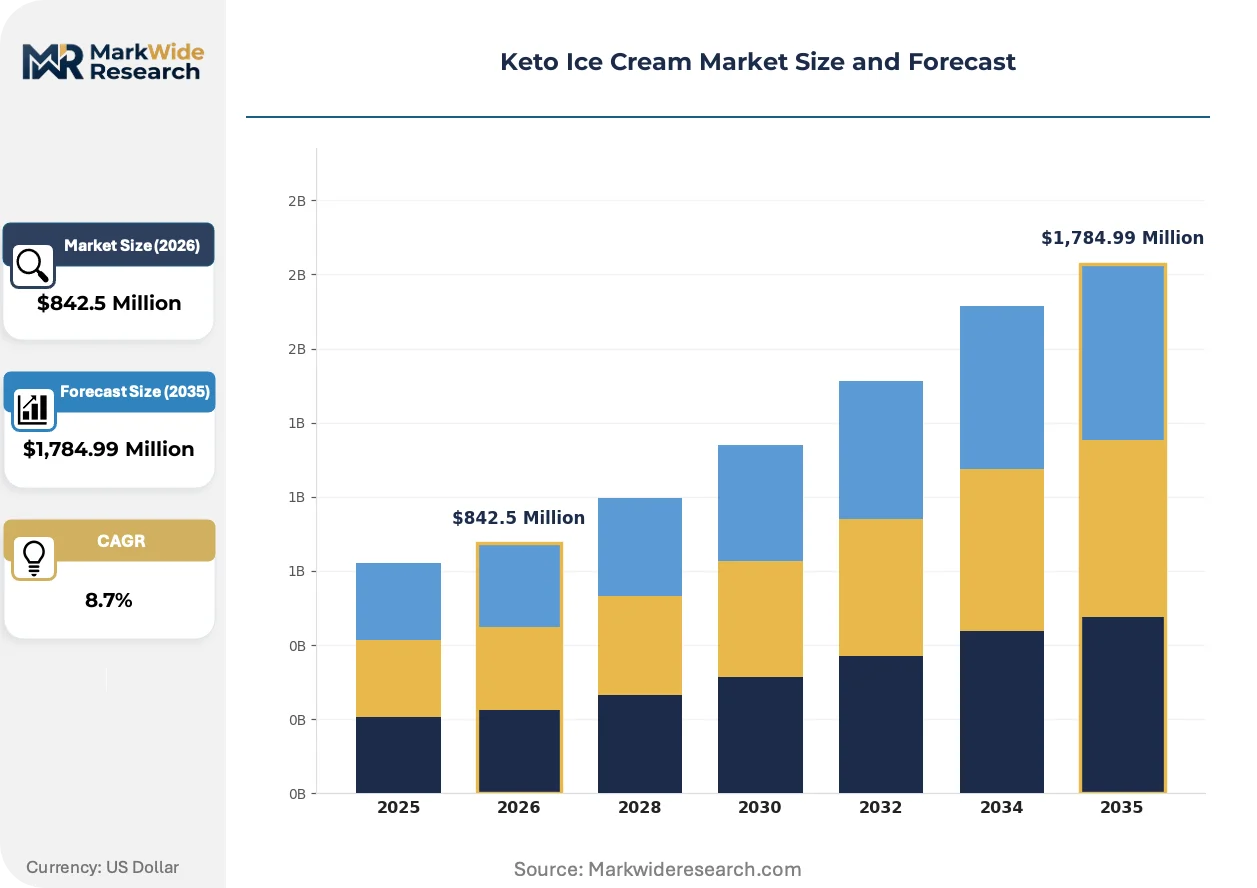
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing reformulation across frozen dessert portfolios, compressing development timelines as manufacturers race to maintain shelf placement while substituting alternative sweeteners.
Growth Catalysts
- Metabolic Health Protocols:Ketogenic dietary frameworks endorsed by functional medicine practitioners are expanding prescriptive consumption beyond weight management into neurological and metabolic condition protocols.
- California Metropolitan Penetration:Specialty grocery density in Los Angeles and San Francisco Bay Area corridors sustains disproportionate velocity for premium frozen dessert SKUs relative to national averages.
- Allulose Regulatory Pathway:GRAS affirmation for allulose sweetener is accelerating clean-label formulation transitions that bypass sugar alcohol gastrointestinal tolerance limitations.
Market Restraints
- Erythritol Input Volatility:Corn-derived feedstock pricing fluctuations and Chinese export concentration for crystalline erythritol create margin compression exposure for cost-sensitive formulations.
- Freezing Point Depression Constraints:Sucrose replacement with high-intensity sweeteners degrades scoopability and texture stability without expensive stabilizer system augmentation.
- EFSA Novel Food Asynchrony:European allulose approval delays relative to FDA timelines fragment product development roadmaps and prevent unified global SKU strategies.
Strategic Opportunities
- Texas Metro Expansion:Dallas-Fort Worth and Houston specialty retail corridors demonstrate underpenetrated velocity potential comparable to California's established performance baselines.
- Direct-to-Home Subscription:Cold-chain logistics maturation enables recurring revenue models that bypass traditional freezer-door competition and build consumption habit formation.
- USDA Organic Certification:Premium tier positioning through organic dairy and alternative sweetener sourcing commands shelf price multiples that offset ingredient cost premiums.
Industry Challenges
- Food Science Talent Scarcity:Formulation expertise spanning cryogenic texture engineering and alternative sweetener synergy optimization commands compensation premiums that strain emerging entrant budgets.
- State Cottage Food Fragmentation:Inconsistent small-scale production exemptions across Texas, California, and New York jurisdictions complicate micro-producer market entry and scaling pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keto Ice Cream Market |
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,784.99 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream Bars, Ice Cream Pints, Scoopable Bowls, Dairy-Free Options Flavor Profile: Chocolate, Vanilla, Strawberry, Mint Chip Packaging Type: Cups, Tubs, Single Serve, Multipacks Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | Rebel Creamery, Halo Top, Enlightened, Keto Pint, Killer Creamery, Mammoth Creamery, So Delicious, Breyers, Cado, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keto Ice Cream Market Trends and Innovations
Alternative sweetener technology maturation and regulatory labeling pressure are converging to reshape frozen dessert formulation architectures, with texture engineering and supply chain cold-chain integrity emerging as decisive competitive variables.
Allulose crystallization control technology is modularizing production scalability for mid-tier manufacturers previously constrained by erythritol cooling sensation limitations. Regional dairy processors in Wisconsin and Pennsylvania are retrofitting existing ice cream lines with modified churning systems at capital expenditure levels below greenfield plant construction. The technology is modularizing entry barriers that historically concentrated keto-format production among specialized co-manufacturers.
EFSA novel food assessment timelines for allulose are compressing European market entry windows relative to FDA-cleared US distribution. Manufacturers with dual-continent ambitions must maintain parallel formulation portfolios pending regulatory harmonization. The EU regulatory friction most acutely impacts allulose-dependent clean-label positioning strategies that sacrifice texture performance in erythritol-only European formulations.
Health-conscious millennial purchasing is consolidating through direct-to-home subscription channels that displace impulse freezer-door transactions. Specialty grocery partners in California and Texas are responding with exclusive flavor collaborations that defend brick-and-mortar relevance against digital-native entrants. The channel rotation is most pronounced in metropolitan markets where cold-chain logistics density enables same-day delivery viability.
Keto Ice Cream Market Segmentation
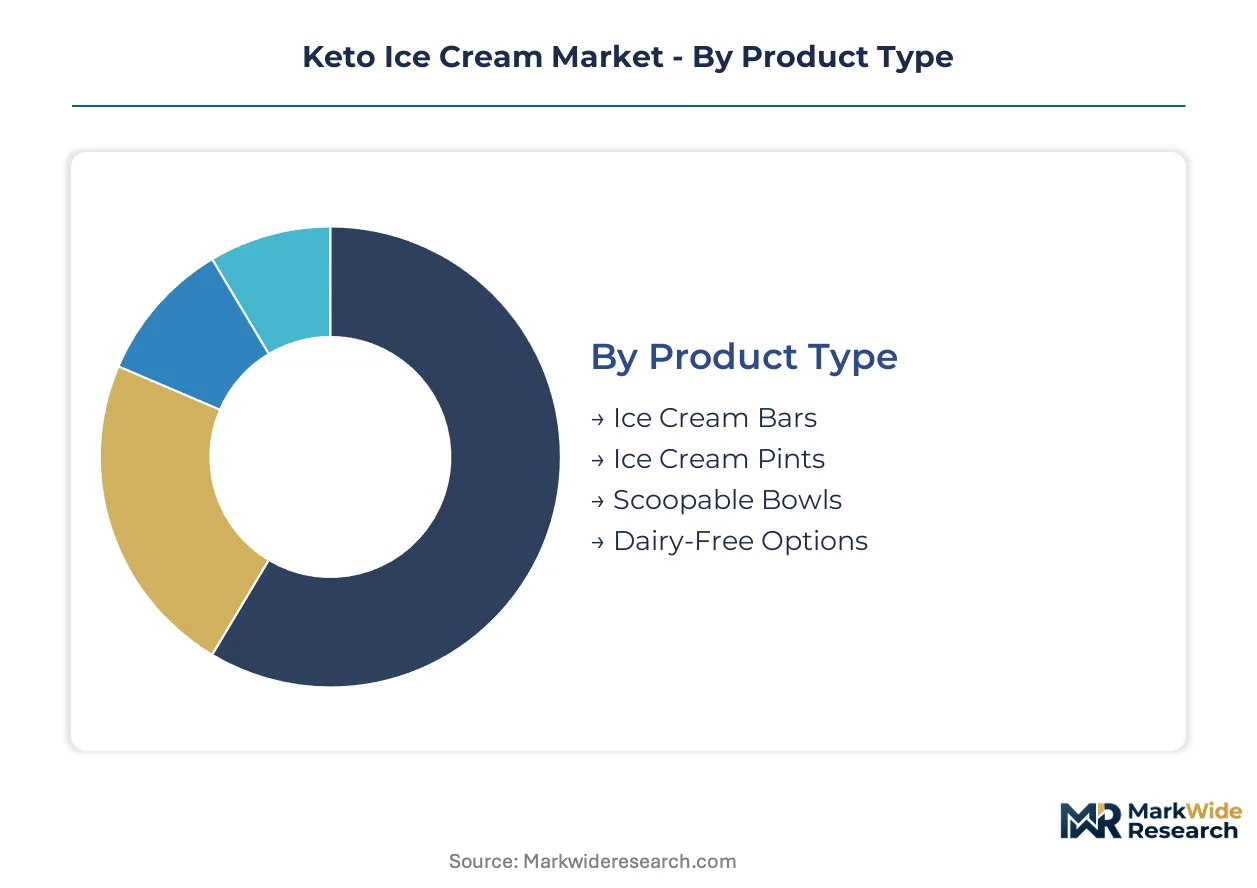
Keto ice cream segmentation reveals how manufacturers balance metabolic compliance with format convenience and channel economics. Product architecture decisions directly determine cold-chain requirements, margin profiles, and retail placement viability across frozen dessert aisles.
Product Type:
Volume concentration favors single-serve impulse formats, while premium positioning clusters around larger pack sizes for at-home consumption rituals.
- Ice Cream Pints:The dominant household stock-up format leverages modified churning processes to maintain creamy texture across freeze-thaw cycles. California and Texas metropolitan households concentrate demand here, driven by subscription replenishment habits and specialty grocery promotional calendars.
- Dairy-Free Options:Coconut cream and avocado base formulations resolve earlier plant-based texture deficiencies while maintaining sub-4g net carbohydrate thresholds. Los Angeles and San Francisco Bay Area corridors show disproportionate velocity for these SKUs relative to conventional dairy keto formats.
- Ice Cream Bars:Portion-controlled formats with built-in stick delivery systems suit convenience channel placement and on-the-go consumption occasions.
- Scoopable Bowls:Ready-to-eat single-serve containers target foodservice and direct-to-home delivery channels with minimal preparation requirements.
Mature deployment sits with Ice Cream Pints. Newer deployment is concentrated in Dairy-Free Options.
Flavor Profile:
Classic profiles anchor retail shelf stability, while limited-edition rotations drive digital channel engagement and subscription retention.
- Chocolate:Cocoa butter fat content aligns naturally with ketogenic macronutrient ratios, reducing formulation complexity for clean-label positioning. FDA added sugar labeling requirements accelerate dark chocolate variant development across US manufacturing facilities.
- Vanilla:The foundational flavor serves as a base for mix-in customization and private-label replication, concentrating volume in conventional supermarket channels.
- Strawberry:Fruit-derived flavoring requires careful carbohydrate accounting to maintain metabolic compliance, limiting formulation flexibility.
- Mint Chip:Chocolate flake inclusions add textural contrast but introduce supply chain complexity for allergen-controlled production lines.
Established velocity centers on Chocolate. Steepest expansion trajectory belongs to Vanilla as private-label penetration accelerates.
Packaging Type:
Cold-chain integrity requirements and retail freezer dimensional constraints shape material selection and unit economics across formats.
- Multipacks:Four-to-six unit configurations concentrate margin pools through improved unit economics that offset higher ingredient costs against single-serve impulse purchases. Texas metro expansion corridors demonstrate particular strength for this format in club and mass retail channels.
- Tubs:Larger family-size containers support scooping rituals and recipe integration, with highest penetration in suburban California households.
- Cups:Individual portion containers suit foodservice and convenience store placement with minimal utensil requirements.
- Single Serve:Grab-and-go formats dominate impulse freezer-door transactions in high-traffic retail locations.
Volume leadership resides with Multipacks. Emerging deployment clusters around Tubs as at-home consumption rituals solidify.
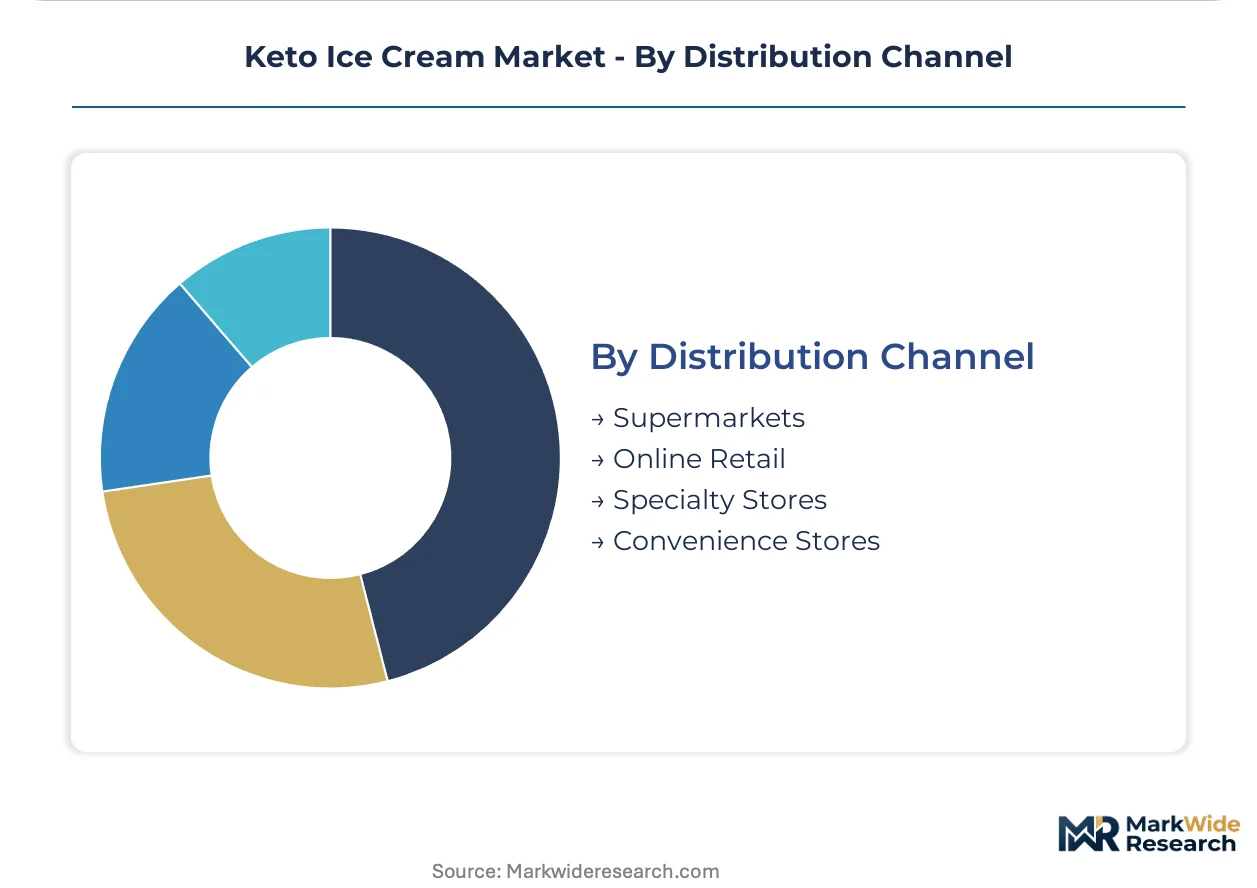
Distribution Channel:
Channel selection determines temperature control investment, promotional spend allocation, and customer data capture capabilities.
- Online Retail:Direct-to-home subscription models bypass traditional freezer-door competition while building consumption habit formation through recurring revenue structures. Cold-chain logistics maturation in Dallas-Fort Worth and Houston corridors enables same-day delivery viability.
- Specialty Stores:Premium positioning and exclusive flavor collaborations defend brick-and-mortar relevance against digital-native entrants in California metropolitan markets.
- Supermarkets:Conventional grocery placement requires slotting fee negotiations and promotional calendar alignment for freezer door visibility.
- Convenience Stores:Limited freezer capacity favors high-velocity single-serve formats with established brand recognition.
Established infrastructure concentrates in Supermarkets. Fastest channel expansion occurs in Online Retail as cold-chain density improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn-derived erythritol feedstock concentration in China and specialty dairy processing infrastructure in the United States anchor regional production capabilities. Cold-chain logistics maturation and metabolic health protocol adoption patterns determine demand distribution across metropolitan corridors.
United States
FDA Nutrition Facts labeling mandates for added sugars accelerate reformulation timelines across frozen dessert portfolios. California and Texas metropolitan areas sustain disproportionate velocity for premium keto SKUs through specialty grocery density and direct-to-home subscription penetration. Los Angeles and Dallas-Fort Worth corridors demonstrate comparable consumption baselines despite divergent retail infrastructure maturation.
Canada
Health Canada regulatory frameworks for novel food ingredients govern allulose importation and labeling protocols. Provincial cottage food exemptions vary across Ontario, Quebec, and British Columbia, complicating small-scale producer scaling pathways. Toronto and Vancouver metropolitan clusters concentrate specialty retail distribution for premium frozen dessert formats.
United Kingdom
FSA novel food assessments and post-Brexit regulatory divergence from EFSA timelines create asynchronous product development windows. London and Southeast England corridors sustain premium positioning for clean-label frozen desserts through specialty grocer partnerships. Manchester and Birmingham retail expansion demonstrates underpenetrated velocity potential relative to established Southern performance.
Germany
EFSA novel food status for allulose remains pending, forcing erythritol-dependent formulations that sacrifice texture performance. Bavaria and North Rhine-Westphalia dairy processing infrastructure supports retrofitting of conventional ice cream lines for ketogenic formats. Berlin metropolitan demand concentrates through organic certification premiums and functional medicine practitioner recommendations.
Australia
FSANZ food standards govern alternative sweetener approval pathways with accelerated timelines relative to European counterparts. Sydney and Melbourne specialty retail corridors demonstrate comparable penetration to North American metropolitan baselines. Queensland and Western Australia expansion remains constrained by cold-chain logistics density limitations.
Keto Ice Cream Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue ultra-premium positioning through specialized formulation architectures. The vendor base distributes across three maturity segments: legacy frozen dessert manufacturers with parallel keto lines, dedicated ketogenic specialists, and dairy-alternative native entrants. Strategic archetypes include scale-driven co-manufacturing partners, formulation-integrated brand owners, and direct-to-consumer subscription operators. Competitive moves concentrate on exclusive flavor collaborations with specialty retailers and cold-chain logistics partnerships for subscription channel viability.
Within the dedicated specialist tier, Rebel Creamery and Halo Top exemplify divergent infrastructure strategies, with the former maintaining specialized production capabilities and the latter leveraging existing light-ice-cream manufacturing footprints. Enlightened occupies a position bridging conventional light-dessert and ketogenic metabolic compliance positioning. These three entities collectively represent the competitive tension between dedicated capital investment and portfolio extension approaches to category participation.
| Leading Market Players |
|---|
| Rebel Creamery |
| Halo Top |
| Enlightened |
| Keto Pint |
| Killer Creamery |
| Mammoth Creamery |
| So Delicious |
| Breyers |
| Cado |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up dairy alternative specialists anchor supply discipline through consolidated procurement of erythritol and monk fruit extracts, translating input cost volatility into tiered pricing power across California and Texas distribution corridors. Their ownership structures prioritize margin defense over volume capture, compressing price competition in the ultra-premium segment while allowing selective discounting in club-channel multipack formats.
Pricing Analysis
Warranty-bundled cold-chain guarantees separate subscription-tier pricing from conventional retail, with direct-to-home operators absorbing logistics risk for recurring revenue lock-in. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status and sweetener grade differentiation. Pricing pressure stems from corn-derived erythritol feedstock volatility originating in Chinese export markets. Club-channel buyers exhibit highest price sensitivity, while functional medicine practitioner recommendations insulate ultra-premium tiers from cost-driven switching.
Supply Chain Analysis
Workforce availability constraints in Wisconsin and Pennsylvania dairy processing regions limit retrofitting velocity for conventional ice cream lines transitioning to keto formats. Crystalline erythritol supply concentrates in China, coconut cream feedstock draws from Southeast Asia, and specialized stabilizer systems originate from European chemical producers. Single-source vulnerability in Chinese erythritol export channels exposes margin compression risk during feedstock price spikes. Distribution runs through cold-chain-consolidated direct-to-home networks in metropolitan California and Texas, supplemented by specialty grocery partnerships in Los Angeles and Dallas-Fort Worth corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Keto ice cream formulation is transitioning from sugar alcohol-dependent architectures toward allulose-centered clean-label platforms, displacing legacy erythritol-heavy recipes as FDA GRAS affirmation matures and gastrointestinal tolerance concerns reshape consumer preferences.
For Market Incumbents: To counter direct-to-home subscription entrants poising recurring revenue capture, Halo Top and Rebel Creamery should deepen exclusive flavor collaborations with Whole Foods and Sprouts Farmers Market while retrofitting existing light-ice-cream infrastructure for allulose formulation flexibility without dedicated plant construction. Cold-chain logistics partnerships with regional dairy processors in Wisconsin and Pennsylvania provide defensive capacity buffers against co-manufacturer queue congestion. For New Entrants and Emerging Players: Technology-first allulose crystallization control systems offer entry wedges for mid-tier manufacturers previously excluded by erythritol cooling sensation limitations. Texas metro expansion corridors in Dallas-Fort Worth and Houston present underpenetrated velocity potential comparable to California baselines, with club-channel multipack placement offering fastest path to volume scale through Costco and Sam's Club buyer engagement. For Investors and Strategic Acquirers: Distressed-cycle entries favor formulation-integrated brand owners with USDA organic certification pathways in California metropolitan corridors, where specialty grocery density sustains premium positioning through slotting fee negotiation leverage. Long-term viability hinges on allulose regulatory harmonization across EFSA and FDA jurisdictions. The signal to watch is European novel food approval timelines, which would unlock unified global SKU strategies and compress European market entry windows for prepared operators.| Strategic Initiative | Industry Significance |
|---|---|
| Allulose Formulation Transition | Clean-label positioning bypasses erythritol gastrointestinal limitations in California and Texas metros. |
| Cold-Chain Logistics Partnership | Same-day delivery viability in Dallas-Fort Worth defends against digital-native subscription entrants. |
| USDA Organic Certification | Premium shelf price multiples offset coconut cream and avocado base ingredient cost premiums. |
| Exclusive Retailer Collaboration | Sprouts Farmers Market and Whole Foods partnerships anchor brick-and-mortar relevance against direct-to-home displacement. |
| Regional Dairy Processor Retrofit | Wisconsin and Pennsylvania line modifications reduce capital expenditure versus greenfield plant construction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with frozen dessert brand managers, category buyers at specialty grocers, cold-chain logistics operators, food science formulation directors, and functional medicine practitioners. FDA GRAS notifications, EFSA novel food assessments, and USDA organic certification databases provided regulatory trajectory validation. Bottom-up SKU velocity modeling triangulated against top-down metabolic health protocol adoption estimates across metropolitan corridors.
Granularity-level modeling distinguished between pint, multipack, and single-serve formats while tracking dairy versus dairy-free base compositions and chocolate versus vanilla versus rotational flavor profiles across the projection horizon. CAGRs derived from price-quantity elasticity functions applied to subscription channel penetration curves and specialty grocery expansion timelines. Erythritol feedstock pricing volatility and allulose regulatory approval status served as scenario-weighting variables.
Several conditions sit outside the modeled scope, including state-level cottage food exemption revisions that could alter micro-producer competitive intensity, and abrupt EFSA allulose approval accelerations that would compress European entry windows. Forecasts reflect assumptions about cold-chain logistics density maturation and metabolic health practitioner endorsement continuity. Material deviation in Chinese erythritol export policy or FDA sweetener GRAS status revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Low-Fat and Low Cholesterol Diet Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Japan Functional Drinks Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Instant Protein Beverages Market