
 Europe Health Drinks Market | 2026-2036
Europe Health Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Health Drinks Market Insights
Aftermarket wellness subscription revenue is tilting toward direct-to-consumer replenishment models. Nestlé SA leverages its pharmaceutical-nutrition heritage to sustain credibility in clinically positioned beverages. Danone SA anchors its European portfolio through fermented functional drinks with live culture claims. Red Bull GmbH competes in the energy-health crossover segment with sugar-adapted variants.
Europe health drinks comprise non-alcoholic beverages formulated with bioactive compounds, vitamins, minerals, or botanical extracts intended to deliver targeted physiological benefits beyond basic hydration, typically processed through cold-aseptic filling or high-pressure processing to preserve nutrient integrity. Functional drinks lead volume contribution as consumers prioritize immunity support and gut health claims, while herbal teas capture premium margin pools through organic certification and single-origin sourcing. Smoothies represent the fastest-growing format as refrigerated distribution networks expand across urban centers.
EFSA novel food approvals govern ingredient legitimacy for health claims, while EU Green Deal packaging mandates and F-Gas Regulation refrigeration standards shape production infrastructure choices. EMA cross-border frameworks influence borderline pharmaceutical-drink classifications in several member states. Stakeholders must monitor evolving nutrient profiling thresholds under the EU Farm to Fork Strategy to anticipate reformulation obligations.
Market Dynamics
EFSA novel food approvals and EU sugar reduction targets are compressing formulation cycles, forcing manufacturers to rebuild ingredient matrices around validated bioactive compounds while maintaining sensory profiles that retain retail shelf placement.
Growth Catalysts
- EFSA novel food pathway:Accelerated approvals for postbiotic and fermented botanical extracts enable faster claim substantiation across Germany, France, and Netherlands retail channels.
- Fitness-oriented millennials:Sustained demand for protein-fortified and electrolyte-replenishment formats drives volume in urban gym and studio distribution networks.
- Cold-aseptic filling:Extended ambient shelf life without thermal degradation preserves vitamin stability in functional drinks targeting pharmacy and convenience channels.
Market Restraints
- Live culture supply concentration:Dependence on Danish and Dutch fermentation specialists creates input bottlenecks for probiotic-positioned SKUs during facility maintenance cycles.
- EU Green Deal packaging mandates:Mandatory recycled content thresholds and extended producer responsibility fees inflate unit economics for single-serve formats.
- Botanical extract standardization:Polyphenol potency variability across harvest batches forces conservative dosing that undermines label claim differentiation.
Strategic Opportunities
- Poland and Romania convenience modernization:Refrigerated distribution infrastructure gaps in secondary cities create first-mover advantage for ambient-stable functional drink entrants.
- EU Farm to Fork nutrient profiling:Anticipated thresholds for sugar and salt content position ahead-of-curve reformulators for front-of-pack labeling preference.
- High-pressure processing plus nitrogen dosing:Converging technologies enable clean-label preservation with extended ambient stability, collapsing cold-chain dependency for direct-to-consumer subscription models.
Industry Challenges
- Clinical trial design expertise:Shortage of nutrition scientists capable of structuring EFSA-compliant human intervention studies delays claim substantiation timelines.
- Legacy ERP integration:Batch-level traceability requirements for novel food ingredient genealogy strain existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Health Drinks Market |
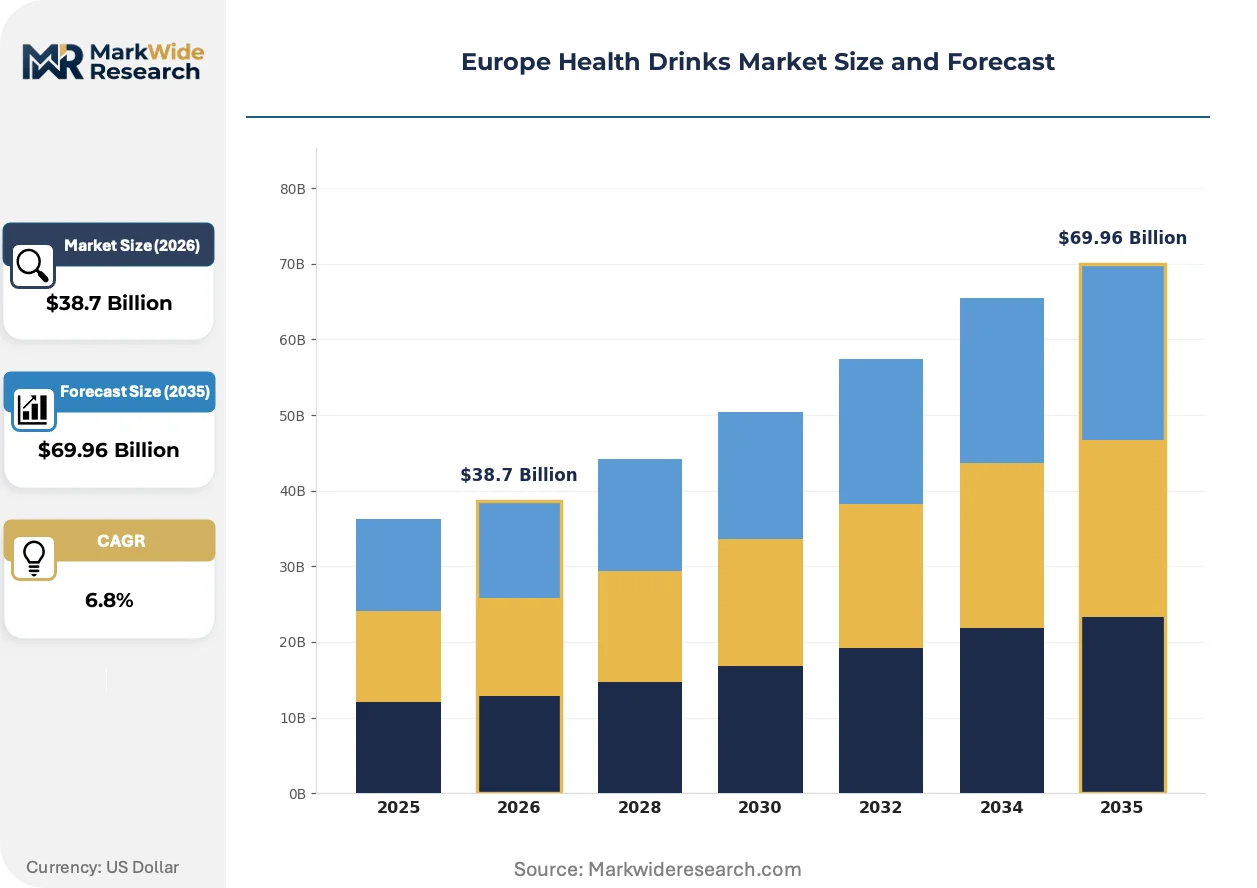
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juices, Smoothies, Herbal Teas, Functional Drinks End User: Health Conscious Consumers, Athletes, Weight Watchers, Seniors Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Cafes Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Nestlé SA, PepsiCo Inc., Red Bull GmbH, Danone SA, The Coca-Cola Company, Suntory Holdings Limited, Oatly Group AB, Monster Beverage Corporation, Biona Organic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Health Drinks Market Trends and Innovations
Cold-chain alternatives and bioactive stabilization technologies are redrawing production geography, while regulatory claim substantiation requirements elevate clinical validation above marketing expenditure in competitive positioning.
High-pressure processing is collapsing the traditional trade-off between nutrient preservation and distribution reach. Ambient-stable probiotic and enzyme-fortified drinks now reach pharmacy and convenience channels previously reserved for pasteurized alternatives. German and French manufacturers are retrofitting lines to capture margin compression from eliminated refrigeration costs.
EU Green Deal packaging mandates and F-Gas Regulation refrigeration standards are restructuring capital allocation across production networks. Manufacturers face simultaneous pressure to eliminate hydrofluorocarbon-based cooling and incorporate minimum recycled plastic content. Cold-aseptic filling investments in Spain and Italy are accelerating as facilities seek compliance pathways that preserve operational flexibility.
Subscription-based replenishment is displacing traditional retail replenishment cycles among urban professionals. Direct-to-consumer platforms in London, Berlin, and Paris offer personalized functional drink stacks based on biometric data integration. This channel shift concentrates customer lifetime value data with brands while fragmenting traditional supermarket negotiating leverage.
Europe Health Drinks Market Segmentation
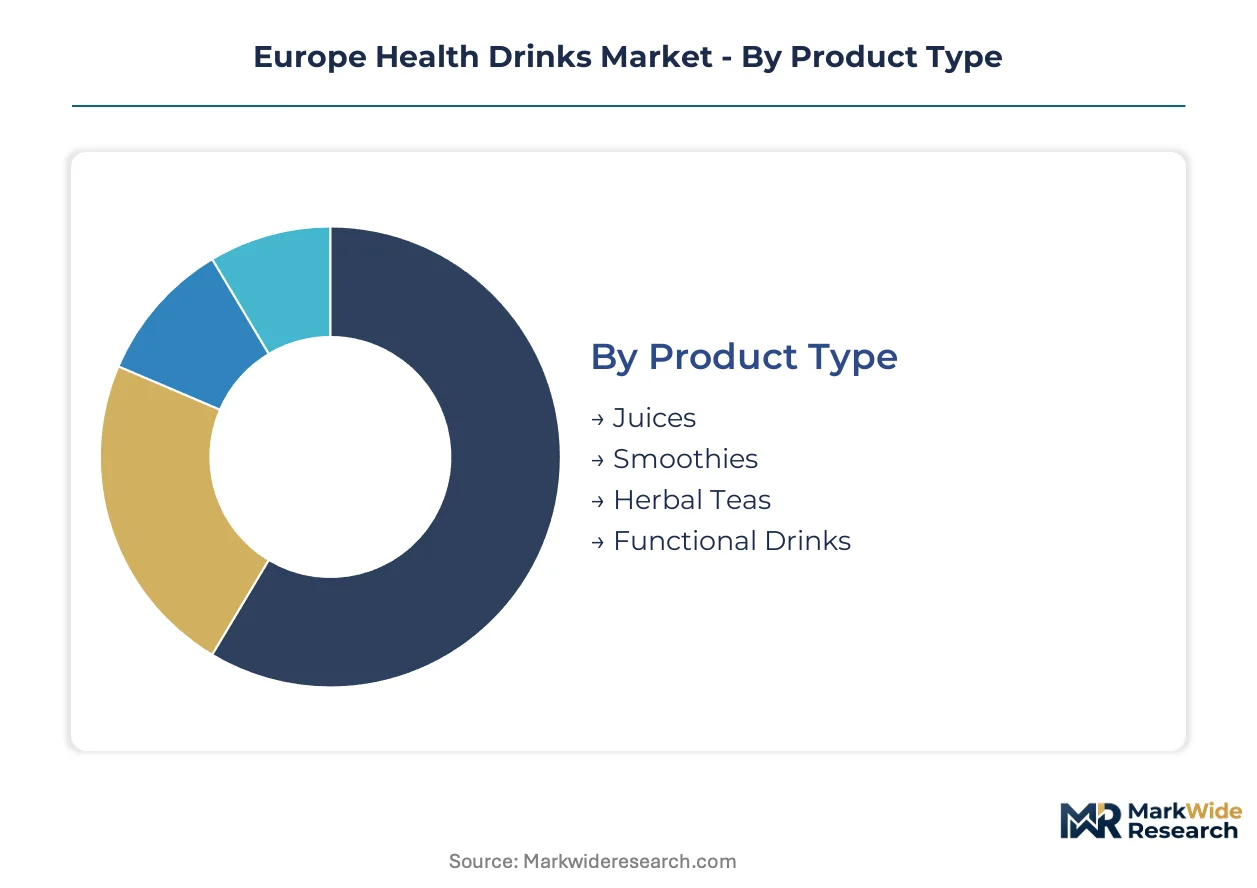
Segmentation in the Europe health drinks market reveals how formulation priorities, channel economics, and demographic targeting fragment revenue capture. Manufacturers must align cold-chain capabilities and claim substantiation investments with specific consumption occasions to defend shelf placement.
Product Type:
Use-case spectrum spans daily wellness maintenance through targeted performance recovery, with each format demanding distinct processing investments and distribution infrastructure.
- Functional Drinks:Bioactive-fortified beverages with validated health claims processed through cold-aseptic filling or high-pressure processing. Demand concentrates in German and French pharmacy channels where EFSA-approved immunity and gut health positioning commands premium placement.
- Smoothies:Refrigerated fruit and vegetable blends with live enzyme retention and extended ambient stability via nitrogen dosing. Urban professionals in London, Berlin, and Paris drive adoption through direct-to-consumer subscription replenishment models.
- Herbal Teas:Botanical-infused beverages with organic certification and single-origin sourcing credentials.
- Juices:Cold-pressed or HPP-treated fruit extracts targeting clean-label positioning in premium retail.
Established volume favors functional drinks; emerging adoption favors smoothies.
End User:
Customer archetypes diverge sharply in their sensitivity to clinical validation versus sensory preference and price accessibility.
- Health Conscious Consumers:Broad demographic prioritizing preventive wellness and ingredient transparency. French and German urban centers show concentration in organic-certified and low-sugar formulations aligned with EU Farm to Fork nutrient profiling anticipation.
- Athletes:Performance-oriented users demanding electrolyte replenishment, protein fortification, and rapid absorption profiles. Gym and studio distribution networks in Netherlands and Spain sustain volume for isotonic and recovery-positioned SKUs.
- Weight Watchers:Calorie-controlled segment seeking satiety signaling and metabolic support claims.
- Seniors:Demographic prioritizing bone health, cognitive function, and medication interaction safety in pharmacy-channel purchases.
Revenue concentration sits with health conscious consumers; steepest expansion trajectory belongs to athletes.
Distribution Channel:
Channel economics determine refrigeration requirements, margin structures, and the feasibility of personalized replenishment models.
- Supermarkets:Mass retail commanding scale economies and front-of-pack labeling visibility. German and French chains drive volume for ambient-stable functional drinks with EFSA-compliant health claims.
- Online Retailers:Direct-to-consumer platforms enabling subscription stacks and biometric data integration. London, Berlin, and Paris urban professionals concentrate here, collapsing traditional wholesale negotiating leverage.
- Health Food Stores:Specialty retail prioritizing organic certification and novel ingredient introduction.
- Cafes:Immediate consumption channel for fresh-blended and premium-positioned formats.
Scale advantages favor supermarkets; margin expansion favors online retailers.
Packaging Type:
Packaging selection balances EU Green Deal compliance costs, shelf-life engineering, and consumer convenience expectations.
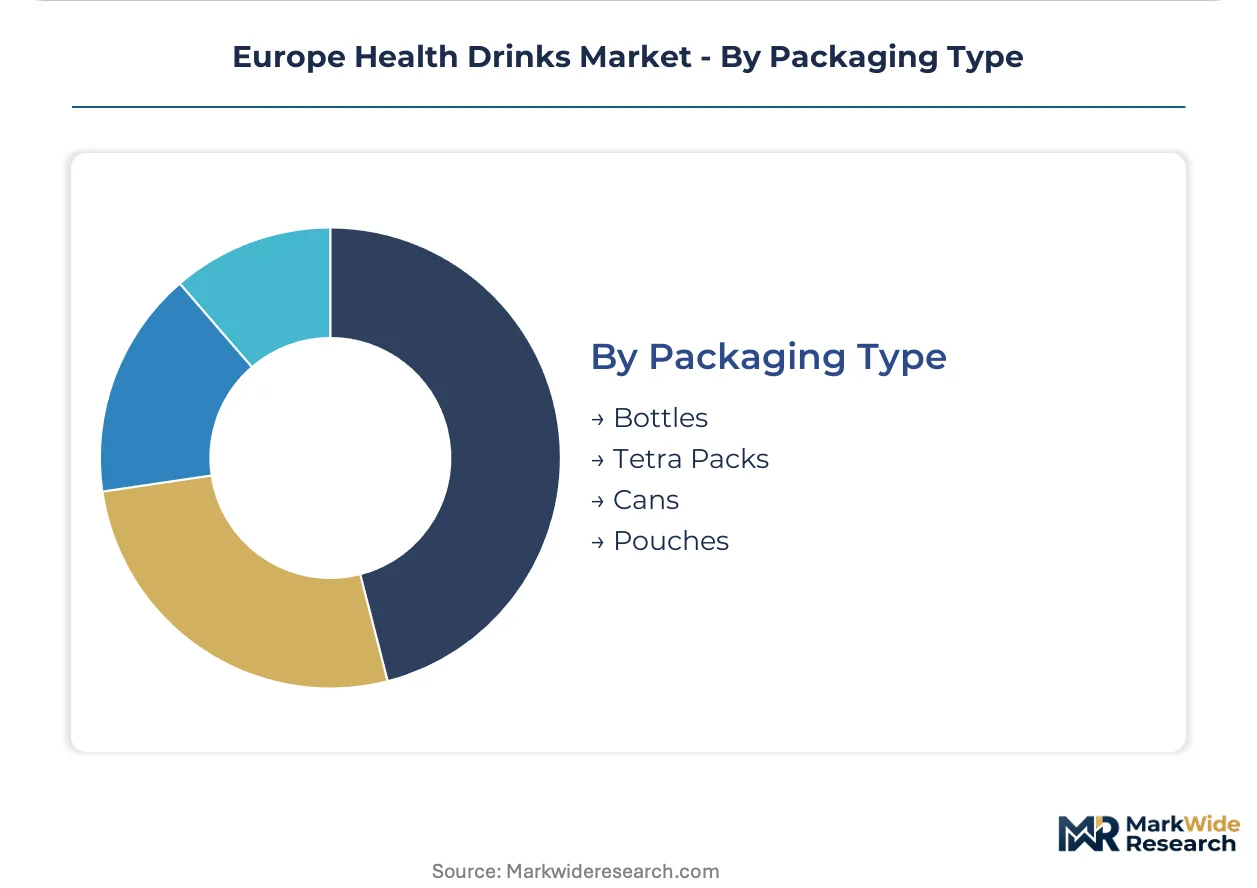
- Bottles:Recycled PET and glass formats dominating premium functional drink positioning. Italian and Spanish manufacturers retrofit lines to meet mandatory recycled content thresholds while preserving cold-aseptic filling compatibility.
- Tetra Packs:Aseptic carton systems enabling ambient distribution without refrigeration infrastructure. Poland and Romania secondary cities show adoption where cold-chain gaps persist.
- Cans:Aluminum formats gaining share in energy-health crossover segments.
- Pouches:Flexible packaging for single-serve portability and reduced material intensity.
Operational flexibility favors bottles; cost adaptation for regulatory compliance favors Tetra Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish and Romanian buyers exhibit the sharpest price elasticity, squeezing margins on imported functional drinks, while German and French consumers absorb premiums for EFSA-validated health claims with minimal volume attrition.
Germany
Fitness-oriented millennials in Berlin and Munich sustain demand for protein-fortified recovery drinks through gym-studio distribution networks. EFSA novel food approvals govern ingredient legitimacy for immunity and gut health positioning. The Baden-Württemberg cluster hosts cold-aseptic filling retrofits that preserve vitamin stability for pharmacy-channel placement.
France
Health-conscious consumers in Paris prioritize organic-certified formulations aligned with anticipated EU Farm to Fork nutrient profiling thresholds. ANSM borderline classifications influence pharmaceutical-drink distinctions in several metropolitan zones. The Île-de-France region concentrates direct-to-consumer subscription platforms leveraging biometric data integration.
Netherlands
Live culture supply dependence on domestic fermentation specialists creates input bottlenecks for probiotic SKUs during facility maintenance cycles. F-Gas Regulation refrigeration standards accelerate hydrofluorocarbon phase-out in processing infrastructure. The Randstad corridor anchors refrigerated distribution modernization serving urban professional demand.
Poland
Convenience modernization gaps in secondary cities create first-mover advantage for ambient-stable functional drink entrants with Tetra Pack compatibility. EU Green Deal packaging mandates inflate unit economics for single-serve formats. The Warsaw metropolitan area drives volume for economy-tier positioning in supermarket mass retail.
Spain
Athlete demand for electrolyte replenishment and rapid absorption profiles sustains isotonic volume through gym networks in Barcelona and Madrid. EMA cross-border frameworks influence borderline pharmaceutical classifications in several autonomous communities. Catalonia hosts cold-aseptic filling investments seeking compliance pathways that preserve operational flexibility.
Europe Health Drinks Market Competitive Landscape
Pharmaceutical-nutrition heritage conglomerates and fermented functional specialists split the market between clinically positioned credibility and live culture authenticity. Consolidation pressure concentrates around EFSA claim substantiation capabilities and cold-chain infrastructure ownership. Three archetypes dominate: legacy food-science multinationals with pharmaceutical divisions, dairy-origin fermentation houses, and energy-drink crossovers adapting sugar-reduced variants. Competitive moves center on high-pressure processing line acquisitions and direct-to-consumer platform buildouts.
Within the pharmaceutical-nutrition tier, Nestlé SA and Danone SA exemplify divergent heritage applications. Nestlé leverages its clinical credibility heritage toward validated bioactive positioning. Danone anchors through fermented functional drinks with live culture claims. Red Bull GmbH occupies the energy-health crossover segment, representing sugar-adapted variant adaptation. These three illustrate how formulation legitimacy sources—clinical validation, fermentation authenticity, and performance heritage—map to distinct consumer trust architectures.
| Leading Market Players |
|---|
| Nestlé SA |
| PepsiCo Inc. |
| Red Bull GmbH |
| Danone SA |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Oatly Group AB |
| Monster Beverage Corporation |
| Biona Organic |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's cold-aseptic filling cluster shapes downstream pricing power through vitamin-stability capabilities that command pharmacy-channel premiums. Danish and Dutch fermentation specialists concentrate live culture supply, creating input bottlenecks that propagate through probiotic SKU pricing during facility maintenance cycles.
Pricing Analysis
Aftermarket wellness subscription revenue drives lifetime value through direct-to-consumer replenishment models. Three-tier pricing structure across premium, standard, and economy levels stratifies by EFSA claim validation and organic certification tier. Cost compression in economy-tier supermarket positioning intensifies because Polish and Romanian buyers exhibit sharp price elasticity. Athletes in gym-studio channels show least price sensitivity; seniors in pharmacy channels prioritize claim credibility over cost.
Supply Chain Analysis
Contract manufacturing concentrates with German and French cold-aseptic specialists and Spanish HPP retrofit facilities. Raw material dependencies center on Danish fermentation houses for live cultures, Italian glass and recycled PET suppliers, and Dutch botanical extract standardizers. Single-source vulnerability in live culture supply creates disruption risk during facility maintenance windows. Distribution runs through refrigerated networks in Randstad and Île-de-France, ambient-stable Tetra Pack channels in Poland and Romania, and direct-to-consumer platforms in London, Berlin, and Paris.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
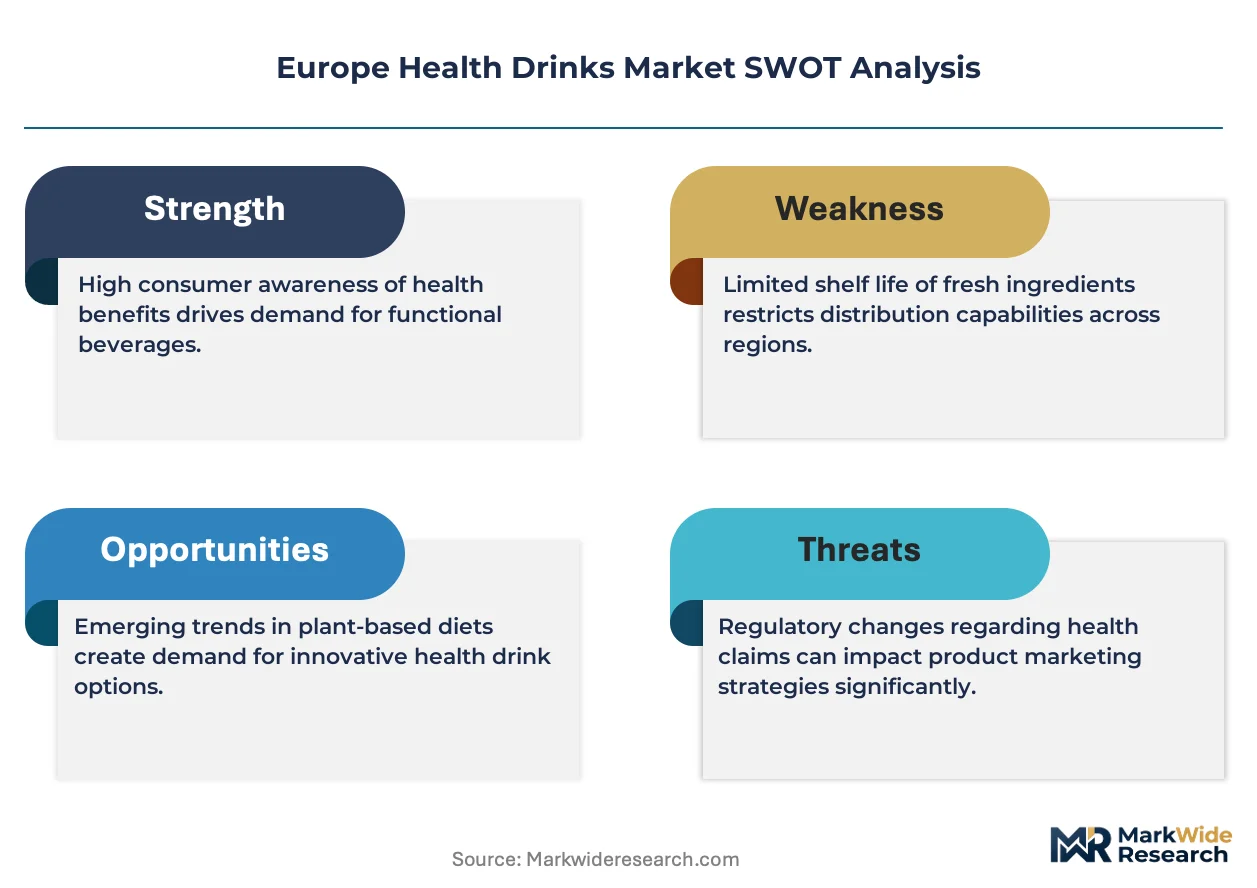
Europe health drinks sit in early-cycle expansion as ambient-stable probiotic technologies collapse cold-chain dependency and unlock pharmacy and convenience penetration previously reserved for pasteurized alternatives.
For Market Incumbents: Pre-empt private-label encroachment by accelerating EFSA claim substantiation investments before EU Farm to Fork nutrient profiling thresholds harden. Lock in multi-year live culture supply contracts with Danish and Dutch fermentation houses to neutralize input bottleneck exposure. Secure cold-aseptic filling capacity in Spain and Italy ahead of F-Gas Regulation compliance deadlines. For New Entrants and Emerging Players: Secondary cities in Poland and Romania present the most penetrable geography where refrigerated distribution gaps favor ambient-stable Tetra Pack entrants. Target athlete segments in Spanish and Dutch gym networks with electrolyte replenishment formats bypassing EFSA claim complexity. Lead through direct-to-consumer subscription stacks leveraging biometric data integration in London, Berlin, and Paris. For Investors and Strategic Acquirers: Carve-out targets emerge from dairy-origin fermentation houses seeking pharmaceutical-nutrition credibility and energy-drink crossovers adapting sugar-reduced variants. Long-term viability frames around EFSA claim substantiation capabilities and cold-chain infrastructure ownership as consolidation pressure intensifies. Watch high-pressure processing line acquisition velocity as inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Approval Pathway | Accelerated postbiotic approvals enable faster claim substantiation across German and French retail channels. |
| Cold-Aseptic Filling Retrofit | Spanish and Italian facility investments preserve vitamin stability while meeting EU Green Deal packaging mandates. |
| Direct-to-Consumer Platform Launch | Biometric data integration in London, Berlin, and Paris collapses traditional supermarket negotiating leverage. |
| Live Culture Supply Agreement | Multi-year contracts with Danish and Dutch fermentation specialists neutralize probiotic SKU input bottleneck risk. |
| High-Pressure Processing Scale-Up | Clean-label preservation with ambient stability eliminates cold-chain dependency for subscription replenishment models. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at German and French supermarket chains, cold-aseptic filling plant engineers, and regulatory affairs leads anchored the qualitative base. Secondary validation drew from EFSA novel food approval databases, EU Farm to Fork Strategy documentation, Nielsen retail audit data, and customs records for botanical extract trade flows. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from national beverage associations.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchors. Segmentation dimensions modeled included product type, end-user archetype, distribution channel, and packaging format alongside EFSA claim validation tier as an industry-specific dimension. CAGRs derived from category growth rate benchmarking against macroeconomic indicators and per-capita functional drink penetration trajectories. Forecast inputs incorporated live culture supply capacity utilization and refrigerated distribution infrastructure expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pharmaceutical-nutrition conglomerates or energy-drink crossovers would shift outcomes beyond modeled ranges. Regulatory acceleration in EU nutrient profiling or EFSA approval pathway streamlining could compress reformulation timelines. Quarterly review of EFSA novel food approval velocity, live culture facility maintenance schedules, and cold-aseptic filling capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Health and Wellness Foods Market
Functional Food and Beverage
Fisetin Market
Functional Food and Beverage
Functional Powdered Lipids Market