
 Non-GMO Verified Sports Drink Market | 2026-2036
Non-GMO Verified Sports Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Verified Sports Drink Market Analytics
Coconut water concentrate is repositioning electrolyte formulations away from synthetic mineral salts. PepsiCo leverages its bottling infrastructure to secure mainstream retail placement for non-GMO verified lines. Nooma differentiates through organic certification layered atop non-GMO verification. BioSteel anchors its position in professional sports locker rooms through team supply partnerships.
Non-GMO verified sports drinks are formulated beverages that exclude genetically modified organisms across all ingredient inputs, typically achieving electrolyte balance through sodium, potassium, and magnesium compounds at concentrations between 200 and 700 milligrams per serving. These products serve athletes and active consumers requiring rapid fluid replacement without synthetic additives or bioengineered sweeteners. Electrolyte drinks dominate current revenue pools due to established consumption rituals around endurance activities, while protein shakes capture the fastest expansion as post-workout recovery protocols broaden beyond traditional gym demographics. E-commerce channels are pulling ahead in growth velocity as direct-to-consumer subscription models reduce reliance on conventional retail gatekeepers.
The Non-GMO Project standard governs ingredient traceability requirements across the United States supply chain, while FDA nutrition labeling rules mandate disclosure of added sugars that directly impact formulation choices in this category. USDA organic regulations intersect with non-GMO claims where dual-certified products command shelf space premiums. Stakeholders must monitor evolving state-level labeling legislation that could fragment compliance obligations beyond federal baselines.
Market Dynamics
Coconut water concentrate is consolidating electrolyte sourcing decisions across formulation teams, compressing synthetic mineral salt volumes while elevating traceability requirements through Non-GMO Project verification protocols.
Growth Catalysts
- Clean-label procurement mandates:NCAA athletic departments and Ironman event organizers now require non-GMO verification for on-site beverage supply contracts.
- USDA organic certification convergence:Dual-certified products command expanded shelf placement in Whole Foods Market and Sprouts Farmers Market locations.
- Endurance sports participation:Marathon and ultramarathon registration volumes in the United States drive ritualized consumption of electrolyte replacement beverages.
Market Restraints
- Input cost volatility:Organic coconut water concentrate prices fluctuate with Philippine and Indonesian harvest cycles.
- Supply concentration risk:Non-GMO Project verification audits cluster among third-party certifiers in the United States, creating bottleneck risk.
- Technical limitation:Natural flavor stability under thermal processing constrains shelf-life extension for clean-label formulations.
Strategic Opportunities
- Direct-to-consumer subscription channels:E-commerce platforms bypass conventional retail slotting fees while capturing recurring revenue from triathlon and CrossFit communities.
- Post-workout protein integration:Blending plant-based protein isolates with electrolyte bases addresses recovery protocol expansion beyond traditional gym demographics.
- State-level labeling legislation:California and Washington pending disclosure requirements could accelerate non-GMO verification adoption ahead of federal baselines.
Industry Challenges
- Certification timeline compression:Non-GMO Project verification cycles average four to six months, delaying product launches against conventional formulation competitors.
- Refrigerated supply chain reconfiguration:Cold-chain requirements for organic-certified lines strain distributor networks accustomed to ambient beverage logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Verified Sports Drink Market |
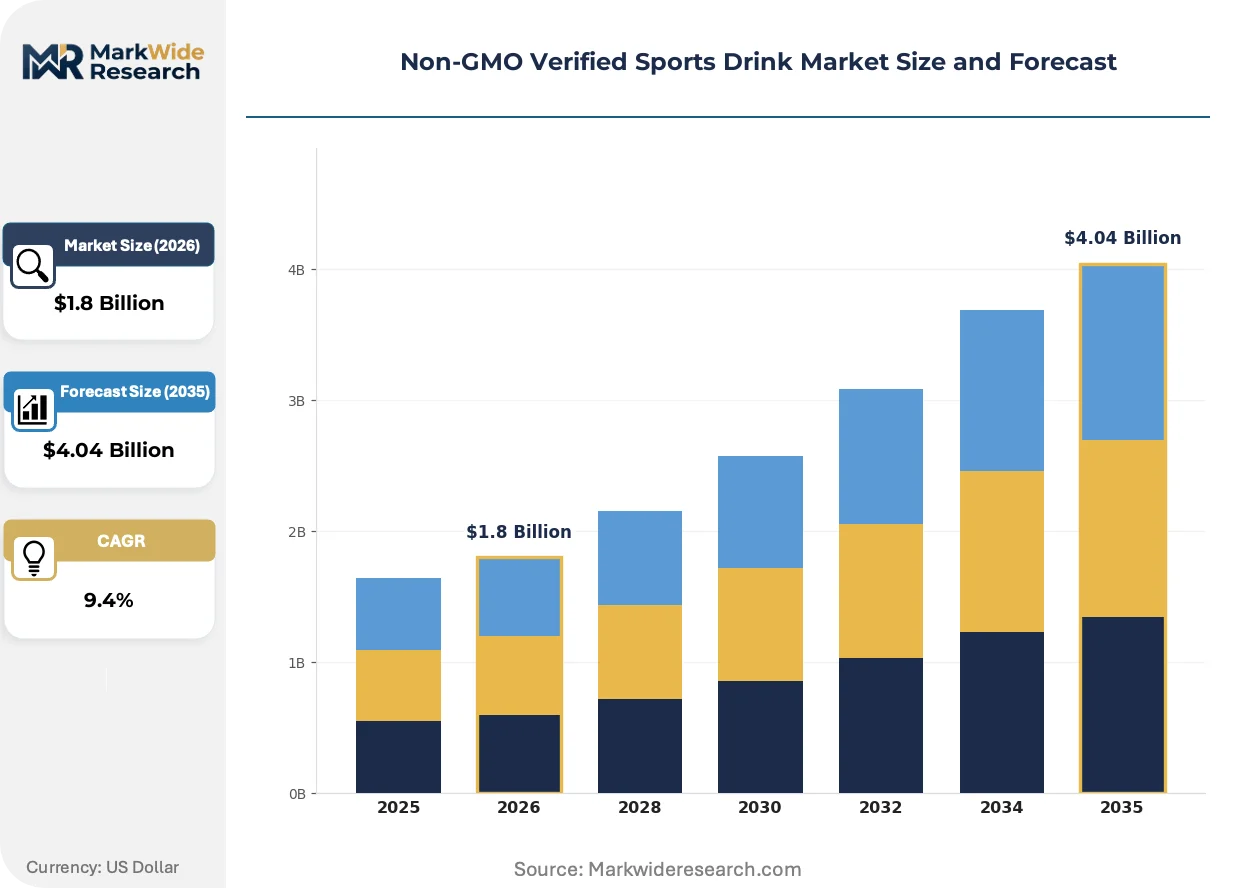
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Drinks, Protein Shakes, Hydration Tablets, Energy Boosters Flavor Profile: Citrus, Berry, Tropical, Herbal Packaging Type: Bottles, Pouches, Cans, Tetra Packs Distribution Channel: Retail Stores, E-commerce, Fitness Centers, Health Clubs |
| Companies Covered | PepsiCo, Coca-Cola, Nestlé, BodyArmor, Nooma, BioSteel, Vita Coco, Abbott Laboratories, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Verified Sports Drink Market Evolving Landscape
Formulation science and verification protocols are compressing development cycles while fragmenting distribution pathways. Three developments are reshaping competitive positioning in this category.
Precision fermentation-derived sweeteners are consolidating carbohydrate sourcing for non-GMO verified lines. Startups supply allulose and tagatose from non-bioengineered yeast strains. Sports nutrition brands adopt these inputs to maintain clean-label positioning while achieving isotonic osmolality targets.
REACH chemical registration requirements in Europe are tightening contaminant thresholds for imported coconut water concentrates. Exporters to EU member states must demonstrate heavy metal and pesticide residue compliance beyond FDA baselines. German and Dutch importers now require batch-level certificates of analysis.
Subscription-based replenishment models are displacing single-unit retail purchases among competitive amateur athletes. Direct-to-consumer platforms capture consumption data that informs flavor development and electrolyte ratio adjustments. This pattern concentrates in the United States where endurance sports participation correlates with higher household digital commerce penetration.
Non-GMO Verified Sports Drink Market Segmentation
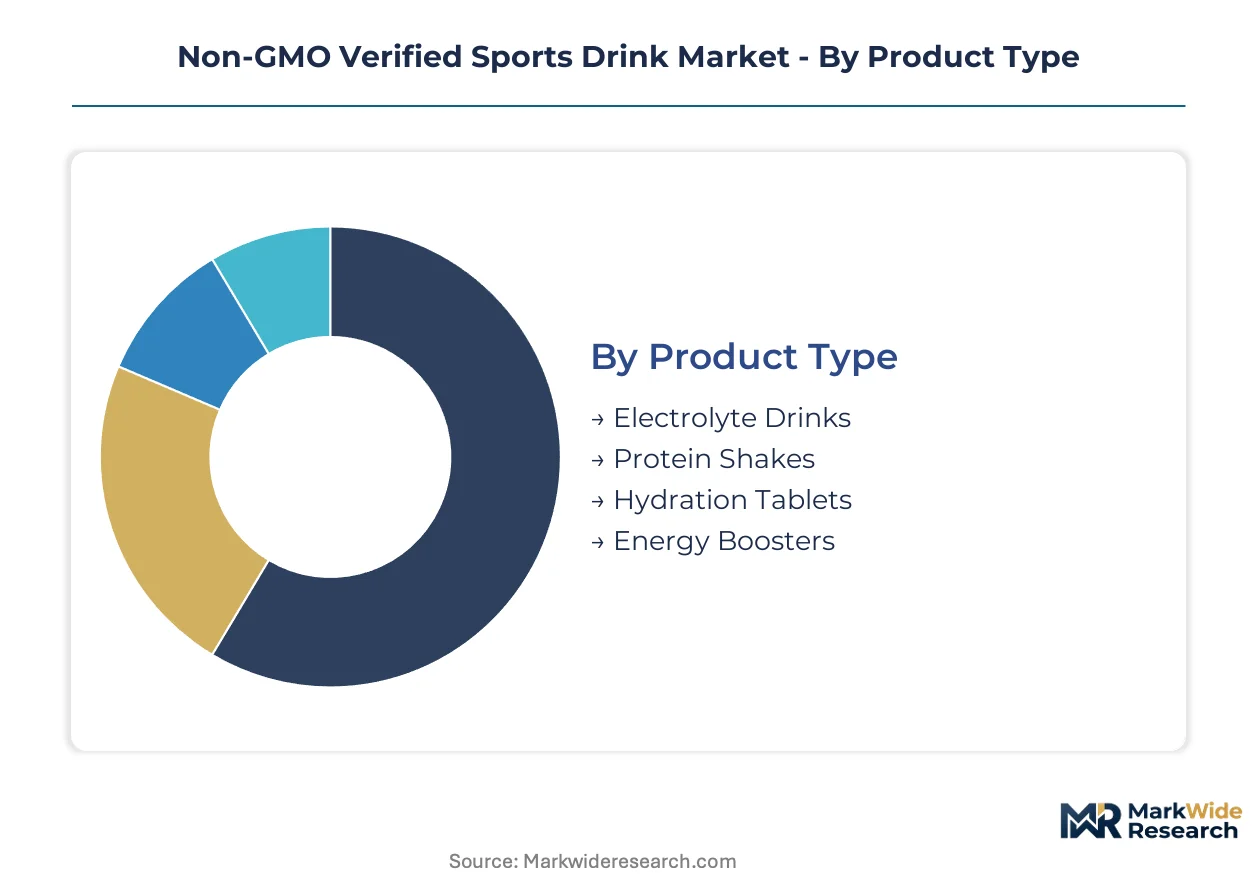
Non-GMO verified sports drink manufacturers calibrate formulation, packaging, and channel strategies against distinct athlete consumption rituals. Segmentation reveals where certification premiums command price realization versus commodity positioning.
Product Type:
Competitive intensity varies sharply by consumption occasion—pre-workout hydration, intra-activity fueling, and post-exercise recovery each demand different nutritional architectures.
- Electrolyte Drinks:Sodium-potassium-magnesium formulations at 200-700mg per serving dominate endurance sports rituals. Marathon and ultramarathon participants in the United States drive repeat purchase frequency through established training protocols.
- Protein Shakes:Plant-based isolates blended with electrolyte bases address recovery protocol expansion. CrossFit and triathlon communities adopt these for post-workout muscle repair, expanding demand beyond traditional gym demographics.
- Hydration Tablets:Compressed mineral effervescents appeal to backpackers and cyclists prioritizing pack weight reduction.
- Energy Boosters:Caffeine-enhanced variants target pre-competition activation in obstacle racing and cycling time trials.
Electrolyte drinks lead volumes today; protein shakes are gaining share fastest.
Flavor Profile:
Palatability under physical stress determines repeat purchase—formulation teams balance masking mineral bitterness against clean-label ingredient constraints.
- Citrus:Lemon-lime and orange profiles mask electrolyte salinity most effectively. NCAA athletic departments specify these for on-site supply contracts due to broad athlete acceptance.
- Berry:Acai and mixed berry variants command premium placement in Whole Foods Market locations. USDA organic certification convergence elevates these SKUs above conventional alternatives.
- Tropical:Coconut water-forward formulations leverage Philippine and Indonesian sourcing.
- Herbal:Adaptogen-infused lines target yoga and wellness practitioners seeking functional benefits beyond hydration.
Citrus dominates current shelf space; berry profiles are expanding most quickly.
Packaging Type:
Supply chain configuration dictates format viability—cold-chain requirements fragment distribution economics across ambient and refrigerated networks.
- Bottles:PET and rPET containers retain mainstream retail dominance. PepsiCo leverages existing bottling infrastructure to secure conventional grocery placement for non-GMO verified lines.
- Pouches:Flexible film reduces shipping cube and appeals to trail runners and cyclists. Subscription-based replenishment models favor this format for direct-to-consumer fulfillment.
- Cans:Aluminum offers infinite recyclability but constrains thermal processing options for natural flavor stability.
- Tetra Packs:Aseptic cartons extend shelf life without refrigeration, penetrating convenience store channels.
Bottles lead unit volumes today; pouches are climbing the fastest.
Distribution Channel:
Channel selection determines margin structure—retail slotting fees erode economics that direct relationships preserve.
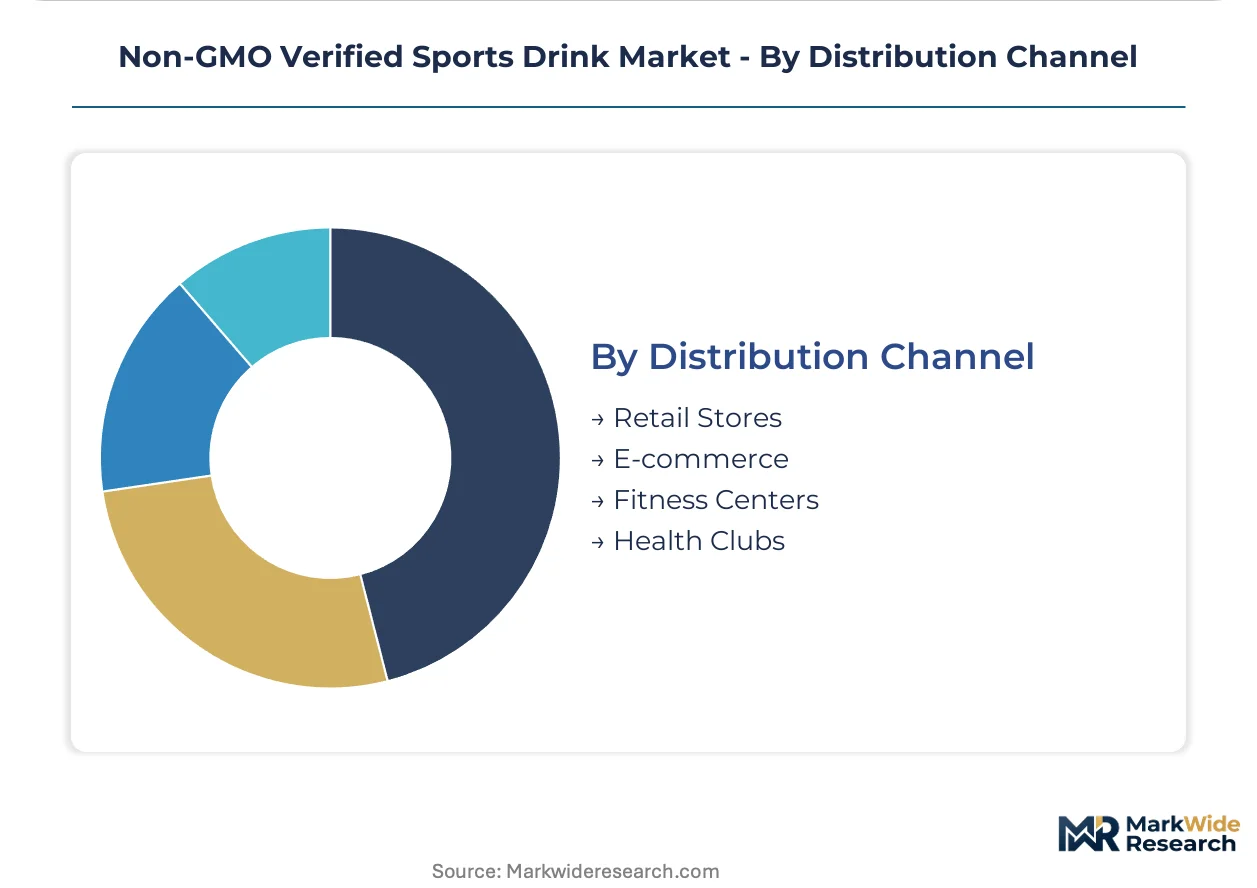
- Retail Stores:Conventional grocery and natural specialty chains demand Non-GMO Project verification for premium shelf placement. Sprouts Farmers Market locations allocate expanded facings to dual-certified organic and non-GMO SKUs.
- E-commerce:Direct-to-consumer platforms bypass slotting fees while capturing consumption data. Triathlon and CrossFit communities drive recurring subscription revenue through digital channels.
- Fitness Centers:On-site coolers at boutique studios and CrossFit boxes capture impulse purchase at point of exertion.
- Health Clubs:Equinox and Life Time facilities curate premium beverage assortments for member amenity programs.
Retail stores lead revenue today; e-commerce is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates non-GMO verified sports drink formulation and certification infrastructure, with endurance sports participation driving demand concentration across coastal metropolitan markets.
United States
NCAA athletic departments and Ironman event organizers mandate Non-GMO Project verification for supply contracts. FDA nutrition labeling rules govern added sugar disclosure thresholds that constrain formulation architectures. Austin and Boulder anchor product development clusters where triathlon communities sustain direct-to-consumer subscription volumes.
Germany
REACH chemical registration requirements tighten contaminant thresholds for imported coconut water concentrates. ECHA compliance mandates batch-level certificates of analysis for heavy metal and pesticide residue documentation. Berlin and Hamburg importers now require documentation beyond FDA baselines for EU market entry.
Canada
Health Canada and PMRA regulations intersect with non-GMO verification for cross-border product distribution. Canadian endurance sports participation rates correlate with clean-label beverage procurement in Ontario and British Columbia. Toronto and Vancouver metropolitan areas concentrate specialty retail placement for dual-certified organic and non-GMO SKUs.
Australia
TGA therapeutic goods frameworks influence functional beverage classification for adaptogen-infused product lines. Marathon and ultramarathon registration growth in New South Wales and Victoria drives electrolyte replacement rituals. Sydney and Melbourne fitness communities sustain premium pricing for coconut water-forward formulations.
United Kingdom
Post-Brexit regulatory divergence from EU REACH standards creates compliance complexity for imported concentrate suppliers. London and Manchester boutique fitness studios curate premium beverage assortments for member amenity programs. CrossFit box proliferation in metropolitan centers sustains impulse purchase velocity at point of exertion.
Non-GMO Verified Sports Drink Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and distribution network depth. The vendor base organizes around beverage conglomerates with bottling infrastructure, organic specialists with dual-certification expertise, and direct-to-consumer platforms with endurance community relationships. Three archetypes dominate: scale-driven multinationals leveraging existing retail gatekeeper relationships, certification-first specialists commanding premium shelf placement, and community-anchored digital natives capturing subscription revenue. Competitive moves concentrate on M&A for certification capability acquisition and strategic partnerships with athletic event organizers for exclusive supply contracts.
Within the multinational tier, PepsiCo and Coca-Cola occupy positions defined by bottling infrastructure scale and mainstream retail penetration. Nooma and BioSteel exemplify the certification-specialist archetype, with organic and non-GMO dual-certification anchoring premium positioning. Among community-anchored platforms, BodyArmor represents digital-native engagement with athlete influencer networks.
| Leading Market Players |
|---|
| PepsiCo |
| Coca-Cola |
| Nestlé |
| BodyArmor |
| Nooma |
| BioSteel |
| Vita Coco |
| Abbott Laboratories |
| Danone |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between dual-certified organic-non-GMO formulations and single-verified commodity lines manifests in divergent margin structures and sourcing configurations across the United States supply chain. Premium tiers command shelf placement premiums at Sprouts Farmers Market and Whole Foods Market locations while commodity positioning depends on PepsiCo's bottling infrastructure for conventional grocery penetration.
Pricing Analysis
Input-cost pass-through from Philippine and Indonesian coconut water concentrate harvest cycles shapes pricing elasticity across formulation tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with dual-certified organic-non-GMO SKUs realizing highest realization and conventional electrolyte bases facing compression. Pricing pressure stems from organic input volatility and Non-GMO Project verification audit bottlenecks. Price-sensitive weekend warriors and recreational athletes drive volume in economy tiers; competitive triathletes and CrossFit communities show lowest sensitivity to certification premiums.
Supply Chain Analysis
Workforce availability constraints in Philippine coconut water processing hubs and Indonesian concentrate extraction facilities tether production scheduling to agricultural labor pools. Raw material flows draw from Southeast Asian coconut plantations, domestic bottling infrastructure in Texas and Georgia, and third-party Non-GMO Project verification auditors concentrated in California and Washington. Single-source vulnerability clusters in Philippine coconut water supply during monsoon disruption periods. Distribution runs through refrigerated networks for organic-certified lines and ambient logistics for conventional formulations, fragmenting downstream economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in certification-premium capture and direct-to-consumer channel bypass of retail slotting fees, with precision fermentation-derived sweeteners offering input cost stabilization.
For Market Incumbents: Deepen captive supply arrangements with Philippine coconut water concentrate processors to buffer harvest cycle volatility. Fortify Non-GMO Project verification relationships with third-party certifiers to compress four-to-six-month audit timelines. Vertical integration into precision fermentation sweetener sourcing through startup partnerships defends against synthetic mineral salt substitution threats. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for endurance community acquisition without conventional retail gatekeeper dependence. Target CrossFit and triathlon segments with post-workout protein-electrolyte blends where established rituals remain underdeveloped. Deploy influencer-athlete partnerships for digital-native credibility building before physical retail expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where certification infrastructure scarcity intersects with endurance sports community relationships. Five-to-ten-year viability favors dual-certification specialists with established Non-GMO Project verification and USDA organic credentials over single-verified commodity players. Watch precision fermentation sweetener cost parity with conventional carbohydrates as inflection signal for formulation disruption timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | USDA organic layered atop Non-GMO Project verification commands Sprouts Farmers Market expanded facings. |
| Direct-to-Consumer Launch | Subscription models bypass conventional grocery slotting fees while capturing triathlon community recurring revenue. |
| Precision Fermentation Partnership | Allulose and tagatose from non-bioengineered yeast strains maintain clean-label positioning at isotonic targets. |
| Team Supply Contract Acquisition | NCAA athletic department and Ironman event organizer mandates lock in institutional volume commitments. |
| Cold-Chain Infrastructure Expansion | Refrigerated distribution networks accommodate organic-certified lines beyond ambient beverage logistics. |
Research Methodology
Bottom-up endurance athlete consumption modeling reconciled against top-down coconut water concentrate supply tracking forms the analytical core of this study. Primary interviews with sports nutrition formulation directors, Non-GMO Project verification auditors, NCAA athletic department procurement officers, and Sprouts Farmers Market category buyers combined with secondary validation. Trade data from FDA nutrition labeling filings, USDA organic certification databases, Non-GMO Project verification registries, and Nielsen retail audit data anchored supply-side and demand-side triangulation.
Historical trendline analysis across electrolyte drink, protein shake, hydration tablet, and energy booster consumption rituals informed projection frameworks. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel across the projection horizon. CAGRs derived from athlete participation growth in marathon, ultramarathon, CrossFit, and triathlon communities intersected with clean-label procurement mandate adoption curves. Precision fermentation sweetener cost trajectory and coconut water concentrate harvest cycle patterns supplied industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-derived carbohydrates would alter the outlook. Forecasts reflect assumptions around Non-GMO Project verification timeline stability and endurance sports participation continuity. Material deviation in organic coconut water supply disruption frequency or state-level labeling legislation acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Functional Shots Market
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Functional Dairy Products Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Vegan Brain Food Market