
 Fermented Non Dairy Non Alcoholic Beverages Market | 2026-2036
Fermented Non Dairy Non Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Non Dairy Non Alcoholic Beverages Market Intelligence
The prevalence of asset-light contract manufacturing models is reconfiguring the competitive landscape, lowering barriers to entry for new brands. GT's Living Foods LLC sustains its market position through brand authenticity and a focus on traditional kombucha brewing methods. In contrast, PepsiCo Inc. leverages its extensive distribution network for its KeVita brand to achieve mass-market penetration. Danone S.A. competes by integrating fermented beverages into its broader portfolio of health-focused dairy and plant-based products.
Fermented non-dairy non-alcoholic beverages are drinks produced through the controlled microbial growth and enzymatic conversion of plant-based substrates like tea, fruit juices, or grains. These products, including kombucha with its symbiotic culture of bacteria and yeast (SCOBY), are valued for their probiotic content and distinct effervescent, tangy flavor profiles. Kombucha remains the dominant product type, while water kefir is an emerging category gaining traction. Supermarkets and health food stores constitute the primary distribution channels, though online retail is expanding its share rapidly.
Regulatory frameworks from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) govern labeling requirements for probiotic content and alcohol-by-volume limits. In parallel, standards from India's FSSAI influence ingredient approvals and good manufacturing practices, shaping market entry conditions. Producers must navigate evolving regional definitions of 'probiotic' and 'live culture' to ensure compliance and maintain consumer trust.
Market Dynamics
The proliferation of asset-light contract manufacturing is the central force altering the market's structure. This model significantly lowers capital expenditure for new entrants, intensifying competition and accelerating product innovation cycles based on emerging consumer health trends.
Growth Catalysts
- Precision Fermentation:Advances in starter culture development and precision fermentation technologies are enhancing product consistency, extending shelf life, and enabling the creation of novel flavor profiles, meeting consumer demand for reliable and diverse beverage options.
- Functional Health Demand:A pronounced consumer shift towards functional beverages for gut health is a primary catalyst. This is especially true among fitness enthusiasts and health-conscious demographics in major urban centers seeking probiotic-rich alternatives to sugary drinks.
- Retail Channel Expansion:The increasing allocation of shelf space in mainstream supermarkets and hypermarkets, beyond niche health food stores, is improving accessibility and driving volume growth, particularly in North America and Europe.
Market Restraints
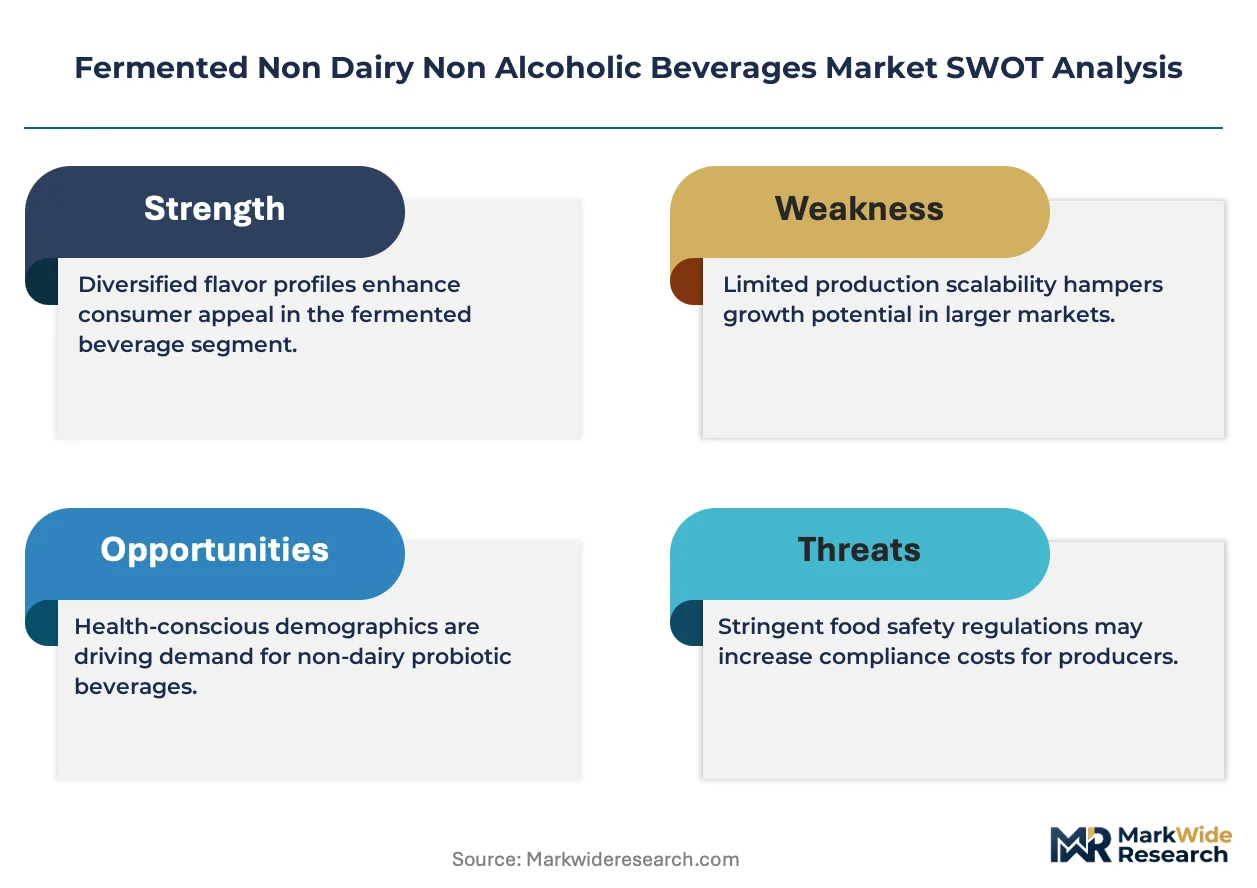
- Input Cost Volatility:The market is sensitive to price fluctuations for key organic inputs, such as specialty teas, organic cane sugar, and exotic fruits. This volatility can compress margins for producers, especially smaller, premium-focused brands.
- Regulatory Ambiguity:Evolving and inconsistent regulations from bodies like the U.S. FDA and EFSA regarding alcohol-by-volume limits and the specific labeling of 'probiotic' content create significant compliance burdens and legal risks for manufacturers.
- Cold Chain Dependency:The requirement for a continuous cold chain from production to consumption to maintain the viability of live cultures adds significant cost and logistical complexity, limiting geographic reach and increasing spoilage risk.
Strategic Opportunities
- Geographic Expansion:There are significant opportunities in underpenetrated Asia-Pacific markets, where traditional fermentation is culturally familiar but the commercialized non-dairy beverage category remains nascent, offering a large potential consumer base.
- New Product Substrates:Innovation beyond tea-based kombucha into beverages derived from fermented water kefir grains, fruit juices, and even plant-based milks presents a white-space opportunity to attract new consumer segments with different taste preferences.
- Direct-to-Consumer Models:Developing robust e-commerce platforms and subscription-based direct-to-consumer (DTC) models allows brands to build direct relationships with consumers, gather valuable data, and capture higher margins by bypassing traditional retail intermediaries.
Industry Challenges
- Scaling Artisanal Production:A primary operational challenge is scaling traditional fermentation methods, which often rely on variable symbiotic cultures (SCOBYs), to an industrial level while maintaining the authentic flavor profiles and perceived health benefits that define the category.
- Multi-Jurisdictional Compliance:Navigating the disparate labeling laws, ingredient approvals, and manufacturing standards set by regulators such as the FSSAI in India, the FDA in the United States, and EFSA in Europe is a complex and resource-intensive task.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Non Dairy Non Alcoholic Beverages Market |
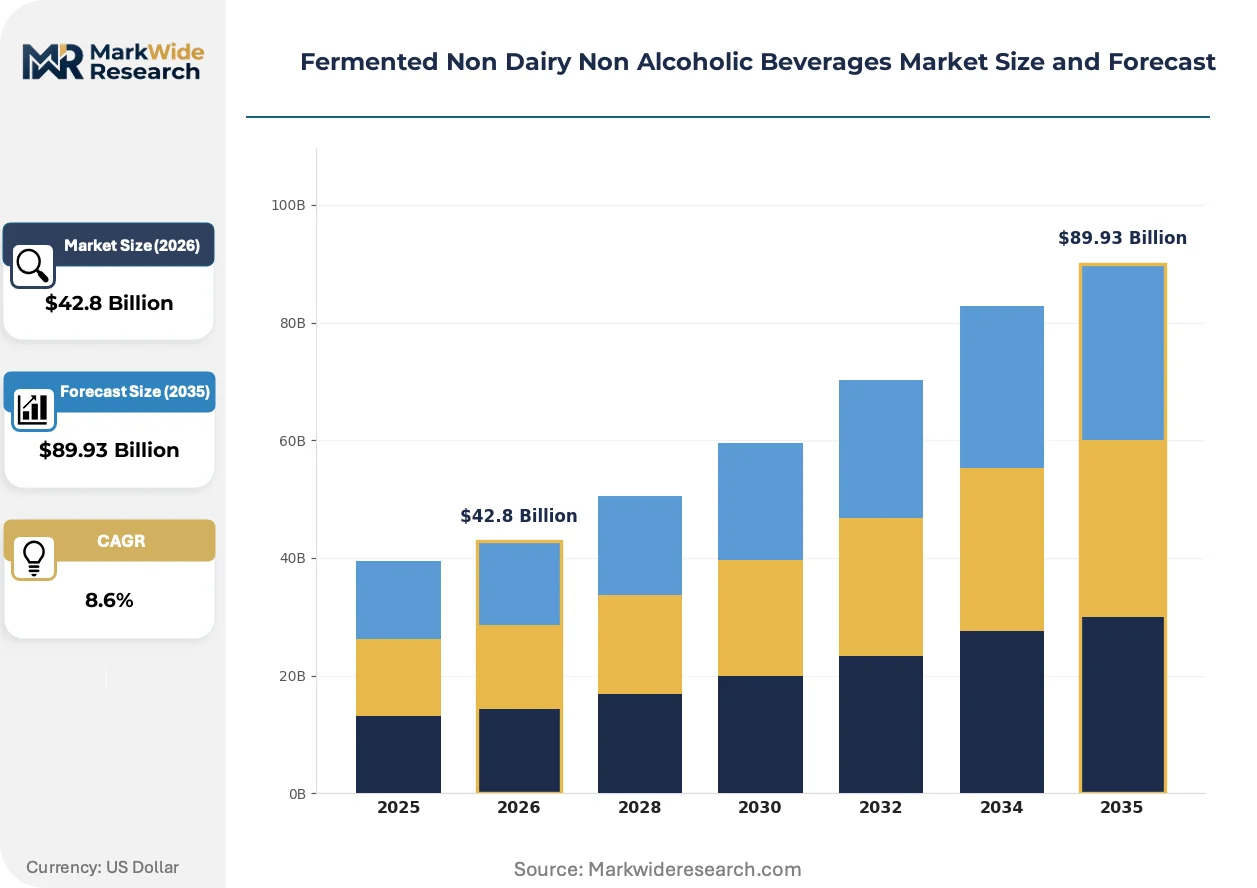
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $89.93 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kombucha, Kefir, Fermented Lemonade, Water Kefir End User: Health-conscious Consumers, Fitness Enthusiasts, Vegans, Retail Customers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Flavor Profile: Citrus, Berry, Ginger, Herbal |
| Companies Covered | Health-Ade LLC, Lifeway Foods Inc., PepsiCo Inc., Brew Dr. Kombucha, Reed's Inc., Danone S.A, KeVita Inc., Remedy Drinks, GT's Living Foods LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Non Dairy Non Alcoholic Beverages Market Strategic Shifts & Innovations
Industrialization of artisanal products defines the current market evolution. Producers are focused on balancing the demand for authentic, traditional fermentation with the need for scalable, consistent, and shelf-stable products suitable for mass-market distribution and regulatory scrutiny.
Precision fermentation technology allows for the use of specific, isolated microbial strains to achieve predictable outcomes in flavor, acidity, and probiotic count. New market entrants and large-scale producers are rapidly adopting these engineered starter cultures to improve batch-to-batch consistency. The market is migrating from a reliance on variable, wild-culture SCOBYs toward highly controlled bioprocesses that ensure product safety and quality for mainstream retail channels.
Regulatory frameworks governing alcohol content are tightening production controls. The U.S. FDA’s strict enforcement of the 0.5% alcohol-by-volume (ABV) limit for non-alcoholic classification compels producers to invest in advanced monitoring systems or de-alcoholization equipment. The kombucha segment is most affected, with brands implementing rigorous quality assurance protocols to manage post-bottling fermentation and ensure compliance throughout the supply chain.
Consumer purchasing patterns are evolving from incidental discovery in retail stores to intentional, recurring buys through digital platforms. This shift disrupts the dominance of health food stores and supermarkets, creating an opening for brands that excel at online marketing and direct-to-consumer (DTC) subscription services. This trend is most advanced in dense urban areas across the United States and Germany with sophisticated logistics networks.
Fermented Non Dairy Non Alcoholic Beverages Market Segmentation
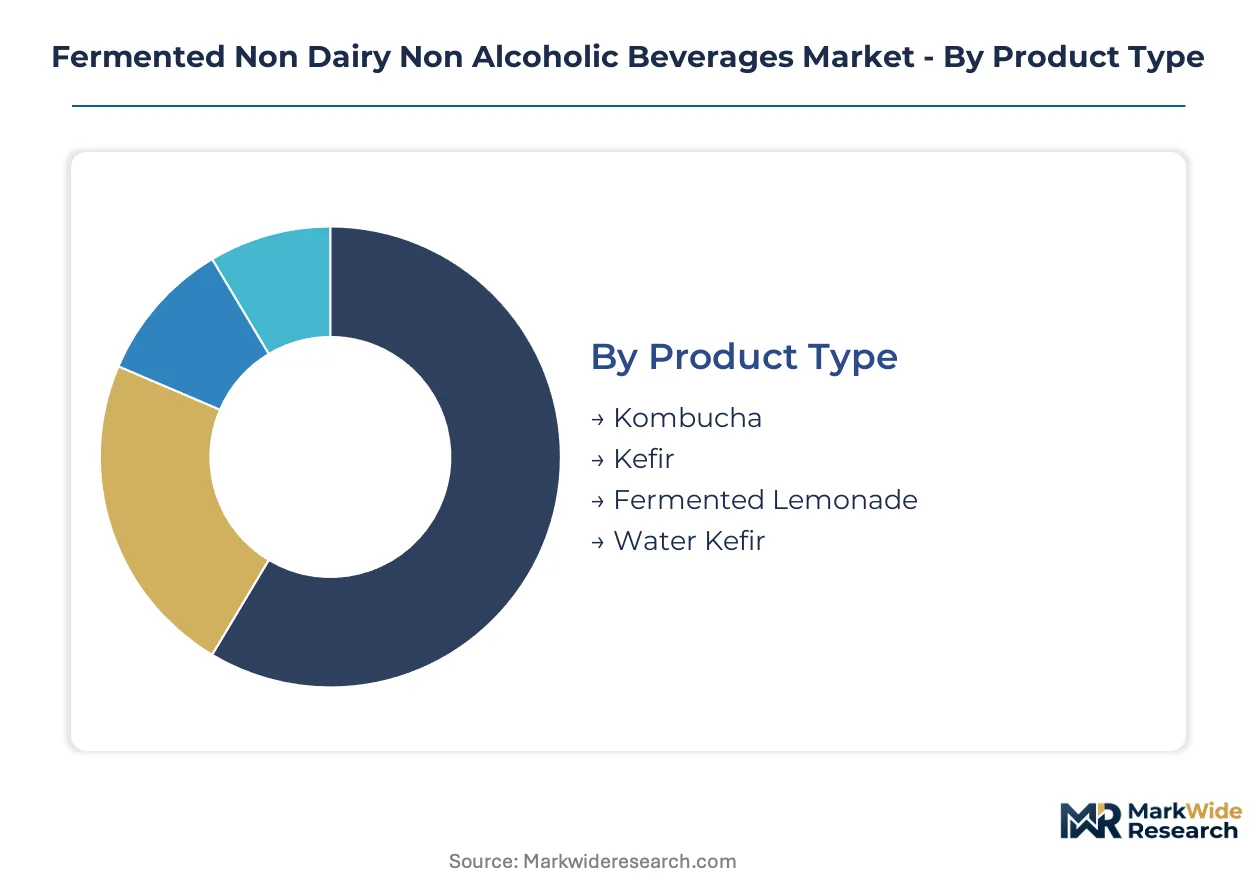
Market segmentation clarifies distinct consumer groups, product preferences, and sales avenues within the fermented non-dairy non-alcoholic beverages sector. This detailed categorization enables producers to refine product development and strategically target specific market niches for optimal growth.
Product Type:
The product type dimension delineates the core fermented beverage offerings available to consumers.
- Kombucha:This effervescent beverage is produced by fermenting sweetened tea using a symbiotic culture of bacteria and yeast (SCOBY). Demand concentrates in urban centers across North America and Europe, driven by its perceived gut health benefits.
- Water Kefir:Originating from water kefir grains, this probiotic-rich drink ferments sugar water, fruit juice, or coconut water. Its rising popularity among health-conscious consumers in Germany and the United States reflects a search for diverse probiotic sources.
- Kefir:Traditional kefir involves fermenting milk, but non-dairy versions use plant-based milks, offering a tangy, probiotic-rich alternative.
- Fermented Lemonade:This category includes lemonades enhanced with fermentation, providing a tart, probiotic-infused refreshment.
Kombucha commands the established base. The steepest expansion runs through Water Kefir.
End User:
Consumer profiles define the distinct groups actively seeking fermented non-dairy non-alcoholic beverages.
- Health-conscious Consumers:Individuals prioritizing wellness and preventative health measures often seek out beverages with probiotic content and natural ingredients. This demographic in major urban centers drives demand for functional food and drink alternatives.
- Fitness Enthusiasts:Athletes and active individuals consume these beverages for hydration, gut health support, and as a natural alternative to sugary sports drinks. Their purchasing patterns in North America reflect a focus on performance and recovery.
- Vegans:This group specifically seeks plant-based, non-dairy options, making fermented non-dairy beverages a natural fit for their dietary requirements.
- Retail Customers:General consumers purchasing these products from supermarkets or convenience stores represent the broader market adoption beyond niche demographics.
Demand from Health-conscious Consumers remains foundational, while Fitness Enthusiasts show significant growth potential.
Distribution Channel:
The pathways through which these beverages reach consumers significantly influence market accessibility and sales volumes.
- Supermarkets:These large retail chains offer widespread availability, making fermented beverages accessible to a broad consumer base through dedicated health or beverage aisles. Increased shelf space allocation in European and North American supermarkets drives volume growth.
- Online Retail:E-commerce platforms and brand-specific direct-to-consumer websites facilitate convenient purchasing and subscription models, particularly in dense urban areas like those in the United States and Germany. This channel allows for direct consumer engagement and higher margins.
- Health Food Stores:These specialized outlets cater to consumers specifically seeking organic, natural, and functional food and beverage options.
- Convenience Stores:Smaller retail formats provide quick access for on-the-go consumption, capturing impulse buys from a diverse customer base.
Traditional retail channels like Supermarkets continue to anchor sales, but Online Retail is rapidly gaining share.
Flavor Profile:
Consumer preferences for taste are categorized by the distinct flavor profiles offered within the market.
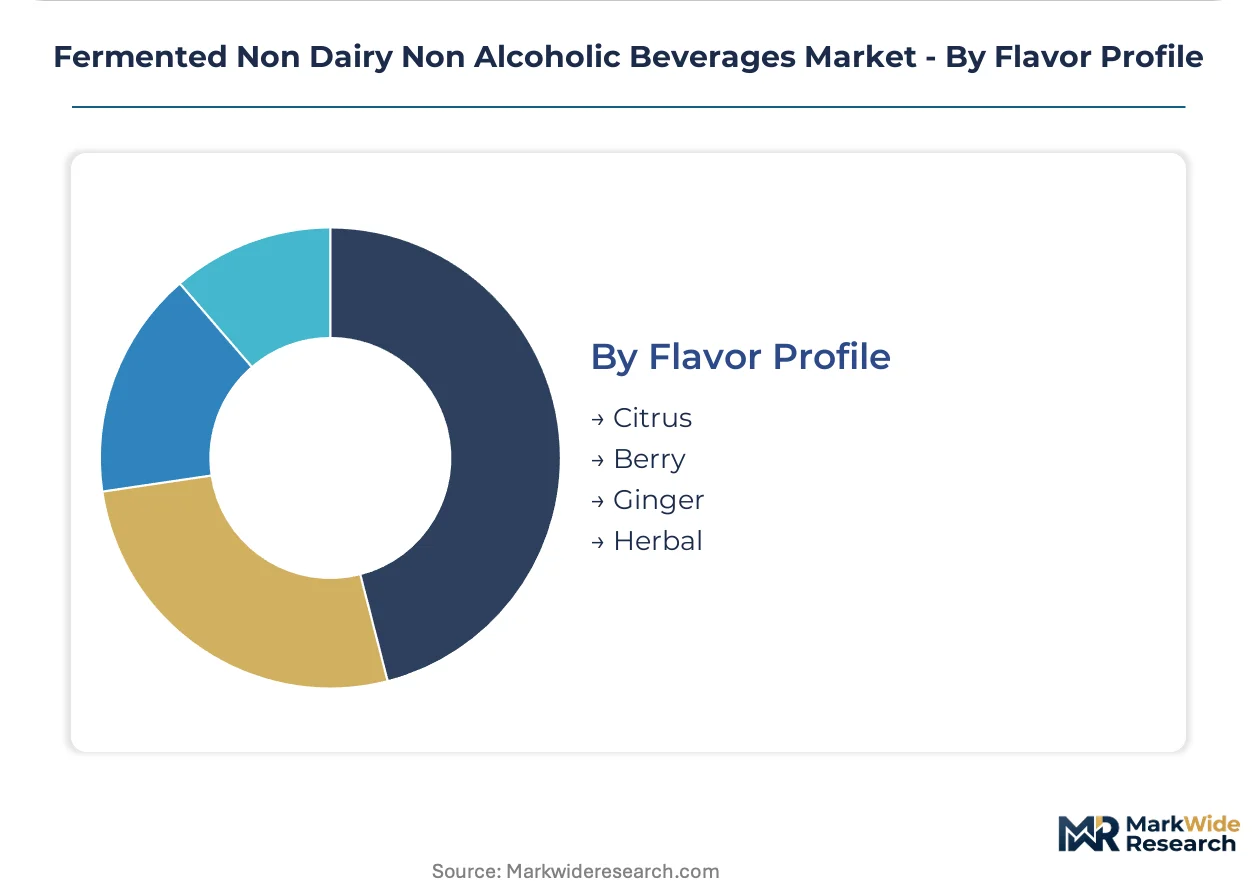
- Berry:Flavors derived from various berries, such as strawberry, raspberry, and blueberry, offer a sweet and tangy taste popular across diverse demographics. These profiles attract consumers seeking fruity, palatable options.
- Ginger:Beverages infused with ginger provide a spicy, zesty, and often warming taste, appealing to consumers desiring a bolder flavor experience. Ginger-based options are particularly popular in health-focused segments for their perceived wellness benefits.
- Citrus:Profiles featuring lemon, lime, or orange provide a refreshing and tart taste, widely appealing to a broad consumer base.
- Herbal:These flavors incorporate botanical extracts like mint, lavender, or hibiscus, offering unique and sophisticated taste experiences for adventurous palates.
While Berry flavors maintain broad appeal, Ginger profiles are experiencing notable expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious consumers and fitness enthusiasts drive demand for fermented non-dairy non-alcoholic beverages across major urban centers. North America and Europe represent primary consumption hubs, with significant adoption rates for probiotic-rich alternatives. Underpenetrated markets in Asia-Pacific also offer substantial growth potential for commercialized products.
United States
A pronounced consumer shift towards functional beverages for gut health drives significant demand for fermented options. The U.S. FDA’s strict enforcement of the 0.5% alcohol-by-volume limit compels producers to invest in advanced monitoring systems. Major metropolitan areas like Los Angeles and New York City exhibit high concentrations of brands and specialized retail offerings.
Germany
Demand for diverse probiotic sources and plant-based alternatives fuels the market, particularly for water kefir products. The European Food Safety Authority (EFSA) influences labeling requirements for probiotic content and health claims. Berlin and Hamburg serve as key innovation centers, with numerous startups developing novel flavor profiles.
United Kingdom
Consumers prioritize wellness and preventative health measures, increasing the uptake of fermented non-dairy beverages. UK food safety regulations align with broader EU standards regarding product composition and labeling. London remains a central hub for product launches and specialized health food stores, reflecting strong urban consumer interest.
India
Traditional fermentation is culturally familiar, creating a receptive environment for commercialized non-dairy beverages among health-conscious urban populations. India's FSSAI standards influence ingredient approvals and good manufacturing practices, shaping market entry conditions. Major cities like Mumbai and Bangalore show rising interest in wellness-oriented food and drink products.
Australia
Fitness enthusiasts and vegans seek plant-based, probiotic-rich alternatives for hydration and gut health support. The country's food standards body regulates product claims and safety for fermented beverages. Sydney and Melbourne are significant markets, with a growing presence of health food stores and online retail platforms.
Fermented Non Dairy Non Alcoholic Beverages Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market structure. The landscape features large consumer packaged goods companies alongside innovative artisanal brands. Strategic archetypes include diversified beverage giants, niche health-focused producers, and agile direct-to-consumer businesses. Distribution network expansion and precision fermentation technology adoption represent dominant competitive moves.
Scale-driven conglomerates like PepsiCo Inc. and Danone S.A. leverage extensive distribution networks for mass-market penetration. PepsiCo Inc. extends its reach through the KeVita brand, while Danone S.A. integrates fermented options into its broader health portfolio. Artisanal specialists such as GT's Living Foods LLC sustain market position through brand authenticity and traditional brewing methods.
| Leading Market Players |
|---|
| Health-Ade LLC |
| Lifeway Foods Inc. |
| PepsiCo Inc. |
| Brew Dr. Kombucha |
| Reed's Inc. |
| Danone S.A |
| KeVita Inc. |
| Remedy Drinks |
| GT's Living Foods LLC |
| Others |
Cost & Logistics Intelligence
Trans-Atlantic shipping lanes and other global freight corridors significantly influence the cost dynamics of specialty ingredients, impacting supply concentration and downstream price differentiation. Volatility in these logistics costs directly affects producer margins and consumer pricing for fermented non-dairy non-alcoholic beverages.
Pricing Analysis
Cost-plus contract models, often indexed to raw material prices for organic sugar and specialty teas, define much of the market's pricing structure. Price differentiation stems from brand premium, particularly for authentic traditional brewing methods, and from specific organic or non-GMO certifications. Pricing softness affects mass-market segments due to intense competition from asset-light contract manufacturers. Retail customers demonstrate the highest price sensitivity, while health-conscious consumers and vegans prioritize product attributes over minimal cost savings.
Supply Chain Analysis
Cold chain dependency adds significant cost and logistical complexity, limiting geographic reach and increasing spoilage risk for live culture products. Geographic supply concentration for key raw materials includes specialty teas from India and China, organic cane sugar from Brazil, and exotic fruits from Southeast Asia. Raw material dependencies center on these organic inputs and specific starter cultures. Distribution runs through a hybrid model, combining widespread supermarket presence with rapidly expanding direct-to-consumer (DTC) channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fermented non-dairy non-alcoholic beverages market is at a platform-economics inflection point, driven by the shift towards integrated digital health ecosystems connecting consumers with functional food and beverage solutions.
For Market Incumbents:Insulate core market share by investing in precision fermentation R&D to ensure product consistency and extend shelf life against emerging artisanal brands. Deepen channel control in mainstream supermarkets to counter online retail expansion, leveraging existing distribution networks. Focus on certification investment in organic and non-GMO labels to maintain brand premium and consumer trust amidst evolving regulatory scrutiny.
For New Entrants and Emerging Players:Build out direct-to-consumer (DTC) subscription models targeting urban health-conscious consumers in Germany and the United States, bypassing traditional retail gatekeepers. Target underpenetrated Asia-Pacific markets with novel substrate innovations beyond kombucha, such as water kefir or fermented plant-based milks. Emphasize unique flavor profiles and specific functional benefits through digital marketing as a primary go-to-market angle.
For Investors and Strategic Acquirers:Carve-out targets emerge from large consumer packaged goods companies seeking to divest non-core fermented beverage brands with strong regional presence. Long-term viability hinges on identifying agile, mid-cap specialists with proprietary starter cultures or robust DTC infrastructure. Acquisition target archetype includes companies demonstrating scalable production of novel fermented substrates with clear regulatory compliance pathways. Sustained growth in online retail penetration and successful expansion into new geographic markets is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Enhances product consistency and extends shelf life, meeting mainstream retail demands. |
| Direct-to-Consumer Channel Expansion | Builds direct consumer relationships and captures higher margins, particularly in urban centers. |
| Novel Substrate Development | Attracts new consumer segments with diverse taste preferences beyond traditional kombucha. |
| Global Regulatory Compliance Unit | Ensures adherence to varied alcohol-by-volume limits and probiotic labeling standards like FSSAI. |
| Cold Chain Optimization | Reduces logistical costs and spoilage risk, improving market accessibility for live culture products. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather comprehensive market insights. Primary interviews with brand managers, product development specialists, supply chain logistics heads, and retail category buyers provided qualitative insights. Secondary validation leveraged regulatory body reports from the U.S. FDA, EFSA, and FSSAI, alongside trade association publications. A bottom-up estimation of market size was triangulated with top-down validation from industry revenue reports.
Quantitative models were calibrated against historical market performance and projected growth drivers across the analysis window. Segmentation dimensions modeled included product type, end-user, distribution channel, flavor profile, and regional consumption patterns. Compound Annual Growth Rates (CAGRs) were derived by integrating supply-side capacity expansions and demand-side consumer trend shifts. Forecast inputs included raw material price trends and regulatory compliance costs.
Stress conditions across raw material price volatility and evolving regulatory enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding consumer health trends and technological advancements in fermentation. Significant shifts in global trade policies or unexpected public health crises would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Global Non-Alcoholic RTD Beverages Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Europe Soy Beverages Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Iced Tea Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Fermented Non-Dairy Beverages Market
Non-Alcoholic Beverages
Non-Alcoholic Beer Market
Non-Alcoholic Beverages
Global Non Alcoholic Concentrated Syrup Market
Non-Alcoholic Beverages
Global Nonalcoholic Beverage Market