
 Global Digestive Enzymes Market | 2026-2036
Global Digestive Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digestive Enzymes Market Foresight
North American fermentation capacity is hardening as contract manufacturers expand multi-enzyme production lines to serve branded marketers. Enzymedica leverages its specialized plant-based enzyme formulations to command premium shelf positioning in natural retail channels. NOW Health Group sustains broad distribution across mass-market and practitioner segments through vertically integrated manufacturing. Garden of Life anchors its market presence with USDA-certified organic and non-GMO verified enzyme products targeting clean-label consumers.
Digestive enzymes comprise biocatalyst proteins—primarily protease, amylase, lipase, cellulase, and lactase—typically extracted through microbial fermentation or plant sourcing, then stabilized for pH-specific activity across gastric and intestinal environments. These enzymes accelerate macronutrient hydrolysis, enabling therapeutic intervention for malabsorption disorders and performance optimization in sports nutrition. Protease and lipase formulations dominate pharmaceutical applications due to their established clinical efficacy in pancreatic insufficiency management, while lactase leads retail growth as dairy intolerance awareness spreads. Dietary supplements capture the widest margin pool through direct-to-consumer subscription models, though functional foods represent the fastest-expanding application as beverage and snack manufacturers embed enzymes into positioned wellness products.
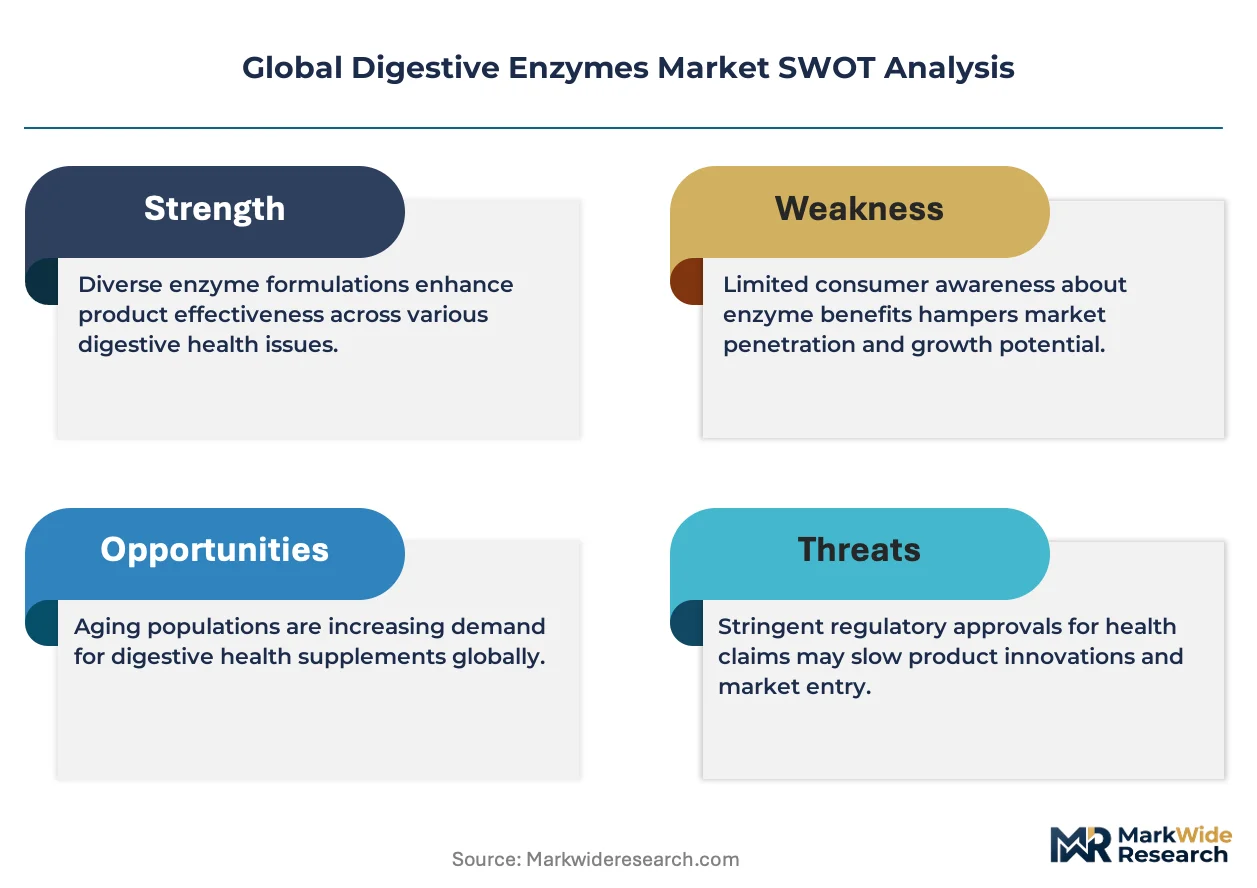
FDA cGMP enforcement for dietary supplements elevates batch testing and identity verification costs, while EFSA health claim assessments in Europe constrain permissible marketing language for enzyme efficacy. The EU Novel Food regulation creates additional pre-market authorization barriers for non-traditional enzyme sources entering member states. Japan's FOSHU framework offers a contrasting pathway, enabling functional enzyme claims through rigorous clinical substantiation. Stakeholders must monitor divergent regulatory tolerance for structure-function versus disease claims across these jurisdictions to optimize portfolio allocation and labeling strategy.
Market Dynamics
FDA cGMP enforcement intensity and EFSA health claim assessments are bifurcating supplier compliance costs, forcing mid-tier enzyme manufacturers to consolidate or exit as certification burdens mount.
Growth Catalysts
- Japan's FOSHU framework:Functional enzyme claims gain regulatory legitimacy through rigorous clinical substantiation pathways, opening premium positioning for substantiated formulations.
- Functional food embedding:Beverage and snack manufacturers integrate protease and lactase into positioned wellness products, converting supplement buyers into habitual consumers.
- Direct-to-consumer subscription models:Digital-native wellness channels bypass traditional retail markups, capturing margin pools previously absorbed by distributors.
Market Restraints
- Microbial fermentation input volatility:Specialized yeast and bacterial strain supply concentrates among European contract manufacturers, exposing pricing to agricultural commodity swings.
- EU Novel Food pre-market barriers:Non-traditional enzyme sources face 18-24 month authorization timelines, freezing innovation pipelines for novel microbial strains.
- Plant-based enzyme performance gaps:Fungal-derived proteases outperform plant-sourced alternatives in gastric pH stability, limiting clean-label formulation flexibility.
Strategic Opportunities
- India's FSSAI regulatory evolution:Functional food categorization expansion creates first-mover advantage for enzyme-fortified traditional foods targeting lactose-intolerant populations.
- Sports nutrition performance optimization:Amylase-lipase blends for macronutrient timing protocols attract endurance athlete segments seeking measurable digestion metrics.
- Clinical nutrition program integration:Hospital formulary adoption of pancreatic insufficiency protocols expands reimbursed prescription enzyme volumes.
Industry Challenges
- Enzymologist talent scarcity:Formulation scientists with pH-activity optimization expertise command premium compensation, constraining R&D expansion at emerging suppliers.
- cGMP batch testing capex intensity:Identity verification and potency assay equipment requirements strain capital allocation for sub-$50M revenue manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digestive Enzymes Market |
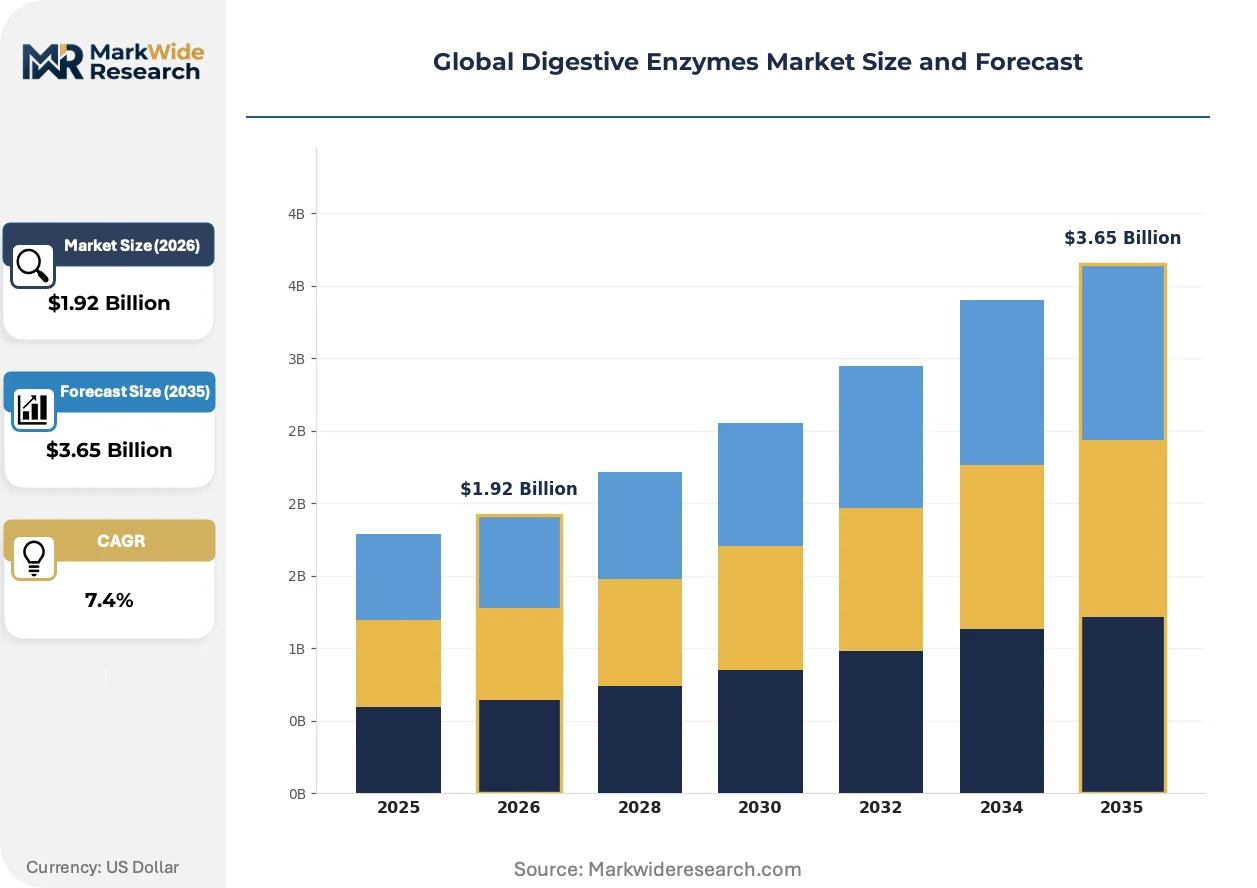
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.65 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protease, Amylase, Lipase, Cellulase, Lactase Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Animal Nutrition, Cosmetics End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Home Care Providers, Wellness Centers Form: Powder, Capsule, Liquid, Tablet, Gel |
| Companies Covered | GNC Holdings, Klaire Labs, Enzymedica, Nestle, Amway Corporation, NOW Health Group, Biotics Research Corporation, National Enzyme Company, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digestive Enzymes Market Shifts & Advancements
Bioprocess intensification and regulatory claim substantiation requirements are compressing product development cycles while elevating the technical threshold for competitive participation.
Cell-free enzyme synthesis is rewriting manufacturing economics by eliminating upstream fermentation bottlenecks. Contract manufacturers in Germany and Switzerland pilot continuous-flow biocatalysis systems, reducing batch-to-batch potency variance from 12% to under 4%. This compression of unit economics is rewriting margin structures for high-dose therapeutic formulations.
EFSA's 2023 guidance on enzyme-specific health claims tightens permissible marketing language for digestive efficacy assertions. Supplement marketers must now commission human intervention studies for structure-function claims, elevating substantiation costs. European direct-to-consumer brands respond by pivoting toward practitioner-only distribution where clinical credibility substitutes for consumer-facing claims.
Subscription-based replenishment models displace pharmacy and health food store purchasing for routine digestive support. Digital wellness platforms in the United States bundle enzyme protocols with microbiome testing, converting transactional buyers into annual contract relationships. This channel shift concentrates customer lifetime value data with platform operators rather than enzyme suppliers.
Global Digestive Enzymes Market Segmentation
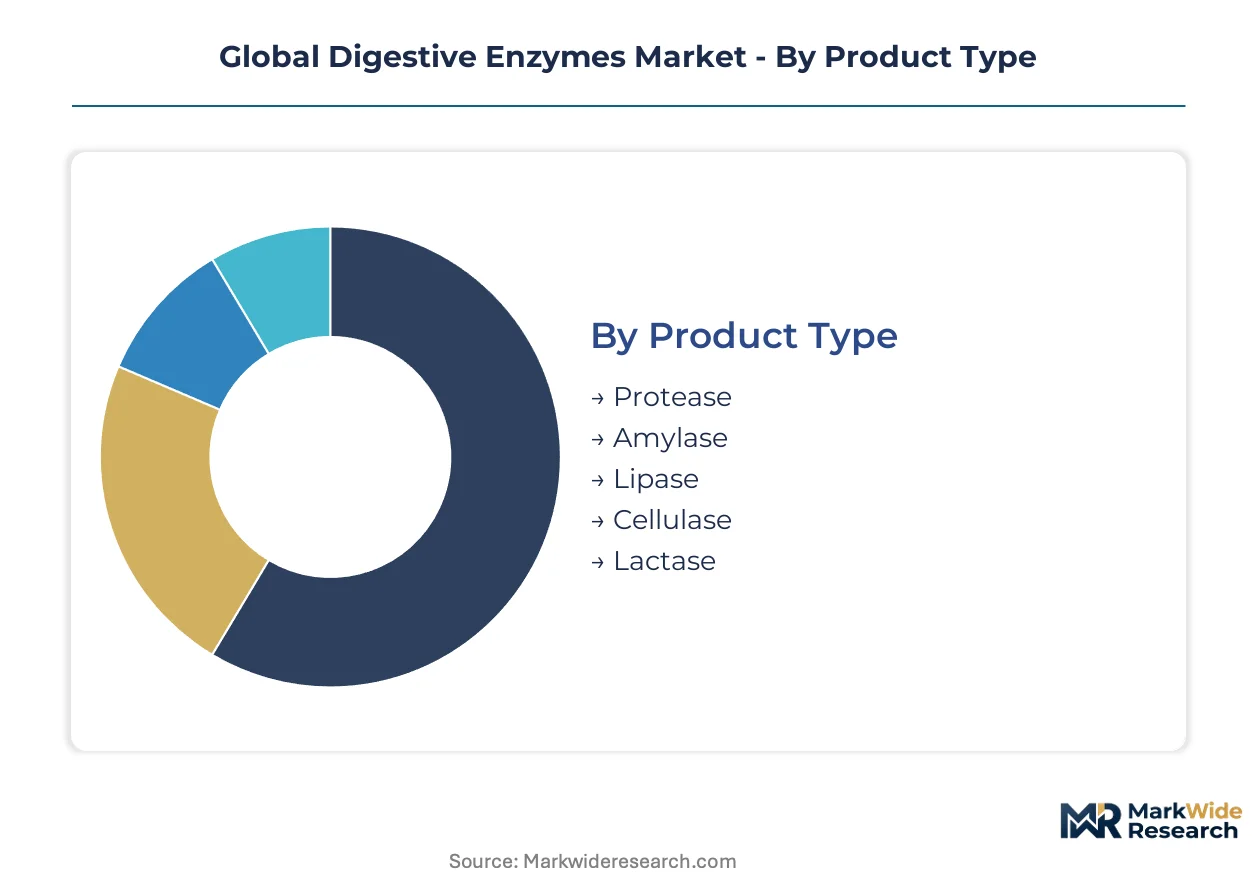
Enzyme segmentation determines regulatory pathway complexity and manufacturing investment intensity. Product type governs cGMP certification requirements, while application dictates whether FDA, EFSA, or FSSAI approvals apply.
Product Type:
FDA cGMP enforcement falls heaviest on protease and lipase formulations used in pancreatic insufficiency therapeutics, while EFSA Novel Food assessments constrain non-traditional microbial sources.
- Protease:Fungal-derived formulations dominate gastric pH stability requirements. Hospital formulary adoption in the United States and Germany drives prescription volumes for pancreatic insufficiency protocols.
- Lipase:High-dose therapeutic grades require batch potency variance below 4% under FDA scrutiny. Contract manufacturers in Switzerland and Germany invest in continuous-flow biocatalysis to meet specification.
- Amylase:Sports nutrition applications in the United States favor amylase-lipase blends for macronutrient timing.
- Cellulase:Plant-based enzyme positioning appeals to clean-label consumers seeking non-microbial alternatives.
- Lactase:Retail growth concentrates in direct-to-consumer channels as dairy intolerance awareness expands.
Leading the category by volume: protease. Growing fastest: lactase.
Application:
Margin structures diverge sharply between reimbursed pharmaceutical channels and subscription-based dietary supplement models.
- Dietary Supplements:Digital-native wellness platforms capture customer lifetime value through bundled microbiome testing. The United States dominates subscription replenishment models displacing traditional retail.
- Functional Foods:Beverage and snack manufacturers embed protease and lactase into positioned wellness products. Japan's FOSHU framework offers regulatory legitimacy for substantiated enzyme claims.
- Pharmaceuticals:Pancreatic insufficiency management requires EMA-approved high-dose formulations in Europe.
- Animal Nutrition:Feed enzyme applications face distinct regulatory pathways under USDA and equivalent national veterinary authorities.
- Cosmetics:Topical enzyme applications occupy niche positioning with limited clinical substantiation requirements.
Widest margin pool: dietary supplements. Steepest expansion trajectory: functional foods.
End User:
Procurement authority determines pricing power and formulation specification intensity across clinical versus consumer channels.
- Hospitals:Formulary committees in the United States and Germany mandate pancreatic enzyme replacement therapy protocols. Reimbursement coding drives volume concentration among high-dose lipase suppliers.
- Specialty Clinics:Gastroenterology practices in Japan and Switzerland prescribe therapeutic enzymes for malabsorption disorders.
- Diagnostic Laboratories:Enzyme-based testing reagents require distinct manufacturing certifications from nutritional grades.
- Home Care Providers:Long-term care facilities in the United States manage enteral nutrition with enzyme-fortified formulations.
- Wellness Centers:Practitioner-only distribution channels in Europe bypass EFSA consumer-facing claim restrictions.
Volume concentration: hospitals. Channel shift momentum: wellness centers.
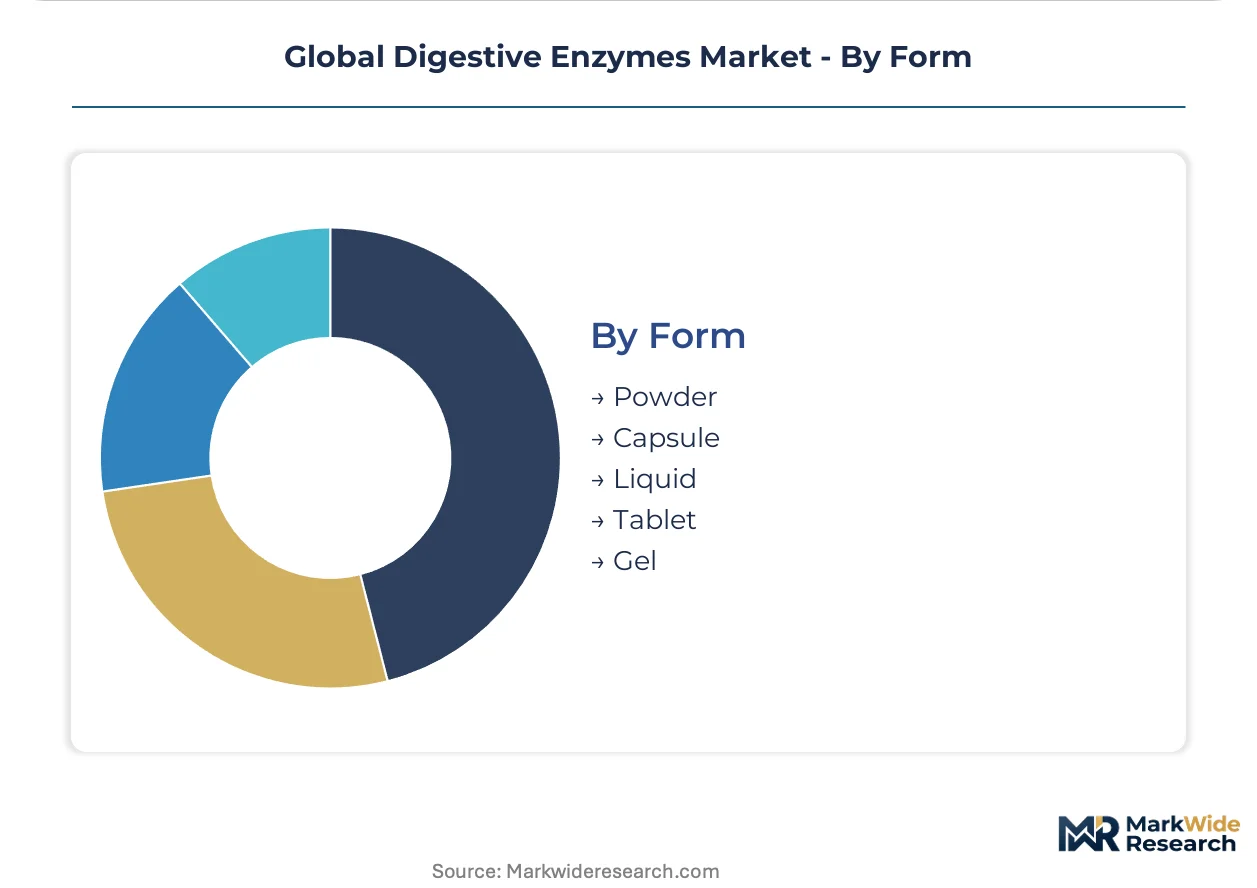
Form:
Manufacturing capex and stability validation requirements scale with dosage form complexity.
- Capsule:Enteric coating technology protects pH-sensitive enzymes through gastric transit. United States and German manufacturers lead in acid-resistant shell innovation.
- Powder:Bulk active pharmaceutical ingredient supply serves contract manufacturers with blending and tableting capabilities.
- Liquid:Pediatric and geriatric applications favor dropper delivery in Japan and United States home care settings.
- Tablet:Compression forces and excipient compatibility constrain heat-labile enzyme stability.
- Gel:Novel delivery formats target sports nutrition convenience positioning.
Dominant production format: capsule. Emerging format investment: liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized yeast and bacterial strain supply concentrates among European contract manufacturers, exposing pricing to agricultural commodity swings across fermentation-dependent production networks.
United States
Direct-to-consumer wellness channels and clinical nutrition programs drive premium formulation uptake. FDA cGMP enforcement elevates batch testing and identity verification costs for enzyme suppliers. Boston and San Diego clusters host contract manufacturers expanding multi-enzyme production lines to serve branded marketers.
Germany
Hospital formulary adoption of pancreatic enzyme replacement therapy protocols expands reimbursed prescription volumes. EMA oversight of high-dose therapeutic grades requires batch potency variance below 4%. Swiss and German manufacturers invest in continuous-flow biocatalysis systems around Basel-Zurich corridor.
Japan
Functional enzyme claims gain regulatory legitimacy through FOSHU framework's rigorous clinical substantiation pathways. METI guidance shapes permissible marketing language for digestive efficacy assertions. Tokyo-Osaka corridor concentrates digital wellness platforms bundling enzyme protocols with microbiome testing.
India
FSSAI regulatory evolution around functional food categorization creates first-mover advantage for enzyme-fortified traditional foods. CDSCO oversight of therapeutic grades parallels FDA stringency for export-oriented manufacturers. Maharashtra and Gujarat clusters specialize in plant-based enzyme extraction for clean-label export markets.
Switzerland
Swissmedic certification commands premium positioning in practitioner-only distribution channels. Continuous-flow biocatalysis pilots reduce batch-to-batch potency variance from 12% to under 4%. Basel region anchors contract manufacturing serving European pharmaceutical and nutraceutical formulators.
Global Digestive Enzymes Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance and fermentation capacity dimensions. The supplier base stratifies between vertically integrated nutraceutical conglomerates and specialized enzyme houses. Three archetypes dominate: pharmaceutical-grade specialists, plant-based clean-label formulators, and mass-market contract manufacturers. Competitive moves concentrate on cGMP certification acquisition and multi-enzyme production line expansion.
Within the plant-based formulation tier, Enzymedica and Garden of Life exemplify clean-label positioning archetypes. NOW Health Group occupies a position bridging mass-market and practitioner segments through captive manufacturing capabilities. Klaire Labs represents the clinical-specialist archetype serving gastroenterology practices with therapeutic-grade protocols.
| Leading Market Players |
|---|
| GNC Holdings |
| Klaire Labs |
| Enzymedica |
| Nestle |
| Amway Corporation |
| NOW Health Group |
| Biotics Research Corporation |
| National Enzyme Company |
| Garden of Life |
| Others |
Supply & Pricing Matrix
FDA-mandated cGMP batch testing requirements are forcing mid-tier enzyme suppliers to either absorb identity verification equipment costs or exit reimbursed pharmaceutical channels entirely. This procurement specification compression stratifies the supplier base between certified premium-grade manufacturers and uncertified commodity producers.
Pricing Analysis
Certification-inclusive contract structures separate FDA-validated therapeutic grades from uncertified dietary supplement tiers. Price differentiation hinges on EMA batch potency variance specifications below 4% versus standard 12% variance allowances, with Swiss and German contract manufacturers commanding premiums for continuous-flow biocatalysis guarantees. Cost compression in mass-market supplement tiers is intensifying as direct-to-consumer subscription models displace retail markups. Hospital formulary procurement committees exhibit lowest price sensitivity due to reimbursement coding, while wellness platform subscribers show highest elasticity to monthly replenishment costs.
Supply Chain Analysis
Dual-sourcing mandates from United States and German pharmaceutical formulators require qualified backup suppliers for high-dose lipase and protease strains. Fermentation capacity concentrates in Switzerland, Germany, and India, with specialized yeast and bacterial strain libraries anchoring European contract manufacturing dominance. Raw material dependencies include agricultural substrate feedstocks, pH-buffering excipients, and enteric coating polymers. Single-source vulnerability runs through European microbial strain repositories concentrated around Basel-Zurich corridor. Distribution runs through practitioner-only channels in Europe, direct-to-consumer platforms in the United States, and FOSHU-authorized functional food networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-free enzyme synthesis is displacing legacy fermentation-dependent manufacturing, compressing unit economics for high-dose therapeutic formulations and rewriting competitive thresholds.
For Market Incumbents: Acquire continuous-flow biocatalysis equipment and pH-activity optimization talent pools before enzymologist scarcity drives compensation premiums beyond R&D expansion feasibility. Consolidate fermentation capacity in Switzerland and Germany to defend against Indian plant-based enzyme competitors targeting clean-label export markets. cGMP certification acquisition represents the critical defensive lever for maintaining hospital formulary positioning. For New Entrants and Emerging Players: Launch via India's FSSAI-evolving functional food categorization pathway, targeting enzyme-fortified traditional foods for lactose-intolerant populations before regulatory clarity attracts multinational competition. White-space concentrates in sports nutrition amylase-lipase blends for macronutrient timing protocols and practitioner-only European distribution bypassing EFSA consumer-facing claim restrictions. For Investors and Strategic Acquirers: The window for entry favors clinical-specialist enzyme houses with therapeutic-grade protocols and existing gastroenterology practice relationships. Long-term viability hinges on regulatory claim substantiation capabilities rather than commodity fermentation scale. Swissmedic certification momentum serves as the inflection indicator for premium positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Biocatalysis Adoption | Switzerland and Germany contract manufacturers reduce batch potency variance from 12% to under 4%. |
| FOSHU Framework Clinical Substantiation | Japanese METI pathway enables premium functional enzyme claims with rigorous evidence requirements. |
| Direct-to-Consumer Subscription Launch | United States digital wellness platforms capture customer lifetime value through bundled microbiome testing. |
| cGMP Certification Investment | FDA enforcement elevates identity verification costs, forcing mid-tier supplier consolidation. |
| Plant-Based Enzyme Extraction Scale-Up | India's Maharashtra and Gujarat clusters target clean-label export markets with non-microbial alternatives. |
Research Methodology
FDA enforcement action databases, EFSA Novel Food authorization registries, and FOSHU approval listings formed the secondary backbone for regulatory pathway mapping. Primary interviews with contract manufacturing executives, gastroenterology practitioners, hospital formulary directors, and dietary supplement procurement managers at wellness platforms informed supply chain and channel dynamics. Bottom-up and top-down triangulation validated segment-level volume estimates against customs fermentation equipment import data and enzyme active pharmaceutical ingredient trade flows.
Bottom-up modeling anchored volume projections to hospital prescription volumes, subscription platform subscriber counts, and functional food embedding rates across beverage and snack categories. Segmentation dimensions included enzyme type, application channel, end-user procurement authority, and dosage form complexity. CAGRs derived from regression analysis of historical pricing trajectories and capacity expansion announcements. Forecast inputs incorporated cGMP certification penetration rates and cell-free synthesis technology adoption curves.
Regulatory enforcement intensity shifts, microbial strain supply disruptions, and enzymologist talent availability are the dominant revision risks to capacity and pricing assumptions. Deviation in FDA cGMP audit frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Australia Nutraceuticals Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Liuweidihuang Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Tryptophan Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Lutein Market