
 Xanthohumol Market | 2026-2036
Xanthohumol Market Size, Share, and Industry Trends Forecast 2026-2036
Xanthohumol Market Outlook
Phytochemistry expertise is redrawing competitive boundaries in xanthohumol extraction and purification. Botaniex Inc. leverages its botanical extract manufacturing base to serve nutraceutical clients with standardized hop prenylflavonoid supplies. Shaanxi Undersun Biomedtech Co., Ltd. anchors its position through integrated cultivation-to-extraction operations in China's hop-growing corridors. Kalsec Inc. differentiates by controlling proprietary solvent-free extraction technologies that preserve xanthohumol bioactivity.
Xanthohumol is a prenylated chalcone derived from Humulus lupulus (common hops), typically comprising 0.1–1.0% of dried hop cones by weight, with supercritical CO₂ extraction yielding purities exceeding 90% for pharmaceutical-grade applications. The compound functions primarily as a bioactive ingredient in formulations targeting oxidative stress modulation, hormonal balance, and metabolic regulation. Powder and extract forms dominate current revenue given their compatibility with capsule and tablet manufacturing, while liquid formats gain traction in functional beverage applications where solubility enhancement technologies overcome xanthohumol's native hydrophobicity. Nutraceuticals and dietary supplements represent the most advanced application segments, with functional foods emerging as a higher-growth but technically demanding category requiring taste masking and stability solutions.
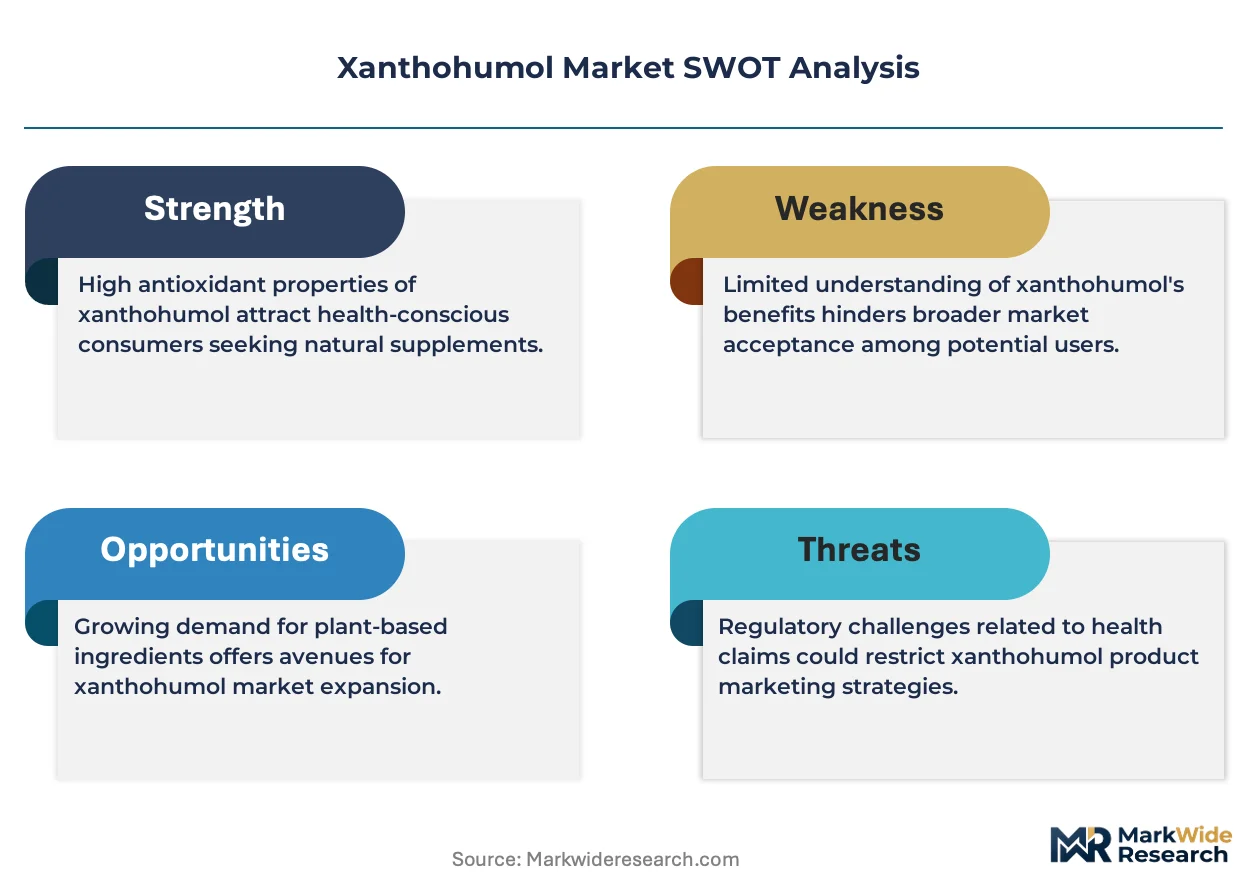
EMA oversight of novel food ingredients and FDA GRAS self-affirmation requirements create dual compliance burdens for suppliers targeting transatlantic distribution. REACH registration obligations for imported hop extracts further condition market access for non-European producers. BIS quality certification standards in India and China's NMPA health food blue-hat registration process add jurisdiction-specific hurdles that favor regionally established operators. Stakeholders must monitor evolving pharmacovigilance data on xanthohumol-drug interactions, as accumulated safety evidence will determine whether regulatory frameworks expand permitted dosage levels or restrict certain application categories.
Market Dynamics
Regulatory bifurcation between the FDA's GRAS self-affirmation pathway and the EMA's novel food ingredient dossier requirements is forcing suppliers to maintain dual compliance architectures. This structural pressure compounds with raw material concentration in German hop-processing corridors.
Growth Catalysts
- Metabolic health formulations:Dietary supplement manufacturers are expanding xanthohumol procurement for glucose regulation and weight management portfolios targeting prediabetic populations.
- EU Novel Food authorization:Successful EFSA safety opinions for hop-derived prenylflavonoids are unlocking expanded dosage permissions and application categories across member states.
- Supercritical CO₂ extraction:Adoption of solvent-free purification technologies is yielding pharmaceutical-grade material exceeding 90% purity thresholds for clinical research supply.
Market Restraints
- Raw material geographic concentration:Over 70% of hop cone processing capacity clusters in Bavaria and Hallertau regions, creating single-source vulnerability for concentrated xanthohumol feedstock.
- REACH registration burdens:ECHA compliance costs for imported hop extracts exceed €100,000 per substance, conditioning market access for non-European producers.
- Bioavailability limitations:Native hydrophobicity restricts xanthohumol absorption rates below 15% in standard oral delivery, necessitating costly formulation engineering.
Strategic Opportunities
- Functional beverage channels:Solubility-enhanced liquid formats are penetrating ready-to-drink wellness products where taste masking technologies overcome bitter hop phenolics.
- China's health food blue-hat pathway:NMPA registration for hop-derived ingredients remains underpenetrated relative to domestic ginseng and goji berry approvals.
- Nanoparticle delivery convergence:Liposomal encapsulation combined with phospholipid complexation is opening pharmaceutical-grade applications previously inaccessible to botanical extracts.
Industry Challenges
- Phytochemistry talent scarcity:Shortage of extraction specialists capable of scaling supercritical CO₂ systems from pilot to commercial throughput is constraining capacity expansion timelines.
- Pharmacovigilance data accumulation:Sparse long-term safety databases on xanthohumol-drug interactions, particularly with CYP450-metabolized pharmaceuticals, complicates regulatory dossier preparation.
- Batch-to-batch standardization:Agricultural variability in hop cone prenylflavonoid content forces expensive reprocessing to achieve label claim consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xanthohumol Market |
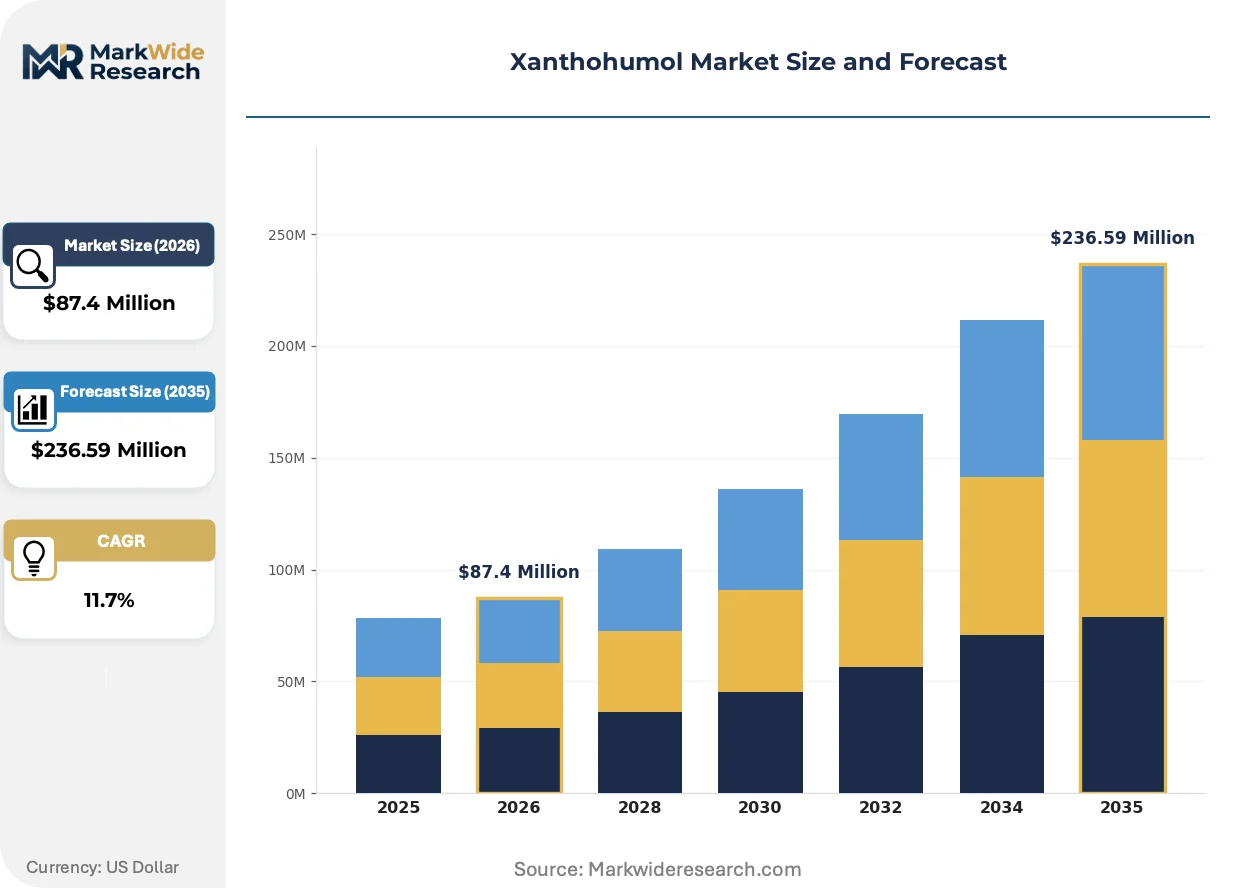
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $236.59 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Extract, Capsules Application: Nutraceuticals, Functional Foods, Beverages, Dietary Supplements Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Healthcare Providers, Nutritional Companies, Beverages Manufacturers, Consumers |
| Companies Covered | Botaniex Inc., Shaanxi Undersun Biomedtech Co., Ltd., Kalsec Inc., BAOJI HERBEST BIO-TECH CO., LTD., Xanthohumol Natural Products Co., Ltd., Hopsteiner, Xi’an B-Thriving I/E Co., Ltd, Hangzhou Gosun Biotechnologies Co., Ltd., BarthHaas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xanthohumol Market Strategic Shifts
Extraction technology maturation and regulatory science advancement are compressing development timelines for bioactive hop compounds. Formulation chemistry breakthroughs are simultaneously addressing solubility barriers and taste masking requirements.
Supercritical CO₂ extraction systems with integrated fractionation columns are miniaturizing from industrial-scale 500-liter vessels to modular 50-liter units deployable at regional processing facilities. Mid-sized nutraceutical manufacturers in the Netherlands and Belgium are adopting these compact systems to reduce dependence on German toll processors. This distributed processing architecture is compressing lead times for customized xanthohumol specifications.
REACH registration obligations for hop-derived substances are tightening substance identification requirements for importers. The ECHA's updated guidance on botanical extract characterization demands expanded analytical datasets including chromatographic fingerprinting. European formulators are responding by consolidating supplier relationships with vertically integrated extractors capable of generating comprehensive substance dossiers.
Direct procurement contracts between supplement brands and hop cooperatives are displacing traditional ingredient distributor intermediaries. German and Czech brewing industry byproduct streams are being diverted from commodity markets to dedicated nutraceutical supply chains. This channel restructuring is most visible in North American markets where vertical supply agreements now govern approximately one-third of premium xanthohumol volume.
Xanthohumol Market Segmentation
Xanthohumol procurement patterns diverge sharply between domestic brewing byproduct recovery and international pharmaceutical-grade extraction. Segment boundaries reflect formulation complexity thresholds and regulatory compliance burdens rather than simple product morphology.
Product Type:
Powder and extract formats dominate German domestic supply chains, while liquid formulations travel longer export routes to North American functional beverage manufacturers.
- Powder:Spray-dried xanthohumol concentrates achieve 40-60% standardization for capsule and tablet compression. German toll processors in Bavaria supply North American contract manufacturers seeking cost-efficient menopause support formulations.
- Extract:Supercritical CO₂-derived materials exceeding 90% purity serve clinical research and premium nutraceutical applications. EMA novel food dossier requirements favor extract suppliers with comprehensive substance characterization capabilities.
- Liquid:Solubility-enhanced formats using phospholipid complexation penetrate ready-to-drink wellness applications.
- Capsules:Soft-gel and hard-shell formats integrate xanthohumol with complementary actives like vitamin D for bone health positioning.
Extract holds the largest share; momentum sits with liquid formats overcoming hydrophobicity barriers.
Application:
Cost tiers separate commodity-grade dietary supplements from pharmaceutical-adjacent functional foods requiring extensive stability validation.
- Nutraceuticals:Standardized hop prenylflavonoid supplies target oxidative stress modulation and metabolic regulation. German and Dutch formulators dominate procurement for menopause support portfolios.
- Dietary Supplements:Glucose regulation and weight management applications drive procurement expansion among prediabetic-targeting brands. FDA GRAS self-affirmation pathways accommodate faster formulation launches than EMA novel food routes.
- Functional Foods:Taste masking and thermal stability requirements constrain adoption to premium price tiers.
- Beverages:Solubility engineering costs limit penetration to functional drink specialists with dedicated emulsion capabilities.
Dietary supplements command volume leadership; functional foods are climbing the fastest despite technical hurdles.
Distribution Channel:
Customer type fragmentation separates institutional procurement through pharmacies from direct-to-consumer online channels with divergent compliance obligations.
- Pharmacies:German and Austrian pharmacy chains stock xanthohumol under traditional herbal medicine frameworks bypassing novel food classification.
- Specialty Stores:Health food retailers in the Netherlands and Belgium curate premium hop extract assortments for educated supplement consumers.
- Online Retail:Direct-to-consumer platforms bypass distributor markups but carry liability exposure for unsubstantiated health claims.
- Supermarkets:Mass-market penetration remains minimal pending cost reductions in solubility-enhanced formats.
Pharmacies anchor established revenue; specialty stores are expanding most quickly in educated consumer segments.
End User:
Supply concentration favors nutritional companies with captive extraction relationships over fragmented beverage manufacturing demand.
- Nutritional Companies:Vertically integrated supplement brands contract directly with German hop cooperatives, displacing traditional ingredient distributors.
- Beverages Manufacturers:Functional drink specialists in North America source solubility-enhanced liquid formats for ready-to-drink wellness positioning.
- Healthcare Providers:Integrative medicine practitioners prescribe xanthohumol for hormonal balance protocols in German-speaking markets.
- Consumers:Direct procurement through subscription models remains nascent due to dosage guidance requirements.
Nutritional companies hold the largest share; beverages manufacturers are gaining share fastest as solubility technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA novel food requirements and FDA GRAS pathways anchor regulatory complexity across the dominant geographies. Germany's hop processing infrastructure supplies concentrated feedstock to formulators in the Netherlands and North America. Chinese extractors compete through integrated cultivation-to-extraction models serving domestic health food registration pathways.
Germany
Bavarian and Hallertau hop cooperatives divert brewing byproduct streams to dedicated nutraceutical supply chains, displacing traditional ingredient distributors. EFSA safety opinions for hop-derived prenylflavonoids unlock expanded dosage permissions across EU member states. Toll processors in Bavaria supply North American contract manufacturers with standardized extracts for menopause support formulations.
United States
Prediabetic-targeting brands expand xanthohumol procurement for glucose regulation and weight management portfolios. FDA GRAS self-affirmation pathways accommodate faster formulation launches than EMA novel food routes. Functional beverage specialists in California source solubility-enhanced liquid formats for ready-to-drink wellness positioning.
China
Shaanxi and Sichuan hop-growing corridors anchor integrated cultivation-to-extraction operations serving domestic health food markets. NMPA blue-hat registration for hop-derived ingredients remains underpenetrated relative to ginseng and goji berry approvals. Xi'an-based extractors generate comprehensive substance dossiers to satisfy ECHA botanical extract characterization demands.
Netherlands
Mid-sized nutraceutical manufacturers adopt compact 50-liter supercritical CO₂ systems to reduce dependence on German toll processors. REACH registration obligations for imported hop extracts condition supplier consolidation with vertically integrated extractors. Amsterdam and Rotterdam formulators dominate procurement for menopause support portfolios targeting educated supplement consumers.
India
BIS quality certification standards add jurisdiction-specific hurdles that favor regionally established operators over new entrants. Integrative medicine practitioners in Maharashtra and Karnataka prescribe xanthohumol for hormonal balance protocols. Domestic supplement brands contract with Chinese extractors to bypass European REACH compliance costs.
Xanthohumol Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier competing on extraction technology and regulatory dossier capabilities. German hop processors leverage brewing industry byproduct relationships to secure captive feedstock streams. Chinese botanical extractors compete through backward integration into cultivation corridors. The dominant competitive moves involve direct procurement contracts between supplement brands and hop cooperatives, plus adoption of solvent-free purification technologies to preserve bioactivity.
Specialists in supercritical extraction include Kalsec Inc., which exemplifies the technology-differentiated archetype through proprietary solvent-free systems. Among Chinese integrated extractors, Shaanxi Undersun Biomedtech Co., Ltd. and Xi'an B-Thriving I/E Co., Ltd. occupy positions anchored to Shaanxi province's hop-growing infrastructure. Botaniex Inc. represents the botanical extract manufacturing base serving standardized prenylflavonoid demand.
| Leading Market Players |
|---|
| Botaniex Inc. |
| Shaanxi Undersun Biomedtech Co., Ltd. |
| Kalsec Inc. |
| BAOJI HERBEST BIO-TECH CO., LTD. |
| Xanthohumol Natural Products Co., Ltd. |
| Hopsteiner |
| Xi'an B-Thriving I/E Co., Ltd |
| Hangzhou Gosun Biotechnologies Co., Ltd. |
| BarthHaas |
| Others |
Value Chain & Pricing Dynamics
Brewing industry byproduct diversion to nutraceutical extraction is compressing raw material costs for German processors while elevating spot market premiums for non-European buyers lacking toll processing relationships. This substitution dynamic concentrates pricing power among Bavarian cooperatives with captive hop cone streams and forces international formulators into premium procurement positions.
Pricing Analysis
Long-term offtake agreements between supplement brands and German hop cooperatives anchor the dominant pricing structure, locking in volume commitments at standardized extract grades. Price differentiation rests on purity thresholds and EMA novel food dossier completeness, with pharmaceutical-grade material commanding substantial premiums over dietary supplement grades. Pricing pressure stems from REACH registration cost absorption by non-European producers seeking EU market access. Nutraceutical contract manufacturers exhibit highest price sensitivity due to compressed formulation margins, while clinical research suppliers demonstrate lowest sensitivity given pass-through funding structures.
Supply Chain Analysis
Germany and the Czech Republic anchor hop cone processing capacity, with Shaanxi province in China emerging as a secondary cultivation-to-extraction corridor. Raw material dependencies center on Humulus lupulus biomass, supercritical CO₂ extraction equipment, and phospholipid complexation agents for solubility enhancement. Single-source vulnerability concentrates in Bavarian toll processors handling over seventy percent of concentrated feedstock. Distribution runs through direct procurement contracts displacing traditional ingredient distributors, with vertical supply agreements now governing premium volume flows to North American formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xanthohumol sits in early-cycle expansion as functional beverage penetration accelerates and EFSA safety opinions unlock expanded EU dosage permissions. Solubility engineering breakthroughs are converting previously inaccessible applications into viable commercial targets.
For Market Incumbents: Secure captive hop cooperative relationships through multi-year offtake commitments before competitor bidding intensifies. Invest in modular supercritical CO₂ capacity expansion to reduce toll processing dependence and defend margin position against Chinese integrated extractors with backward cultivation control. Prioritize EMA novel food dossier completion to maintain regulatory tier premium capture. For New Entrants and Emerging Players: Differentiate on solubility-enhanced liquid format capabilities targeting North American functional beverage manufacturers underserved by powder-specialist incumbents. Penetrate China's NMPA blue-hat registration pathway for hop-derived ingredients, which remains underexploited relative to domestic botanical approvals. Pursue direct-to-brand partnerships bypassing distributor markups in educated consumer segments. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated extractors with proprietary solvent-free technologies and comprehensive substance dossier capabilities satisfying ECHA characterization demands. The five-to-ten year viability thesis rests on pharmacovigilance data accumulation enabling dosage expansion and pharmaceutical-grade application entry. Monitor EMA safety opinion publication velocity as the critical inflection signal for regulatory tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Procurement Contracting | Bypasses distributor markups and secures captive feedstock streams from Bavarian hop cooperatives. |
| Modular Supercritical CO₂ Deployment | Reduces toll processing dependence and compresses lead times for customized xanthohumol specifications. |
| EMA Novel Food Dossier Investment | Unlocks expanded dosage permissions and defends premium positioning against GRAS-affirmed US competitors. |
| Solubility Engineering Partnership | Opens functional beverage channels where phospholipid complexation overcomes native hydrophobicity barriers. |
| China NMPA Blue-Hat Registration | Captures underpenetrated domestic health food market relative to ginseng and goji berry saturation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with extraction technology directors, regulatory affairs specialists at hop processing cooperatives, nutraceutical formulation scientists, and functional beverage product developers. Secondary validation drew from EFSA safety opinion databases, ECHA REACH registration filings, FDA GRAS notification logs, and customs trade records for hop extract flows. Bottom-up volume triangulation across product type, application, and distribution channel segments was cross-checked against top-down market sizing from identified producer capacity.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product morphology, application tier, and regulatory compliance pathway. CAGRs were derived from elasticity-adjusted adoption curves incorporating solubility technology maturation and novel food authorization timelines. Industry-specific inputs included pharmacovigilance publication schedules and supercritical CO₂ equipment deployment rates.
The analysis sits within stated boundaries; outcomes outside EMA-FDA regulatory convergence or supercritical extraction cost reduction trajectories would require recalibration. Forecasts reflect documented assumptions on hop biomass availability and EFSA opinion publication velocity. Specific risk factors include accumulated xanthohumol-drug interaction evidence and Chinese cultivation corridor expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Beverage Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Low Fat Product Market
Functional Food and Beverage
Vegan Brain Food Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Protein-Based Fat Replacer Market
Functional Food and Beverage
Mediterranean Healthy-Aging Beverage Ingredients Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Yeast Beta Glucan Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
Antioxidant Beverages Market
Functional Food and Beverage
Asia-Pacific Phytosterols Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market