
 Asia-Pacific Phytosterols Market | 2026-2036
Asia-Pacific Phytosterols Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Phytosterols Market Outlook
Southeast Asian oleochemical processors is realigning phytosterol extraction capacity toward higher-purity outputs for pharmaceutical-grade applications. Cargill Incorporated leverages its integrated oilseed crushing network across Indonesia and Malaysia to secure raw material streams for sterol isolation. BASF SE sustains technology leadership through proprietary solvent-free purification systems that reduce residual lipid contamination below pharmacopeial thresholds. Matrix Fine Sciences Pvt Ltd anchors Indian domestic supply through backward integration into rice bran oil refining, a high-yield sterol feedstock.
Asia-Pacific phytosterols comprise plant-derived 4-desmethyl sterols—principally beta-sitosterol, campesterol, and stigmasterol—extracted from vegetable oil deodorizer distillates or tall oil pitch, typically standardized to 95% total sterol content for nutraceutical use and serving primarily as cholesterol-metabolism modulators in functional foods and lipid-lowering therapeutics. Beta-sitosterol dominates volume due to its abundance in soy and rapeseed sources, though stigmasterol commands premium positioning in pharmaceutical applications requiring specific prodrug precursors. The application split reveals nutraceuticals as the fastest-expanding consumption channel, while food and beverages retains the deepest margin pool through long-term supply contracts with multinational dairy and spread manufacturers.
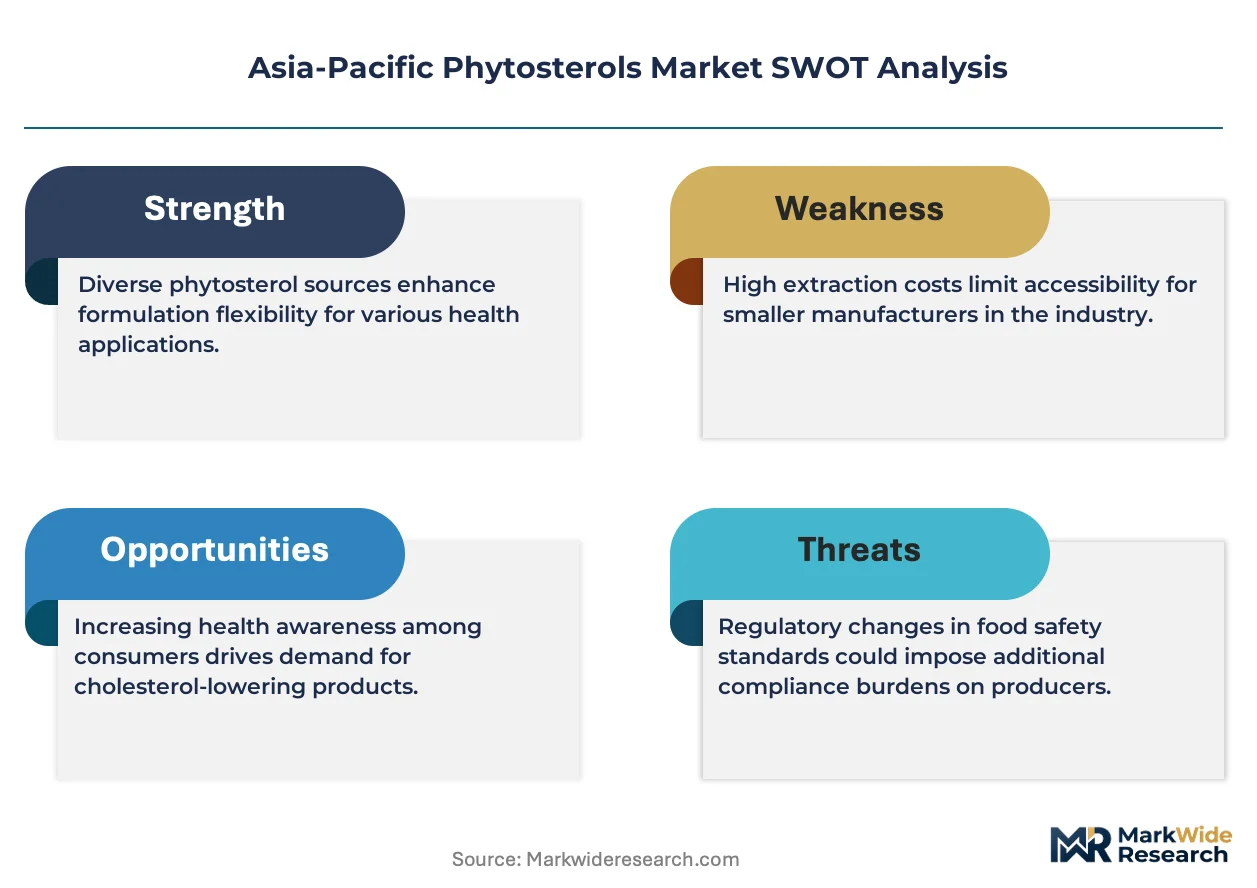
FSSAI in India, China's NMPA, and Japan's MHLW collectively govern phytosterol product standards—ranging from maximum allowable daily intake labeling to novel food ingredient approvals—thereby dictating formulation ceilings and market entry timelines across the region. REACH-equivalent substance registration requirements in multiple Asia-Pacific jurisdictions further constrain raw material sourcing flexibility for imported sterol intermediates. Stakeholders must monitor evolving maximum-level regulations for phytosterol-fortified foods, as tightening thresholds in key markets will determine whether reformulation investments or portfolio pruning becomes the more viable strategic response.
Market Dynamics
India's FSSAI labeling enforcement is compelling reformulation investments across cholesterol-lowering claim categories, while China's NMPA novel food approvals dictate entry timelines for imported sterol intermediates. This regulatory compression is reshaping competitive positioning toward backward-integrated domestic producers.
Growth Catalysts
- Nutraceutical contract manufacturing:Domestic supplement brands in China's Shanghai-Jiangsu corridor scale production for export markets, creating pull for pharmaceutical-grade sterol outputs.
- FSSAI claim standardization:Tightened cholesterol-lowering labeling norms in India force portfolio upgrades, filtering out non-compliant imports and rewarding certified domestic suppliers.
- Solvent-free purification:Proprietary systems reducing residual lipid contamination below pharmacopeial thresholds enable premium positioning in therapeutic applications.
Market Restraints
- Deodorizer distillate supply concentration:Vegetable oil refining capacity in Indonesia and Malaysia controls raw material access, creating feedstock bottlenecks for non-integrated processors.
- REACH-equivalent registration:Multiple Asia-Pacific jurisdictions impose substance registration requirements on imported sterol intermediates, constraining sourcing flexibility.
- Stigmasterol yield limitations:Specific prodrug precursor requirements in pharmaceutical applications face supply constraints from non-soy feedstocks.
Strategic Opportunities
- Rice bran oil integration:India's underdeveloped rice bran refining capacity offers white space for high-yield sterol feedstock capture through backward integration.
- Functional beverage fortification:Dairy alternative manufacturers in China expand phytosterol inclusion, creating new formulation partnerships beyond traditional spreads.
- Dual carbon alignment:China's SAMR sustainability incentives favor low-carbon extraction technologies, rewarding process innovators with preferential approval pathways.
Industry Challenges
- Pharmacopeial certification timelines:Japan's MHLW and China's NMPA approval cycles for novel sterol applications extend commercialization horizons by 18-36 months.
- Multi-jurisdiction compliance staffing:Simultaneous FSSAI, NMPA, and MHLW filing requirements strain regulatory affairs capacity at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Phytosterols Market |
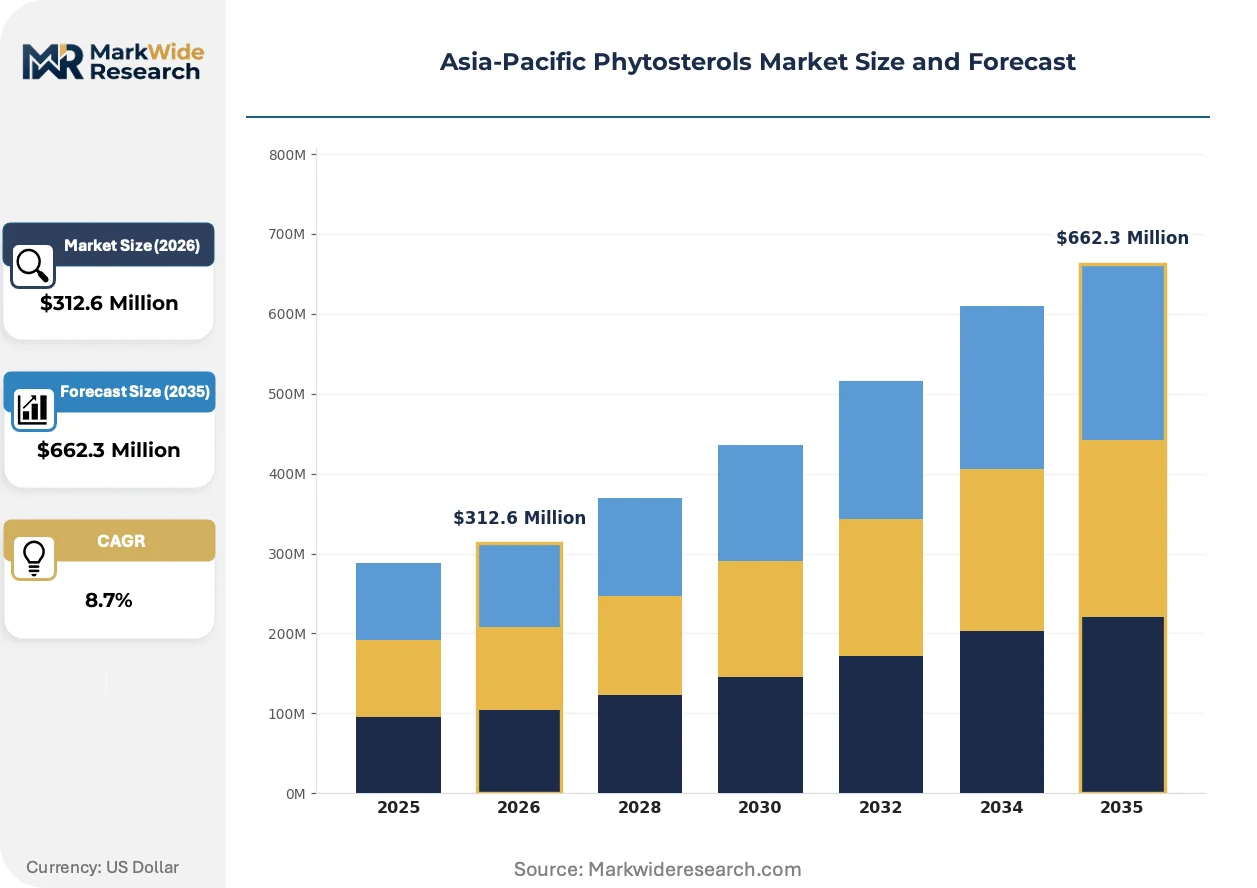
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $662.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Sitosterol, Campesterol, Stigmasterol, Brassicasterol Application: Food & Beverages, Nutraceuticals, Personal Care, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Dietary Supplement Providers, Pharmaceutical Firms Form: Powder, Liquid, Granules, Emulsified |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, BASF SE, Ashland Global Specialty Chemicals Inc, Matrix Fine Sciences Pvt Ltd, DuPont Nutrition & Health, Gustav Parmentier GmbH, Kraft Heinz Company, Kemin Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Phytosterols Market Strategic Shifts
Technology convergence between extraction automation and purity analytics is compressing batch-to-batch variability, while regulatory harmonization pressures are forcing standardization investments across the Asia-Pacific phytosterols value chain.
Supercritical CO2 extraction is consolidating as the dominant purification modality for pharmaceutical-grade sterols, replacing legacy solvent-based systems. Nutraceutical contract manufacturers in China's Jiangsu province adopt these units at 40% capacity expansion rates. This technology shift is consolidating market share toward processors with capital deployment capability above 50 million RMB.
China's NMPA novel food ingredient approval framework tightens documentation requirements for imported sterol concentrates, extending review timelines. Domestic producers with established GB standard compliance records capture accelerated pathways. The nutraceutical segment responds by prioritizing in-country formulation over direct import of finished sterol blends.
Buyers in Japan's functional foods sector compress supplier qualification cycles from 24 months to 12 months, demanding real-time purity certification rather than batch release documentation. This behavioral shift displaces spot-market procurement with multi-year supply agreements. The pattern is most visible in Tokyo-Osaka corridor dairy alternative manufacturers seeking sterol-fortified product lines.
Asia-Pacific Phytosterols Market Segmentation
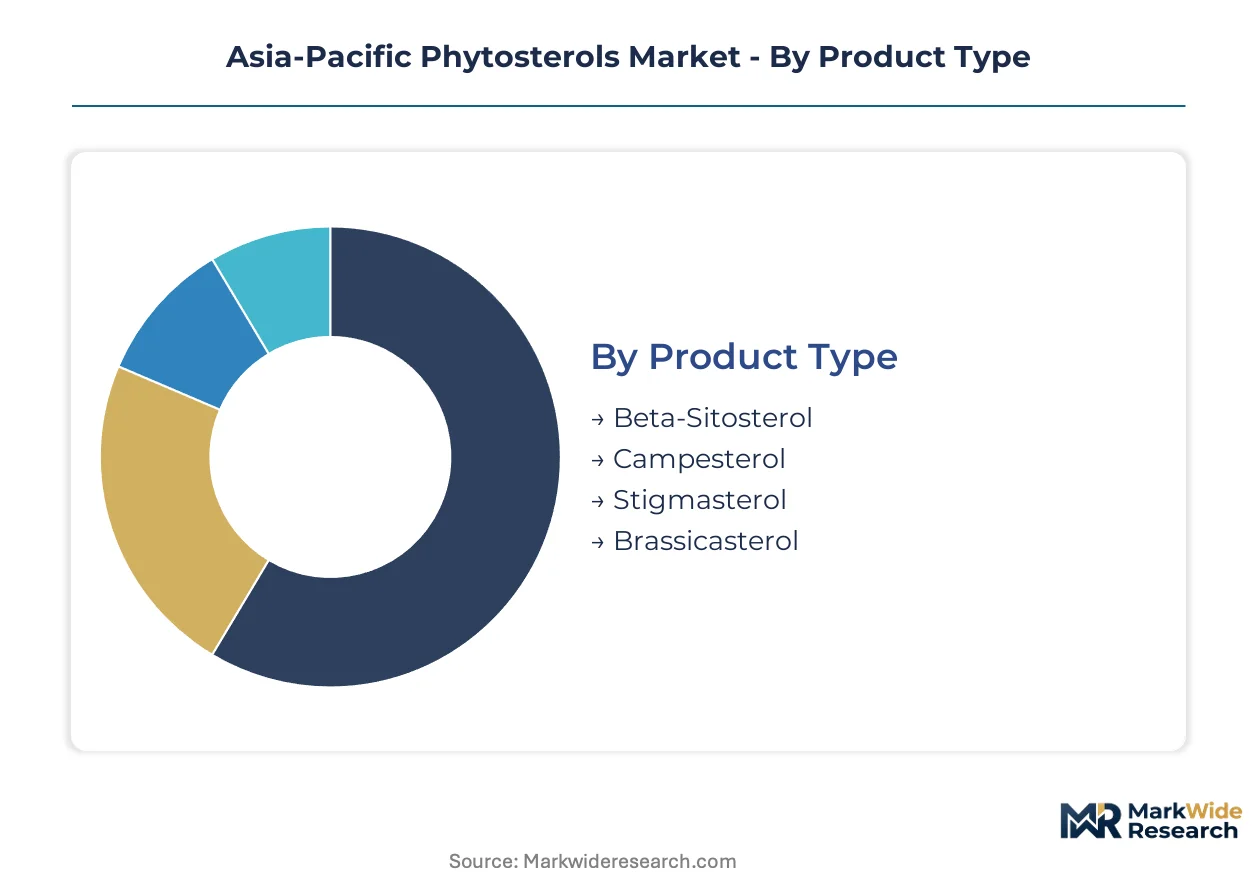
Phytosterol procurement patterns diverge sharply across product grades and end-use specifications, with pharmaceutical buyers demanding pharmacopeial certification while food manufacturers prioritize cost-optimized standardization. Segmentation discipline separates margin-accretive therapeutic applications from volume-driven functional food channels.
Product Type:
Standardization intensity varies from commodity-grade beta-sitosterol to precision-specified stigmasterol isolates, reflecting the customization spectrum from bulk nutraceutical inputs to pharmaceutical precursor requirements.
- Beta-Sitosterol:The predominant 4-desmethyl sterol extracted from soy and rapeseed deodorizer distillates, typically standardized to 95% purity for cholesterol-lowering functional foods. Demand clusters in China's Shanghai-Jiangsu nutraceutical corridor where domestic supplement brands scale contract manufacturing for export markets.
- Stigmasterol:A C-24 ethyl-substituted sterol commanding premium positioning as a specific prodrug precursor in pharmaceutical synthesis, with supply constraints from non-soy feedstocks limiting volume expansion. India's rice bran oil processors capture this segment through backward integration into high-yield sterol feedstock refining.
- Campesterol:C-24 methyl-substituted sterol co-isolated with beta-sitosterol, serving as a secondary active in blended nutraceutical formulations.
- Brassicasterol:Ergostane-derived sterol concentrated in rapeseed and mustard oil distillates, utilized in specialized cosmetic applications requiring specific unsaturation profiles.
Leading the category by volume: Beta-Sitosterol. Expanding most quickly: Stigmasterol.
Application:
Margin architecture inverts across this dimension, with long-term supply contracts in food and beverages anchoring cash flow while nutraceutical spot demand drives price volatility.
- Food & Beverages:Phytosterol fortification in dairy alternatives, spreads, and functional beverages, where China's SAMR novel food approvals dictate 18-36 month entry timelines for imported concentrates. India's FSSAI tightened labeling norms compel reformulation investments across cholesterol-lowering claim categories.
- Nutraceuticals:Dietary supplement capsules and tablets targeting lipid metabolism modulation, with supercritical CO2 extraction systems consolidating market share toward processors with capital deployment above 50 million RMB in China's Jiangsu province.
- Personal Care:Emollient and anti-inflammatory applications in topical formulations, primarily sourcing brassicasterol-rich fractions from rapeseed-derived feedstocks.
- Pharmaceuticals:Sterol precursors for hormone synthesis and therapeutic lipid-lowering agents, where Japan's MHLW pharmacopeial certification timelines extend commercialization horizons.
Deepest margin pool: Food & Beverages. Steepest expansion trajectory: Nutraceuticals.
End User:
Procurement sophistication separates multinational food manufacturers with integrated quality systems from mid-scale cosmetic compounders managing spot-market variability.
- Food Manufacturers:Multinational dairy and spread producers in China and India negotiating long-term supply agreements with integrated oilseed processors.
- Dietary Supplement Providers:Domestic brands in China's nutraceutical corridor scaling contract manufacturing for both local consumption and export markets.
- Pharmaceutical Firms:Therapeutic developers requiring stigmasterol isolates with prodrug precursor specifications and full pharmacopeial documentation.
- Cosmetic Companies:Formulators seeking brassicasterol-enriched fractions for emollient applications in Japan's functional beauty sector.
Contract security highest with: Food Manufacturers. Fastest procurement cycle compression: Dietary Supplement Providers.
Form:
Processing intensity and stability requirements differentiate powder standardization from emulsified delivery system complexity.
- Powder:Spray-dried sterol concentrates for tablet compression and dry blend fortification, dominating nutraceutical manufacturing workflows.
- Liquid:Oil-soluble sterol suspensions for beverage emulsion systems and softgel encapsulation.
- Granules:Agglomerated forms improving flow properties for high-speed food processing lines.
- Emulsified:Water-dispersible sterol systems enabling functional beverage fortification without phase separation.
Volume concentration: Powder. Fastest technology transition: Emulsified.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia anchor raw material flows through integrated oilseed crushing networks that feed deodorizer distillate streams to regional sterol processors.
China
Shanghai-Jiangsu corridor contract manufacturers scale pharmaceutical-grade sterol outputs for export markets. NMPA novel food ingredient approvals extend review timelines for imported concentrates, favoring domestic producers with established GB standard compliance. Supercritical CO2 extraction units consolidate market share toward processors with capital deployment above 50 million RMB in Jiangsu province.
India
Rice bran oil refining capacity in Maharashtra and Gujarat underpins backward-integrated sterol feedstock capture. FSSAI tightened labeling norms for cholesterol-lowering claims compel reformulation investments across functional food portfolios. Matrix Fine Sciences anchors domestic supply through captive rice bran oil processing in western India.
Japan
Tokyo-Osaka corridor dairy alternative manufacturers compress supplier qualification cycles from 24 months to 12 months. MHLW pharmacopeial certification timelines extend commercialization horizons for novel sterol therapeutic applications. Functional beauty sector demand in Osaka drives brassicasterol-enriched fraction procurement for emollient formulations.
South Korea
Seoul Capital Area nutraceutical brands source sterol concentrates for lipid metabolism modulation supplements. MFDS substance registration requirements constrain imported intermediate sourcing flexibility. Daegu-Gyeongbuk pharmaceutical cluster explores stigmasterol isolates for prodrug precursor applications.
Indonesia
Sumatra and Kalimantan palm oil refining complexes control deodorizer distillate supply access for regional sterol extraction. Cargill leverages integrated crushing networks across the archipelago to secure raw material streams. Oleochemical processors realign capacity toward higher-purity outputs serving pharmaceutical-grade specifications.
Asia-Pacific Phytosterols Market Competitive Environment
Global majors compete with regional champions across feedstock access and purification technology tiers. The vendor base stratifies between integrated oilseed processors with captive distillate supply and specialized sterol refiners dependent on spot-market procurement. Three archetypes dominate: multinational agribusiness conglomerates with crushing-to-refining integration, mid-scale Asian processors with backward-linked vegetable oil refining, and European technology licensors with solvent-free purification IP. Competitive moves center on backward integration into rice bran and palm feedstocks, plus capacity expansion of supercritical extraction systems.
Within the integrated agribusiness tier, Cargill Incorporated exemplifies the crushing-network archetype through its Indonesian and Malaysian oilseed operations. BASF SE represents the technology-licensor position with proprietary solvent-free purification systems. Matrix Fine Sciences Pvt Ltd anchors the regional backward-integration archetype through its Indian rice bran oil refining operations. These three occupy positions spanning raw material control, process innovation, and domestic market anchoring respectively.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| BASF SE |
| Ashland Global Specialty Chemicals Inc |
| Matrix Fine Sciences Pvt Ltd |
| DuPont Nutrition & Health |
| Gustav Parmentier GmbH |
| Kraft Heinz Company |
| Kemin Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap processors across India's Maharashtra and Gujarat states anchor regional supply discipline through captive rice bran oil refining, translating feedstock control into pricing power that resists spot-market volatility. Their ownership structure insulates long-term contract negotiations with multinational food manufacturers from quarterly earnings pressure.
Pricing Analysis
Warranty-backed pharmacopeial certification bundles command 15-25% premiums over unbundled sterol concentrates, with Japan's MHLW-compliant documentation included in long-term supply agreements. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and commodity food-grade levels separates beta-sitosterol from stigmasterol isolates. Cost compression in commodity food-grade tiers intensifies because Indonesian palm oil processors expand deodorizer distillate capacity. Dietary supplement providers in China's Jiangsu province exhibit highest price sensitivity, while Tokyo-Osaka pharmaceutical developers absorb certification premiums without volume reduction.
Supply Chain Analysis
Pharmacopeial qualification gates operated by Japan's MHLW and China's NMPA constrain supplier pools to processors with documented GB standard compliance and solvent-free purification systems. Raw material flows concentrate in Indonesia, Malaysia, and India, with deodorizer distillate supplies drawing from palm oil refining in Sumatra and Kalimantan plus rice bran processing in western India. Feedstock dependency on vegetable oil refining cycles creates single-source vulnerability when El Niño disrupts Southeast Asian palm harvests. Distribution runs through integrated oilseed processors with captive crushing networks rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deodorizer distillate refining capacity in Indonesia and Malaysia operates at effective saturation, propping pricing power for backward-integrated processors with captive feedstock access.
For Market Incumbents: Hedge regulatory compression in India and China by accelerating pharmacopeial certification investments ahead of FSSAI and NMPA timeline extensions. Deepen upstream control over rice bran oil refining in Maharashtra and Gujarat to offset stigmasterol yield limitations from soy-dependent competitors. For New Entrants and Emerging Players: Launch via contract manufacturing partnerships with Shanghai-Jiangsu nutraceutical brands seeking pharmaceutical-grade sterol outputs for export markets. Target India's underdeveloped rice bran refining capacity as the most penetrable white space, exploiting FSSAI labeling enforcement that filters non-compliant imports. For Investors and Strategic Acquirers: NMPA approval of novel food ingredient applications with accelerated GB standard pathways is the leading indicator that domestic Chinese processors will consolidate market share against import-dependent competitors. Five-to-ten-year viability favors processors with supercritical CO2 extraction deployment capability above 50 million RMB and established regulatory affairs capacity across FSSAI, NMPA, and MHLW jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Bran Refining | Captures high-yield sterol feedstock in India's western processing corridor. |
| Supercritical CO2 Extraction Scale-Up | Consolidates Jiangsu province market share toward capital-deployed processors. |
| Pharmacopeial Certification Investment | Accelerates NMPA and MHLW approval pathways for therapeutic applications. |
| Long-Term Supply Agreement Expansion | Locks in Tokyo-Osaka dairy alternative manufacturers compressing qualification cycles. |
| Joint Venture with Indonesian Oilseed Processors | Secures deodorizer distillate access amid Sumatra refining capacity constraints. |
Study Parameters
Multi-period observation of NMPA approval timelines, FSSAI enforcement patterns, and supercritical extraction capacity additions anchored the trend analysis, supplemented by interviews with plant managers at Indonesian oleochemical facilities, regulatory affairs leads at Indian nutraceutical exporters, procurement directors at Japanese functional food manufacturers, and technical R&D directors at solvent-free purification technology providers. Secondary validation drew from China GB standard filings, India FSSAI notification registers, Japan MHLW pharmacopeial updates, and ASEAN customs trade data. Bottom-up sterol demand modeling triangulated against top-down vegetable oil refining capacity estimates.
Input-output matrices structured the projection framework, mapping beta-sitosterol, stigmasterol, campesterol, and brassicasterol volumes across food and beverages, nutraceuticals, personal care, and pharmaceutical applications by powder, liquid, granule, and emulsified form factors. CAGRs derived from regression analysis of historical capacity utilization and regulatory approval velocity. Industry-specific forecast inputs incorporated rice bran oil refining yield curves and supercritical CO2 unit deployment rates across China's Jiangsu province.
Regulatory timeline delays, feedstock harvest volatility, and certification standard harmonization failures are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in NMPA novel food ingredient review timelines or Indonesian palm oil refining capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Grape Skin–Carob Synergy Antioxidant Systems Market
Functional Food and Beverage
Vitamin Functional Water Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Functional Flavor Market
Functional Food and Beverage
Soluble Beta Glucan Market
Functional Food and Beverage
Prebiotic Fiber Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Instant Protein Beverages Market
Functional Food and Beverage
Liquid Breakfast Products Market
Functional Food and Beverage
Adaptogen Drink Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Middle East and Africa Protein Bar Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Fermented Protein Market