
 Hydrogen Water Market | 2026-2036
Hydrogen Water Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Water Market Outlook
Food-grade molecular hydrogen handling expertise is rotating toward beverage formulation teams as producers scale beyond niche wellness circles. HyVIDA Brands Inc. leverages its North American channel relationships to sustain shelf placement in premium retail. Guangzhou Olansi Healthcare Co. Ltd. anchors Asian manufacturing capacity with in-house generator production. DrinkHRW differentiates through clinical-adjacent positioning that appeals to performance-oriented consumers.
Hydrogen water is water infused with dissolved molecular hydrogen gas, typically at concentrations between 0.5 and 1.6 parts per million, produced through electrolysis or direct gas dissolution methods. The beverage functions as an antioxidant delivery vehicle targeting oxidative stress reduction in consumer wellness applications. Bottled hydrogen water leads volume due to convenience and established cold-chain logistics, though hydrogen tablets represent the fastest-expanding segment as portable formats capture travel and gym use cases. Wellness centers constitute a concentrated margin pool where bulk dispenser installations create recurring revenue streams.
The FDA classifies hydrogen water as a conventional food in the United States, limiting disease-treatment claims while permitting general wellness positioning. Japan's PMDA and Consumer Affairs Agency enforce stricter functional claim substantiation under Foods with Function Claims frameworks. China's SAMR monitors hydrogen concentration labeling accuracy under evolving beverage standards. Stakeholders must track regulatory divergence between permissive and restrictive jurisdictions when designing cross-border product portfolios and marketing architectures.
Market Dynamics
Japan's PMDA is tightening functional claim substantiation for hydrogen water, forcing producers to restructure clinical validation pipelines and reformulate positioning strategies across East Asian export corridors.
Growth Catalysts
- Fitness recovery protocols:Athletic training facilities in South Korea and Australia are integrating hydrogen water dispensers into post-workout recovery stations, creating institutional procurement anchors.
- Foods with Function Claims frameworks:Japan's regulatory clarity permits specific antioxidant positioning, enabling premium pricing that other jurisdictions cannot legally replicate.
- Electrolysis miniaturization:On-demand hydrogen generation technology is reducing dependency on bottled distribution, unlocking portable use cases for business travelers.
Market Restraints
- Concentration volatility:Dissolved hydrogen dissipates within hours of opening, creating spoilage risk that cold-chain logistics cannot fully mitigate.
- East Asian supply concentration:Guangzhou and Osaka manufacturing clusters control generator component supply, exposing non-Asian brands to tariff and shipping friction.
- Functional beverage substitution:Electrolyte drinks and adaptogenic teas compete for the same wellness-oriented shelf space and consumer attention.
Strategic Opportunities
- German pharmacy channel:Wellness-focused Apotheken chains remain underpenetrated by hydrogen water, offering first-mover positioning for clinical-adjacent brands.
- Corporate wellness mandates:Large employers in Singapore and Dubai are adding functional beverages to employee benefit programs, creating B2B volume anchors.
- ISO hydrogen concentration standards:Emerging international testing protocols will favor producers with in-house analytical capabilities, compressing marginal competitors.
Industry Challenges
- Food-grade gas handling certification:Beverage formulation teams lack molecular hydrogen safety training, slowing product development cycles and raising compliance costs.
- Cross-border claim harmonization:Divergent FDA, PMDA, and SAMR positioning rules force producers to maintain multiple label variants and marketing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Water Market |
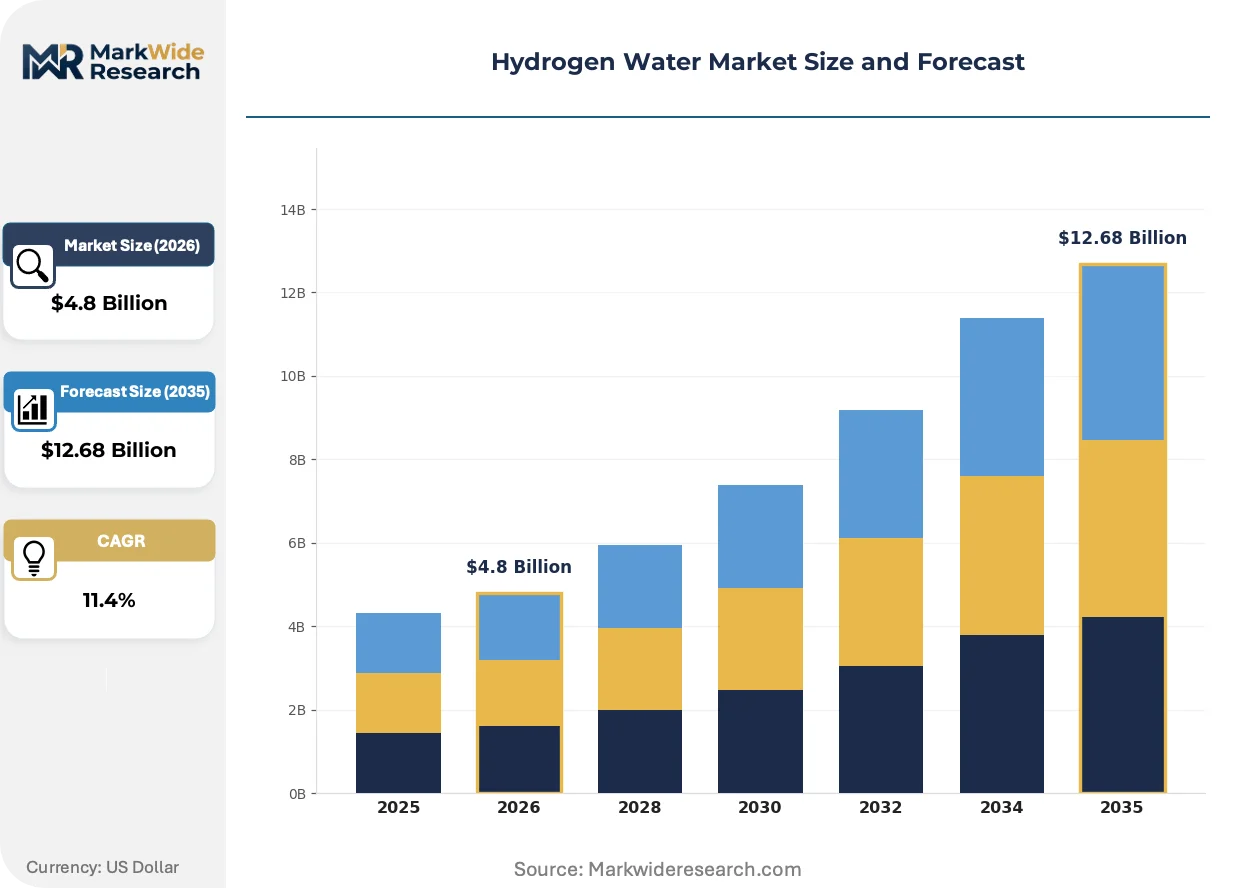
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Tablets, Hydrogen Water Dispensers, Hydrogen Infusers, Bottled Hydrogen Water End User: Health Conscious Consumers, Fitness Enthusiasts, Athletes, Wellness Centers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Shops Packaging Type: Bottles, Pouches, Cans, Tetra Packs |
| Companies Covered | Perricone Hydrogen Water Company, HyVIDA Brands Inc., H2 Beverages Inc., Piurify LLC, DrinkHRW, HyEdge Inc., Guangzhou Olansi Healthcare Co. Ltd., Young Living Essential Oils LC., Naturally Plus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Water Market Strategic Shifts
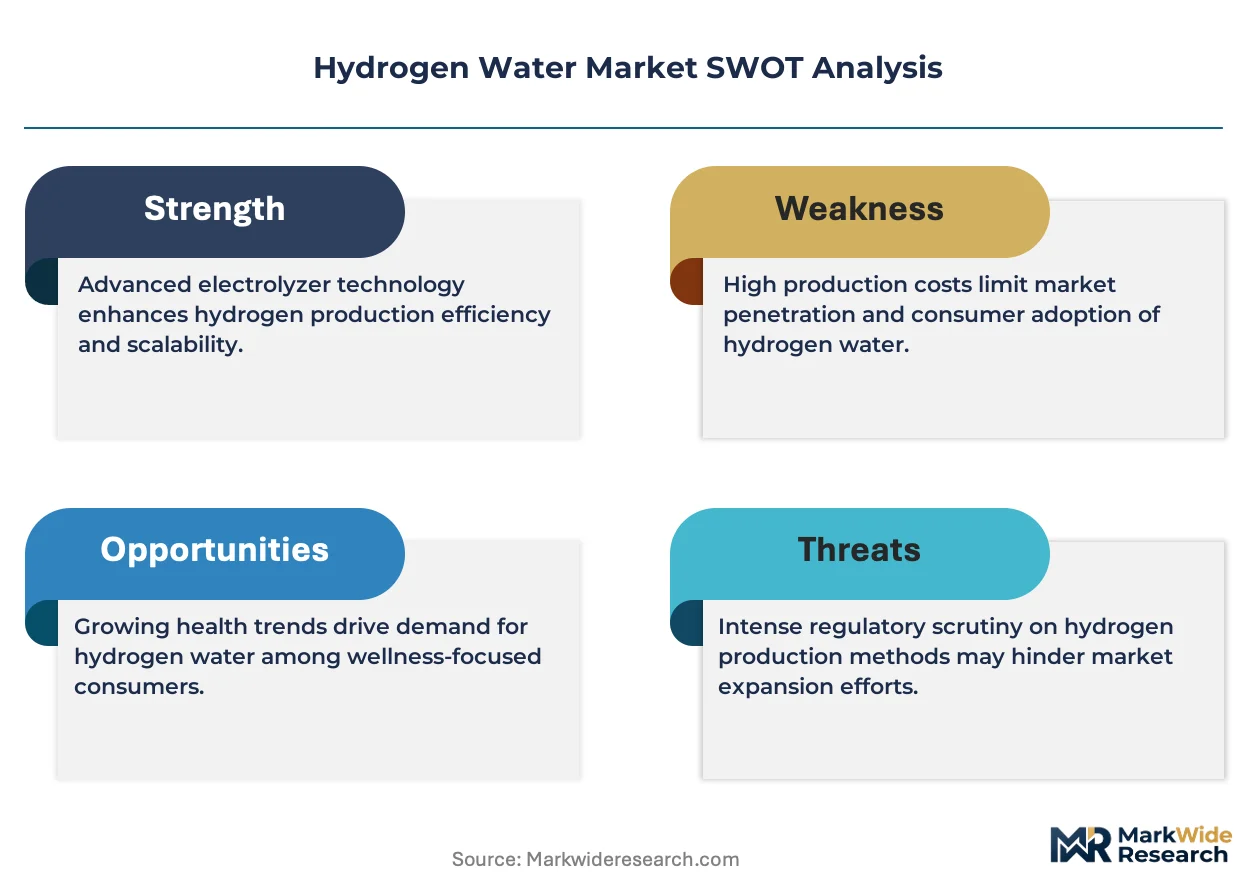
Electrolysis-based on-site generation is disrupting bottled distribution economics, while regulatory divergence between Japan's permissive functional claims and the FDA's restrictive stance is forcing portfolio segmentation.
Solid-state electrolysis technology is fragmenting production scale assumptions. Portable generators now achieve 1.2 parts per million concentration in under three minutes, matching bottled product specifications. Boutique fitness studios in Melbourne and Austin are adopting countertop units to eliminate inventory carrying costs. This hardware shift is compressing margins for traditional bottlers while opening recurring revenue streams through cartridge subscription models.
The EU's proposed updates to nutrition and health claims regulation are tightening evidentiary requirements for antioxidant positioning. Producers targeting European distribution must now commission human intervention studies that satisfy EFSA scrutiny. German and Dutch importers are responding by sourcing exclusively from Japanese suppliers with existing PMDA dossiers, creating a two-tier supply structure.
Certification-driven purchasing is reshaping institutional procurement. Corporate wellness directors in Singapore and Sydney now require third-party hydrogen concentration verification before contract approval. This specification shift favors producers with ISO-accredited testing partnerships and displaces brands relying solely on in-house quality assertions. The behavior is most pronounced in financial services and technology sector employers with established wellness infrastructure budgets.
Hydrogen Water Market Segmentation
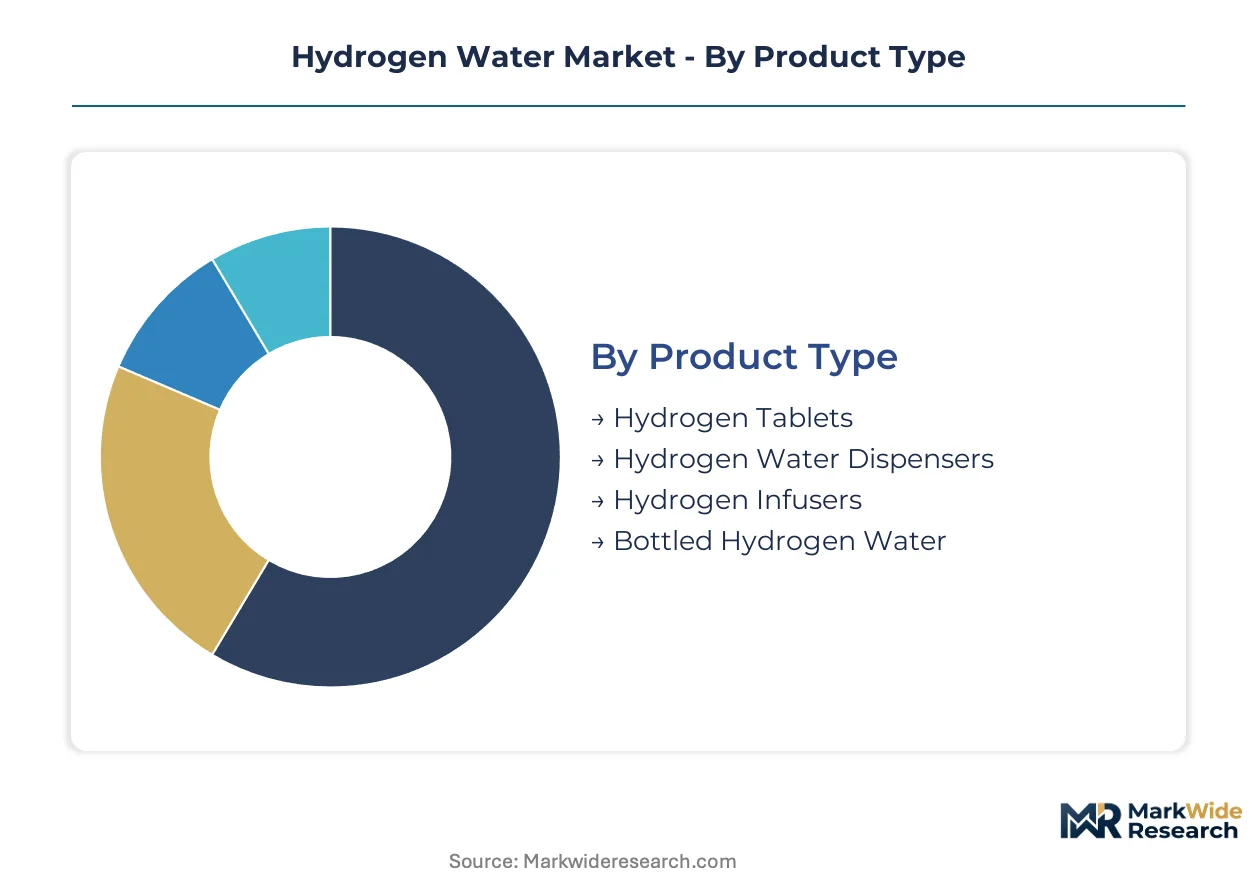
Channel economics in hydrogen water diverge sharply by product format, with portable solutions commanding premium multiples in direct-to-consumer channels while institutional dispensers anchor recurring revenue through wellness infrastructure contracts. Segmentation strategy must align hydrogen concentration stability requirements with the cold-chain capabilities of each route-to-market.
Product Type:
Dispensers and bulk systems flow through B2B wellness contracts, while portable formats dominate e-commerce velocity with minimal logistics overhead.
- Bottled Hydrogen Water:Pre-infused at 0.5 to 1.6 parts per million through electrolysis or direct gas dissolution, packaged in aluminum or glass with oxygen-barrier seals. Convenience retail in Japan and South Korea drives volume, though spoilage risk from hydrogen dissipation constrains inventory depth. Cold-chain dependency compresses margin in export markets.
- Hydrogen Tablets:Magnesium-based effervescent formulations generating molecular hydrogen on contact with water. Gym bag and travel use cases in Australia and Singapore are climbing the fastest as consumers reject single-use plastic and ambient storage eliminates spoilage risk.
- Hydrogen Water Dispensers:Countertop electrolysis units producing on-demand hydrogen concentration for wellness centers and boutique fitness studios. Melbourne and Austin installations are displacing bottled procurement through cartridge subscription economics.
- Hydrogen Infusers:Portable bottle-attachment devices enabling consumer-controlled hydrogen generation. Early-adopter penetration concentrates in direct-to-consumer channels with minimal retail footprint.
Bottled hydrogen water dominates installed base. Hydrogen tablets are where expansion concentrates.
End User:
Customer lifetime value stratifies sharply, with institutional wellness contracts delivering 3-4 year retention against transactional consumer repurchase cycles.
- Fitness Enthusiasts:Individual consumers integrating hydrogen water into post-workout recovery protocols, typically purchasing through specialty retail or subscription direct-to-consumer. South Korean athletic training facilities are installing dispensers to capture this demand at point of use.
- Wellness Centers:Spas, clinics, and corporate wellness programs deploying bulk dispenser infrastructure with recurring cartridge or maintenance contracts. Singapore employer mandates are steepening expansion trajectory for this segment.
- Health Conscious Consumers:General wellness seekers purchasing sporadically through supermarkets and online retail, exhibiting high price sensitivity and low format loyalty.
- Athletes:Competitive and professional performers with protocol-driven consumption requirements. Clinical-adjacent positioning and third-party concentration verification command disproportionate share of this narrow segment.
Wellness centers dominate installed base. Fitness enthusiasts are where expansion concentrates.
Distribution Channel:
Margin structure inverts across channels, with specialty retail capturing 40-50% product markup against 15-20% in mass supermarket placement.
- Specialty Stores:Dedicated wellness and supplement retailers with educated staff capable of explaining hydrogen concentration specifications and antioxidant positioning. German Apotheken chains represent underpenetrated expansion opportunity for clinical-adjacent brands.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription mechanics and educational content delivery. Portable formats and infusers achieve disproportionate velocity here due to shipping-weight economics.
- Supermarkets:Mass retail placement requiring volume commitments and promotional spend, viable only for bottled formats with established brand recognition and cold-chain partnerships.
- Health Shops:Hybrid positioning between specialty and mass, common in East Asian convenience retail where functional beverage education is culturally embedded.
Specialty stores dominate installed base. Online retail is where expansion concentrates.
Packaging Type:
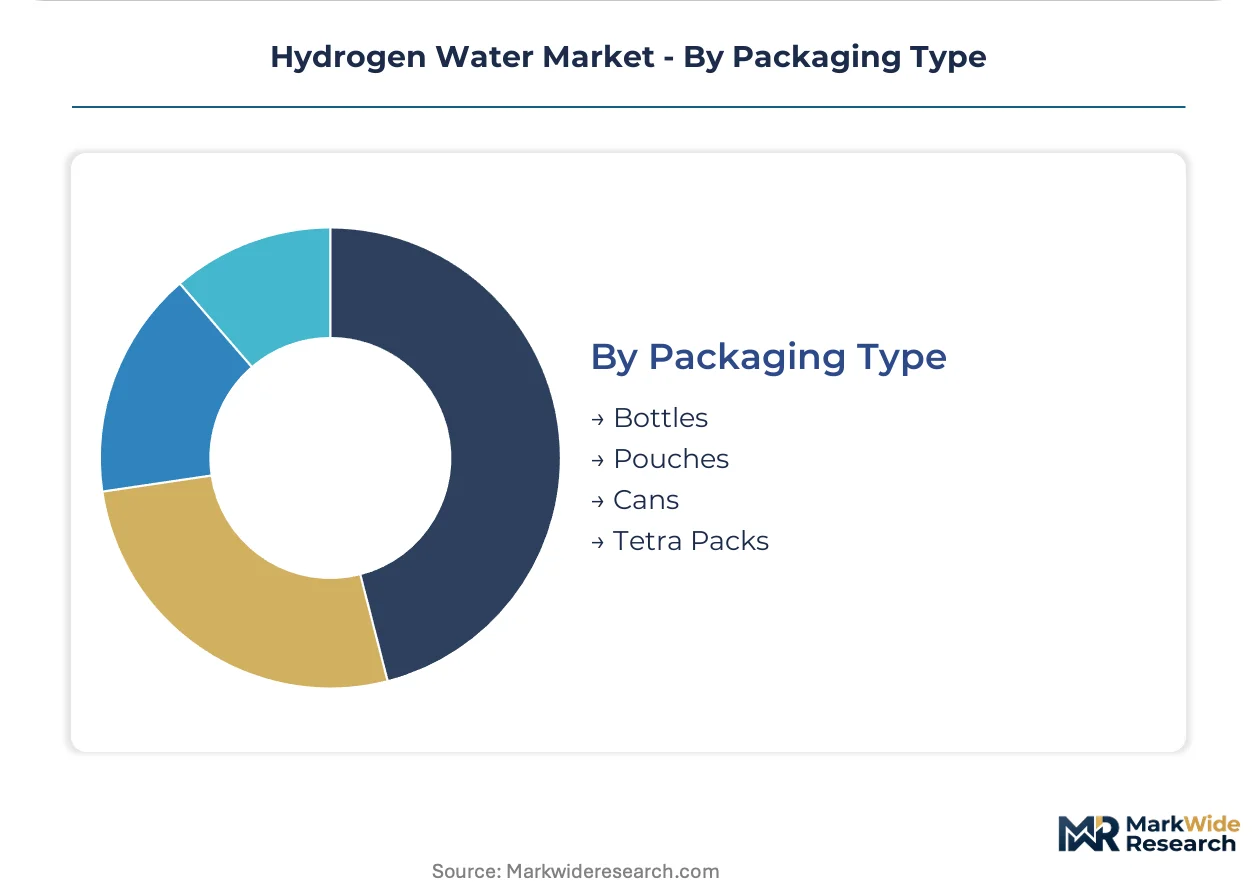
Material science investments track hydrogen permeability coefficients, with aluminum and barrier-coated glass outperforming conventional plastics in concentration retention.
- Bottles:Aluminum and glass containers with oxygen-barrier closures dominating premium positioning. Established cold-chain infrastructure supports this format's channel ubiquity.
- Cans:Aluminum beverage cans with internal epoxy linings preventing hydrogen permeation. Emerging format for single-serve convenience in Japanese vending and Australian convenience retail.
- Pouches:Flexible multilayer films with metalized barrier layers, gaining traction in trial-size and sampler applications where shipping efficiency outweighs premium perception.
- Tetra Packs:Aseptic carton formats with limited current adoption due to hydrogen permeation challenges through paperboard substrates and seal interfaces.
Bottles dominate installed base. Cans are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's PMDA functional claims framework anchors the dominant geography, creating regulatory spillover effects that shape product positioning across East Asian export corridors and influence formulation strategies in secondary markets.
Japan
Tokyo and Osaka wellness centers drive institutional dispenser procurement, with corporate wellness mandates steepening demand trajectories. PMDA Foods with Function Claims frameworks permit specific antioxidant positioning unavailable in other jurisdictions. The Kansai manufacturing cluster around Osaka controls generator component supply, exposing non-Asian brands to shipping friction.
South Korea
Seoul athletic training facilities integrate hydrogen water dispensers into post-workout recovery stations, creating institutional procurement anchors. MFDS monitors hydrogen concentration labeling accuracy under evolving beverage standards. Busan-Ulsan manufacturing capacity supports regional export demand with established cold-chain infrastructure.
United States
Fitness enthusiasts in California and Texas represent rapidly expanding buyer segments as hydrogen water gains traction in athletic recovery protocols. FDA classification as conventional food limits disease-treatment claims while permitting general wellness positioning. Pacific Northwest specialty retailers drive premium channel velocity with educated staff capable of explaining concentration specifications.
Germany
Wellness-focused Apotheken chains remain underpenetrated, offering first-mover positioning for clinical-adjacent brands targeting pharmacy channel expansion. EFSA scrutiny of antioxidant claims under proposed nutrition regulation updates tightens evidentiary requirements. Bavaria and North Rhine-Westphalia concentrate importer activity sourcing from Japanese suppliers with existing PMDA dossiers.
Australia
Boutique fitness studios in Melbourne adopt countertop electrolysis units to eliminate inventory carrying costs, displacing bottled procurement. TGA oversight of therapeutic claims shapes marketing architecture for performance-oriented positioning. Sydney corporate wellness directors require third-party hydrogen concentration verification before contract approval, favoring ISO-accredited producers.
Hydrogen Water Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with electrolysis miniaturization specialists commanding premium positioning against scale-driven bottlers. The vendor base organizes around three strategic archetypes: clinical-adjacent brands with third-party verification partnerships, Asian manufacturers with captive generator production, and North American channel specialists sustaining shelf placement in premium retail. Dominant competitive moves include geographic expansion into underpenetrated pharmacy channels and portfolio diversification toward portable tablet formats.
Among North American positioning specialists, HyVIDA Brands Inc. and DrinkHRW exemplify divergent archetype strategies, with the former anchoring premium retail relationships and the latter occupying clinical-adjacent territory. Guangzhou Olansi Healthcare Co. Ltd. represents the Asian manufacturing tier with integrated generator production capabilities. These three entities illustrate how regulatory divergence between PMDA-permissive and FDA-restrictive jurisdictions forces portfolio segmentation across player types.
| Leading Market Players |
|---|
| Perricone Hydrogen Water Company |
| HyVIDA Brands Inc. |
| H2 Beverages Inc. |
| Piurify LLC |
| DrinkHRW |
| HyEdge Inc. |
| Guangzhou Olansi Healthcare Co. Ltd. |
| Young Living Essential Oils LC. |
| Naturally Plus |
| Others |
Value Chain & Pricing Dynamics
Forty-eight to seventy-two hour hydrogen retention windows in finished product inventory compress pricing power for bottled formats while amplifying margin capture for on-site generation hardware. This spoilage-driven inventory velocity ties directly to Osaka and Guangzhou manufacturing clusters, where generator component concentration enables tiered pricing discrimination across export corridors.
Pricing Analysis
Japanese retail commands three-to-fourfold premiums over Australian supermarket placement for equivalent concentration products. Three-tier pricing structure across premium clinical-grade, standard wellness, and economy hydration levels separates PMDA-substantiated antioxidant claims from general wellness positioning. Cost compression in the bottled segment is intensifying as electrolysis miniaturization displaces traditional distribution economics. Corporate wellness directors exhibit lowest price sensitivity due to mandate-driven procurement, while sporadic health-conscious consumers in mass retail show highest elasticity.
Supply Chain Analysis
Generator component inventory cycles of ninety to one hundred twenty days from Kansai and Pearl River Delta manufacturing clusters expose non-Asian brands to shipping friction and tariff volatility. Electrolysis cell membranes and food-grade hydrogen handling equipment draw from Japan, South Korea, and China. Single-source vulnerability concentrates in proton exchange membrane supply from Osaka-area specialty chemical producers. Distribution runs through wellness center B2B contracts, specialty retail partnerships, and direct-to-consumer subscription platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolysis miniaturization is disrupting bottled distribution economics, creating asymmetric opportunity windows for hardware-first entrants and defensive urgency for legacy bottlers.
For Market Incumbents: Fortify generator component supply through backward integration into electrolysis cell production or exclusive Osaka-area supplier partnerships. Lock in ISO-accredited testing capabilities before emerging concentration verification mandates displace unverified brands from Singapore and Sydney corporate wellness procurement. Hydrogen tablet substitution and portable infuser encroachment threaten traditional bottled volume anchors. For New Entrants and Emerging Players: PMDA Foods with Function Claims fast-track certification unlocks premium pricing unavailable to FDA-restricted competitors. German Apotheken pharmacy chains remain substantially underpenetrated by clinical-adjacent positioning. Direct-to-consumer subscription mechanics with educational content delivery capture fitness enthusiast segments without mass retail volume commitments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified beverage conglomerates with dormant hydrogen water SKUs lacking dedicated management attention. Five-to-ten year viability hinges on regulatory convergence or persistent divergence between PMDA-permissive and FDA-restrictive jurisdictions. Watch for ISO hydrogen concentration standard finalization as inflection signal favoring producers with captive analytical capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolysis Miniaturization R&D | Portable generators achieving PMDA-equivalent concentrations in under three minutes displace bottled procurement in Melbourne and Austin fitness studios. |
| PMDA Foods with Function Claims Dossier Investment | Antioxidant positioning substantiation enables premium pricing tiers inaccessible to FDA-classified conventional food competitors. |
| ISO-Accredited Testing Partnership | Third-party hydrogen concentration verification satisfies Sydney and Singapore corporate wellness director procurement specifications. |
| German Apotheken Channel Entry | Pharmacy chain penetration captures clinical-adjacent positioning with educated staff capable of explaining concentration specifications. |
| Hydrogen Tablet Format Expansion | Magnesium-based effervescent formulations eliminate cold-chain dependency and capture gym bag and travel use cases in Australia and Singapore. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wellness center procurement directors, beverage formulation chemists, specialty retail category managers, and electrolysis equipment engineers. Secondary validation drew from PMDA Foods with Function Claims filings, MFDS beverage standard updates, FDA conventional food classification guidance, and customs trade data for generator component flows. Bottom-up volume modeling across product formats triangulated against top-down macroeconomic absorption capacity estimates.
Across the projection horizon, the analytical framework modeled hydrogen water segmentation by product type, end-user archetype, distribution channel, and regional regulatory cluster. CAGRs were derived from installed base growth rates, replacement cycle assumptions, and penetration elasticity coefficients. Forecast inputs incorporated electrolysis technology cost curves, cold-chain logistics expansion trajectories, and corporate wellness mandate adoption patterns.
Decision-makers should treat outputs as directional under stable PMDA-FDA regulatory divergence and continued electrolysis miniaturization; material deviation in claim substantiation requirements or hydrogen retention technology would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Low Fat Smoothies Market
Functional Food and Beverage
Galacto Oligosaccharides (GOS) Market
Functional Food and Beverage
Asia-Pacific Functional Beverages Market
Functional Food and Beverage
Mediterranean Lemon Bioflavonoid Shot Bases Market
Functional Food and Beverage
Low Fat and Low Cholesterol Diet Foods Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Saudi Arabia Protein Bar Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
Global Functional Proteins Market
Functional Food and Beverage
Global Functional Foods Market
Functional Food and Beverage
Marine Functional Ingredients Market
Functional Food and Beverage
Xanthohumol Market