
 Therapeutic Food Delivery for Clinical Nutrition Market | 2026-2036
Therapeutic Food Delivery for Clinical Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Food Delivery for Clinical Nutrition Market Insights
Modular packaging of disease-specific blends into single-dose, ready-to-hang configurations is realigning how hospitals and home healthcare providers evaluate total cost of therapy. Abbott leverages its enteral device portfolio to sustain channel control across acute care settings. Nestlé Health Science anchors its position through geographic dominance in European long-term care networks. Danone Nutricia differentiates via R&D intensity in immune-enhancing nutrient formulations.
Therapeutic food delivery for clinical nutrition encompasses medically prescribed nutritional formulations administered through oral, enteral, or parenteral routes to treat or prevent malnutrition in patients with specific disease states, typically requiring precise macronutrient ratios within sterile or aseptically prepared packaging. These formulations serve the primary commercial purpose of reducing infection rates, shortening hospital length of stay, and lowering readmission penalties for provider systems. Disease-specific blends command the deepest margin pools due to formulation complexity and limited substitutability, while oral nutritional supplements represent the most mature segment with established reimbursement pathways. Home healthcare providers constitute the fastest-growing end-user channel as payors shift reimbursement toward lower-acuity settings.
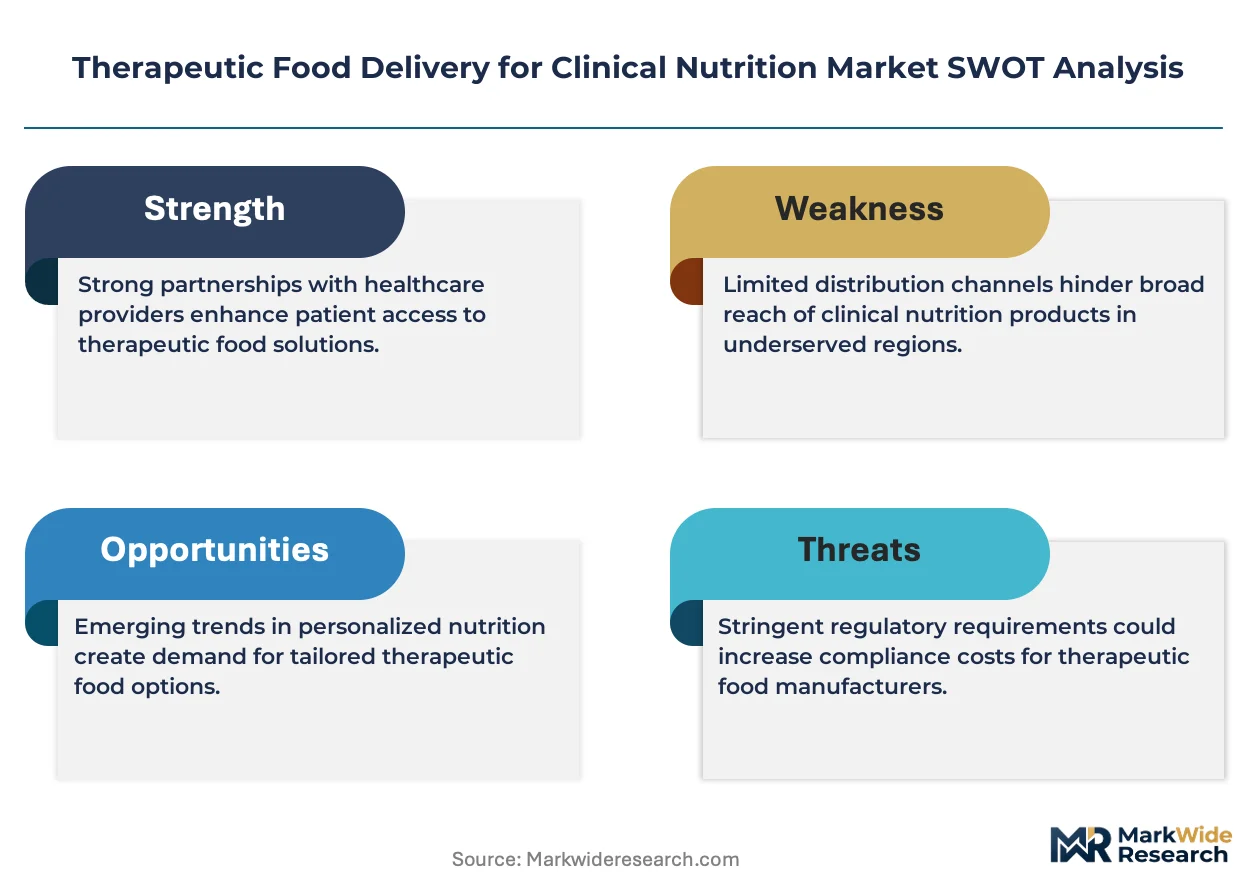
The FDA governs enteral feeding tube materials and parenteral nutrition compounding standards under device and drug regulations respectively, while the EMA's Medical Device Regulation tightens clinical evidence requirements for enteral delivery systems in Europe. These frameworks shape demand by elevating compliance costs for manufacturers and creating preference for suppliers with pre-validated quality systems. Stakeholders must monitor how CMS reimbursement recalibration for home-based clinical nutrition affects channel economics and portfolio prioritization decisions.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around suppliers with pre-validated enteral device safety systems, compressing the competitive field to manufacturers capable of meeting FDA's updated quality benchmarks without retrofitting legacy production lines.
Growth Catalysts
- CMS Reimbursement Recalibration:The US Center for Medicare & Medicaid Services is expanding coverage for home-based clinical nutrition, redirecting patient volume from acute care to lower-acuity settings and creating new demand for ready-to-hang modular formulations.
- Integrated Health Networks:Large US hospital systems are standardizing enteral feeding protocols across multi-site footprints, forcing formulary consolidation that favors suppliers with comprehensive device-nutrition portfolios.
- Enteral Device Safety Guidance:The FDA's tightened material specifications for feeding tubes is eliminating marginal manufacturers and concentrating procurement authority with established quality-system holders.
Market Restraints
- Specialty Ingredient Concentration:Sourcing of pharmaceutical-grade amino acids and lipid emulsions depends on a limited supplier base concentrated in Western Europe, exposing formulators to input volatility.
- EMA MDR Compliance Burden:Europe's Medical Device Regulation imposes clinical evidence requirements for enteral delivery systems that extend certification timelines and elevate fixed costs for market participation.
- Compounding Pharmacy Substitution:Hospital-based sterile compounding facilities in the United States retain capacity to formulate patient-specific parenteral nutrition, limiting addressable market for pre-manufactured alternatives in critical care.
Strategic Opportunities
- Home Healthcare Channel Expansion:Payor pressure to reduce readmission penalties is accelerating discharge-to-home protocols, creating demand for shelf-stable, patient-administered enteral systems with remote monitoring integration.
- Immune-Enhancing Formulation R&D:Nutrient blends incorporating specific immunonutrients address surgical and oncology patient populations with limited therapeutic alternatives and premium pricing tolerance.
- European Long-Term Care Networks:Aging demographics and institutional procurement centralization in Germany, France, and the Netherlands create scalable contract opportunities for disease-specific nutrition programs.
Industry Challenges
- Cross-Functional Talent Scarcity:Manufacturers require personnel combining clinical nutrition science with medical device regulatory expertise, a profile concentrated among competitors with decades of dual-category experience.
- Legacy System Integration:Hospital IT infrastructure for inventory management and bedside medication verification demands custom interface development for connected enteral pumps, extending sales cycles.
- Batch Release Testing Bottlenecks:Sterile parenteral nutrition requires endotoxin and sterility validation that can extend lead times when laboratory capacity constraints coincide with demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Food Delivery for Clinical Nutrition Market |
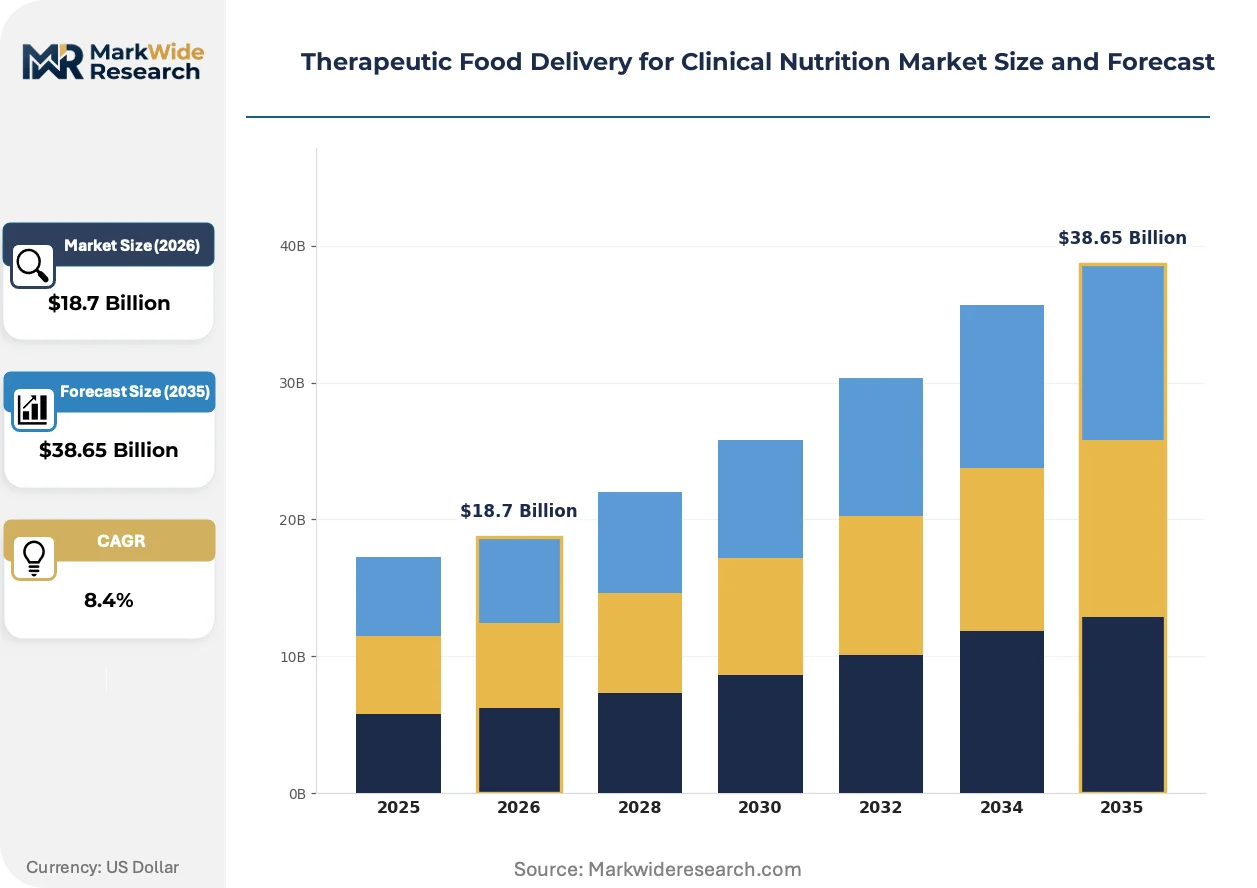
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Oral Nutritional Supplements, Enteral Feeding Tubes, Parenteral Nutrition, Nasogastric Feeding, Orogastric Feeding Product Type: High-Protein Formulas, Energy-Dense Formulations, Low-Lactose Products, Disease-Specific Blends, Immune-Enhancing Nutrients Application: Malnutrition Management, Oncology Nutrition, Critical Care Nutrition, Gastrointestinal Disorders, Metabolic Disease Therapy End User: Hospitals, Long-Term Care Facilities, Home Healthcare Providers, Rehabilitation Centers, Specialized Clinics |
| Companies Covered | Abbott, Nestlé Health Science, Danone Nutricia, Fresenius Kabi, Baxter International, B. Braun Melsungen, Otsuka Holdings, Reckitt, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Food Delivery for Clinical Nutrition Market Trends and Innovations
Automation of formulation preparation and packaging is compressing production economics while regulatory convergence between drug and device frameworks is reshaping competitive qualification requirements.
Closed-system transfer devices for parenteral nutrition compounding are automating aseptic handling previously performed in open laminar flow hoods. Large hospital systems and outsourced compounding facilities are adopting these systems to reduce contamination risk and personnel exposure. This technology is automating batch record documentation and environmental monitoring, enabling manufacturers to defend premium positioning through demonstrable sterility assurance.
REACH regulation amendments governing chemical substances in medical devices are tightening material disclosure requirements for enteral feeding sets sold into European markets. Manufacturers must now document full supply chain composition for polymers and adhesives, elevating compliance costs for non-integrated suppliers. German and French procurement authorities are incorporating these disclosure standards into tender evaluation criteria, favoring suppliers with established regulatory dossiers.
Health system value analysis committees have displaced individual clinician preference as the primary purchasing authority for clinical nutrition products. These committees evaluate total cost of therapy including device-nutrition compatibility, waste reduction, and nursing labor rather than unit price alone. This behavioral shift is most visible in United States integrated delivery networks, where standardization across dozens of facilities amplifies contract value and intensifies vendor consolidation.
Therapeutic Food Delivery for Clinical Nutrition Market Segmentation
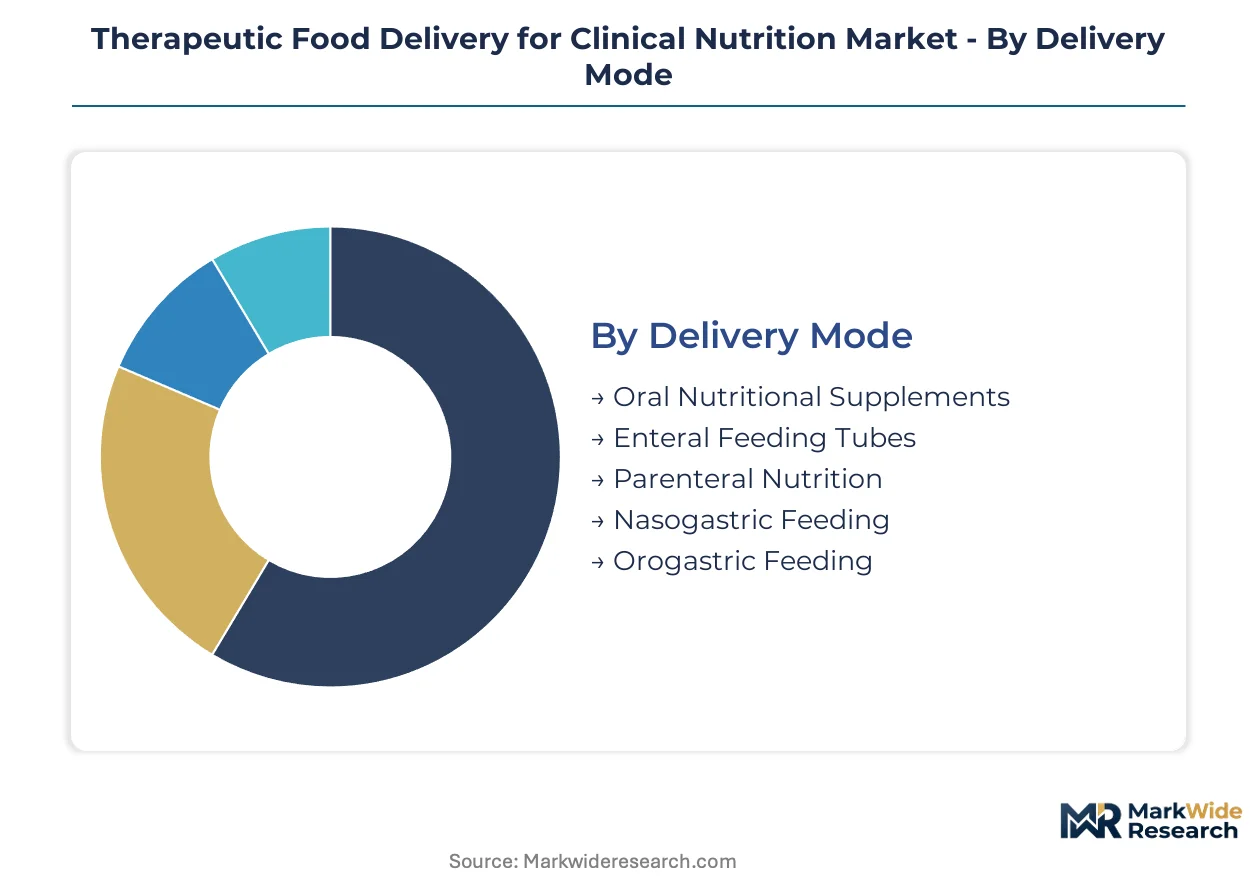
Segmentation in therapeutic food delivery reveals how capital deployment, regulatory burden, and reimbursement pathways concentrate profitability across distinct commercial configurations. Understanding these divides enables manufacturers to align R&D spend with segments offering sustainable margin protection.
Delivery Mode:
Capital intensity escalates sharply from oral formats through parenteral systems, with sterile manufacturing infrastructure and device-nutrition integration demanding the heaviest upfront commitment.
- Oral Nutritional Supplements:Standardized powder and liquid formats requiring minimal sterile infrastructure. Demand concentrates in European long-term care networks where institutional procurement centralization favors high-volume, low-SKU suppliers.
- Enteral Feeding Tubes:Polymer-based delivery systems with integrated pump compatibility. Hospital procurement departments in the United States prioritize suppliers with pre-validated FDA enteral device safety dossiers, compressing vendor pools.
- Parenteral Nutrition:Sterile lipid emulsion and amino acid solutions compounded under USP 797 standards. Critical care units in Germany and France drive specification.
- Nasogastric Feeding:Short-term enteral access devices with material compliance under REACH amendments. Acute discharge protocols expand volume.
- Orogastric Feeding:Surgical and emergency placement configurations. Pediatric and neonatal intensive care units specify diameter and material flexibility.
Enteral feeding tubes absorb the bulk of installed capacity; home healthcare channel expansion is expanding most quickly.
Product Type:
Margin structure stratifies across formulation complexity, with immune-modulating and disease-specific compositions commanding premium positioning through limited substitutability.
- Disease-Specific Blends:Renal, hepatic, and pulmonary formulations with restricted electrolyte and micronutrient profiles. Oncology and critical care departments in integrated US health networks drive formulary inclusion.
- Immune-Enhancing Nutrients:Arginine, omega-3 fatty acid, and nucleotide-enriched formulations targeting surgical recovery. German and Dutch hospital consortia reimburse under procedure-linked diagnosis-related group adjustments.
- High-Protein Formulas:Concentrated nitrogen delivery for wound healing and sarcopenia management. Post-acute rehabilitation facilities in France specify.
- Energy-Dense Formulations:Calorically compact solutions for fluid-restricted patients. Home healthcare providers in the United States favor ready-to-hang configurations.
- Low-Lactose Products:Hydrolyzed protein bases for intolerance management. Pediatric and geriatric segments sustain volume.
Disease-specific blends capture the deepest margin pools; immune-enhancing nutrients are climbing the fastest.
Application:
Reimbursement calibration across acute versus post-acute settings determines addressable market size and pricing elasticity for each therapeutic indication.
- Malnutrition Management:Screening and intervention protocols in hospitalized elderly populations. US CMS readmission penalty frameworks create institutional demand for standardized oral supplementation programs.
- Critical Care Nutrition:Early enteral feeding protocols in surgical and trauma intensive care. French and German academic medical centers specify immune-modulating formulations.
- Oncology Nutrition:Chemotherapy-induced mucositis and cachexia management. Outpatient infusion centers in the United States expand home enteral coverage.
- Gastrointestinal Disorders:Short bowel syndrome and inflammatory bowel disease maintenance. Specialized intestinal rehabilitation centers concentrate demand.
- Metabolic Disease Therapy:Inborn errors of metabolism requiring phenylalanine-restricted or other specialized amino acid profiles. Pediatric metabolic clinics specify.
Malnutrition management absorbs the bulk of installed capacity; oncology nutrition is gaining share fastest.
End User:
Procurement authority and technical specification complexity vary dramatically across institutional versus decentralized care environments.
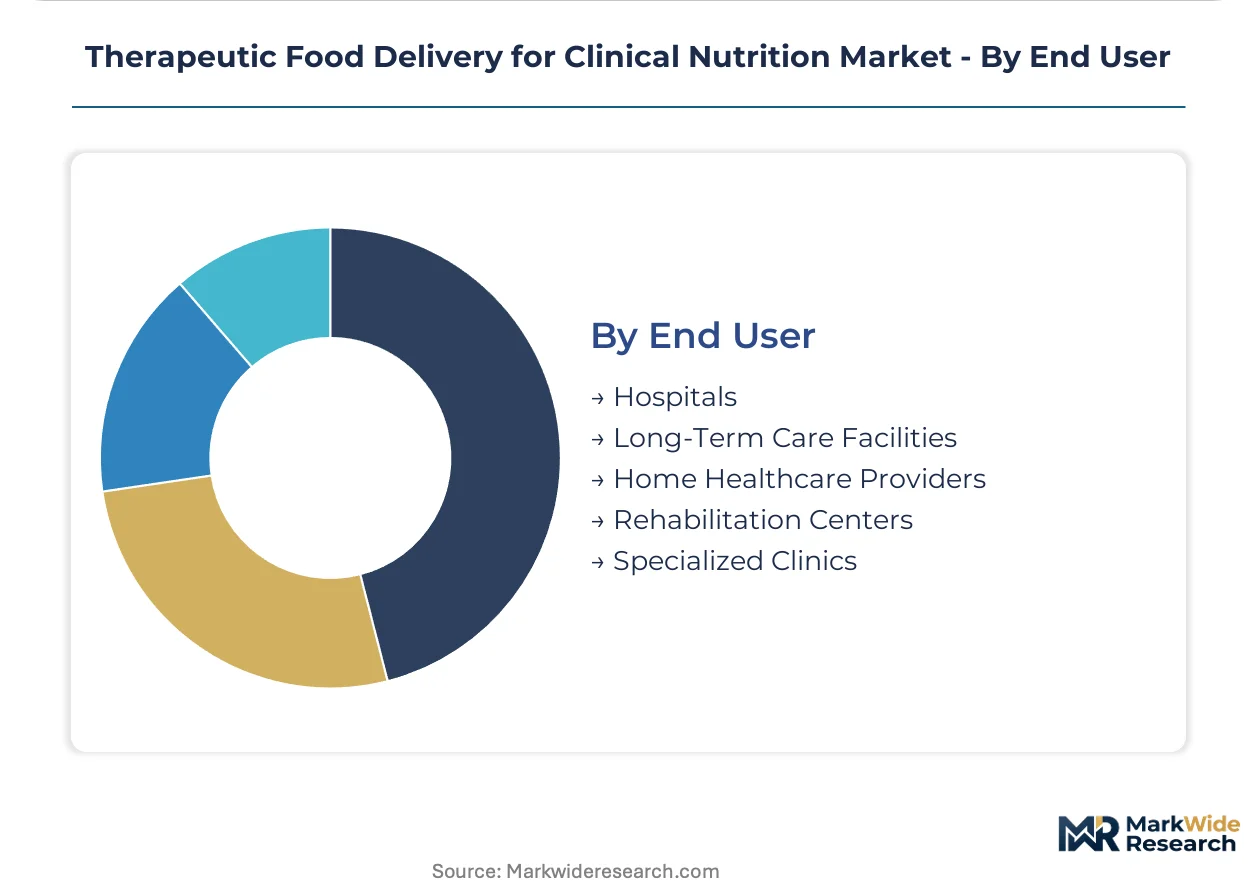
- Hospitals:Value analysis committees with device-nutrition portfolio requirements. US integrated delivery networks consolidate contracts across multi-site footprints.
- Home Healthcare Providers:Patient-administered enteral systems with remote monitoring integration. US CMS reimbursement recalibration redirects acute volume.
- Long-Term Care Facilities:Centralized purchasing through German and Dutch institutional procurement cooperatives. Standardized oral nutrition programs dominate.
- Rehabilitation Centers:Post-acute protein supplementation for functional recovery. French and Belgian neurological rehabilitation networks specify.
- Specialized Clinics:Metabolic, oncology, and intestinal failure centers with patient-specific compounding relationships. Limited addressable market for pre-manufactured alternatives.
Hospitals absorb the bulk of installed capacity; home healthcare providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for sterile parenteral nutrition concentrates in Western Europe while consumption growth accelerates in North American home healthcare channels. Germany hosts the densest cluster of pharmaceutical-grade lipid emulsion suppliers. The United States absorbs the largest share of disease-specific blend volume through integrated health network procurement.
United States
CMS reimbursement recalibration for home-based clinical nutrition redirects acute care volume toward patient-administered enteral systems. FDA enteral device safety guidance tightens material specifications for feeding tubes, eliminating marginal suppliers from hospital vendor pools. The Mayo Clinic and Cleveland Clinic anchor multi-site standardization protocols that compress formulary diversity.
Germany
German hospital consortia in North Rhine-Westphalia and Bavaria reimburse immune-enhancing formulations under procedure-linked diagnosis-related group adjustments. EMA Medical Device Regulation extends certification timelines for enteral delivery systems, elevating fixed costs for market entry. The Frankfurt-Rhine-Main cluster concentrates compounding pharmacy capacity for patient-specific parenteral nutrition.
France
French academic medical centers in Paris and Lyon specify immune-modulating formulations for surgical and oncology intensive care. ANSM material disclosure requirements under REACH amendments govern polymer composition in enteral feeding sets. The Île-de-France region centralizes procurement for national hospital networks, amplifying contract scale effects.
Netherlands
Dutch institutional procurement cooperatives standardize oral nutrition programs across long-term care facilities. EMA clinical evidence requirements for enteral devices favor suppliers with pre-validated quality dossiers. The Utrecht-Rotterdam corridor hosts concentrated distribution infrastructure for ready-to-hang modular formulations.
Japan
PMDA governs sterile manufacturing standards for parenteral nutrition emulsions used in critical care units. METI incentives for home healthcare technology adoption expand demand for patient-administered enteral systems with remote monitoring. The Kanto region around Tokyo anchors pharmaceutical formulation R&D and hospital network procurement authority.
Therapeutic Food Delivery for Clinical Nutrition Market Competitive Landscape
The competitive structure tilts toward diversified nutrition-device portfolio holders with pre-validated regulatory dossiers. Hospital procurement consolidation compresses vendor pools to manufacturers capable of meeting FDA and EMA quality benchmarks without retrofitting legacy infrastructure. Three archetypes dominate: integrated device-nutrition suppliers, pharmaceutical-grade compounders with sterile manufacturing assets, and regional oral nutrition specialists serving institutional long-term care networks. Competitive moves concentrate on formulary consolidation through multi-site health system contracts and backward integration into pharmaceutical-grade ingredient supply.
Within the integrated device-nutrition tier, Abbott exemplifies portfolio breadth across acute care settings, while Nestlé Health Science anchors European long-term care network penetration. Danone Nutricia occupies a position emphasizing R&D intensity in specialized formulations. These three represent the archetype of diversified clinical nutrition platforms capable of spanning hospital, home, and institutional channels under unified quality systems.
| Leading Market Players |
|---|
| Abbott |
| Nestlé Health Science |
| Danone Nutricia |
| Fresenius Kabi |
| Baxter International |
| B. Braun Melsungen |
| Otsuka Holdings |
| Reckitt |
| Grifols |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade amino acid spot prices cascade through sterile parenteral nutrition manufacturing into three-tier pricing stratification across premium immune-enhancing formulations, standard disease-specific blends, and economy oral supplements. Hospital procurement committees exploit volume concentration to compress margins on legacy enteral devices while immune-modulating nutrient premiums hold firm.
Pricing Analysis
Margin tightening in standard enteral feeding systems reflects hospital formulary consolidation around pre-validated FDA device-nutrition portfolios. Three-tier pricing structure across premium, standard, and economy levels separates immune-enhancing formulations with arginine and omega-3 enrichment from basic protein supplements. Cost-down pressure on economy oral nutrition accelerates because German and Dutch institutional procurement cooperatives centralize high-volume contracts. Post-acute rehabilitation facilities exhibit highest price sensitivity; critical care units demonstrate lowest sensitivity due to procedure-linked reimbursement.
Supply Chain Analysis
Pharmaceutical-grade lipid emulsion supply rests on German, French, and Swiss specialty chemical producers with USP-grade certification. Sterile amino acid sourcing draws from Western European fermentation facilities and select Indian API manufacturers. Single-source vulnerability concentrates in lipid emulsion precursors where three producers anchor global capacity. Distribution runs through hospital GPO contracts in the United States and national procurement frameworks in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automation of closed-system transfer devices for parenteral compounding is displacing open-hood sterile handling, forcing capital redeployment across formulation and device manufacturing tiers.
For Market Incumbents: Hedge against compounding pharmacy substitution by securing backward integration into pharmaceutical-grade amino acid supply and accelerating FDA enteral device safety dossier updates. Channel control through integrated pump-nutrition portfolios defends position against hospital vendor consolidation. Prioritize immune-enhancing formulation R&D to sustain premium pricing tolerance in surgical and oncology segments. For New Entrants and Emerging Players: Direct-to-clinician digital platforms bypass entrenched GPO relationships in specialized metabolic and intestinal rehabilitation clinics. Home healthcare providers in the United States represent the most penetrable channel given CMS reimbursement recalibration momentum. Lead with remote monitoring integration for patient-administered enteral systems to differentiate from legacy device-nutrition bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor sterile manufacturing asset owners in Germany and France facing EMA MDR compliance cost escalation. Five-to-ten year viability hinges on pre-validated quality systems spanning device and drug regulatory frameworks. Watch FDA enforcement patterns on enteral device material specifications as inflection signal for vendor pool compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pharmaceutical-Grade Lipids | German chemical producers secure captive supply for sterile parenteral emulsion manufacturing. |
| FDA Enteral Device Safety Dossier Expansion | Abbott and Nestlé Health Science pre-validate materials to compress hospital vendor pools. |
| Home Healthcare Channel Partnership | Remote monitoring integration captures CMS-reimbursed patient-administered enteral volume. |
| Immune-Enhancing Formulation R&D | Danone Nutricia targets surgical recovery segments with limited therapeutic substitutes. |
| European Long-Term Care Network Contracting | Dutch and German procurement cooperatives standardize disease-specific oral nutrition programs. |
Research Methodology
FDA 510(k) filings, EMA Medical Device Regulation submissions, and CMS Medicare reimbursement databases formed the secondary backbone, cross-referenced with primary interviews spanning hospital procurement directors, enteral device biomedical engineers, GPO contracts managers, and sterile compounding pharmacy operators. Bottom-up and top-down triangulation validated manufacturer capacity claims against hospital formulary adoption data.
Bottom-up modeling aggregated segment-level volume across delivery mode, product type, application, and end-user dimensions, while top-down constraints checked aggregate figures against macro health expenditure trends. CAGRs derived from fitted growth curves across the projection horizon, incorporating immune-enhancing nutrient penetration rates and home healthcare channel shift assumptions.
The model holds under stable FDA and EMA regulatory enforcement; deviation in reimbursement recalibration velocity or lipid emulsion supply disruption would shift trajectory. Forecasts embed assumptions on hospital vendor consolidation pace and sterile manufacturing capacity expansion. A small set of named triggers—CMS home-based nutrition coverage expansion, REACH material disclosure enforcement, and batch release testing bottlenecks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Functional Chewing Gums Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Very Low Calorie Desserts Market
Functional Food and Beverage
Digestive Health Drinks Market
Functional Food and Beverage
Natural Functional Food Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Middle East and Africa Functional Beverages Market
Functional Food and Beverage
Global Low Calorie Food Market
Functional Food and Beverage
Hydrogen Water Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Functional Tea Market
Functional Food and Beverage
Ready-To-Drink (RTD) Protein Beverages Market
Functional Food and Beverage
Fermented Protein Market