
 South America Baby Food Market | 2026-2036
South America Baby Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Baby Food Market Analytics
Organic certification tiers is redrawing competitive boundaries across the South America Baby Food Market. Nestlé SA leverages its dairy supply chain depth to dominate wet formula shelf space in Brazilian pharmacies. Danone SA anchors its position through specialized nutrition R&D for premature infant segments. Abbott Laboratories differentiates via medical channel control, sustaining prescription-linked distribution networks that competitors struggle to replicate.
Baby food comprises processed or prepared nutritional products formulated for infants and toddlers, typically featuring controlled protein-lipid-carbohydrate ratios, iron fortification, and micronutrient profiles meeting pediatric dietary standards. Manufacturing employs aseptic processing, retort sterilization, or gentle cold-pressing to preserve nutritional integrity while ensuring shelf stability. Dry baby food retains margin concentration due to logistics efficiency and longer shelf life, while organic baby food captures fastest growth as Brazilian and Argentine parents prioritize residue-free claims. Ready-to-feed formats expand through convenience-seeking urban households, though wet baby food still occupies volume leadership in lower-income brackets where cost per serving governs purchase decisions.
ANVISA governs infant formula registration, labeling, and compositional standards across Brazil, while Argentina's national food safety authority enforces parallel fortification requirements that shape cross-border product adaptation. The Mercosur technical regulation harmonization effort reduces compliance fragmentation for manufacturers operating across member states. Stakeholders must monitor pending updates to sodium and sugar thresholds, as these thresholds will determine which existing formulations require reformulation or face market withdrawal.
Market Dynamics
Urban working mothers across Brazil's metropolitan corridors are compressing preparation time windows, forcing manufacturers to reconfigure product formats around single-serve convenience and extended ambient stability without refrigeration dependency.
Growth Catalysts
- ANVISA fortification mandates:Updated iron and micronutrient requirements for infant cereals are pulling reformulated premium lines into Brazilian retail channels, creating compliance-driven upgrade cycles across the installed base.
- São Paulo-Rio de Janeiro corridor concentration:Dense urban household clustering in Brazil's Southeast enables logistics efficiency for ambient-stable ready-to-feed formats, reducing last-mile distribution costs relative to dispersed rural markets.
- Cold-pressing technology adoption:Gentle processing methods preserving heat-sensitive vitamins are expanding organic puree shelf presence in Argentine premium retail, differentiating residue-free claims against conventional retort products.
Market Restraints
- Dairy input cost volatility:Powdered milk and whey protein concentrate prices fluctuate with Argentine and Uruguayan dairy auction cycles, compressing margin predictability for wet formula manufacturers.
- Import dependency for specialized ingredients:DHA and ARA lipid concentrates flow through concentrated European and North American suppliers, exposing Brazilian formulators to currency-driven cost spikes and extended lead times.
- Substitution pressure from home-prepared complementary foods:Grandmother networks in lower-income Brazilian households persistently undercut commercial cereal penetration through traditional porridge preparation.
Strategic Opportunities
- Colombia and Chile underpenetration:Per-capita commercial baby food consumption in Andean markets trails Brazilian levels by substantial margins, offering first-mover positioning for ambient-stable pouch formats.
- Mercosur technical harmonization:Pending alignment of sodium and sugar thresholds across member states will enable single-SKU regional strategies, reducing formulation fragmentation costs.
- Pharmacy channel expansion:Prescription-linked specialty nutrition for premature infants represents a high-margin white space with limited current competition outside hospital discharge protocols.
Industry Challenges
- Pediatric nutritionist talent scarcity:Formulation science expertise combining micronutrient stability knowledge with regional taste adaptation remains concentrated in São Paulo and Buenos Aires, constraining R&D scaling.
- Organic certification timeline compression:Brazilian MAPA and Argentine SENASA organic audit backlogs extend new product qualification cycles, delaying residue-free line launches against competitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Baby Food Market |
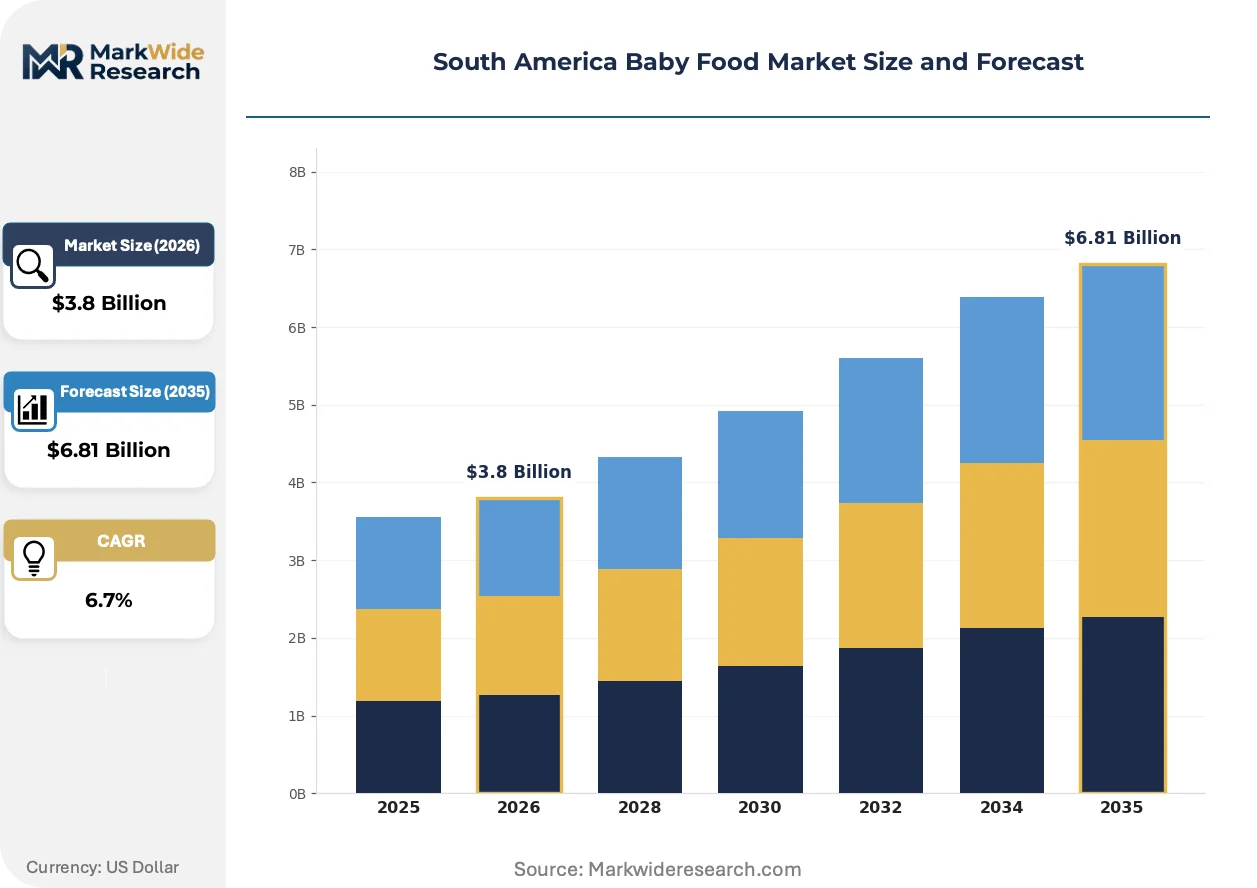
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Baby Food, Wet Baby Food, Organic Baby Food, Ready-to-Feed Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Age Group: Infants, Toddlers, Newborns, Premature Babies Packaging Type: Squeeze Pouches, Jars, Tins, Pouches |
| Companies Covered | Nestlé SA, Danone SA, Abbott Laboratories, The Hero Group, Reckitt Benckiser Group plc, Nutrimental SA, Sun-Maid Growers of California, Holle baby food AG, The Hain Celestial Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Baby Food Market Evolving Landscape
Processing technology convergence and regulatory threshold tightening are reconfiguring competitive advantage around formulation precision and shelf-life engineering rather than brand heritage alone.
Aseptic cold-filling systems for ambient-stable purees are supplanting traditional retort sterilization in Brazilian premium manufacturing. São Paulo-based processors are adopting European-designed sterile blow-fill-seal lines to preserve vitamin C and polyphenol content in fruit-vegetable blends. This equipment transition is compressing heat-degradation losses from 15-20% to under 5%, enabling cleaner-label positioning without preservative dependency.
ANVISA's pending sodium threshold reductions for toddler snacks are forcing reformulation of existing cereal-based finger food portfolios. Manufacturers must replace sodium-dependent texture modifiers with alternative binding systems or face mandatory market withdrawal. The snack segment, concentrated in Brazil's Southeast retail chains, is responding with potassium chloride substitution trials and yeast extract flavor masking investments.
Subscription-based replenishment models are displacing traditional supermarket stock-up behavior among dual-income households in Buenos Aires and Santiago. Direct-to-consumer platforms offering personalized nutrition stage progression are capturing trial-to-loyalty conversion through pediatrician-endorsed algorithmic recommendations. This channel shift is most visible in organic and hypoallergenic segments where parental information-seeking intensity peaks.
South America Baby Food Market Segmentation
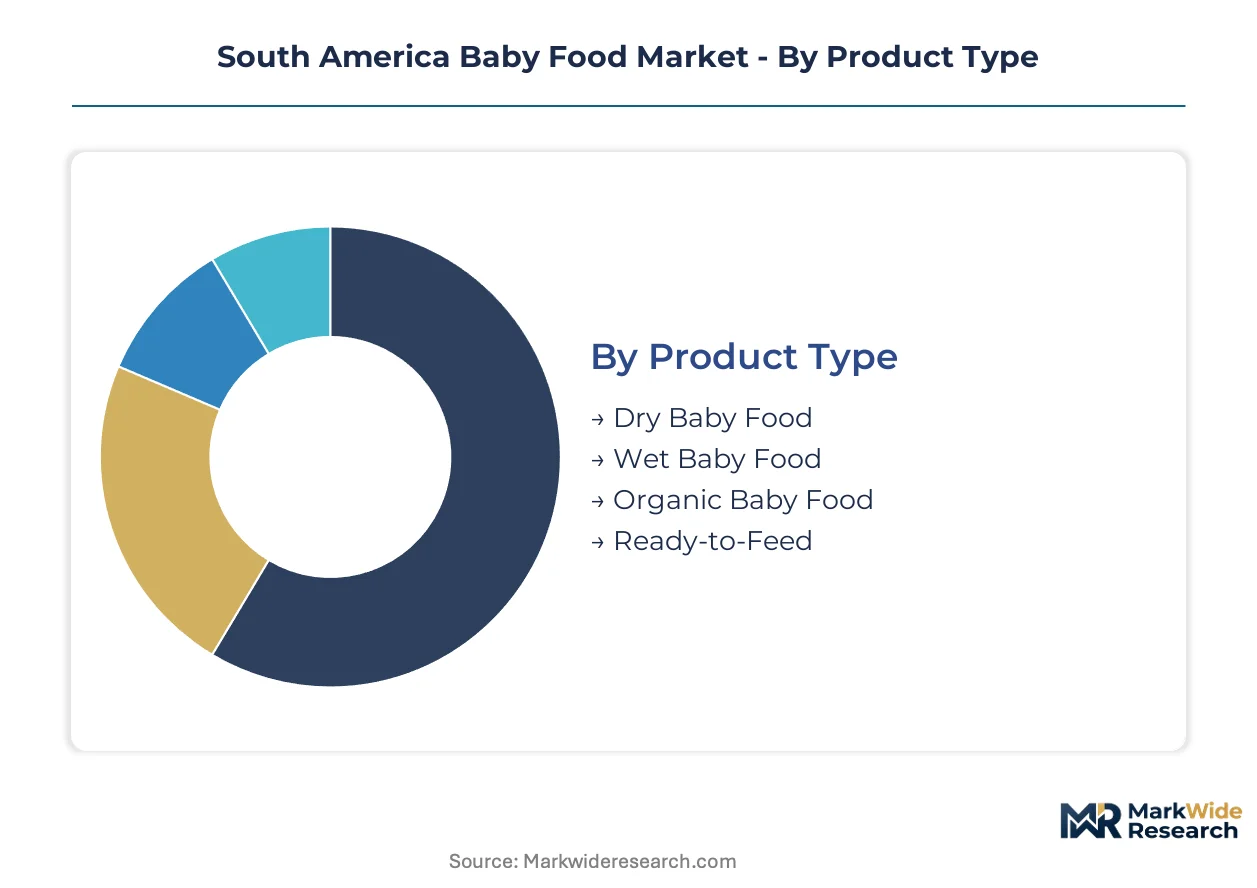
Segmentation in South America's baby food sector reflects divergent regulatory thresholds, urban infrastructure gaps, and maternal workforce participation patterns that reshape format preferences across Brazilian and Argentine households. Manufacturers must align product architecture with ANVISA fortification tiers, pharmacy channel requirements, and cold-chain availability to capture addressable demand.
Product Type:
ANVISA compositional standards differentiate permissible micronutrient profiles across liquid, powdered, and residue-free categories, forcing distinct registration pathways and reformulation cycles.
- Dry Baby Food:Powdered cereals and infant formulas dominate logistics economics through ambient stability and extended shelf life. São Paulo-based distributors leverage rail-linked warehousing to push iron-fortified variants into Brazil's Northeast, where refrigeration infrastructure remains sparse.
- Wet Baby Food:Sterilized purees and liquid concentrates require retort or aseptic processing to meet bacterial load standards. Argentine SENASA enforces parallel thermal treatment documentation, creating compliance friction for cross-border SKU rationalization.
- Organic Baby Food:MAPA and SENASA audit backlogs constrain residue-free line velocity. Brazilian premium retailers in Rio de Janeiro's Zona Sul cluster command three-tier pricing across certified organic, transitional, and conventional tiers.
- Ready-to-Feed:Single-serve ambient-stable formats address time-compressed urban mothers in Belo Horizonte and Curitiba. ANVISA's updated labeling mandates for added sugar disclosure are forcing portfolio pruning of sweetened variants.
Dry baby food handles the majority of throughput; ready-to-feed formats are climbing the fastest on share.
Distribution Channel:
Channel selection in South America tracks cold-chain maturity, prescription linkage requirements, and urban household density gradients.
- Supermarkets:Hypermarket chains in Brazil's Southeast anchor volume through promotional bundling of cereal-stage products. Carrefour and GPA shelf-space negotiations concentrate assortment decisions in São Paulo buyer offices.
- Online Retail:Subscription algorithms for stage-progression nutrition gain traction among Buenos Aires dual-income households. Direct-to-consumer platforms bypass traditional wholesale markups while capturing pediatrician endorsement data.
- Specialty Stores:Pharmacy-linked specialty nutrition for premature infants operates under ANVISA's restricted distribution regulations. Hospital discharge protocols in Rio de Janeiro and São Paulo create captive demand funnels.
- Convenience Stores:Impulse-oriented formats in urban corridors stock emergency replenishment SKUs. Limited shelf space favors high-velocity ready-to-feed pouches over bulk dry formats.
Supermarkets retain the dominant transaction volume; online retail is expanding most quickly as logistics platforms mature.
Age Group:
Developmental stage determines protein-lipid ratios, texture progression, and micronutrient density specifications under pediatric dietary guidelines.
- Infants:Complementary feeding initiation at 4-6 months drives iron-fortified cereal demand. Brazilian Northeastern states show delayed commercial adoption relative to Southeast urban corridors.
- Toddlers:Finger foods and textured purees align with self-feeding skill acquisition. ANVISA's pending sodium threshold reductions target this segment for mandatory reformulation.
- Newborns:Starter formulas require DHA-ARA lipid enrichment from European and North American suppliers. Import dependency creates currency-exposed margin volatility for Brazilian formulators.
- Premature Babies:Specialized high-protein, high-calorie formulations command pharmacy channel premiums. Buenos Aires neonatal intensive care units generate concentrated demand for prescription-linked nutrition.
Infants represent the largest addressable population base; premature babies deliver the steepest margin expansion trajectory.
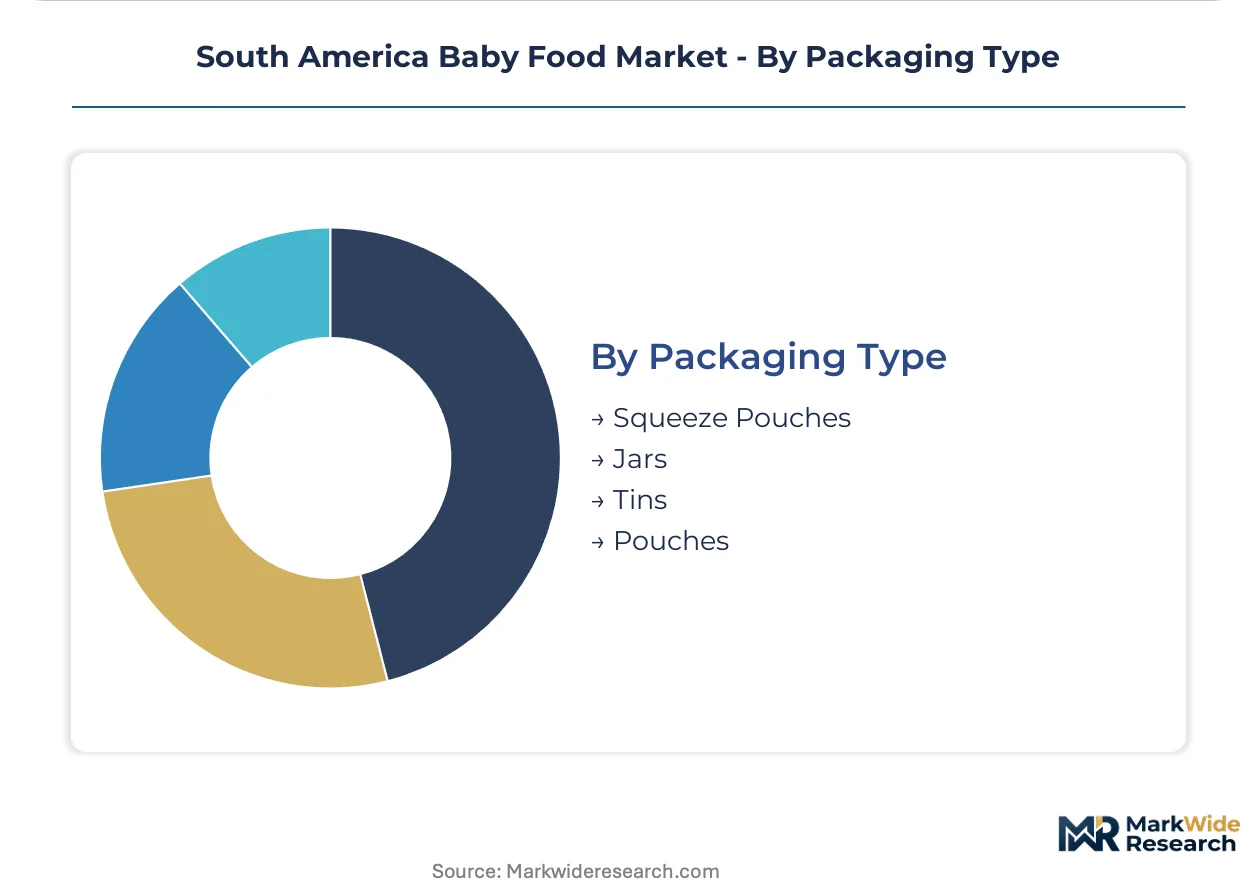
Packaging Type:
Material selection balances shelf-life engineering, parental convenience signaling, and regional recycling infrastructure capabilities.
- Squeeze Pouches:Flexible multilayer films with spout fitments enable single-hand feeding. Cold-pressing compatibility preserves vitamin C in Argentine organic fruit-vegetable blends.
- Jars:Glass containers dominate traditional wet food segments in lower-income Brazilian brackets. São Paulo's selective collection programs struggle with post-consumer glass recovery rates.
- Tins:Metal canisters retain powdered formula share through moisture barrier performance. Mercosur technical harmonization is streamlining regional tinplate specification compliance.
- Pouches:Stand-up flexible formats reduce shipping cube versus rigid alternatives. Chilean retail chains are piloting aseptic cold-filled pouch lines for ambient-stable premium purees.
Jars and tins together handle the majority of existing stock-keeping units; squeeze pouches are gaining share fastest through convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Brazil's Southeast corridor, where São Paulo and Rio de Janeiro anchor manufacturing capacity and distribution infrastructure for ambient-stable formats. Argentina's Pampas region supplies dairy inputs while Colombia and Chile emerge as underpenetrated expansion targets for pouch-format entrants.
Brazil
ANVISA fortification mandates for infant cereals drive reformulation cycles among São Paulo-based processors. The Southeast region generates concentrated demand for ready-to-feed products from time-compressed urban households. Belo Horizonte and Curitiba logistics hubs enable last-mile efficiency for ambient-stable formats reaching Brazil's Northeast.
Argentina
SENASA thermal treatment documentation requirements create compliance friction for cross-border SKU flows with Brazil. Buenos Aires neonatal intensive care units generate concentrated demand for prescription-linked specialty nutrition. The Pampas dairy belt supplies whey protein concentrate to regional formulators facing currency-exposed input costs.
Chile
Santiago retail chains pilot aseptic cold-filled pouch lines for premium organic purees targeting upper-income households. The country's national food safety authority enforces parallel labeling standards that ease Mercosur harmonization pathways. Antofagasta and Valparaíso distribution corridors enable Pacific-facing export positioning.
Colombia
Bogotá and Medellín urban corridors show per-capita commercial baby food consumption trailing Brazilian levels by substantial margins. The national health regulator's pending sodium threshold alignments will determine reformulation requirements for entering cereal-stage segments. Andean logistics constraints favor ambient-stable dry formats over cold-chain-dependent alternatives.
Uruguay
Dairy auction cycles in Montevideo supply whey protein concentrate to Brazilian wet formula manufacturers. The country's compact geography enables efficient collection of organic milk for residue-free line production. Punta del Este retail clusters test premium pricing acceptance for imported European organic certifications.
South America Baby Food Market Competitive Landscape
Concentration sits with multinational nutrition conglomerates possessing dairy supply chain depth and pharmacy channel control. Brazilian and Argentine markets show tiered structure across premium organic, standard fortified, and economy segments. Three archetypes dominate: pharmaceutical-linked specialty nutrition providers, dairy-integrated mass-market formulators, and organic-certified pure-play entrants. Competitive moves center on cold-processing technology licensing and subscription-based direct-to-consumer platform builds.
Within the pharmaceutical-linked tier, Abbott Laboratories and Danone SA exemplify prescription-channel anchoring for premature infant segments. Nestlé SA occupies a position representing dairy-integrated mass-market scale, leveraging warehousing density across Brazil's Southeast corridor. Among organic-certified specialists, Holle baby food AG and The Hain Celestial Group sit within the residue-free premium tier where MAPA and SENASA audit backlogs constrain new entrant velocity.
| Leading Market Players |
|---|
| Nestlé SA |
| Danone SA |
| Abbott Laboratories |
| The Hero Group |
| Reckitt Benckiser Group plc |
| Nutrimental SA |
| Sun-Maid Growers of California |
| Holle baby food AG |
| The Hain Celestial Group |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for DHA-ARA lipid concentrates tether Brazilian formulators to European supplier payment terms, compressing working capital flexibility while amplifying cost pass-through leverage for dairy-integrated incumbents with captive whey sourcing.
Pricing Analysis
ANVISA fortification mandates dictate the pricing tier structure across Brazilian retail channels. Three-tier pricing separates certified organic SKUs from standard fortified lines and economy private-label alternatives. Price differentiation rests on MAPA audit status and cold-processing certification. Cost compression in economy cereals is intensifying because grandmother-network substitution erodes volume scale. Lower-income households in Brazil's Northeast exhibit highest price sensitivity; pharmacy-channel specialty nutrition for premature infants shows lowest.
Supply Chain Analysis
Argentina and Uruguay anchor whey protein concentrate supply for regional wet formula production. Brazilian manufacturers draw from Pampas dairy auction cycles and Montevideo processing facilities. Import dependency for DHA-ARA lipids creates single-source vulnerability through concentrated North American and European suppliers. Distribution runs through São Paulo-based rail-linked warehousing into Southeast retail corridors, with Belo Horizonte and Curitiba hubs extending ambient-stable formats northward.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
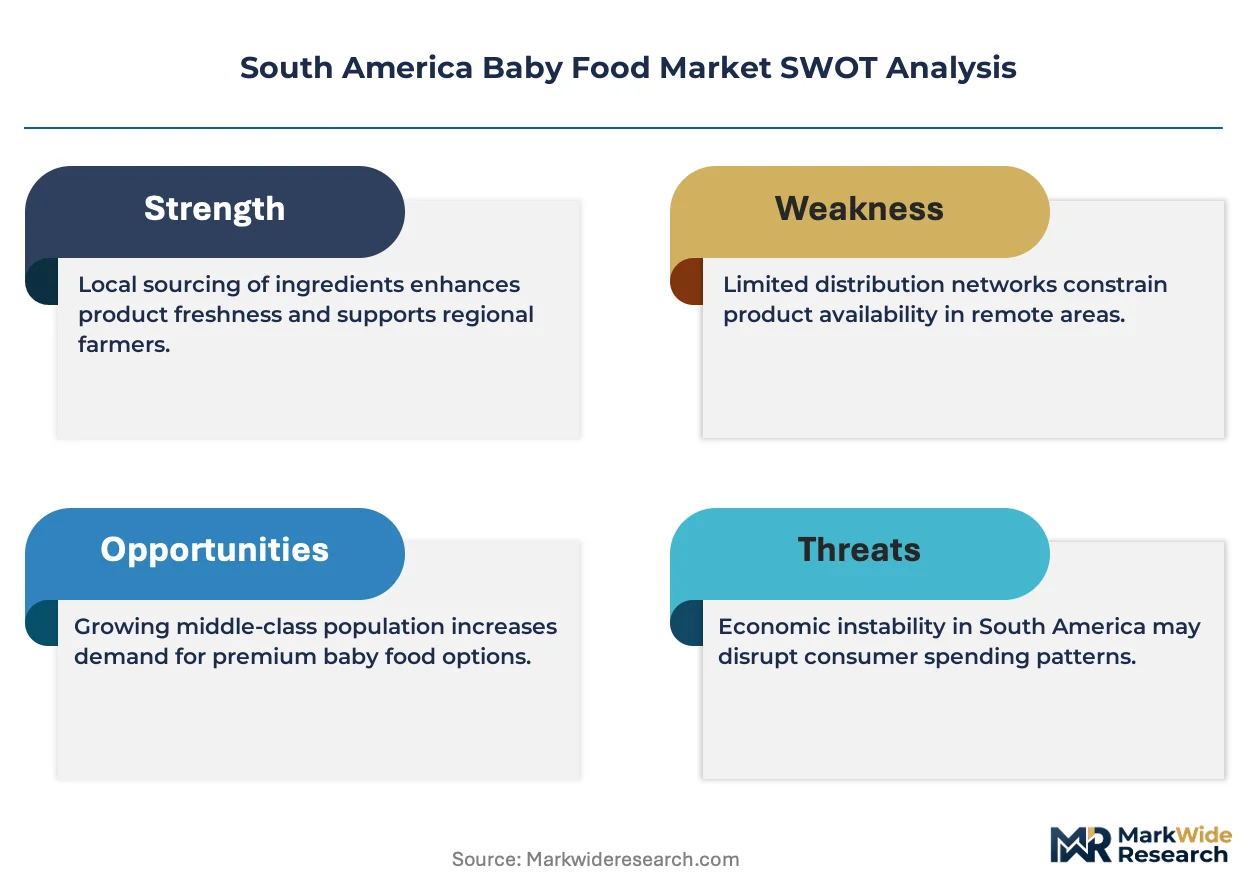
South America's baby food sector sits in early-cycle expansion as Colombian and Chilean per-capita consumption trails Brazilian benchmarks, creating runway for format innovation and channel development.
For Market Incumbents: Compound pharmacy channel control through prescription-linked specialty nutrition for premature infant segments, defending against dairy-integrated competitors seeking hospital discharge protocol access. Deepen backward integration into Pampas whey processing to buffer Argentine peso volatility and secure margin stability against currency-exposed input cost spikes. For New Entrants and Emerging Players: Lead with ambient-stable pouch formats in Bogotá and Medellín corridors where cold-chain gaps favor logistics-efficient alternatives. Target Colombia's underpenetrated cereal-stage segments through direct-to-consumer subscription platforms, bypassing traditional wholesale markups while capturing pediatrician endorsement data for algorithmic stage-progression recommendations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because pharmacy-channel specialty nutrition and organic certification backlogs create durable moats for first-movers with regulatory navigation capabilities. Acquisition focus should center on Brazilian mid-cap processors with ANVISA registration depth and São Paulo warehousing density. The signal to watch is MAPA organic audit queue compression, which would accelerate residue-free line velocity and compress premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Cold-Filling Technology Licensing | Preserves vitamin C in Argentine organic purees while enabling cleaner-label positioning against retort competitors. |
| Direct-to-Consumer Platform Build | Captures Buenos Aires dual-income households through pediatrician-endorsed algorithmic nutrition stage progression. |
| Backward Integration into Whey Processing | Secures margin stability against Montevideo dairy auction cycle volatility for Brazilian wet formula manufacturers. |
| Pharmacy Channel Expansion | Accesses Rio de Janeiro and São Paulo hospital discharge protocols for high-margin premature infant specialty nutrition. |
| Mercosur Harmonization Preparation | Enables single-SKU regional strategies as sodium and sugar threshold alignment reduces formulation fragmentation costs. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings for this study. Primary fieldwork engaged formulation scientists at São Paulo and Buenos Aires R&D centers, procurement leads at Brazilian dairy processors, pharmacy channel managers in Rio de Janeiro, and category buyers at Southeast hypermarket chains. Secondary validation drew from ANVISA registration databases, MAPA organic certification records, Mercosur technical regulation harmonization documents, and Brazilian customs trade flow data. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Sensitivity analysis around dairy input cost assumptions and currency exposure scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, developmental age group, and packaging material, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from installed base penetration curves and replacement rate dynamics, incorporating ANVISA reformulation cycle timing and organic certification queue projections as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained ANVISA enforcement consistency or Mercosur harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding maternal workforce participation trends and cold-chain infrastructure expansion. Recalibration cycles align with material shifts in MAPA organic audit processing capacity and pending sodium threshold finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Omega 3 Ingredients for Infant Food Market
Baby Food and Infant Formula
West Africa Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Hypo Anti Allergic Baby Food Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Canned Baby Food Market