
 Global Cane Molasses Market | 2026-2036
Global Cane Molasses Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cane Molasses Market Analysis
ISO 22000 certification is reorganizing supplier eligibility across the Global Cane Molasses Market, forcing smaller mills to upgrade food safety systems or retreat to non-food applications. Archer Daniels Midland Company leverages its North American distribution network to secure premium unsulfured grades for food manufacturers. Mitr Phol Sugar Corporation anchors supply reliability through captive cane estates in Thailand's central plains. Cargill, Incorporated competes on bulk logistics scale, operating dedicated molasses terminals at key export ports.
Cane molasses denotes the viscous, dark-brown syrup extracted during repeated boiling of sugarcane juice, containing 20-25% sucrose, 15-20% reducing sugars, and significant mineral content including iron, calcium, and potassium; manufacturers produce it through three-stage evaporation and centrifugation, yielding a hygroscopic liquid primarily employed as a fermentable carbohydrate source and palatability enhancer. Blackstrap molasses commands the deepest processing investment due to its concentrated mineral profile and nutraceutical appeal. The animal feed segment dominates volume offtake as livestock producers substitute molasses for grain-based energy in ruminant diets. Alcohol production represents the fastest-expanding end-use channel, with distilleries in Brazil and India capturing fermentation economics.
FDA food additive regulations in the United States, EFSA purity standards under EU food law, and BIS certification requirements in India collectively determine which molasses grades enter human-consumption channels versus restricted industrial use. The EU Green Deal's deforestation-free supply chain mandates are pressuring European importers to document cane origin down to plantation level. Stakeholders must monitor how carbon border adjustment mechanisms and evolving feedstock traceability rules reshape procurement geography and certification costs.
Market Dynamics
ISO 22000 certification is reorganizing supplier eligibility across the Global Cane Molasses Market, forcing smaller mills to upgrade food safety systems or retreat to non-food applications. This structural filter is concentrating supply among vertically integrated processors with captive laboratories and audit-ready documentation.
Growth Catalysts
- EU Green Deal deforestation-free mandates:European importers must document cane origin to plantation level, favoring suppliers with integrated estate-to-port traceability systems.
- Alcohol production expansion:Brazilian and Indian distilleries capture fermentation economics by substituting molasses for grain-based feedstocks in ethanol manufacturing.
- Ruminant diet reformulation:Livestock producers in Australia and Argentina substitute molasses for grain-based energy to reduce acidosis risk and improve palatability.
Market Restraints
- Input cost volatility:Sugarcane prices fluctuate with monsoon patterns in India and crushing season timing in Brazil, squeezing processor margins.
- Supply concentration risk:Three countries control over 80% of exportable molasses volume, creating geographic single-point-of-failure exposure.
- Substitution threat:Beet molasses and corn steep liquor compete for animal feed and fermentation applications in North American and European markets.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya lack domestic molasses refining capacity, creating import substitution openings for integrated suppliers.
- Nutraceutical grade blackstrap:Concentrated mineral profiles appeal to dietary supplement formulators seeking natural iron and calcium sources.
- Carbon border adjustment positioning:EU CBAM implementation rewards processors with verified low-carbon cane cultivation and biogas-powered evaporation.
Industry Challenges
- ISO 22000 certification timeline:Small and mid-size mills face 18-24 month compliance windows with limited technical staffing.
- Legacy traceability system integration:Plantation management software must interface with EU deforestation-free documentation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cane Molasses Market |
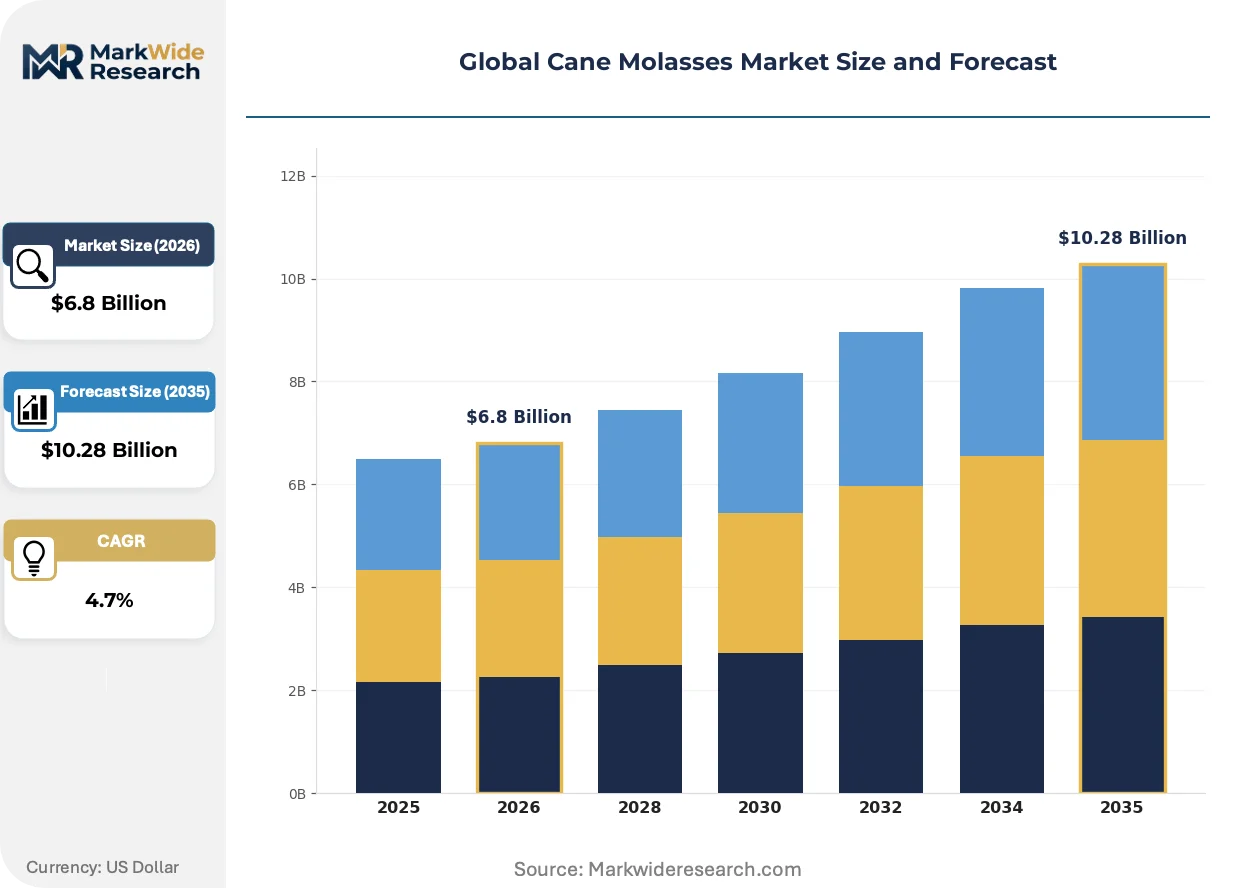
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sulfured Molasses, Unsulfured Molasses, Blackstrap Molasses, Cooking Molasses End Use: Animal Feed, Food Industry, Alcohol Production, Nutraceuticals Packaging Type: Bags, Drums, Bulk Containers, Jars Distribution Channel: Online Retail, Direct Sales, Supermarkets, Wholesale |
| Companies Covered | Archer Daniels Midland Company, ED&F Man Holdings Limited, Wilmar International Limited, Sudzucker AG, Mitr Phol Sugar Corporation, Cargill, Incorporated, Tereos Group, Raizen Energia, Louis Dreyfus Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cane Molasses Market Emerging Trajectories
Processing technology and regulatory documentation requirements are splitting the supplier base into certified food-grade operators and commodity-grade sellers. This divergence is reshaping capital allocation and competitive positioning across extraction and distribution stages.
Membrane filtration technology is bifurcating the molasses processing landscape. Advanced ceramic and polymeric membranes enable selective sugar recovery and impurity removal without thermal degradation. Brazilian and Thai processors deploying these systems capture premium unsulfured grades for pharmaceutical and food manufacturers. The technology is bifurcating market tiers: membrane-equipped facilities command 40-60% price premiums over conventional evaporators while legacy operators retreat to bulk animal feed channels.
EFSA purity standards under EU food law are tightening contaminant thresholds for 3-MCPD esters and glycidyl esters in molasses destined for human consumption. European importers now require batch-level testing certificates from accredited laboratories. Food-grade molasses shipments to Germany, Netherlands, and France face extended customs clearance protocols, diverting marginal supply into industrial alcohol channels.
Direct contracting between distilleries and plantation groups is displacing spot market purchases in Brazil's Center-South region. Large ethanol producers negotiate multi-year supply agreements with fixed volume floors and quality bands. This consolidation of procurement decision-making concentrates pricing power among buyers with dedicated storage and rail-loading infrastructure. The shift is most visible in São Paulo state, where over 60% of crushing capacity now operates under integrated supply arrangements.
Global Cane Molasses Market Segmentation
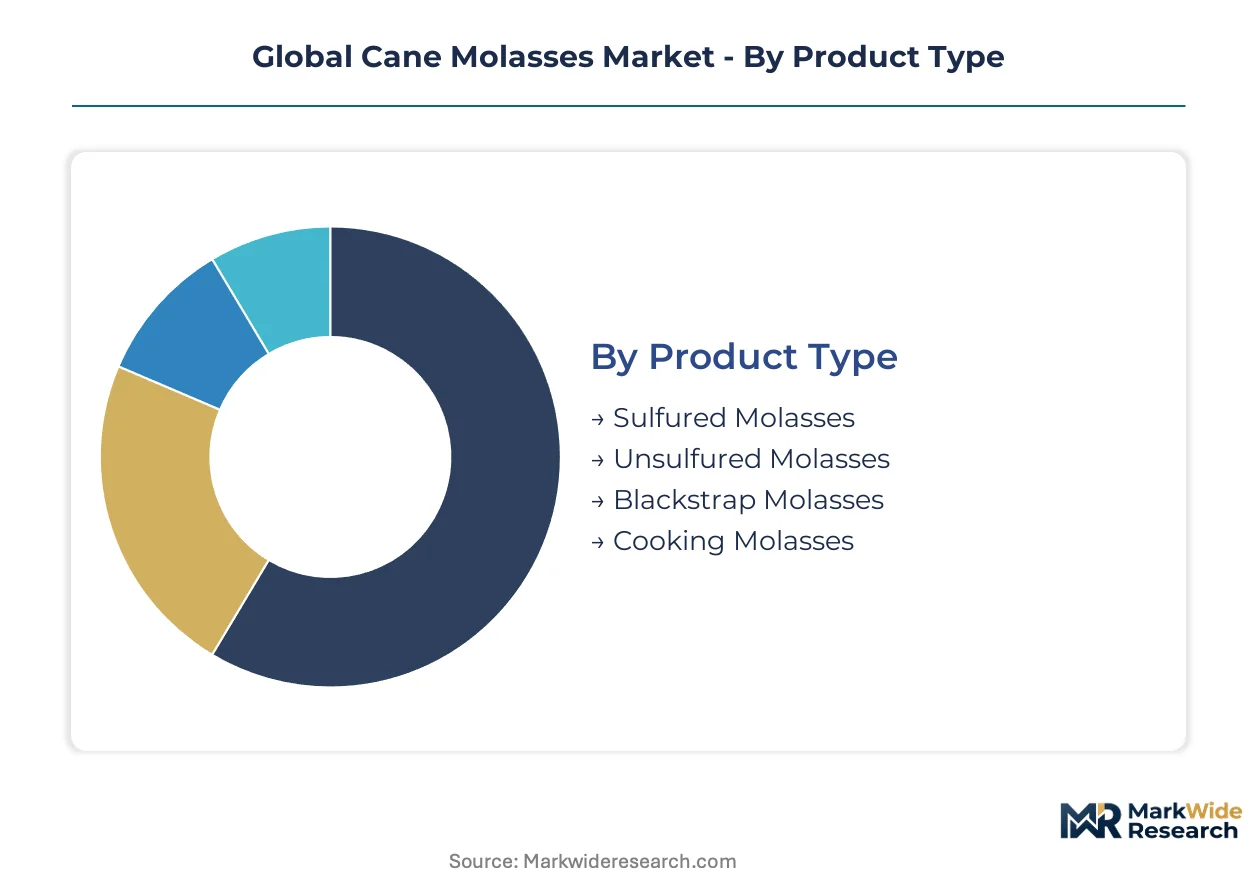
Molasses procurement patterns diverge sharply across product grades, end-use specifications, and logistics formats. Understanding these fault lines reveals where certification premiums concentrate and which channels absorb volume at commodity pricing.
Product Type:
Margin pools sit deepest in grades commanding food-safety certification and pharmaceutical suitability.
- Unsulfured Molasses:Produced without sulfur dioxide treatment, this grade retains cleaner flavor profiles and lower residual sulfite levels. European food manufacturers and premium bakeries in France and Germany specify unsulfured grades for clean-label product lines, paying certification premiums that conventional processors cannot capture.
- Blackstrap Molasses:The third-boiling extraction yields 40-50% total sugars with concentrated iron, calcium, and magnesium content. Nutraceutical formulators in the United States and dietary supplement distributors in Australia source blackstrap for natural mineral fortification, though EFSA contaminant thresholds now require batch-level testing for glycidyl esters.
- Sulfured Molasses:Sulfur dioxide treatment during juice clarification preserves lighter color and extended shelf stability; industrial alcohol distilleries in Brazil and animal feed compounders in India absorb most sulfured volume at commodity price points.
- Cooking Molasses:Intermediate sucrose content (25-35%) positions this grade between table syrup and blackstrap; regional sauce manufacturers in Thailand and small-scale confectioners in Indonesia represent primary offtake.
Unsulfured molasses holds installed capacity. Blackstrap molasses is rotating up the share rankings.
End Use:
Application mix determines whether processors invest in membrane filtration or remain in bulk commodity channels.
- Animal Feed:Ruminant diet reformulation drives the largest volume channel, with Australian cattle operations and Argentine dairy cooperatives substituting molasses for grain-based energy to reduce acidosis risk. Bulk logistics and price sensitivity dominate procurement criteria here.
- Alcohol Production:Brazilian Center-South distilleries and Indian ethanol manufacturers capture fermentation economics by displacing grain feedstocks. Direct plantation contracting now covers over sixty percent of São Paulo state crushing capacity.
- Food Industry:Bakery, sauce, and confectionery applications require ISO 22000 certification and documented deforestation-free origin under EU Green Deal mandates; German and Dutch importers face extended customs clearance without accredited laboratory certificates.
- Nutraceuticals:Concentrated mineral profiles in blackstrap appeal to supplement formulators seeking natural iron sources; this segment climbs fastest as clean-label positioning spreads from North America into European pharmacy channels.
Animal feed anchors volume throughput. Alcohol production is climbing the fastest.
Packaging Type:
Packaging economics split between ocean-bulk efficiency and last-mile flexibility requirements.
- Bulk Containers:ISO tank containers and flexitanks dominate intercontinental shipments from Brazilian Santos and Thai Laem Chabang ports, minimizing handling costs for distillery and feed mill customers with dedicated unloading infrastructure.
- Drums:Standard 200-liter steel and polyethylene drums serve mid-size food manufacturers and regional distributors requiring smaller lot sizes without cold chain investment.
- Bags:Multi-layer laminated bags target artisanal bakeries and small-scale livestock operations in Nigeria and Kenya where import substitution opportunities remain underpenetrated.
- Jars:Retail-format glass and PET containers reach supermarket shelves and online retail channels in North American and European consumer markets.
Bulk containers dominate export tonnage. Drums are gaining share fastest in regional distribution.
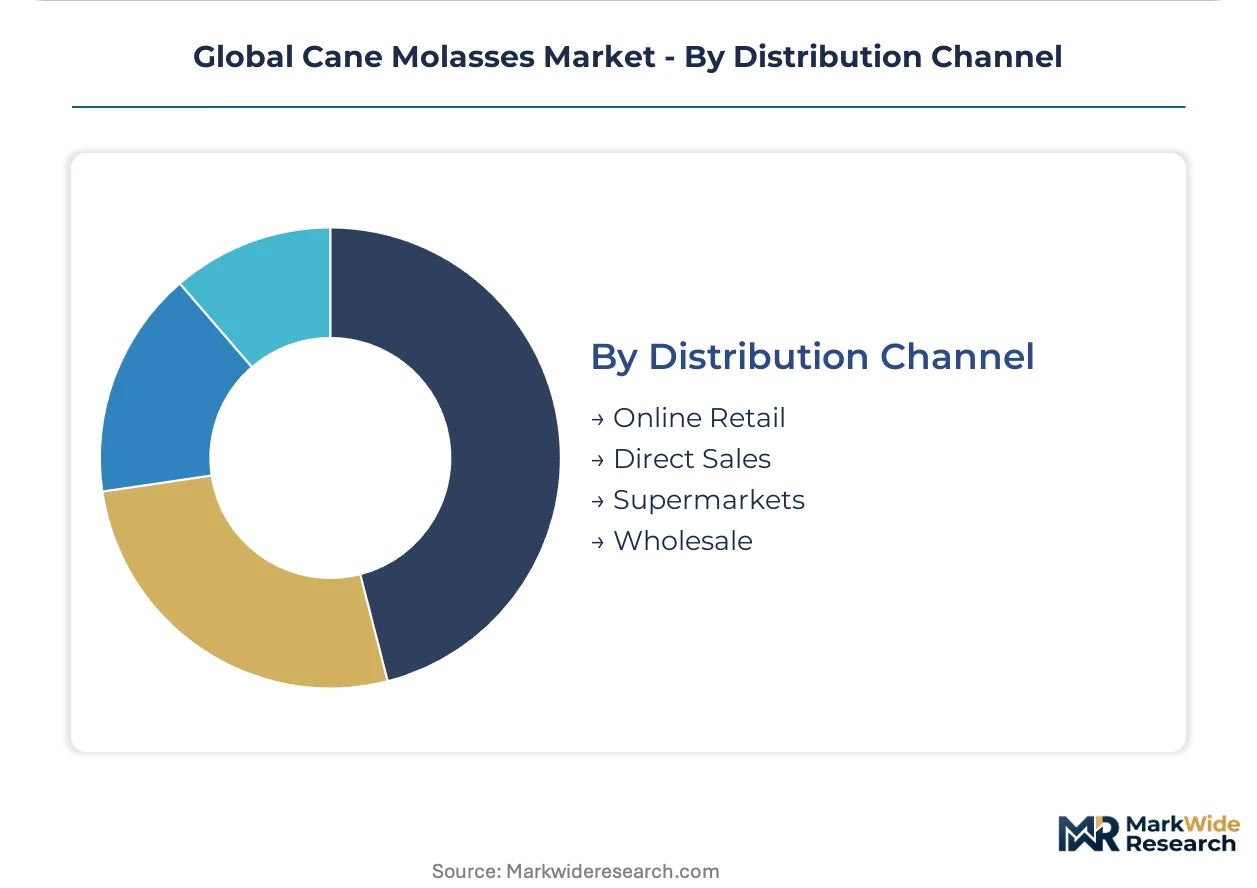
Distribution Channel:
Channel structure reflects the tension between plantation-direct efficiency and fragmented end-user access.
- Direct Sales:Integrated sugar processors in Thailand's central plains and Brazilian Center-South negotiate multi-year supply agreements with ethanol producers and multinational feed compounders, eliminating intermediary margins.
- Wholesale:Regional distributors in India's Maharashtra and Uttar Pradesh aggregate output from small mills lacking export certification, reselling into domestic industrial channels.
- Supermarkets:Retail shelf presence concentrates in North American and European urban centers where consumer molasses competes with honey and maple syrup for baking and breakfast applications.
- Online Retail:E-commerce platforms capture specialty and organic-certified grades for home bakers and small-batch food entrepreneurs, though refrigerated shipping requirements limit blackstrap penetration.
Direct sales command volume concentration. Online retail is expanding most quickly in specialty segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal deforestation-free mandates and India's PLI scheme for ethanol production are redirecting investment toward integrated cane estates with plantation-level traceability systems. Brazil's Center-South region and Thailand's central plains anchor exportable supply, while Germany and the Netherlands impose the strictest contaminant testing protocols for food-grade imports.
Brazil
Center-South distilleries in São Paulo state capture fermentation economics by displacing corn feedstocks with molasses-based ethanol. ANVISA's updated food additive regulations align with Mercosur harmonization efforts, tightening sulfite residual limits for human-consumption grades. Santos port operators have installed dedicated molasses terminals to handle direct contracting volumes from integrated plantation groups.
India
Maharashtra and Uttar Pradesh mills supply domestic alcohol manufacturers and animal feed compounders amid rising ethanol blending mandates. BIS certification requirements for food-grade molasses now require ISO 22000 documentation, forcing smaller processors toward industrial channels. The crushing belt around Kolhapur anchors capacity expansion as distilleries negotiate multi-year supply agreements with fixed volume floors.
Thailand
Mitr Phol's captive estates in the central plains supply unsulfured grades to European food manufacturers seeking clean-label inputs. The country's Board of Investment incentives favor biogas-powered evaporation systems that reduce carbon intensity scores for EU CBAM compliance. Laem Chabang port infrastructure handles bulk container shipments to German and Dutch importers requiring batch-level testing certificates.
Germany
EFSA purity standards under EU food law impose extended customs clearance protocols for molasses shipments lacking accredited laboratory documentation. Hamburg and Rotterdam serve as distribution hubs for regional bakery and sauce manufacturers specifying unsulfured grades. The country's feed compounders substitute beet molasses for cane origins when traceability documentation proves insufficient.
United States
FDA food additive regulations distinguish between sulfured and unsulfured grades for pharmaceutical and nutraceutical applications. Archer Daniels Midland leverages its North American distribution network to secure premium unsulfured volumes for food manufacturers. Gulf Coast terminals handle bulk imports from Brazilian Santos for distillery customers with dedicated rail-loading infrastructure.
Global Cane Molasses Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, with public companies commanding food-grade premiums and private operators dominating bulk commodity channels. The vendor base splits between vertically integrated plantation groups and merchant traders lacking captive crushing capacity. Three archetypes dominate: estate-integrated processors with in-house laboratories, global traders with dedicated port terminals, and regional distributors aggregating uncertified small-mill output. Competitive moves concentrate on backward integration into cane cultivation and membrane filtration technology licensing.
Within the estate-integrated tier, Mitr Phol Sugar Corporation and Raizen Energia exemplify the model of captive supply chains with plantation-to-port traceability systems. Among global trading houses, Cargill, Incorporated occupies a position defined by bulk logistics scale rather than upstream asset ownership. Archer Daniels Midland Company represents the North American distribution-focused archetype, securing premium grades through contractual relationships rather than crushing capacity.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| ED&F Man Holdings Limited |
| Wilmar International Limited |
| Sudzucker AG |
| Mitr Phol Sugar Corporation |
| Cargill, Incorporated |
| Tereos Group |
| Raizen Energia |
| Louis Dreyfus Company |
| Others |
Supply Flow & Price Mechanics
Beet molasses substitution in European feed formulations simultaneously redraws procurement geography toward Baltic processing zones and compresses price premiums for uncertified cane grades. This input displacement forces Brazilian and Thai suppliers to defend food-grade positioning through ISO 22000 documentation or retreat to bulk alcohol channels.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-accredited food-grade shipments and commodity sulfured volumes bound for industrial use. Three-tier pricing structure across premium unsulfured, standard food-grade, and economy industrial levels reflects membrane filtration investment and laboratory documentation costs. Pricing pressure stems from beet molasses competition in German and Dutch feed compounder procurement. Animal feed buyers exhibit highest price sensitivity, while pharmaceutical and nutraceutical formulators absorb certification premiums for contaminant-tested blackstrap.
Supply Chain Analysis
Santos port terminal congestion underwrites delivery risk for Center-South plantation groups negotiating direct distillery contracts. Supply concentrates in Brazil, India, and Thailand, with crushing capacity expansion in Maharashtra and São Paulo states. Raw material flows hinge on monsoon-dependent cane yields, sulfur dioxide availability for juice clarification, and membrane filtration equipment lead times. Single-source vulnerability runs through the three-country export concentration. Distribution runs through integrated estate-to-port traceability systems for EU-bound food-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from beet molasses and corn steep liquor in North American and European feed channels. Defense requires certification moats and captive supply chain control.
For Market Incumbents: Compound defensibility through backward integration into biogas-powered evaporation systems that lower carbon intensity scores for EU CBAM compliance. Secure multi-year plantation-direct contracts with fixed volume floors to lock in São Paulo and Kolhapur crushing capacity. Counter beet molasses encroachment by emphasizing traceability documentation that EU Green Deal mandates now require. For New Entrants and Emerging Players: Differentiate on nutraceutical-grade blackstrap positioning for North American dietary supplement channels where natural mineral fortification commands premium absorption. Target underpenetrated Nigerian and Kenyan markets lacking domestic refining capacity. Enter through bagged retail formats serving artisanal bakeries and small-scale livestock operations bypassing bulk infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed plantation groups in Thailand's central plains holding captive estate networks and existing EU export relationships. Long-term viability centers on processors with verified low-carbon cultivation and membrane filtration technology licensing. Watch carbon border adjustment implementation timelines as the inflection signal for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Brazilian processors deploying ceramic and polymeric systems capture 40-60% price premiums over conventional evaporators. |
| Biogas-Powered Evaporation Retrofit | Thai Board of Investment incentives reward carbon intensity reductions that satisfy EU CBAM documentation requirements. |
| Plantation-Direct Contracting Consolidation | São Paulo state crushing capacity now operates under integrated supply arrangements covering over sixty percent of volume. |
| ISO 22000 Certification Investment | Food-grade eligibility under EFSA purity standards requires accredited laboratory documentation for German and Dutch customs clearance. |
| African Import Substitution Buildout | Nigeria and Kenya lack domestic refining capacity, creating distribution openings for bagged and drum-format suppliers. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with sugar mill operations directors, distillery procurement managers, feed compounder formulation scientists, and European food manufacturer quality assurance leads; and secondary validation through customs trade databases, ANVISA regulatory filings, BIS certification registries, and SEC disclosures from listed processors. Bottom-up volume triangulation across crushing capacity, extraction yields, and end-use consumption patterns was cross-checked against top-down trade flow analysis.
Across the analysis window, forecasts modeled grade tier differentiation, end-use application mix, packaging format economics, and regional regulatory cluster alignment. CAGRs were derived from segment-level volume projections weighted by price realization bands. Industry-specific inputs included cane yield sensitivity to monsoon patterns, ethanol blending mandate trajectories, and EU deforestation-free documentation adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt beet molasses price shifts would require recalibration. Forecasts reflect documented assumptions about certification timeline compliance and membrane filtration adoption rates. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and feedstock traceability rules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Xylitol Injection Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Australia Allulose Market
Sweeteners
Japan Allulose Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
China Food Sweetener Market
Sweeteners
White Sugar Market
Sweeteners
Glucose Syrup Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
South Korea Allulose Market
Sweeteners
Dry Sweeteners Market