
 Galactose Market | 2026-2036
Galactose Market Size, Share, and Industry Trends Forecast 2026-2036
Galactose Market Analysis
China is tilting toward microbial fermentation capacity for galactose production, backed by state-level biomanufacturing targets. Kyowa Hakko Bio Co., Ltd. leverages its amino acid fermentation infrastructure to anchor galactose output in Asia-Pacific. Merck KGaA specializes in high-purity biochemical grades for European pharmaceutical customers. CJ CheilJedang Corp. competes on enzymatic conversion scale, extending its sweetener technology platform into rare sugars.
Galactose is a monosaccharide sugar, C6H12O6, typically derived from lactose hydrolysis or microbial biosynthesis, with specific rotation [α]D20 = +80.2° serving as a key purity marker. The molecule functions as a critical carbon source in cell culture media and a building block for pharmaceutical glycosylation. Powdered galactose dominates pharmaceutical procurement due to stability and precise dosing requirements, while liquid formulations are gaining traction in industrial fermentation feedstock. Microbial galactose represents the fastest-expanding product category as synthetic biology platforms reduce production costs. Food and beverage applications remain mature, with margin pools shifting toward nutraceutical-grade certifications.
FDA excipient guidelines and EMA GMP standards govern pharmaceutical-grade galactose purity thresholds, directly shaping supplier qualification timelines. ISO 22000 and FSSC 22000 certifications operate as baseline requirements for food-processing segment entry. REACH registration obligations in Europe constrain small-volume importers, consolidating supply relationships with established registrants. Stakeholders must monitor regulatory divergence between pharmacopeial grades and emerging cell-culture specifications to anticipate qualification bottlenecks.
Market Dynamics
Biopharmaceutical-grade purity specifications are compressing supplier margins while simultaneously erecting qualification barriers that favor established fermentation platforms over chemical synthesis routes.
Growth Catalysts
- FDA excipient guideline tightening:Pharmaceutical manufacturers now require documented carbohydrate impurity profiles for parenteral nutrition formulations, forcing excipient suppliers to invest in analytical capability.
- Cell culture media expansion:CHO cell and hybridoma production lines for monoclonal antibodies consume galactose as a defined carbon source, with biologics manufacturing capacity expanding across the United States.
- Microbial biosynthesis maturation:Engineered yeast and bacterial strains now achieve titers competitive with lactose hydrolysis, reducing feedstock dependency on dairy industry volatility.
Market Restraints
- High-purity certification costs:Pharmacopeial-grade validation requires extensive heavy metal and endotoxin testing, creating fixed cost burdens that exclude smaller fermentation operators.
- Lactose price volatility:Dairy commodity markets transmit feedstock cost instability directly to hydrolysis-based galactose producers, compressing margin predictability.
- Enzymatic conversion yield ceilings:Current β-galactosidase biocatalysts face thermodynamic limits on lactose conversion efficiency, constraining unit economics against microbial routes.
Strategic Opportunities
- India biopharma contract manufacturing:CDSCO manufacturing license reforms and PLI scheme incentives for active pharmaceutical ingredients create demand for qualified excipient suppliers.
- Synthetic biology platform integration:CRISPR-edited microbial chassis combined with continuous fermentation is opening cost structures previously inaccessible to pharmaceutical carbohydrate production.
- Direct-to-biotech distribution:Bypassing traditional chemical distributors through qualified supplier programs with cell therapy developers shortens procurement cycles and captures margin.
Industry Challenges
- Analytical chemistry talent scarcity:Carbohydrate structural analysis and glycoprotein characterization expertise concentrates in academic and large-pharma settings, limiting quality control hiring pools for mid-scale suppliers.
- Dual certification timeline compression:Simultaneous FDA Drug Master File and EMA CEP submissions require parallel documentation streams, straining regulatory affairs bandwidth.
- Legacy lactose supply contract renegotiation:Long-term dairy processor agreements lock in volume commitments that misalign with shifting pharmaceutical grade mix toward microbial-origin product.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galactose Market |
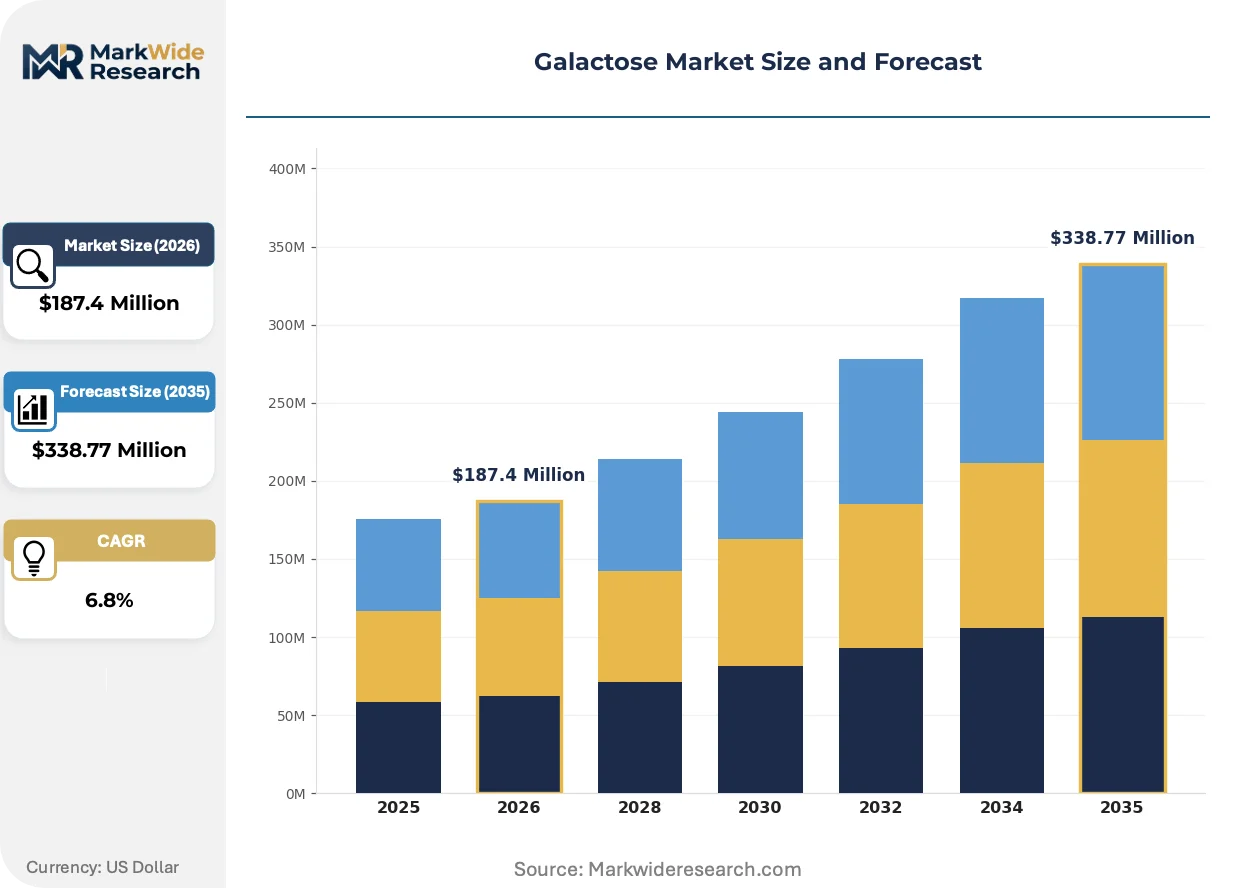
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Galactose, Powdered Galactose, Galactose Syrup, Microbial Galactose Application: Food & Beverages, Pharmaceuticals, Nutraceuticals, Cosmetics End Use Industry: Healthcare, Food Processing, Personal Care, Animal Feed Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Kyowa Hakko Bio Co., Ltd., CJ CheilJedang Corp., Merck KGaA, Nacalai Tesque Inc., Sigma-Aldrich, Thermo Fisher Scientific Inc., Cargill Inc., Anhui HeGeng Biotech Engineering Co., LTD., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galactose Market Emerging Trajectories
Synthetic biology and precision fermentation are collapsing the traditional boundary between agricultural-derived and biomanufactured sugars, while regulatory agencies accelerate the documentation burden on supply chains.
Continuous fermentation technology is hybridizing with traditional batch carbohydrate production. Bioprocess engineers at contract manufacturing organizations are retrofitting amino acid production lines for rare sugar output, achieving steady-state operation that reduces downstream purification load. This hybridization is compressing capital intensity thresholds for pharmaceutical-grade galactose entry.
EMA's tightened nitrosamine risk assessment guidelines for excipients now require carbohydrate suppliers to demonstrate absence of N-nitrosodimethylamine and related compounds. Pharmaceutical formulators have responded by demanding comprehensive impurity testing protocols that extend qualification timelines by six to twelve months. European biologics manufacturers are consolidating supplier relationships with established registrants possessing dedicated analytical infrastructure.
Biotech procurement teams are unbundling excipient sourcing from general chemical distributor contracts, establishing direct quality agreements with carbohydrate specialists capable of lot-level traceability. This disintermediation displaces traditional fine chemical intermediaries from high-value pharmaceutical sugar segments. United States cell therapy developers are most aggressive in this transition, driven by FDA scrutiny of raw material variability in autologous manufacturing processes.
Galactose Market Segmentation
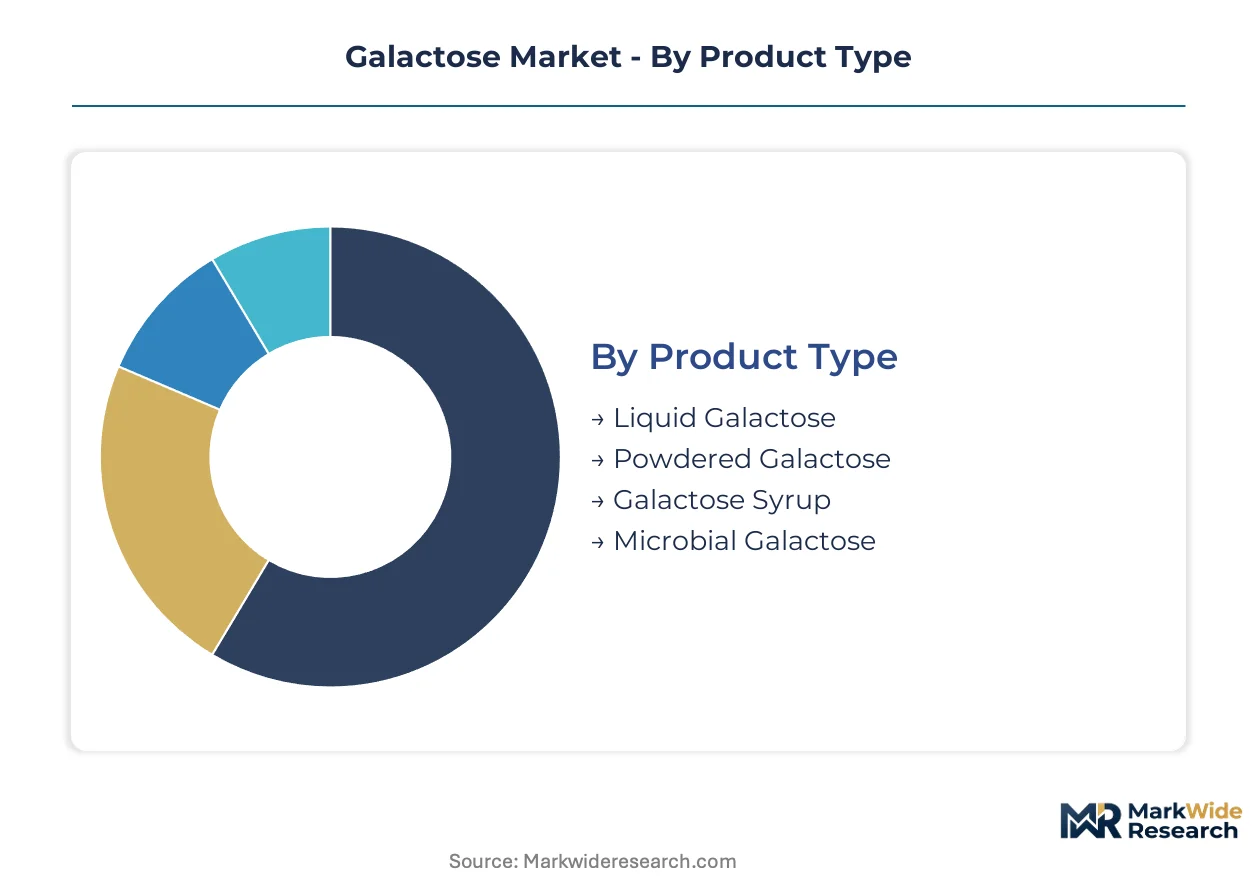
Galactose procurement patterns diverge sharply across physical forms, end-use specifications, and channel structures. Each segment carries distinct purity requirements, pricing tiers, and supplier qualification timelines that reshape competitive positioning.
Product Type:
Use cases span industrial fermentation feedstock through injectable-grade excipients, with physical form dictating stability, handling, and downstream processing economics.
- Powdered Galactose:Spray-dried crystalline form with defined particle size distribution serves pharmaceutical tableting and parenteral nutrition compounding. United States biopharmaceutical manufacturers specify endotoxin-controlled lots for monoclonal antibody production workflows.
- Microbial Galactose:Precision-fermented output from engineered yeast chassis eliminates dairy supply chain dependency. Synthetic biology platforms in China achieve titers that undercut lactose hydrolysis economics, attracting cell culture media formulators seeking batch-to-batch consistency.
- Liquid Galactose:Aqueous solutions at standardized concentrations streamline industrial fermentation dosing protocols.
- Galactose Syrup:Viscous intermediate grade finds niche applications in confectionery and beverage processing.
The dominant share belongs to Powdered Galactose, while Microbial Galactose is expanding most quickly as fermentation economics improve.
Application:
Regulatory intensity and margin capture potential vary dramatically across end-use categories, with pharmaceutical qualification barriers filtering supplier participation.
- Pharmaceuticals:Excipient-grade material for parenteral nutrition, biologic drug glycosylation, and cell culture media demands pharmacopeial compliance. FDA Drug Master File submissions and EMA CEP documentation create multi-year supplier onboarding cycles that favor established fermentation operators with dedicated quality infrastructure.
- Nutraceuticals:Dietary supplement formulations targeting gut microbiome modulation and sports recovery drive demand for non-GMO and organic-certified grades. European consumers show willingness to pay premiums for microbial-origin product with documented carbon footprint credentials.
- Food & Beverages:Low-lactose dairy product formulations and specialized infant nutrition represent mature volume applications with compressed margins.
- Cosmetics:Skin conditioning agents and prebiotic formulations in premium personal care constitute a nascent, small-volume segment.
Pharmaceuticals commands the highest value per kilogram, though Nutraceuticals is climbing fastest as wellness positioning commands shelf price premiums.
End Use Industry:
Customer technical sophistication and procurement scale separate price-tolerant niche buyers from commodity-volume processors.
- Healthcare:Hospital pharmacies, compounding facilities, and biopharmaceutical manufacturers purchase against stringent USP and EP monographs. Lot-level Certificates of Analysis with heavy metal and microbial specifications are non-negotiable.
- Food Processing:Industrial dairy and bakery operations source against FSSC 22000 and ISO 22000 benchmarks with less stringent carbohydrate impurity profiling.
- Personal Care:Cosmetic formulators seek halal and vegan certifications for label claims in Southeast Asian and European markets.
- Animal Feed:Calf milk replacer and pet nutrition applications tolerate broader specification bands at correspondingly lower price points.
Healthcare absorbs the dominant procurement value, while Personal Care is gaining share fastest on clean-label positioning.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and the criticality of supply security.
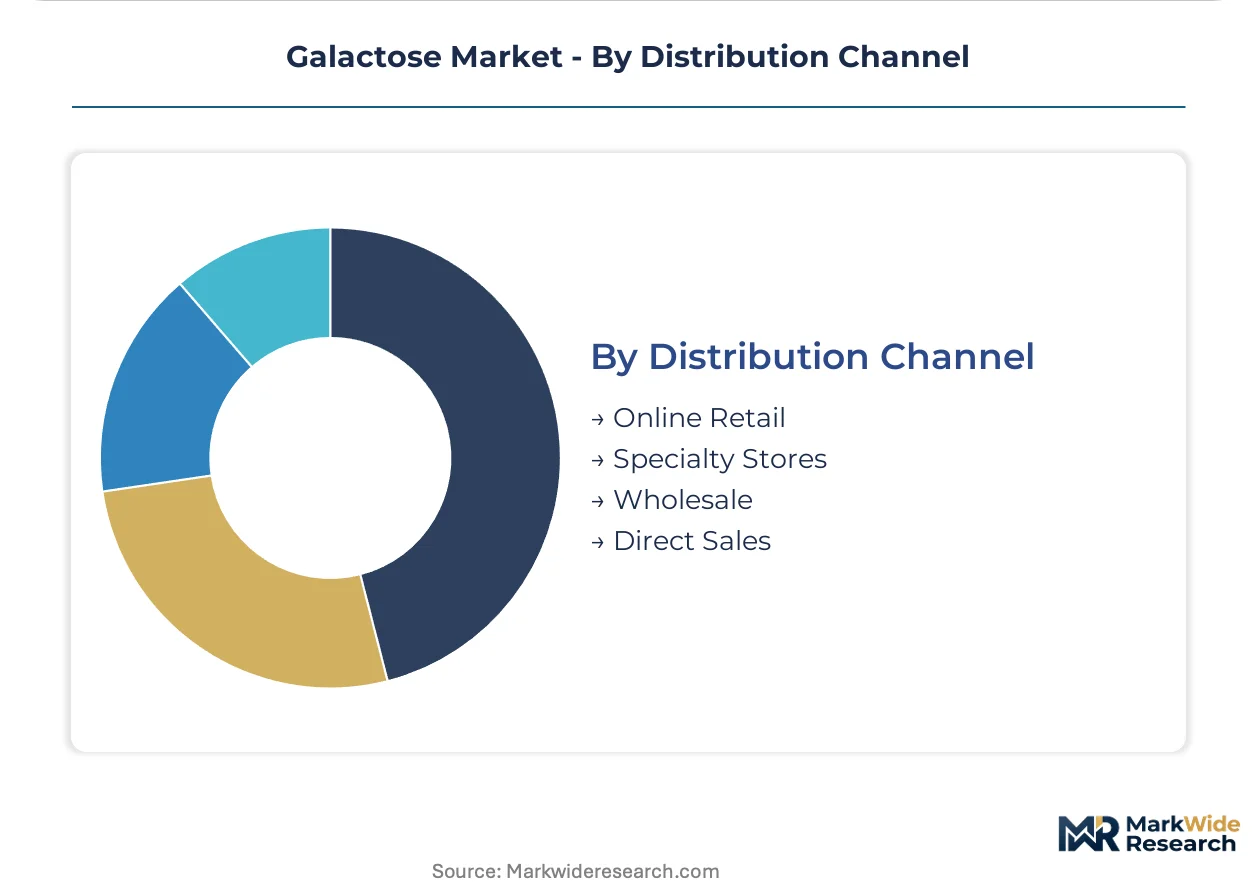
- Direct Sales:Multi-year supply agreements with qualified supplier programs dominate pharmaceutical and large-scale biotechnology procurement. Quality agreements specify change control protocols, audit rights, and dedicated inventory buffers.
- Wholesale:Chemical distributors and ingredient brokers serve mid-tier food processors and regional nutraceutical formulators with standardized grade offerings.
- Specialty Stores:Regional ingredient suppliers and niche distributors cater to artisan food producers and small-batch cosmetic manufacturers.
- Online Retail:E-commerce platforms move research-grade and small-package quantities to academic laboratories and early-stage biotechnology startups.
Direct Sales captures the dominant contract value, while Online Retail is scaling fastest as distributed research and development expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies, with pharmaceutical-grade specifications dominating procurement in the United States and Germany while food-processing applications retain share in emerging markets. This demand-mix differential shapes supplier qualification investments and channel strategies.
United States
Biopharmaceutical manufacturing expansion in Massachusetts and North Carolina drives pharmaceutical-grade galactose procurement. FDA excipient guideline tightening for parenteral nutrition formulations forces documented carbohydrate impurity profiles. Boston-Cambridge cell therapy clusters source directly through qualified supplier programs, bypassing traditional chemical distributors.
China
State-level biomanufacturing targets accelerate microbial fermentation capacity buildout for galactose production. NMPA alignment with international pharmacopeial standards raises purity thresholds for domestic suppliers. Yangtze River Delta synthetic biology platforms achieve titers competitive with lactose hydrolysis, reducing dairy feedstock dependency.
Germany
European biologics manufacturers consolidate supplier relationships with established REACH registrants possessing dedicated analytical infrastructure. EMA tightened nitrosamine risk assessment guidelines for excipients extend qualification timelines. Rhine-Ruhr chemical processing clusters retrofit amino acid production lines for rare sugar output.
India
CDSCO manufacturing license reforms and PLI scheme incentives for active pharmaceutical ingredients create demand for qualified excipient suppliers. Hyderabad and Bengaluru biopharma contract manufacturing expansion drives procurement against USP and EP monographs. Domestic fermentation operators face high-purity certification cost barriers.
Japan
PMDA pharmacopeial compliance requirements govern cell culture media formulations for monoclonal antibody production. Kanto region biopharmaceutical manufacturers specify endotoxin-controlled lots. METI industrial biotechnology programs support precision fermentation scale-up for rare sugar domestic supply security.
Galactose Market Vendor Landscape
Capability concentration sits with fermentation specialists possessing dedicated quality infrastructure; scale advantage sits with diversified chemical conglomerates leveraging existing distribution networks. The market structures around three tiers: established pharmaceutical-grade suppliers with regulatory dossiers, emerging microbial biosynthesis operators, and commodity processors serving food applications. Dominant competitive moves include strategic partnerships with cell therapy developers and synthetic biology platform licensing for cost structure compression.
Within the fermentation-specialist tier, Kyowa Hakko Bio Co., Ltd. and CJ CheilJedang Corp. exemplify players leveraging amino acid production infrastructure for rare sugar output. Merck KGaA occupies a position representing European pharmaceutical-grade biochemical specialists. These three anchors illustrate how geographic origin and legacy fermentation expertise determine qualification trajectory in pharmaceutical carbohydrate supply.
| Leading Market Players |
|---|
| Kyowa Hakko Bio Co., Ltd. |
| CJ CheilJedang Corp. |
| Merck KGaA |
| Nacalai Tesque Inc. |
| Sigma-Aldrich |
| Thermo Fisher Scientific Inc. |
| Cargill Inc. |
| Anhui HeGeng Biotech Engineering Co., LTD. |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta synthetic biology clusters anchor microbial galactose capacity expansion, translating fermentation scale economies into downstream pricing leverage for pharmaceutical-grade material. This geographic concentration of precision-fermented output is compressing lactose-hydrolysis margins while reshaping procurement negotiations for cell culture media formulators.
Pricing Analysis
Asian-origin microbial galactose commands a 15-20% premium over European lactose-derived material in United States spot markets, reflecting batch-to-batch consistency and dairy supply chain independence. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-certified, and industrial-feedstock levels separates buyers by endotoxin specification and documentation burden. Cost compression in hydrolysis-based supply is intensifying because dairy commodity volatility transmits directly to conversion economics. Contract research organizations and early-stage cell therapy developers exhibit highest price sensitivity, while commercial biologics manufacturers prioritize qualification security over unit cost.
Supply Chain Analysis
Extended payment terms from Chinese fermentation operators to domestic enzyme suppliers are stabilizing input cost structures for microbial galactose platforms. Manufacturing concentrates in China, Germany, and the United States, with each hub serving distinct regulatory dossier requirements. Raw material flows draw from engineered yeast chassis development, lactose whey streams, and analytical reagent-grade purification media. Single-source vulnerability sits with CRISPR-edited strain IP holders controlling titer performance. Distribution runs through qualified supplier programs for pharmaceutical procurement and chemical distributors for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Galactose demand is recovering from biopharmaceutical capital expenditure cyclicality, with monoclonal antibody pipeline expansion serving as the primary cyclical driver reactivating capacity utilization.
For Market Incumbents: Entrench analytical chemistry capabilities as defensive moats against synthetic biology platform commoditization. Invest in parallel FDA Drug Master File and EMA CEP submission infrastructure to compress dual-certification timelines. Secure backward integration into precision-fermented strain development to reduce licensing cost exposure. For New Entrants and Emerging Players: India's CDSCO-regulated contract manufacturing expansion offers the most penetrable white-space for qualified excipient supply. Target direct-to-biotech distribution relationships with Boston-Cambridge cell therapy clusters seeking lot-level traceability. Lead with microbial-origin carbon footprint credentials to capture European nutraceutical premium positioning. For Investors and Strategic Acquirers: Long-term, this sits as a fermentation infrastructure consolidation play because pharmaceutical-grade carbohydrate qualification barriers are concentrating supply relationships with dossier-holding operators. Target mid-scale amino acid producers with retrofit-ready bioreactor capacity and existing quality management systems. Watch synthetic biology titer announcements as the inflection signal for hydrolysis-route obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Engineered yeast platforms in China achieve titers that undercut lactose hydrolysis economics for cell culture media. |
| Regulatory Dossier Expansion | Parallel FDA and EMA submissions compress multi-year supplier onboarding cycles for pharmaceutical carbohydrate procurement. |
| Direct-to-Biotech Distribution | Bypassing chemical distributors captures margin from United States cell therapy developers demanding lot-level traceability. |
| Backward Integration into Strain IP | In-house CRISPR-edited chassis development reduces licensing costs and secures titer performance control. |
| Analytical Infrastructure Investment | Dedicated heavy metal and endotoxin testing capability meets EMA nitrosamine guideline tightening for excipient qualification. |
Methodological Framework
Operator-level perspectives from fermentation plant managers, pharmaceutical procurement leads, regulatory affairs directors, and cell culture media formulators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA Drug Master File submissions, EMA CEP documentation, USP monograph revisions, and customs trade flow data. Bottom-up capacity assessments triangulated against top-down pharmaceutical excipient demand modeling.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include physical form, application grade, end-use industry technical sophistication, and regional regulatory cluster. CAGRs derived from capacity expansion timelines, biologics manufacturing growth assumptions, and substitution elasticity between microbial and hydrolysis routes. Forecast inputs incorporated synthetic biology titer improvement curves and dairy commodity price volatility bands.
Macroeconomic conditions sit as an overlay; deviation in biopharmaceutical capital expenditure cycles, dairy feedstock pricing, or regulatory harmonization timelines would shift the trajectory. Forecasts reflect assumptions on fermentation scale-up success rates and pharmacopeial standard convergence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Oligofructose Market
Sweeteners
Sour Sugar Market
Sweeteners
Sorbitol Market
Sweeteners
Aspartame Market
Sweeteners
Icing Sugar Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Corn Sweeteners Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
Non Sugar Sweeteners Market
Sweeteners
Beetroot Molasses Market
Sweeteners
Palm Sugar Market
Sweeteners
Isomaltulose Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
White Sugar Market
Sweeteners
Fructose Market