
 Resistant Dextrin Market | 2026-2036
Resistant Dextrin Market Size, Share, and Industry Trends Forecast 2026-2036
Resistant Dextrin Market Insights
Functional beverage manufacturers are redrawing procurement priorities for soluble fiber ingredients as gut-health positioning gains shelf-space leverage. Tate & Lyle sustains formulation partnerships with multinational drink brands across multiple continents. Matsutani Chemical Industry Co., Ltd. dominates enzymatic production methods originating from Japanese starch-processing heritage. Roquette leverages European agricultural supply chains to anchor regional manufacturing capacity.
Resistant dextrin is a soluble dietary fiber produced through controlled enzymatic hydrolysis of starch, yielding glucose polymers linked predominantly by alpha-1,2 and alpha-1,3 bonds that resist human digestive enzymes while undergoing partial fermentation in the colon. The ingredient functions primarily as a low-calorie bulking agent, prebiotic substrate, and moisture-retention additive in processed foods and nutritional products. Powder formats lead volume shipments due to blending efficiency in industrial-scale food production, while sachets capture premium positioning in direct-to-consumer nutritional supplements. Applications in digestive health command the widest formulation adoption, whereas dietary fiber fortification in bakery products represents the fastest-expanding use case as clean-label reformulations accelerate.
FDA dietary fiber definition updates and EFSA health claim frameworks govern product positioning and substantiation requirements across North America and Europe. Japan's FOSHU system and China's national food safety standards additionally shape market access protocols for functional ingredient suppliers. Stakeholders must monitor evolving prebiotic classification criteria and fiber analytical methodologies that determine compliant label declarations.
Market Dynamics
Enzymatic hydrolysis patents concentrated among Japanese and European starch processors are reshaping competitive access to high-purity resistant dextrin grades. This intellectual property concentration forces new entrants into licensing arrangements or alternative fermentation pathways.
Growth Catalysts
- FDA Dietary Fiber Definition:The FDA's expanded dietary fiber definition permits resistant dextrin to carry fiber content claims on nutrition labels, accelerating adoption by US functional food formulators seeking clean-label positioning.
- Functional Beverage Procurement:Beverage manufacturers in China and Japan are prioritizing soluble fiber additives that deliver prebiotic benefits without viscosity impacts, driving volume commitments to domestic enzymatic producers.
- EFSA Health Claim Framework:EFSA's substantiated health claims for digestive function enable European brands to market resistant dextrin-fortified products with regulatory-backed efficacy messaging.
Market Restraints
- Corn Starch Input Volatility:Agricultural commodity price swings for corn starch—the primary feedstock—compress margin predictability for enzymatic producers without long-term supply contracts.
- Japanese Patent Concentration:Core enzymatic production methods remain concentrated among heritage starch processors in Japan, creating licensing barriers for regional entrants in Southeast Asia.
- Fermentation Rate Limitations:Resistant dextrin's partial fermentation profile limits its prebiotic efficacy claims compared to fully fermentable alternatives like inulin in certain gut-health applications.
Strategic Opportunities
- Bakery Reformulation Mandates:China's updated national food safety standards incentivize fiber fortification in processed wheat products, opening formulation partnerships with industrial bakeries.
- Dual Carbon Policy Alignment:China's dual carbon goals favor low-carbon ingredient processing, advantaging enzymatic resistant dextrin over chemically modified fiber alternatives in domestic procurement.
- Direct-to-Consumer Sachet Channels:E-commerce nutrition platforms in Japan and South Korea enable premium positioning of single-serve resistant dextrin supplements outside traditional food-service distribution.
Industry Challenges
- Analytical Methodology Disputes:Divergent fiber quantification protocols between AOAC and ISO standards create compliance friction for multi-territory suppliers seeking harmonized label declarations.
- Prebiotic Classification Uncertainty:Evolving scientific consensus on prebiotic criteria threatens existing marketing claims, requiring continuous substantiation investment from ingredient suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resistant Dextrin Market |
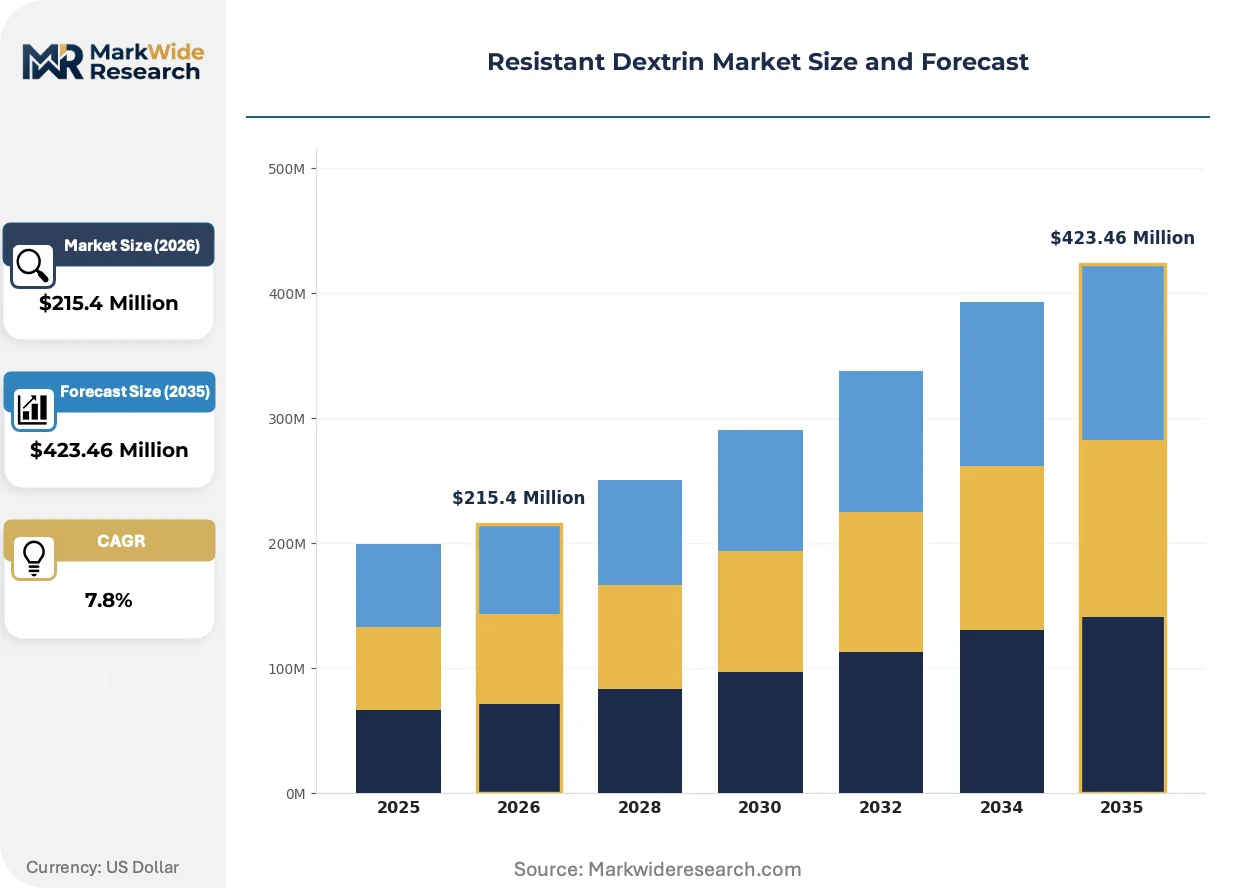
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $423.46 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Sachets, Tablets End User: Food Industry, Beverage Manufacturers, Pharmaceuticals, Nutritional Supplements Application: Weight Management, Digestive Health, Bakery Products, Dietary Fiber Fortification Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Roquette, Tate & Lyle, Shandong Bailong Chuangyuan Bio-Tech Co., Ltd., Baolingbao Biology Co., Ltd., Matsutani Chemical Industry Co., Ltd., L&P Food Ingredient Co., Ltd., Cargill, Incorporated, Ingredion Incorporated, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resistant Dextrin Market Trends and Innovations
Bioprocessing advances and regulatory clarity are fragmenting traditional supply relationships while enabling new application categories. Three developments warrant particular attention.
Continuous enzymatic processing is fragmenting batch-production economics in resistant dextrin manufacturing. Industrial enzyme suppliers are licensing immobilized catalyst systems to mid-scale producers, reducing capital intensity for entrants. This technology diffusion is compressing price premiums historically commanded by integrated starch processors.
EFSA's updated guidance on dietary fiber analytical methods is tightening substantiation requirements for resistant dextrin suppliers seeking health claims. The regulation mandates specific in-vitro digestion protocols that disqualify lower-purity grades from premium positioning. European functional food brands are reformulating around compliant ingredient sources to maintain label integrity.
Buyer concentration among multinational beverage conglomerates is consolidating procurement leverage over specialty fiber suppliers. These manufacturers are unbundling technical service from ingredient supply, demanding standalone formulation support without volume commitments. This pattern is most pronounced in North American and Western European contract negotiations.
Resistant Dextrin Market Segmentation
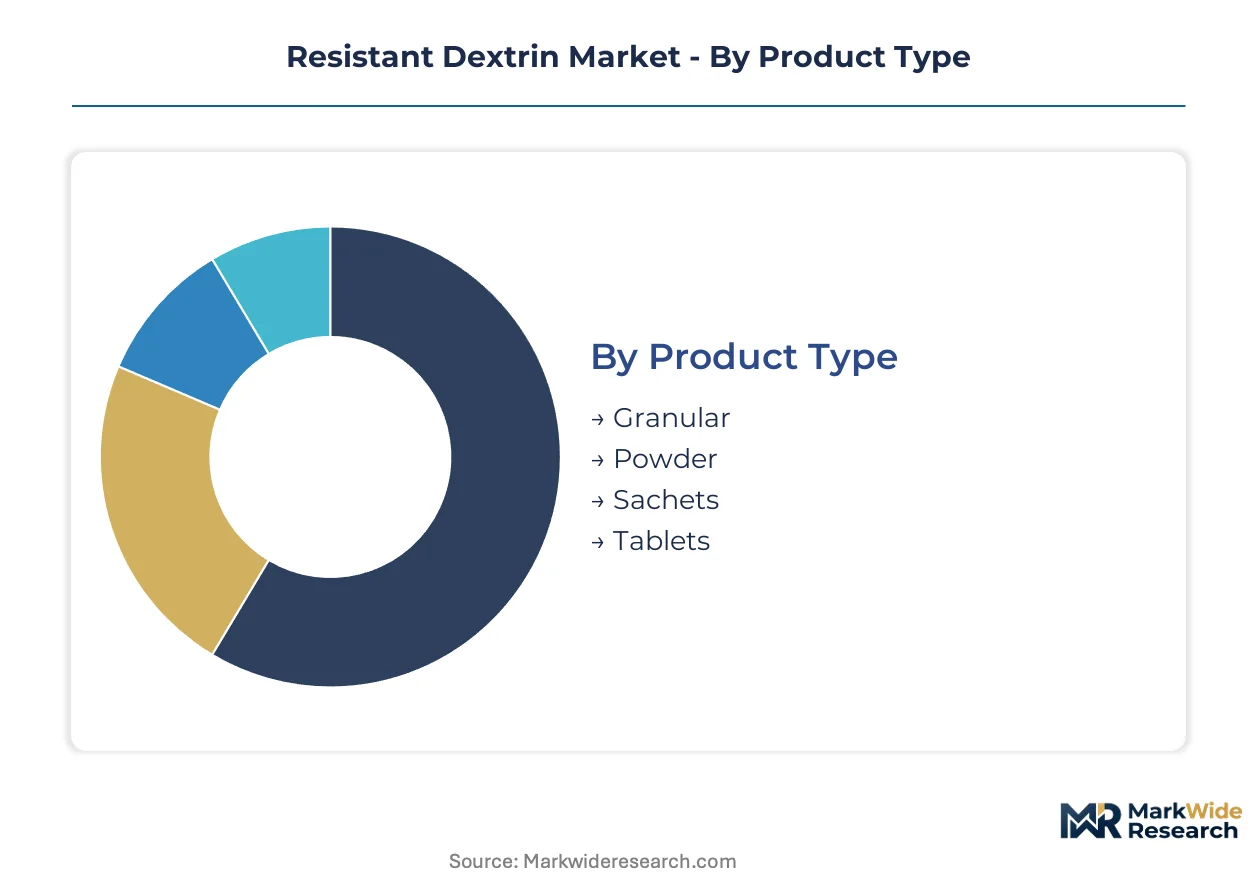
Resistant dextrin procurement patterns diverge sharply across product formats and end-use channels. Industrial buyers prioritize blending efficiency and bulk handling characteristics. Consumer-facing channels reward convenience formats with premium positioning.
Product Type:
Channel-mix dynamics separate industrial-scale procurement from direct-to-consumer distribution. Powder and granular formats dominate food manufacturing supply chains. Sachets and tablets capture e-commerce and pharmacy channels with higher per-unit economics.
- Granular:Coarse-particle resistant dextrin offers superior flow properties for high-speed blending equipment. Bakery manufacturers in Japan and Germany specify this grade for automated dough conditioning systems where dust control matters.
- Powder:Fine-mesh soluble fiber integrates rapidly into beverage matrices without clumping. Functional drink producers in China specify this format for clean-label fiber fortification where viscosity neutrality is essential.
- Sachets:Single-serve packaging targets direct-to-consumer nutritional supplement channels in South Korea and Japan.
- Tablets:Compressed fiber delivery suits pharmacy and health practitioner distribution networks.
Powder dominates installed base. Sachets are where expansion concentrates.
End User:
Application requirements determine purity specifications and volume scale across customer categories. Food and beverage manufacturers drive tonnage demand with standardized grades. Pharmaceutical and supplement buyers command premium pricing for certified fiber content.
- Food Industry:Industrial bakeries and processed food manufacturers specify resistant dextrin for moisture retention and texture modification. China's updated GB standards for wheat product fiber content are accelerating reformulation mandates among domestic flour millers.
- Beverage Manufacturers:Clear-soluble fiber grades enable prebiotic positioning in shelf-stable drinks without turbidity or mouthfeel alteration. Japanese and Chinese bottlers lead procurement volume for functional tea and dairy alternatives.
- Pharmaceuticals:Excipient-grade resistant dextrin meets pharmacopeial standards for tablet binders and controlled-release matrices.
- Nutritional Supplements:Branded fiber supplements target gut-health positioning through pharmacy and e-commerce channels.
Food Industry anchors volume demand. Beverage Manufacturers are gaining share fastest.
Application:
Functional positioning determines regulatory substantiation requirements and label claim permissibility. Digestive health applications carry the broadest regulatory acceptance across FDA, EFSA, and Japan's FOSHU frameworks.
- Digestive Health:Prebiotic fermentation claims command the widest formulation adoption. EFSA's substantiated health claims for bowel function enable European brands to market with regulatory-backed efficacy messaging.
- Dietary Fiber Fortification:Clean-label reformulation in bakery products is climbing the fastest as manufacturers respond to China's national food safety standards incentivizing processed wheat fiber enrichment.
- Weight Management:Satiety positioning requires clinical substantiation that varies by jurisdiction.
- Bakery Products:Texture and shelf-life benefits complement nutritional enhancement in industrial bread and pastry applications.
Digestive Health holds the deepest formulation history. Dietary Fiber Fortification shows the steepest expansion trajectory.
Distribution Channel:
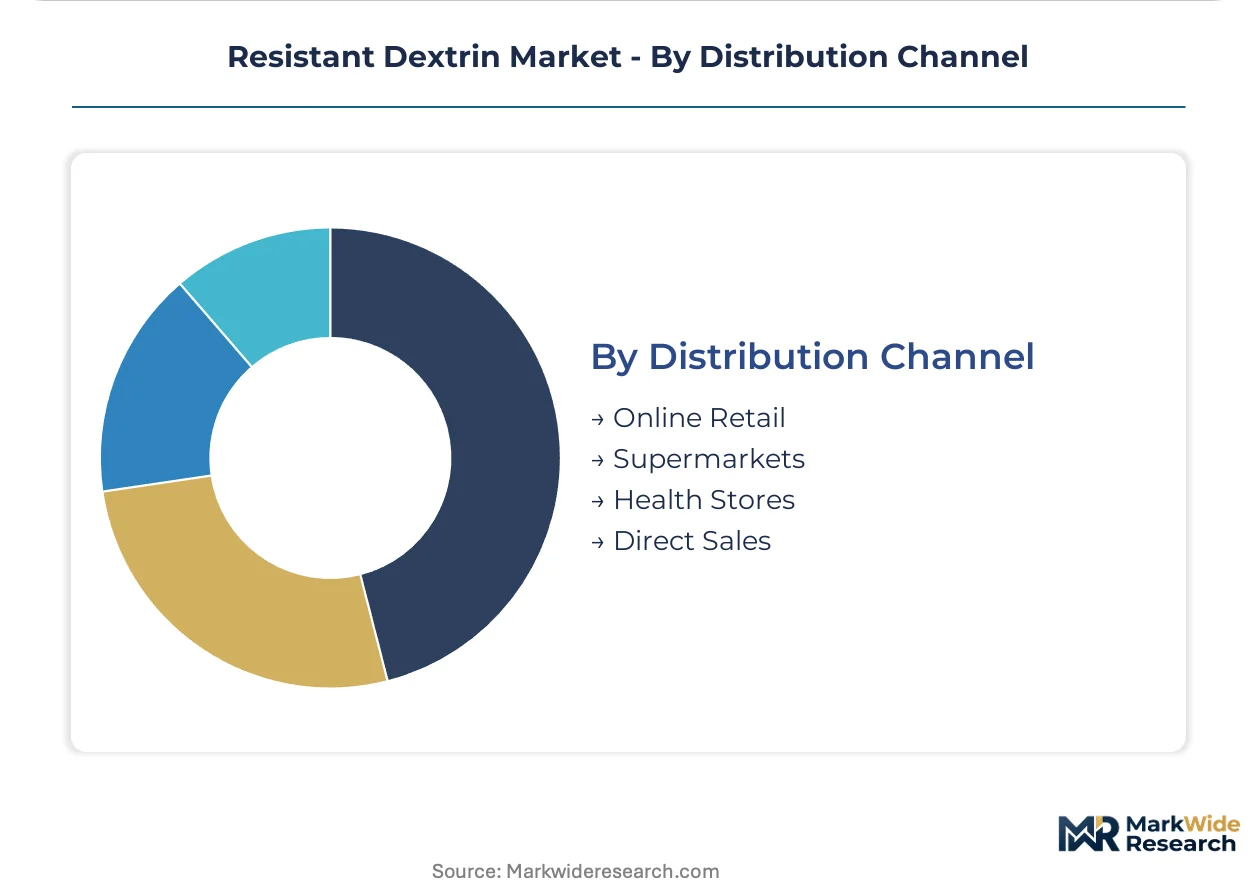
Supply chain configuration determines margin capture and customer relationship intensity. Direct sales to industrial buyers preserve technical service revenue. Online retail fragments pricing power among competing brands.
- Direct Sales:Long-term supply agreements with multinational food manufacturers include embedded formulation support. Tate & Lyle and Roquette sustain procurement relationships through technical service teams co-located with major beverage and bakery customers.
- Supermarkets:Mass-market retail placement for consumer fiber supplements requires trade marketing investment and shelf-space negotiation.
- Health Stores:Specialty retail channels reward premium positioning with educated consumer demographics.
- Online Retail:E-commerce nutrition platforms in Japan and South Korea enable direct-to-consumer sachet sales outside traditional distribution markups.
Direct Sales commands the highest contract values. Online Retail is where new entrant penetration concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports resistant dextrin to functional beverage manufacturers across China and Southeast Asia, leveraging enzymatic processing heritage and established FOSHU regulatory pathways.
China
Domestic beverage brands and industrial bakeries drive procurement volume for soluble fiber fortification. GB standards for wheat product fiber content mandate reformulation across processed food categories. Shandong province hosts concentrated starch-processing capacity serving regional nutraceutical formulators.
Japan
FOSHU-approved digestive health claims sustain premium positioning in functional foods and supplements. METI oversight of food labeling standards shapes substantiation requirements for prebiotic efficacy messaging. Osaka-based enzymatic producers supply resistant dextrin grades to multinational beverage partnerships.
United States
FDA dietary fiber definition updates enable fiber content claims on nutrition labels, accelerating adoption by clean-label formulators. Functional drink and bakery manufacturers prioritize procurement of low-viscosity soluble fiber grades. Midwest agricultural processing clusters anchor corn starch feedstock supply chains.
Germany
EFSA health claim frameworks permit regulatory-backed efficacy messaging for digestive function applications. Industrial bakeries and beverage producers source compliant fiber grades for EU market distribution. North Rhine-Westphalia's food ingredient sector maintains formulation partnerships with multinational brands.
South Korea
E-commerce nutrition platforms enable direct-to-consumer sachet distribution outside traditional retail markups. MFDS food additive regulations govern prebiotic classification and label claim permissibility. Seoul-based supplement brands drive premium positioning of single-serve fiber products.
Resistant Dextrin Market Competitive Landscape
Listed leaders compete with private specialists across enzymatic processing capabilities and regional supply chain integration. The vendor base stratifies between integrated starch processors with captive feedstock and independent ingredient formulators sourcing through contract manufacturing. Three archetypes dominate: heritage Japanese enzymatic specialists, European agricultural processors with backward integration into corn starch, and Chinese domestic producers serving regional beverage and bakery demand. Competitive dynamics center on capacity expansion in enzymatic processing and strategic partnerships with multinational food manufacturers seeking technical service bundling.
Within the heritage enzymatic specialist tier, Matsutani Chemical Industry Co., Ltd. exemplifies Japanese starch-processing lineage, while Tate & Lyle occupies a position as a listed multinational with formulation partnerships across multiple continents. Roquette represents the European agricultural processor archetype with regional manufacturing capacity anchored in feedstock supply chains. Shandong Bailong Chuangyuan Bio-Tech Co., Ltd. and Baolingbao Biology Co., Ltd. sit within the Chinese domestic producer segment serving regional procurement demand.
| Leading Market Players |
|---|
| Roquette |
| Tate & Lyle |
| Shandong Bailong Chuangyuan Bio-Tech Co., Ltd. |
| Baolingbao Biology Co., Ltd. |
| Matsutani Chemical Industry Co., Ltd. |
| L&P Food Ingredient Co., Ltd. |
| Cargill, Incorporated |
| Ingredion Incorporated |
| ADM |
| Others |
Pricing and Supply Chain Analysis
Enzymatic hydrolysis replacing acid-modified starch processing is redrawing procurement geography and compressing price premiums across Japanese, Chinese, and European supply bases simultaneously.
Pricing Analysis
Batch-processing versus continuous enzymatic systems versus next-generation immobilized catalyst platforms stratifies pricing tiers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels dominates contract negotiations. Cost compression in standard food-grade segments is intensifying because continuous processing technology licenses are diffusing to mid-scale Chinese producers. Beverage manufacturers with multinational procurement desks exhibit highest price sensitivity, while pharmaceutical excipient buyers accept substantial premiums for pharmacopeial certification.
Supply Chain Analysis
Strategic stockpiling of corn starch feedstock characterizes Japanese and European enzymatic processors facing agricultural commodity volatility. Supply concentrates in China, Japan, and Germany for enzymatic production capacity. Corn starch, industrial enzymes, and energy inputs constitute the primary cost stack. Single-source vulnerability around amylase enzyme suppliers creates concentration risk. Distribution runs through direct technical-service relationships with multinational food manufacturers rather than spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA dietary fiber definition expansion constitutes a regulatory inflection accelerating clean-label reformulation demand across North American functional food manufacturing.
For Market Incumbents: Secure long-term enzyme supply agreements to defend against fermentation-pathway substitutes threatening enzymatic dextrin positioning. Expand captive corn starch processing in Shandong or Iowa to offset agricultural commodity volatility eroding margin predictability. Prioritize EFSA-compliant analytical certification to maintain European health claim eligibility as methodology standards tighten. For New Entrants and Emerging Players: FDA GRAS notification fast-track enables premium positioning in US beverage reformulation without multi-year FOSHU-equivalent timelines. White-space concentrates in South Korean direct-to-consumer sachet channels and Chinese industrial bakery partnerships under GB standard mandates. Go-to-market leverage targets e-commerce nutrition platforms with standalone formulation support unbundled from volume commitments. For Investors and Strategic Acquirers: The market sits at a technology-diffusion phase that favors continuous-processing equipment suppliers and regional enzymatic specialists over integrated starch incumbents. Long-term viability hinges on regulatory claim substantiation durability across FDA, EFSA, and FOSHU frameworks. Acquisition targets with pharmacopeial-grade certification and existing multinational beverage technical-service relationships command structural scarcity premiums. Signal to monitor: EFSA prebiotic classification criteria revisions threatening existing marketing claim inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Enzymatic Processing License | Immobilized catalyst systems reduce capital intensity for mid-scale entrants competing against Matsutani heritage processors. |
| EFSA Analytical Methodology Compliance Investment | Specific in-vitro digestion protocols qualify resistant dextrin grades for premium health claim positioning in EU markets. |
| Direct-to-Consumer Sachet Channel Launch | E-commerce nutrition platforms in Seoul and Tokyo bypass traditional retail markups for premium per-unit economics. |
| Corn Starch Backward Integration | Captive agricultural processing in Iowa or Shandong insulates margin predictability against commodity price swings. |
| Multinational Beverage Technical Partnership | Standalone formulation support contracts with Tate & Lyle or Roquette anchor procurement relationships without volume guarantees. |
Research Methodology
A standing panel of enzymatic processing plant managers, procurement leads at functional beverage OEMs, distribution channel partners, and regulatory affairs directors at fiber ingredient suppliers provided ongoing calibration. Primary interviews combined with secondary validation against FDA GRAS notifications, EFSA health claim registers, Japanese FOSHU approvals, and Chinese GB standard filings. Bottom-up capacity modeling triangulated against top-down end-use demand estimates across beverage, bakery, and supplement applications.
Consistency checks validated volume and value outputs against customs trade data, SEC 10-K disclosures from listed ingredient suppliers, and industry association production surveys. Segmentation modeling spanned product format, end-user industry, application positioning, and regional regulatory cluster across the analysis window. CAGRs derived from fitted growth curves incorporating enzymatic capacity expansion timelines and reformulation mandate implementation schedules. Forecast inputs included corn starch price indices, enzyme licensing cost trajectories, and e-commerce penetration rates in East Asian supplement markets.
Underlying assumptions cover sustained FDA dietary fiber definition stability, EFSA analytical methodology enforcement, and FOSHU claim renewal patterns, with deviation risk concentrated in prebiotic classification consensus shifts and corn starch commodity volatility. Revision becomes warranted when regulatory claim substantiation requirements cross thresholds that disqualify incumbent production grades from premium positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
North America Food Starch Market