
 Naturally Derived Sweeteners Market | 2026-2036
Naturally Derived Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Naturally Derived Sweeteners Market Foresight
Single-serve sachet bundling is pivoting how foodservice buyers procure naturally derived sweeteners, shifting volume from bulk industrial totes to portion-controlled retail-compatible formats. Cargill, Incorporated leverages its supply chain scale to dominate stevia leaf sourcing across multiple continents. Tate & Lyle PLC anchors its position through deep R&D investment in taste-modulation technologies that mask bitter off-notes. PureCircle Ltd. specializes in vertically integrated stevia cultivation, controlling genetics from seed to extraction.
Naturally derived sweeteners comprise caloric and non-caloric sugar substitutes extracted or refined from botanical sources—steviol glycosides from Stevia rebaudiana leaves, mogrosides from Siraitia grosvenorii fruit, inulin from chicory root, and fructans from agave sap—typically standardized to 80-99% purity with specified glycoside profiles for consistent sweetness equivalence. Their primary commercial purpose is enabling food and beverage manufacturers to reduce added sugars while maintaining labeled clean-label status. Stevia leads product type volume due to regulatory approvals in over 130 countries and established agricultural supply bases, though monk fruit extracts command premium positioning in functional beverage applications where zero-calorie claims carry the highest consumer willingness to pay. Powder and liquid forms split end-user demand, with powders dominating bakery and dry-mix manufacturing while liquids capture beverage formulation workflows.
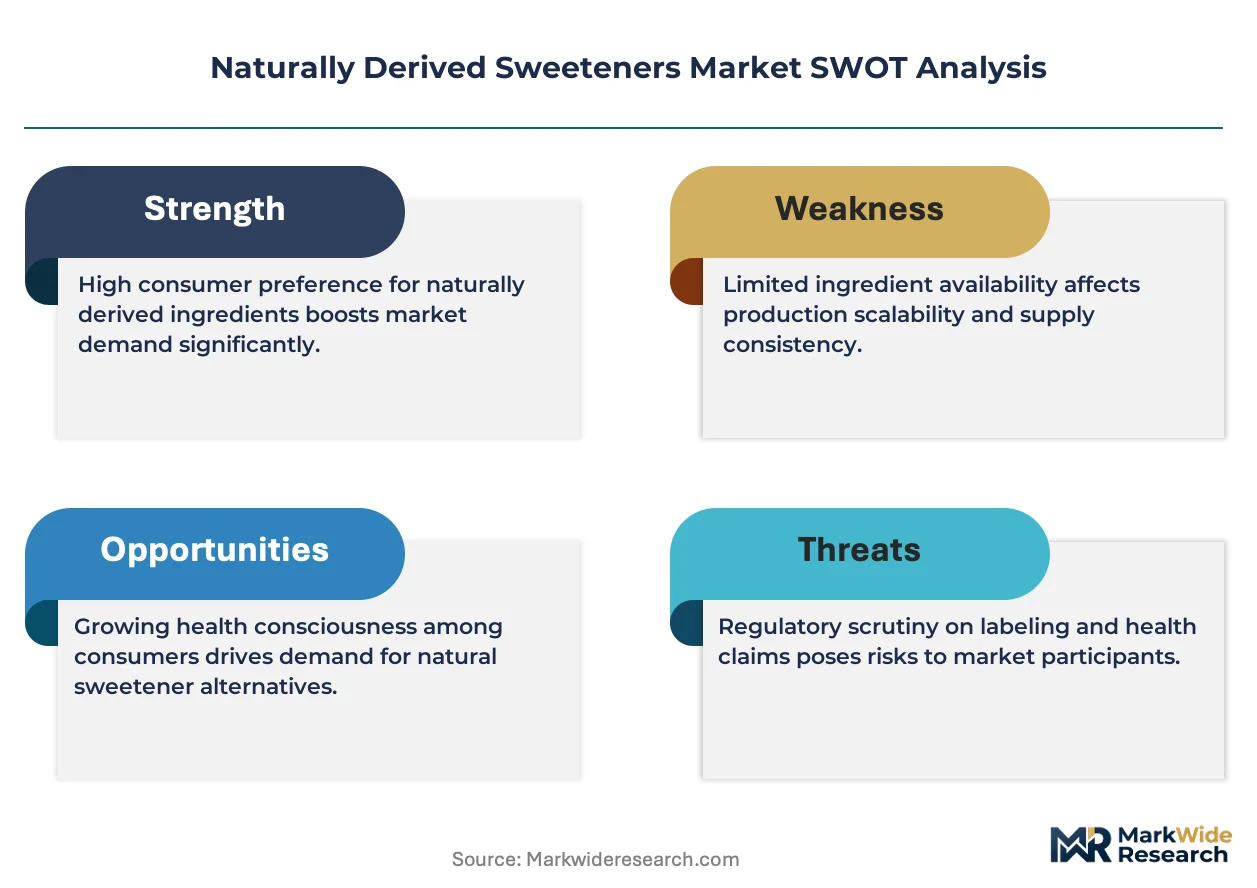
FDA enforcement of GRAS self-affirmation documentation and the EU's Novel Food Regulation, administered by EFSA, jointly determine which botanical extracts achieve commercializable status in the two largest demand jurisdictions. BIS standards in India and China's NMPA registration pathway for new food additives are increasingly influential as formulation activity shifts toward Asian manufacturing hubs. Stakeholders must monitor evolving purity thresholds and extraction-method definitions, as regulatory reclassifications could abruptly disqualify existing supply sources or unlock previously restricted botanical candidates.
Market Dynamics
Beverage reformulation mandates are compressing procurement cycles as manufacturers race to replace synthetic sweeteners ahead of clean-label deadlines, forcing rapid qualification of new botanical extract suppliers.
Growth Catalysts
- EU Novel Food Regulation:EFSA's streamlined approval pathways for steviol glycosides and mogrosides have accelerated market entry timelines, enabling faster portfolio expansion for European food manufacturers.
- Beverage industry clean-label mandates:Carbonated and functional drink producers now require non-caloric botanical extracts to maintain shelf placement in premium retail channels.
- Chicory root cultivation expansion:Agricultural capacity in Belgium and the Netherlands is scaling inulin extraction volumes to meet dairy alternative formulation demand.
Market Restraints
- Stevia leaf supply concentration:Sourcing dependence on specific subtropical growing regions creates harvest volatility and quality inconsistency.
- Monk fruit extraction cost structure:Limited fruit-bearing geography and labor-intensive harvesting constrain mogroside price competitiveness against established alternatives.
- GRAS documentation requirements:FDA's evidentiary demands for self-affirmed botanical status impose substantial regulatory consulting costs on smaller suppliers.
Strategic Opportunities
- India BIS standard harmonization:Alignment with international purity benchmarks would unlock domestic food processing demand for imported stevia and monk fruit extracts.
- Single-serve foodservice formats:Portion-controlled sachet packaging is creating new channel access for premium botanical sweeteners in hospitality and away-from-home consumption.
- Enzymatic biotransformation:Convergence of fermentation engineering with glycoside refinement is enabling novel rebaudioside variants with improved taste profiles.
Industry Challenges
- Flavor chemist talent scarcity:Specialized expertise in bitterness masking and taste modulation commands premium compensation, constraining mid-tier supplier R&D scaling.
- Extraction equipment capex intensity:Supercritical CO2 and membrane filtration systems require substantial capital deployment before achieving viable unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naturally Derived Sweeteners Market |
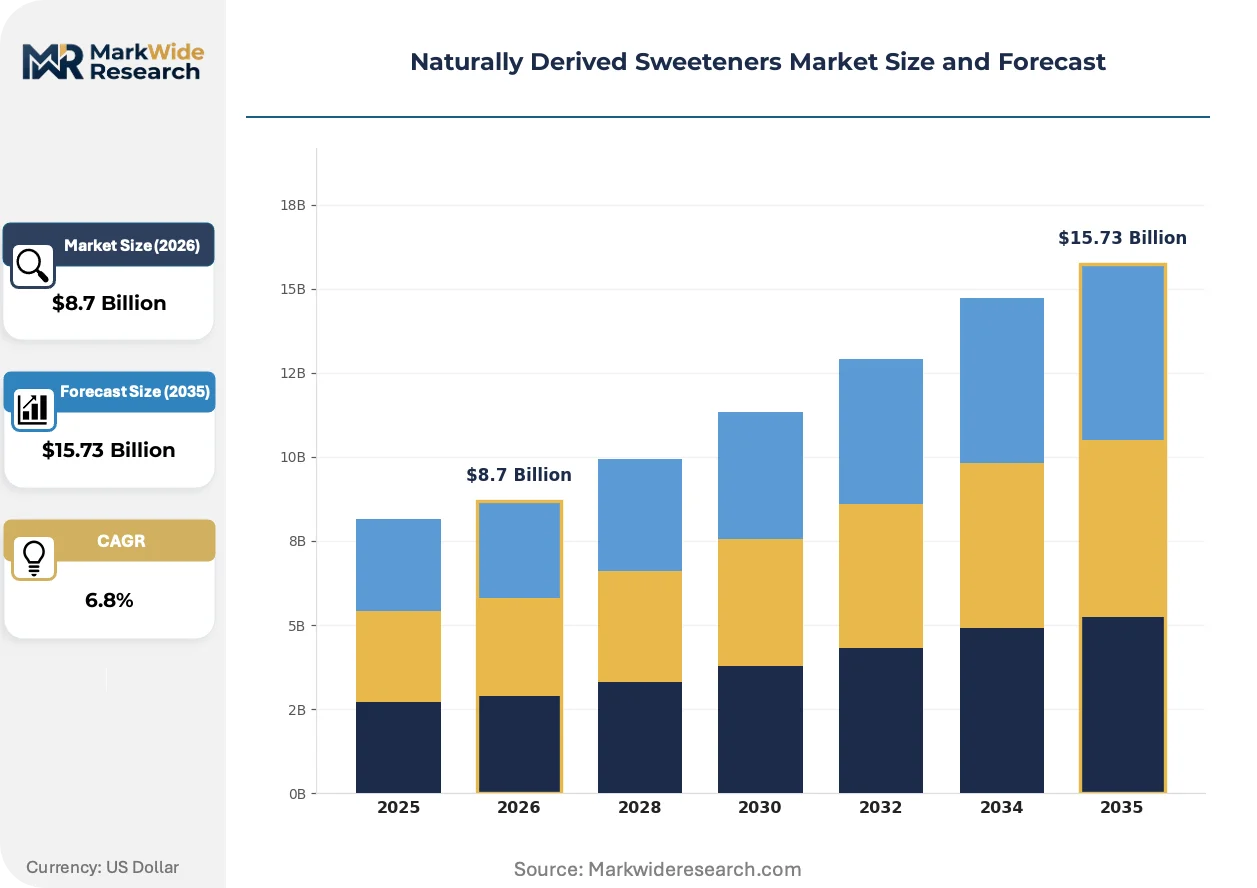
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Monk Fruit, Agave Nectar, Date Sugar Application: Beverages, Bakery, Dairy Products, Snacks Form: Liquid, Powder, Granulated, Cubes End User: Food Manufacturers, Beverage Producers, Retailers, Home Consumers |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, DuPont de Nemours Inc., Ingredion Incorporated, Roquette Frères, PureCircle Ltd., FoodChem International Corporation, GLG Lifetech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naturally Derived Sweeteners Market Shifts & Advancements
Biotechnology and precision agriculture are converging to transform how botanical sweeteners are produced, moving extraction from traditional harvesting toward controlled-environment cultivation and enzymatic synthesis.
Cell-culture steviol glycoside production is decentralizing supply chain risk by enabling year-round manufacturing independent of agricultural growing seasons. Pharmaceutical-grade bioreactor operators are entering the food ingredient space, attracted by higher margins than commodity fermentation. This technology is decentralizing geographic dependence on Paraguayan and Chinese leaf cultivation.
EFSA's 2023 updated guidance on novel food safety assessments has tightened toxicological data requirements for enzymatically modified steviol glycosides. The regulation now demands extended subchronic studies, extending approval timelines by 18-24 months. European functional beverage formulators are responding by accelerating grandfathered ingredient procurement before stricter thresholds take effect.
Foodservice buyers are consolidating procurement through direct-supplier partnerships, bypassing traditional ingredient distributors. Quick-service restaurant chains and coffee shop operators now negotiate volume commitments directly with stevia and monk fruit extractors, securing price stability and custom formulation services. This pattern is most visible in the United States, where beverage-led foodservice chains have achieved sufficient scale to justify dedicated supply agreements.
Naturally Derived Sweeteners Market Segmentation
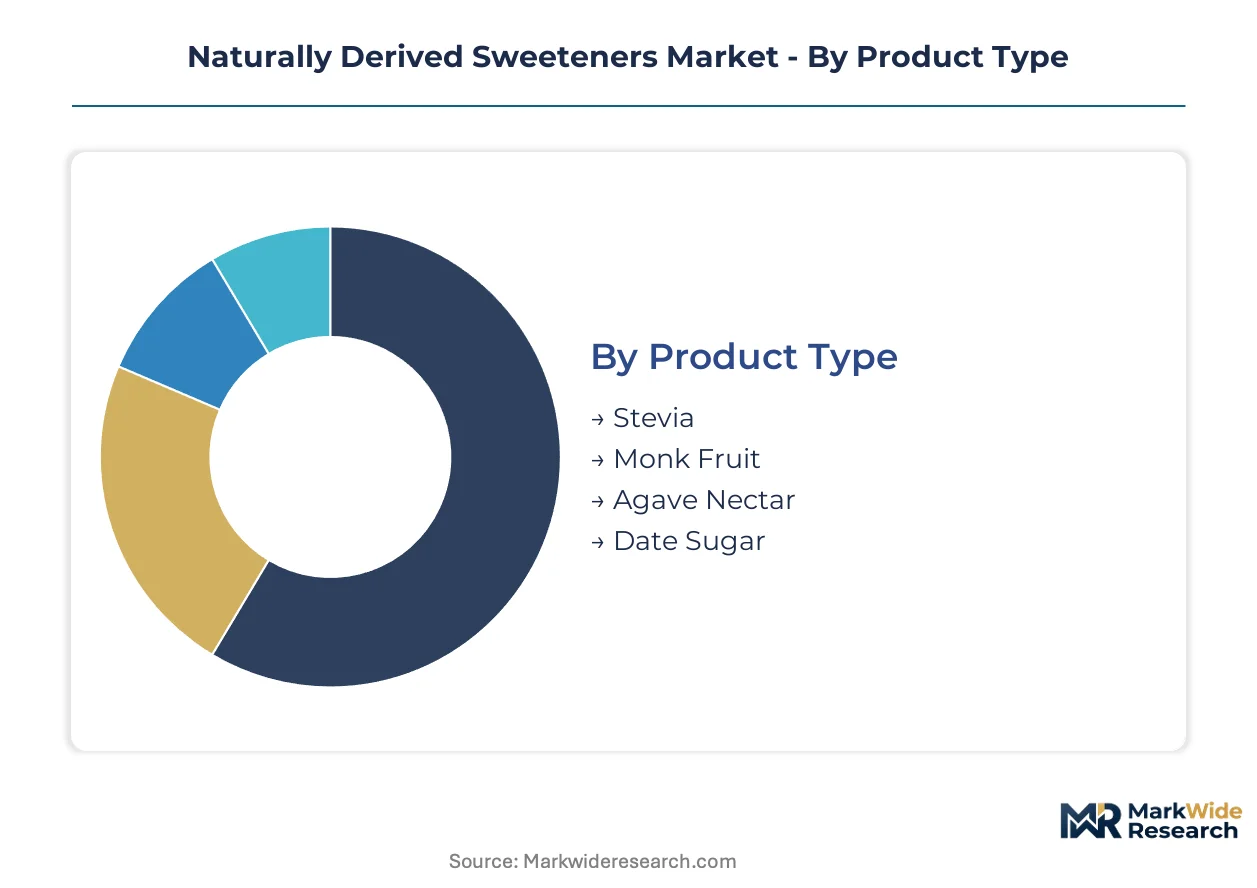
Segmentation in the naturally derived sweeteners market determines procurement workflows, formulation compatibility, and regulatory compliance pathways. Buyers select segments based on sweetness intensity profiles, thermal stability requirements, and clean-label positioning needs.
Product Type:
Cost tier structures the buying decision, with premium extracts commanding dedicated R&D budgets and commodity-grade alternatives competing on volume pricing.
- Stevia:Steviol glycosides extracted from Stevia rebaudiana leaves deliver 200-350x sucrose sweetness with zero caloric contribution. Beverage producers in the United States concentrate procurement here, driven by FDA GRAS status and established agricultural supply bases across Paraguay and China.
- Monk Fruit:Mogrosides from Siraitia grosvenorii fruit provide clean sweetness without bitter aftertaste at 150-200x sucrose equivalence. Functional water formulators pay premium pricing for this extract, constrained by limited cultivation geography in southern China and labor-intensive harvesting cycles.
- Agave Nectar:Fructan-rich sap from Agave tequilana offers low glycemic index positioning for natural food brands seeking paleo and keto-adjacent claims.
- Date Sugar:Whole-fruit granules retain fiber content and mineral complexity, appealing to Middle Eastern and North African manufacturers with established date processing infrastructure.
Volume sits with stevia; growth tilts toward monk fruit.
Application:
Application dictates thermal stability requirements and bitterness masking intensity, separating high-heat processing from cold-blend formulation workflows.
- Beverages:Carbonated drinks, functional waters, and ready-to-drink teas require cold-soluble extracts with rapid dissolution kinetics. Clean-label mandates from major retail chains in the United States are compressing reformulation timelines.
- Bakery:Maillard-reactive sweeteners must withstand oven temperatures above 180°C without caramelization defects or structural collapse. Chicory-derived inulin and agave syrups dominate here for moisture retention and browning control.
- Dairy Products:Yogurt and ice cream applications prioritize freeze-thaw stability and minimal syneresis, favoring liquid stevia extracts with optimized glycoside ratios.
- Snacks:Coating and dusting applications demand non-hygroscopic powder forms with consistent particle size distribution for uniform adherence.
Revenue concentrates in beverages; bakery applications expand most quickly as clean-label mandates extend beyond drinks.
Form:
Manufacturing workflow integration determines form selection, with liquid systems favoring pump-and-meter operations and dry mixes requiring free-flowing particulates.
- Liquid:Aqueous or glycerin-based concentrates enable precise dosing in beverage batching systems and continuous processing lines. Tate & Lyle and Cargill compete here with standardized 60-80% glycoside solutions.
- Powder:Spray-dried extracts with maltodextrin carriers dominate dry-mix manufacturing for instant beverages and baking premixes.
- Granulated:Agglomerated particles with improved flow properties serve tabletop sweetener and foodservice sachet applications.
- Cubes:Compressed tablets with binding agents target hospitality and airline catering channels requiring portion-controlled dispensing.
Liquid captures the largest production volume; granulated formats gain share fastest through foodservice channel expansion.
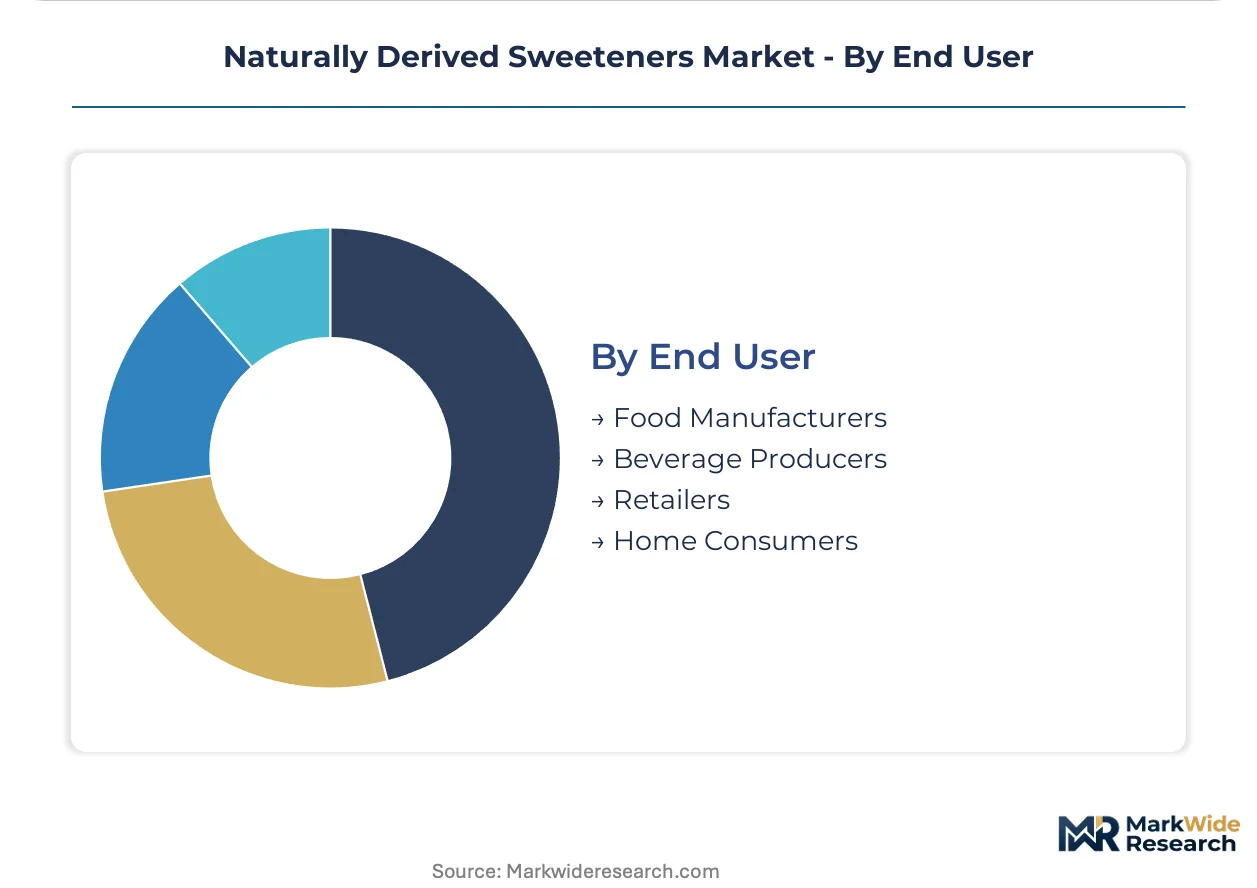
End User:
Customer scale and technical capability separate industrial buyers with in-house formulation expertise from retail-dependent channels requiring finished-product convenience.
- Food Manufacturers:Industrial bakeries, confectioners, and prepared food processors purchase bulk totes with customized glycoside specifications and certificate-of-analysis documentation.
- Beverage Producers:Carbonated and functional drink companies now represent the most procurement-active segment, negotiating direct supply agreements with stevia and monk fruit extractors.
- Retailers:Private-label programs for supermarket and pharmacy chains demand co-manufacturing partnerships with pre-approved ingredient sourcing.
- Home Consumers:Direct-to-purchaser sales through e-commerce and specialty grocers concentrate in single-serve sachets and small-format bottles.
Food manufacturers anchor current volume; beverage producers drive the steepest expansion trajectory as reformulation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraguay's Alto Paraná special economic zone for stevia cultivation concentrates upstream agricultural supply, drawing extraction facility investment from multinational processors seeking GRAS-compliant leaf sourcing.
United States
Beverage reformulation deadlines from major retail chains drive procurement velocity. FDA GRAS self-affirmation requirements elevate compliance barriers for new entrants. California's functional beverage cluster in the San Francisco Bay Area hosts the highest density of monk fruit-sweetened product launches.
China
Monk fruit cultivation in Guangxi Zhuang Autonomous Region supplies global mogroside demand. NMPA registration pathways for novel food additives extend approval timelines for enzymatically modified extracts. Zhejiang and Jiangsu provinces concentrate stevia leaf processing capacity for export markets.
Germany
EFSA novel food assessments determine commercial viability for European launch strategies. REACH compliance for extraction solvents adds regulatory complexity to supply qualification. The Lower Rhine region hosts chicory root inulin extraction facilities serving dairy alternative formulators across the EU.
India
BIS standard harmonization with international purity benchmarks would unlock domestic food processing demand. FSSAI enforcement of additive labeling creates compliance overhead for imported extracts. Maharashtra's Mumbai-Pune industrial corridor concentrates beverage manufacturing requiring clean-label sweetener inputs.
Brazil
São Paulo state's food and beverage manufacturing base drives South American formulation demand. ANVISA's alignment with Codex Alimentarius standards simplifies import clearance for stevia glycosides. The Campinas technology cluster hosts taste-modulation R&D partnerships between extract suppliers and flavor houses.
Naturally Derived Sweeteners Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across multiple technology vectors. The market structure segments into three tiers: agricultural commodity processors with backward integration into cultivation, biotechnology firms with fermentation-based production capabilities, and regional extractors serving local formulation demand. Strategic moves concentrate on direct supply agreements with beverage manufacturers and capacity expansion in cell-culture glycoside production.
Among diversified agricultural processors, Cargill, Incorporated and Archer Daniels Midland Company occupy positions spanning commodity sourcing through formulation support. Tate & Lyle PLC exemplifies the taste-technology specialist archetype, while PureCircle Ltd. represents vertical cultivation-to-extraction integration. These three anchors demonstrate how competitive positioning splits between scale-driven supply security and proprietary glycoside refinement capabilities.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| DuPont de Nemours Inc. |
| Ingredion Incorporated |
| Roquette Frères |
| PureCircle Ltd. |
| FoodChem International Corporation |
| GLG Lifetech Corporation |
| Others |
Supply & Pricing Matrix
Beverage producer procurement concentration at the largest carbonated and functional drink manufacturers anchors pricing power with volume-commitment contract structures, compressing spot-market liquidity for smaller buyers. This buyer archetype dominance forces tiered negotiation leverage where multi-year offtake agreements command steep discounts against spot purchases.
Pricing Analysis
Short lead-time premiums of 15-25% apply to rush orders from beverage formulators facing reformulation deadlines, while spot inventory from secondary traders clears at discounts to contract benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates GRAS-certified monk fruit extracts from commodity stevia glycosides and unverified regional alternatives. Price differentiation stems from FDA documentation completeness and organic certification tier. Cost compression in standard-grade stevia intensifies because Chinese leaf processors are expanding extraction capacity. Contract beverage manufacturers exhibit highest price sensitivity due to thin reformulation margins, while functional water specialists show least sensitivity for clean-label claims.
Supply Chain Analysis
Steviol glycoside supply rests on subtropical leaf cultivation in Paraguay, China, and Kenya, with mogroside extraction concentrated in Guangxi Zhuang Autonomous Region. Raw material dependencies include stevia seed genetics, monk fruit pollination labor, and supercritical CO2 extraction solvents. Single-source vulnerability runs through Guangxi's narrow cultivation belt for premium monk fruit grades. Distribution runs through direct-supplier partnerships with major beverage manufacturers, bypassing traditional ingredient distributors for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FDA GRAS documentation costs is forcing sub-scale extractors toward acquisition or exit, favoring well-capitalized players with regulatory affairs infrastructure.
For Market Incumbents: Acquire cell-culture fermentation assets to decentralize agricultural supply risk. Secure direct supply agreements with top-five beverage manufacturers to lock volume commitments before reformulation cycles complete. Build backward integration into Paraguayan and Chinese seed genetics programs to control glycoside yield consistency. For New Entrants and Emerging Players: Enzymatic biotransformation of rebaudioside variants offers the most penetrable wedge against established extraction incumbents. Target single-serve foodservice sachet formats where brand loyalty remains undeveloped and premium positioning is achievable. Pursue co-manufacturing partnerships with regional beverage brands lacking in-house formulation expertise. For Investors and Strategic Acquirers: The window for entry favors biotechnology firms with pharmaceutical-grade bioreactor capabilities seeking food ingredient diversification. Acquisition targets should demonstrate EFSA novel food dossier progress or FDA GRAS self-affirmation completion. Watch EFSA toxicological data requirement enforcement as the inflection signal for enzymatically modified glycoside approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Culture Production Scale-Up | Decentralizes supply chain risk from Paraguayan and Chinese agricultural seasons. |
| Direct Supply Agreement Expansion | Bypasses ingredient distributors to capture margin from beverage manufacturer consolidation. |
| Taste-Modulation R&D Partnership | Addresses flavor chemist talent scarcity through collaboration with Campinas technology cluster. |
| GRAS Documentation Investment | Creates compliance barrier against smaller competitors lacking regulatory consulting budgets. |
| Single-Serve Format Development | Unlocks foodservice channel access with portion-controlled sachet packaging. |
Research Methodology
Multi-period observation of stevia leaf import volumes, monk fruit cultivation acreage, and beverage reformulation announcement timelines anchored the trend analysis, supplemented by interviews with extraction facility operators, beverage procurement directors, and regulatory affairs consultants. Secondary validation drew from FDA GRAS notification databases, EFSA novel food opinions, customs trade records, and SEC filings of diversified agricultural processors. Bottom-up volume estimates from individual extraction facilities triangulated against top-down category spending data from food and beverage manufacturers.
Input-output matrices mapped glycoside production capacity to end-use demand across beverage, bakery, dairy, and snack applications over the projection horizon. Segmentation dimensions modeled include product type, application, form, and end-user scale tier. CAGRs were derived from regression analysis of historical volume trajectories against regulatory approval timelines and agricultural yield forecasts. Forecast inputs incorporated EFSA assessment pipeline status and NMPA registration progress for enzymatically modified extracts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory reclassifications or harvest disruptions in concentrated growing regions. Projections reflect assumptions about continued clean-label mandate expansion and stable agricultural trade policy. A small set of triggers—EFSA novel food opinion delays, BIS standard harmonization failure, and cell-culture production cost breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Rice Syrup Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Agave Syrup Market
Sweeteners
Xylitol Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Sweeteners Market
Sweeteners
Global Cane Molasses Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Asia-Pacific Starch Sweetener Market